
 Russia Electric Cars Market | 2026-2036
Russia Electric Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Electric Cars Market Analytics
Market Context
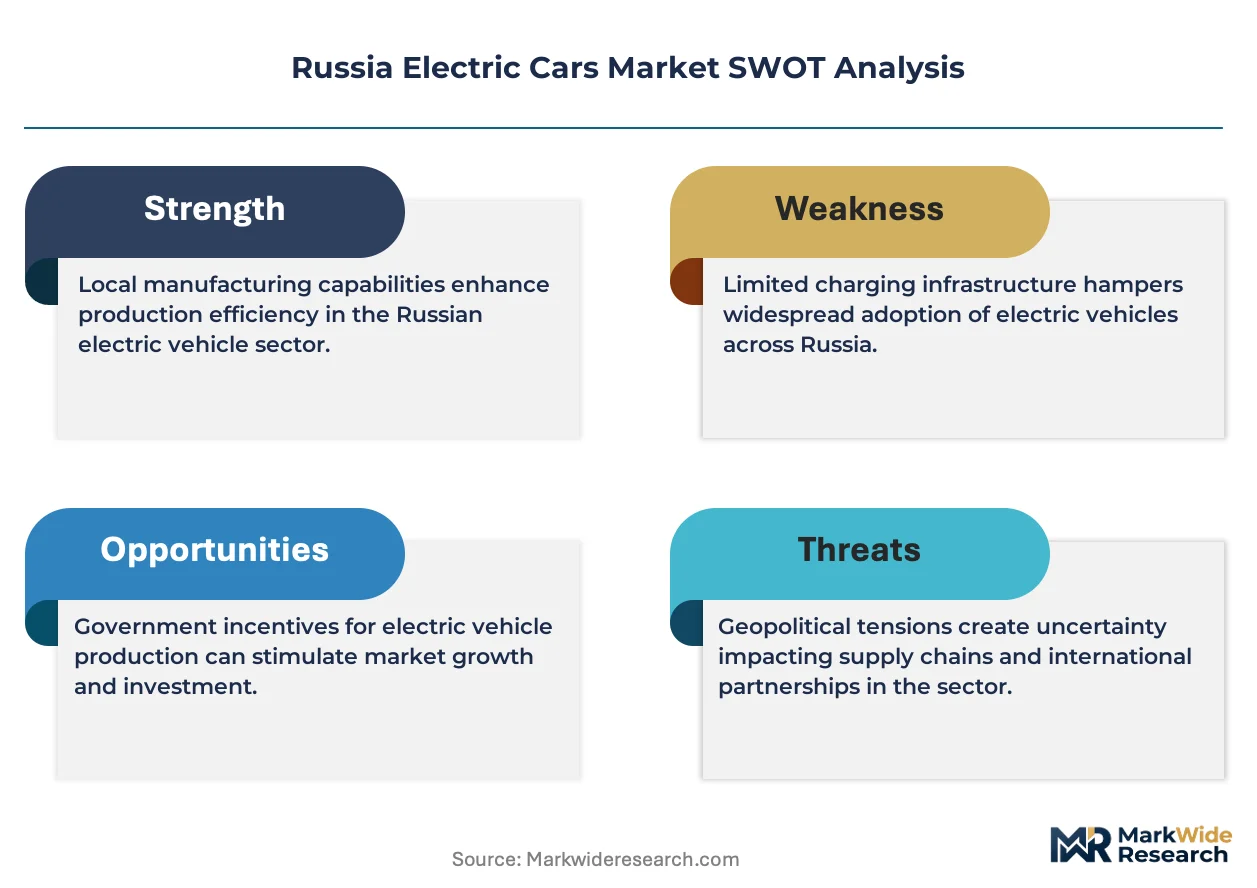
China's battery cell export capacity into Russia is fragmenting as logistics corridors reorient through Central Asian transshipment nodes. Hyundai Motor Company sustains assembly operations in Saint Petersburg, leveraging localized SKD kits to circumvent direct import tariffs. Chery Automobile Co. Ltd anchors the mass-market segment through distributor networks in Kazan and Yekaterinburg, while Kama competes on domestic brand recognition and state-backed fleet procurement channels.
Technical Definition and Segment Structure
Russia electric cars are battery-electric or plug-in hybrid passenger vehicles engineered for operation on federal highways and urban road networks, typically incorporating lithium-ion packs with cold-climate thermal management and regenerative braking calibrated for sub-zero temperatures. The vehicle type dimension shows SUVs capturing preference among private buyers seeking ground clearance on poorly maintained regional roads, while sedans dominate fleet operator tenders where total cost of ownership calculations favor aerodynamic efficiency. Within battery technology, lithium-ion occupies the installed base due to established supply chains, though solid-state chemistries are attracting R&D attention from domestic institutes seeking reduced fire risk in extreme cold.
Regulatory Environment
Russia's Ministry of Industry and Trade coordinates EV subsidy allocation alongside GOST R certification requirements that mandate electromagnetic compatibility and battery safety testing for market access. The EAEU technical regulation on wheeled vehicle safety shapes cross-border import rules, while Moscow's regional government operates zero-emission zone pilots that restrict internal combustion entry into the city center. Stakeholders must monitor how sanctions-driven component scarcity reshapes domestic assembly qualification criteria and whether state-backed leasing instruments expand beyond current pilot volumes.
Market Dynamics
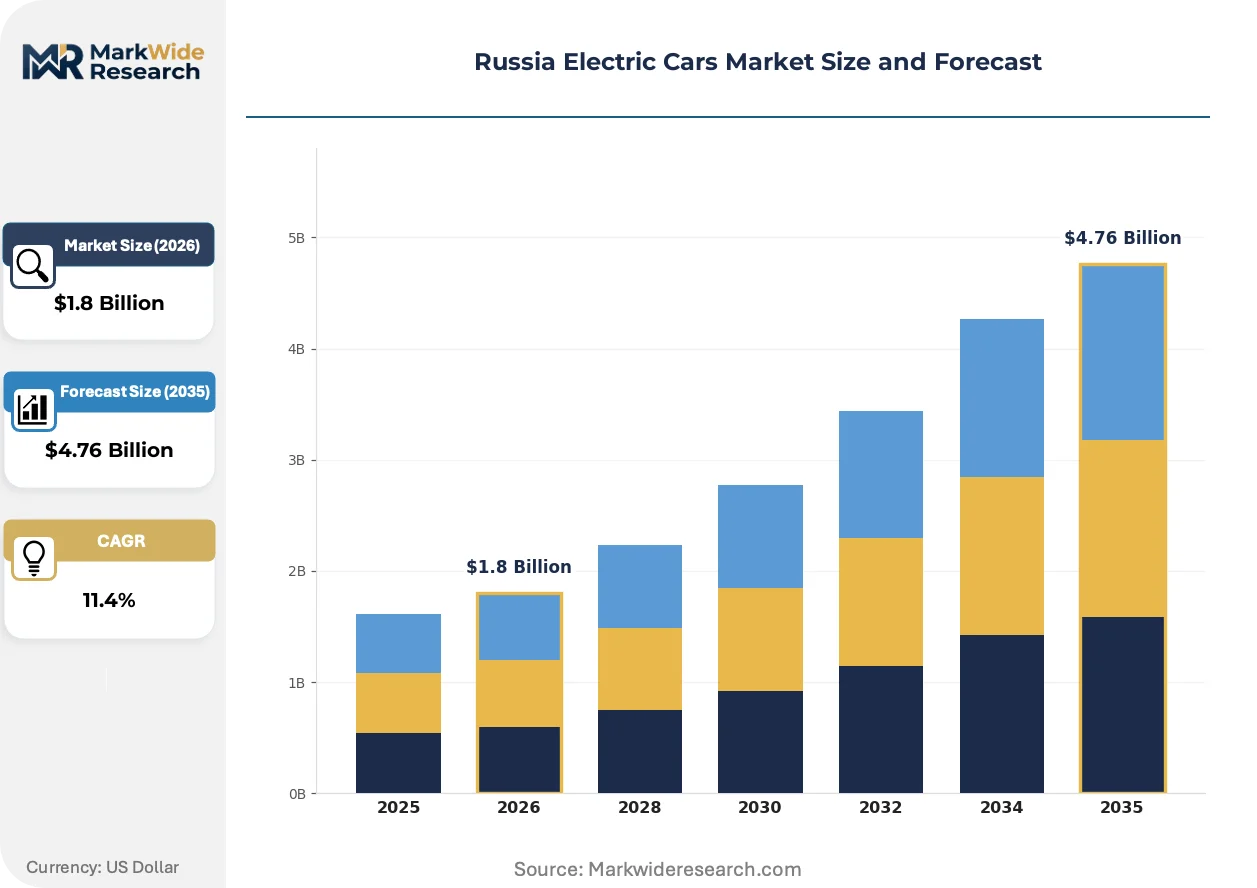
Domestic assembly qualification criteria are compressing import dependency as Moscow's subsidy program redirects procurement toward localized production. This structural pivot is reconfiguring supply chain routing through Central Asian transshipment nodes and reshaping competitive positioning among fleet operators and private buyers.
Growth Catalysts
- Moscow's Regional Subsidy Framework:Zero-emission zone pilots in the capital restrict internal combustion entry, creating mandatory demand pull for battery-electric fleet procurement.
- Lithium-Ion Thermal Management:Cold-climate battery engineering calibrated for sub-zero temperatures enables reliable federal highway operation across Siberian and Far Eastern corridors.
- Urban Logistics Electrification:Fleet operators in the Central Federal District are scaling light-commercial procurement to comply with municipal emission mandates and reduce fuel cost exposure.
Market Restraints
- Component Scarcity from Sanctions:Semiconductor and power electronics import restrictions are elongating SKD kit lead times and constraining Saint Petersburg assembly throughput.
- Charging Infrastructure Gaps:Federal highway networks outside the Moscow corridor lack DC fast-charging density, limiting inter-regional battery-electric viability.
- Petrol Price Subsidies:State-controlled gasoline pricing maintains total cost of ownership parity for internal combustion vehicles in non-urban districts.
Strategic Opportunities
- Solid-State Chemistry R&D:Domestic institutes are attracting state funding for reduced fire-risk battery architectures targeting extreme cold deployment.
- State-Backed Leasing Instruments:Pilot expansion of government fleet financing programs beyond current volumes could unlock mass-market private adoption.
- SUV Ground Clearance Preference:Poorly maintained regional roads in the Volga and Ural Federal Districts create white space for elevated battery-electric platforms with reinforced suspension.
Industry Challenges
- GOST R Certification Timelines:Electromagnetic compatibility and battery safety testing protocols are creating six-to-nine month market access delays for new entrants.
- Legacy Thermal Management Integration:Retrofitting existing service networks with high-voltage training and diagnostic equipment demands substantial retraining investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Electric Cars Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lithium Polymer Charging Infrastructure: Fast Charging Stations, Regular Charging Stations, Home Charging Solutions, Wireless Charging End User: Private Owners, Fleet Operators, Government Entities, Ride-Sharing Services |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, Chery Automobile Co. Ltd, BYD, Kama, Great Wall Motor Company Ltd, Volkswagen AG, Mercedes-Benz, Tesla Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Electric Cars Market Evolving Landscape
Regenerative braking systems recalibrated for sub-zero thermal cycles are becoming standard equipment, while supply chain reorientation through Kazakhstan and Uzbekistan is fragmenting traditional import corridors. These shifts are compressing legacy procurement models and enabling new domestic assembly ecosystems.
Advanced battery preconditioning algorithms that maintain cell temperature during extended parking periods are rendering obsolete conventional resistive heating approaches that degraded winter range by forty percent. Fleet operators in Moscow and Saint Petersburg are mandating this specification in tender documents. The technology is compressing total cost of ownership calculations that previously favored internal combustion in cold climates.
EAEU technical regulation harmonization on wheeled vehicle safety is streamlining cross-border type approval between Russia, Belarus, and Kazakhstan. Domestic assemblers are leveraging this framework to source SKD kits through EAEU-qualified suppliers rather than direct import channels. The regulation most affects passenger vehicle categories seeking rapid multi-country market access.
Direct-to-fleet sales channels are bypassing traditional distributor markups as large logistics operators negotiate volume contracts with domestic assembly plants. Kazan and Yekaterinburg distributor networks are losing share to manufacturer-operated fleet account teams. This pattern concentrates in the Central Federal District where procurement scale justifies dedicated sales infrastructure.
Russia Electric Cars Market Segmentation
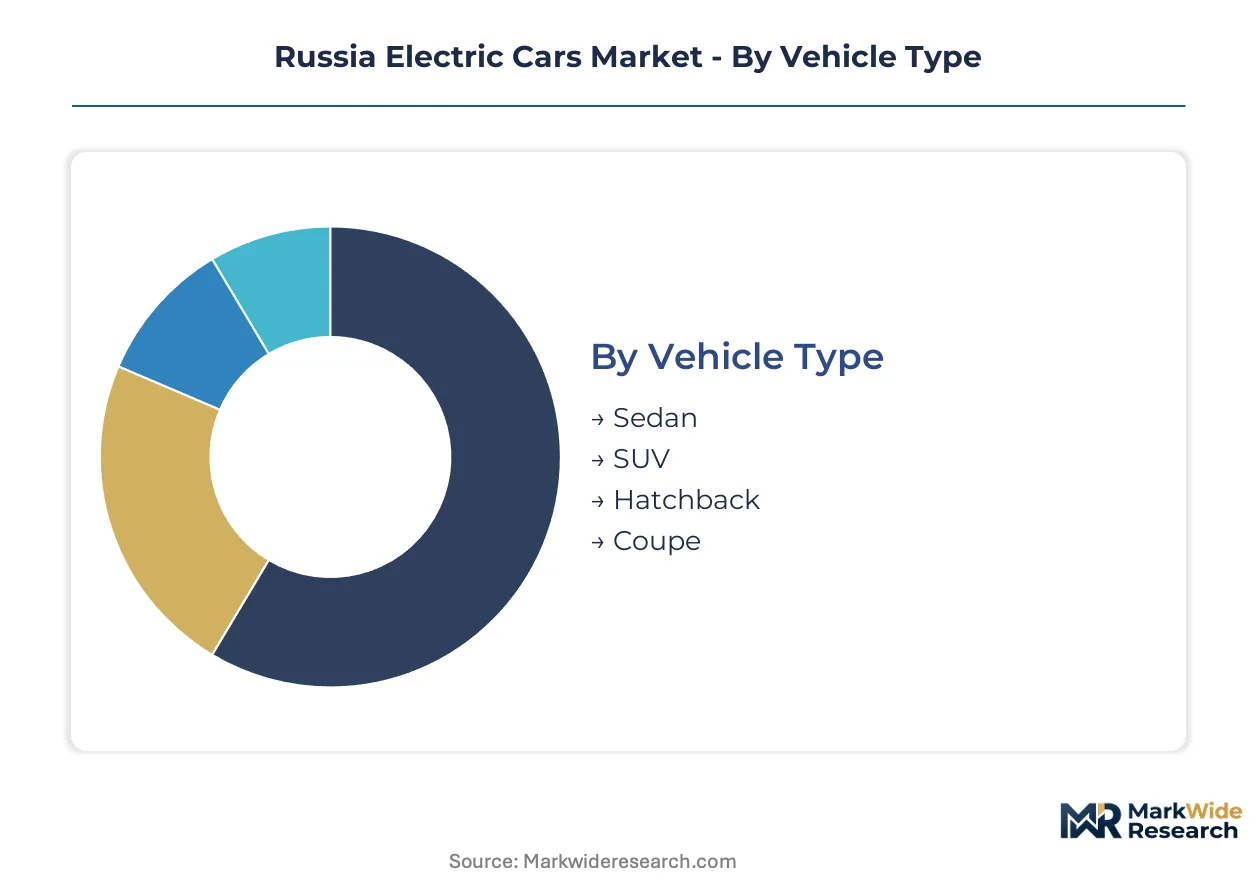
Segmentation in the Russia Electric Cars Market exposes divergent procurement rhythms across vehicle categories and powertrain technologies. Fleet operators cycle through light-commercial units on compressed timelines while private buyers retain passenger vehicles longer, creating tiered demand pulses that reshape inventory planning and subsidy allocation.
Vehicle Type:
Replacement cycles stretch longest for sedans deployed in government fleets and shortest for hatchbacks in urban ride-sharing pools, with SUVs occupying the middle band where private ownership dominates.
- SUV:Elevated ground clearance and reinforced suspension accommodate poorly maintained regional roads across the Volga and Ural Federal Districts. Procurement concentrates among private buyers in Moscow and Saint Petersburg seeking all-weather capability on degraded infrastructure.
- Sedan:Aerodynamic efficiency drives total cost of ownership advantages in high-mileage fleet applications. Tender volumes from Central Federal District logistics operators favor this configuration for highway-intensive routes where drag coefficients directly impact energy consumption.
- Hatchback:Compact dimensions suit dense urban parking constraints in Saint Petersburg's historic core.
- Coupe:Premium positioning attracts niche demand from affluent private buyers in Moscow's zero-emission zones.
Sedans anchor the volume base while SUVs gain share at the steepest rate as regional road conditions deteriorate and private buyers prioritize durability.
Battery Technology:
Cost tiers separate established chemistries with depreciated capital equipment from emerging architectures requiring fresh manufacturing investment and qualification timelines.
- Lithium-Ion:Mature cell production lines in China supply the installed base through Central Asian transshipment corridors. Cold-climate thermal management systems from domestic engineering institutes extend operational viability across Siberian temperature extremes.
- Solid-State:Reduced fire-risk architectures attract state-funded R&D from Moscow-based battery institutes targeting extreme cold deployment. Pilot programs with fleet operators in the capital test pre-commercial cells for winter reliability validation.
- Nickel-Metal Hydride:Legacy hybrid applications persist in import-restricted service environments.
- Lithium Polymer:Flexible form factors enable compact hatchback pack integration.
Lithium-Ion dominates current procurement volumes while Solid-State expands most quickly as safety certification accelerates for sub-zero operation.
Charging Infrastructure:
Application context determines infrastructure preference, with inter-regional haulers requiring fundamentally different support than urban residential users.
- Fast Charging Stations:DC hardware along federal highways enables battery-electric viability for long-distance fleet routes. Deployment concentrates in the Moscow corridor where subsidy density supports capital recovery on high-utilization sites.
- Home Charging Solutions:Level 2 residential units dominate private owner adoption in multi-unit housing complexes. Moscow's regional government mandates pre-wiring in new construction, embedding infrastructure before vehicle penetration matures.
- Regular Charging Stations:AC destination charging serves workplace and retail parking durations.
- Wireless Charging:Inductive pads remain pilot-scale for premium fleet depots.
Home Charging Solutions represent the deepest installed base while Fast Charging Stations climb the fastest as federal highway coverage gaps constrain inter-regional expansion.
End User:
Customer type shapes volume concentration and margin structure, with aggregated fleet purchasing power diverging sharply from fragmented private demand.
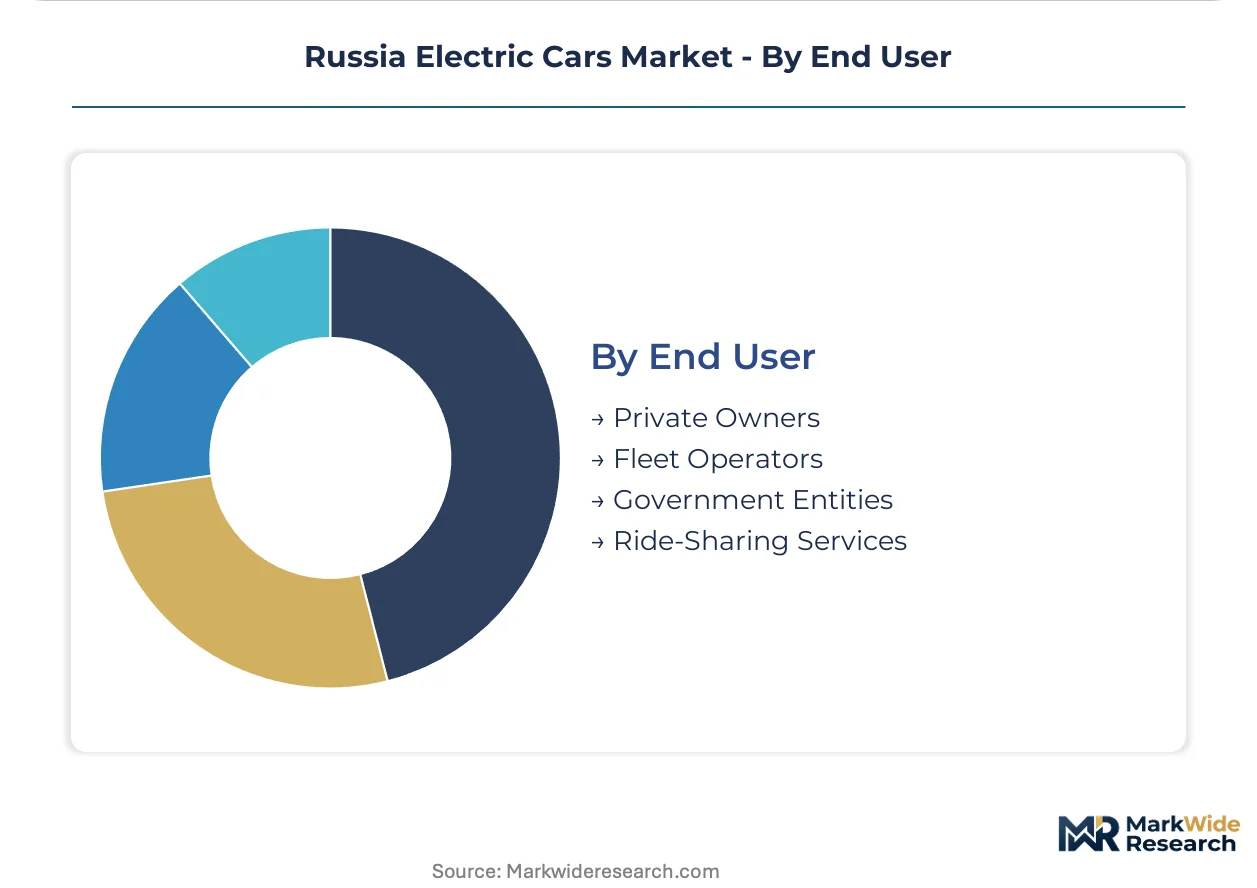
- Fleet Operators:Centralized procurement from logistics companies in the Central Federal District drives aggregated demand for light-commercial electrification. Direct-to-fleet sales channels bypass traditional distributor markups as volume contracts with domestic assembly plants compress acquisition costs.
- Private Owners:Individual buyers in Moscow and Saint Petersburg respond to zero-emission zone restrictions and parking privileges. State-backed leasing instruments in pilot expansion could unlock mass-market penetration beyond current early-adopter profiles.
- Government Entities:Municipal procurement mandates prioritize domestic assembly qualification for subsidy eligibility.
- Ride-Sharing Services:Platform operators cycle vehicles rapidly on utilization-based depreciation schedules.
Fleet Operators anchor the volume base while Private Owners gain share at the steepest rate as subsidy instruments mature and charging density improves in residential clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly plants cluster in the Central Federal District around Moscow, where subsidy density and charging corridor maturity concentrate procurement decisions. State-backed localization programs redirect component flows through Kazakhstan and Uzbekistan, compressing traditional import channels.
Moscow Oblast
Fleet operators in the capital's zero-emission zones drive light-commercial electrification at scale. The Ministry of Industry and Trade coordinates subsidy allocation for domestic assembly qualification. Charging infrastructure deployment concentrates along the Moscow Ring Road corridor where DC fast-charging utilization rates justify capital recovery.
Saint Petersburg
SKD kit assembly operations leverage the Baltic port logistics for component transshipment. GOST R certification requirements mandate electromagnetic compatibility testing for market access. The city's historic core parking constraints accelerate hatchback procurement from ride-sharing platforms.
Tatarstan
Kazan anchors distributor networks serving the Volga Federal District's deteriorating road infrastructure. Regional road maintenance budgets favor SUV ground clearance specifications in private buyer preference. The republic's industrial base supports domestic battery thermal management system integration.
Sverdlovsk Oblast
Yekaterinburg distributor networks compete with direct-to-fleet sales channels from domestic assembly plants. EAEU technical regulation harmonization streamlines cross-border type approval with Kazakhstan. The Ural Federal District's extreme cold drives demand for preconditioning algorithm validation in fleet tenders.
Krasnoyarsk Krai
Siberian temperature extremes test lithium-ion cold-climate engineering beyond standard federal highway specifications. Federal highway charging gaps constrain inter-regional battery-electric viability outside the Moscow corridor. Regional fleet operators prioritize thermal management reliability over acquisition cost in procurement criteria.
Russia Electric Cars Market Competitive Landscape
Domestic assemblers and international kit-based producers split the market along subsidy eligibility lines. Market structure tilts toward localized production qualification as Moscow's subsidy framework redirects procurement. Three archetypes dominate: state-backed domestic brands, Asian kit-assemblers leveraging SKD routes, and premium importers navigating certification delays. Competitive moves center on backward integration into battery supply and direct-to-fleet sales channel establishment.
Among Asian kit-assemblers, Chery Automobile Co. Ltd and Hyundai Motor Company exemplify the SKD-based localization archetype, while Kama occupies the state-backed domestic tier. Toyota Motor Corporation and Volkswagen AG represent established premium importers navigating GOST R certification timelines. These anchors illustrate how subsidy eligibility and supply chain routing determine competitive positioning rather than product specification alone.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Chery Automobile Co. Ltd |
| BYD |
| Kama |
| Great Wall Motor Company Ltd |
| Volkswagen AG |
| Mercedes-Benz |
| Tesla Inc. |
| Others |
Value Network & Pricing Analysis
Saint Petersburg's SKD assembly corridor concentrates kit-based production capacity, compressing procurement timelines for domestic assemblers while fragmenting pricing power among distributor networks competing with direct-to-fleet channels. Moscow's subsidy allocation framework rewards localized production qualification, creating tiered cost structures that separate state-backed fleet tenders from premium private buyer segments.
Pricing Analysis
GOST R certification requirements dictate the pricing tier structure across the Russia electric cars market, separating economy-tier SKD-assembled units from premium imports navigating six-to-nine month electromagnetic compatibility testing delays. Price differentiation centers on domestic assembly qualification for subsidy eligibility and cold-climate thermal management specification grade. Cost compression in the economy tier intensifies as Chery and Hyundai volume contracts compress distributor markups. Fleet operators in the Central Federal District exhibit highest price sensitivity due to total cost of ownership mandates, while Moscow private buyers in zero-emission zones show lowest sensitivity to acquisition premiums.
Supply Chain Analysis
Extended payment terms from Kazakhstan-based logistics intermediaries are restructuring working capital requirements for domestic assemblers sourcing through Central Asian transshipment nodes. Component flows draw from China, South Korea, and Belarus, with lithium-ion cells and power electronics anchoring raw material dependencies. Single-source vulnerability concentrates in semiconductor imports subject to sanctions-driven restriction. Distribution runs through manufacturer-operated fleet account teams bypassing traditional Kazan and Yekaterinburg distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Russia electric cars market functions as a service-attach opportunity where thermal management system integration and high-voltage diagnostic training contracts expand faster than vehicle hardware sales. Fleet operators increasingly mandate extended warranty and preconditioning algorithm validation as tender requirements, embedding recurring revenue layers.
For Market Incumbents: Entrench subsidy eligibility through accelerated domestic assembly qualification in Moscow Oblast and Saint Petersburg. Secure captive supply of cold-climate battery thermal management systems from Tatarstan engineering institutes to defend against emerging solid-state chemistry entrants. Prioritize direct-to-fleet sales channel investment to compress distributor-dependent competitors. For New Entrants and Emerging Players: Pursue SUV platform white space in the Volga and Ural Federal Districts where deteriorating road infrastructure creates ground clearance demand unmet by sedan-focused incumbents. Target Krasnoyarsk Krai fleet operators prioritizing extreme cold reliability over acquisition cost. Establish EAEU technical regulation harmonization pathways for rapid multi-country type approval. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic assemblers with backward integration into battery supply and state-backed leasing instrument relationships. Long-term viability hinges on solid-state chemistry R&D funding access and charging infrastructure deployment density. Watch fleet operator tender specifications for preconditioning algorithm mandates as inflection indicator for thermal management technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell flows through Kazakhstan transshipment corridors for Saint Petersburg assembly. |
| Charging Infrastructure Partnership | Deploys DC fast-charging along Moscow Ring Road corridor where subsidy density supports capital recovery. |
| Software-Defined Vehicle Investment | Enables over-the-air preconditioning algorithm updates validated in Siberian fleet pilot programs. |
| Geographic Manufacturing Footprint | Expands SKD kit assembly to Tatarstan for proximity to Volga Federal District SUV demand. |
| Platform Standardization | Reduces GOST R certification timelines by unifying electromagnetic compatibility testing across model ranges. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, fleet operator tender managers, and charging infrastructure developers provided ongoing calibration across the research process. Primary fieldwork combined structured interviews with secondary validation from EAEU technical regulation filings, vehicle production databases, and customs transshipment records. Bottom-up segment sizing triangulated against top-down macroeconomic anchoring.
Scenario-bracketing framed demand projections across the analysis window, modeling vehicle type, battery technology, charging infrastructure, and end user dimensions alongside regional subsidy density variations. CAGRs derived from logistic diffusion curves fitted to observed fleet procurement cycles and private adoption patterns. Forecast inputs incorporated GOST R certification timeline distributions and EAEU cross-border type approval velocity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed domestic brands or accelerated solid-state chemistry commercialization would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
South America E-Bike Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
E-Bike Smart Systems Market