
 GCC Microwave Oven Market | 2026-2036
GCC Microwave Oven Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Microwave Oven Market Foresight
Market Context
Product bundling with built-in ventilation and smart connectivity is restructuring buyer choice across GCC kitchen-appliance procurement. Samsung Electronics leverages its regional distribution network to sustain premium positioning in Saudi electronics retail chains. LG Electronics anchors its competitiveness through inverter technology specialization. Midea competes aggressively on cost-engineered countertop units targeting food service providers.
Technical and Segment Dynamics
A microwave oven is an electric appliance that generates electromagnetic radiation at 2.45 GHz to heat polar molecules in food, with cavity sizes typically spanning 20 to 40 liters for commercial and residential deployment. Its primary purpose is rapid thermal processing for defrosting, reheating, and cooking across hospitality and household environments. Convection microwave units command the strongest margin pools as buyers trade up for dual-functionality. The food service provider end-user segment expands fastest, driven by cloud kitchen proliferation across Dubai and Riyadh. Solo microwave sales dominate volume through hypermarket channels but face compression as grill and over-the-range configurations gain traction.
Regulatory Environment
Saudi Standards, Metrology and Quality Organization (SASO) energy-efficiency labeling requirements and UAE's Emirates Authority for Standardization and Metrology (ESMA) technical regulations shape product compliance costs and import clearance timelines for manufacturers. Gulf Standardization Organization (GSO) harmonized safety standards further unify market access protocols across member states. Stakeholders must monitor evolving minimum energy performance standards and local content incentives that could redirect sourcing strategies.
Market Dynamics
Energy-efficiency mandates from SASO and ESMA are compressing import clearance timelines and forcing manufacturers to redesign power systems before products reach Saudi and UAE distribution channels.
Growth Catalysts
- Cloud kitchen proliferation:Food service operators across Dubai and Riyadh are outfitting compact commercial spaces with high-duty-cycle microwave units, creating sustained equipment replacement cycles.
- Inverter technology maturation:Power management advances reduce energy draw during variable-load cooking, aligning with Gulf utility cost structures and building code incentives.
- Emirates Authority for Standardization and Metrology technical regulations:ESMA's phased efficiency tiers are accelerating trade-ups from solo to convection configurations among UAE hospitality procurement teams.
Market Restraints
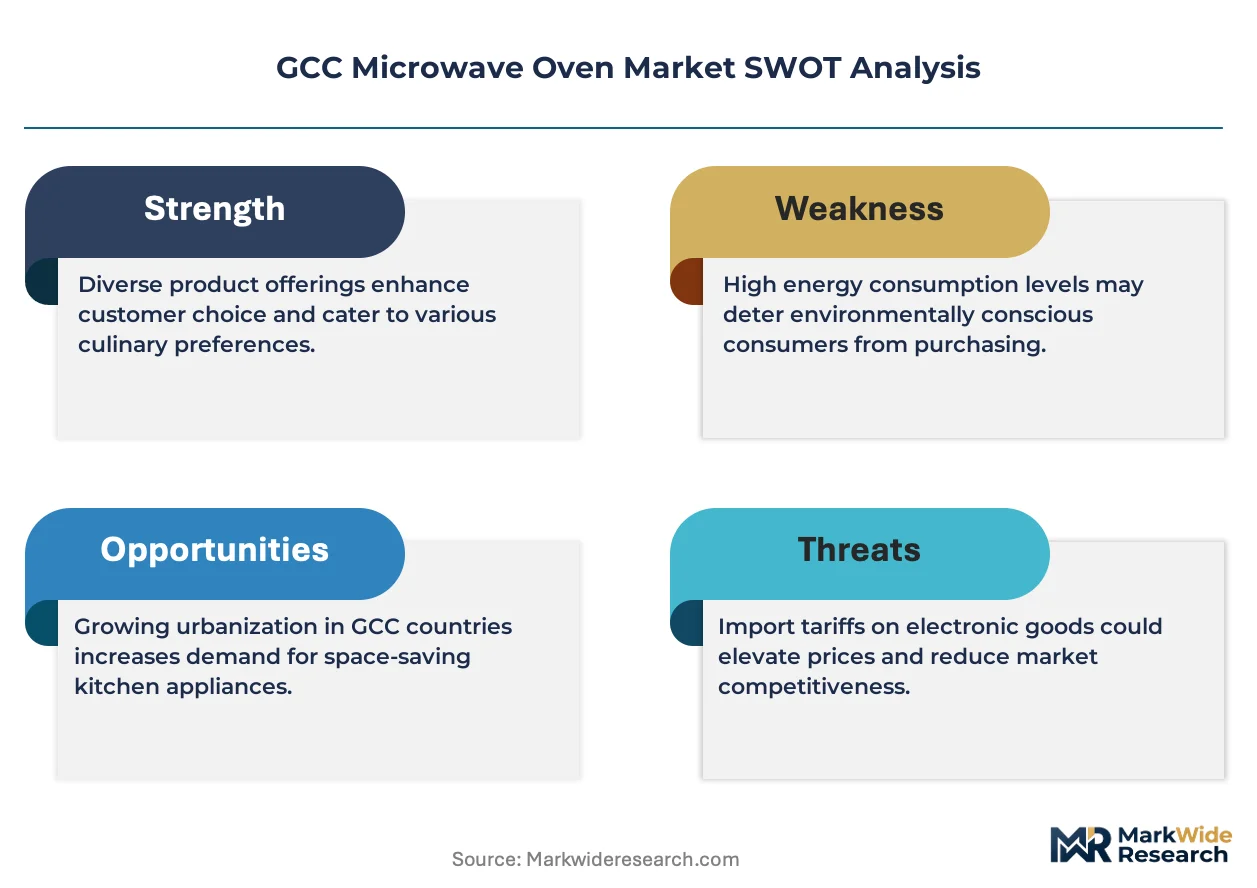
- Steel and copper input volatility:Magnetron manufacturing and cavity fabrication depend on commodity metals whose price swings compress margin predictability for cost-engineered product lines.
- Import concentration through Jebel Ali:Single-gateway clearance for much of GCC volume creates bottleneck risk during peak seasonal shipping windows.
- Induction cooktop substitution:Commercial kitchens evaluating speed-cooking alternatives are diverting capex toward combined induction-ranges in premium build-outs.
Strategic Opportunities
- Kuwait and Oman underpenetration:Lower cloud kitchen density in these markets leaves room for first-mover distribution partnerships with regional food service equipment dealers.
- Smart connectivity integration:IoT-enabled remote diagnostics and usage analytics are opening recurring-revenue service contracts with multi-unit hospitality operators.
- Saudi local content incentives:SASO's evolving domestic manufacturing preferences could reward assembly or component sourcing shifts toward the Kingdom's industrial zones.
Industry Challenges
- Certification timeline compression:Gulf Standardization Organization harmonized safety standards require simultaneous multi-market testing, extending product launch schedules.
- Magnetron supply reconfiguration:Sourcing shifts away from legacy Asian suppliers demand qualification of alternative component vendors without disrupting production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Microwave Oven Market |
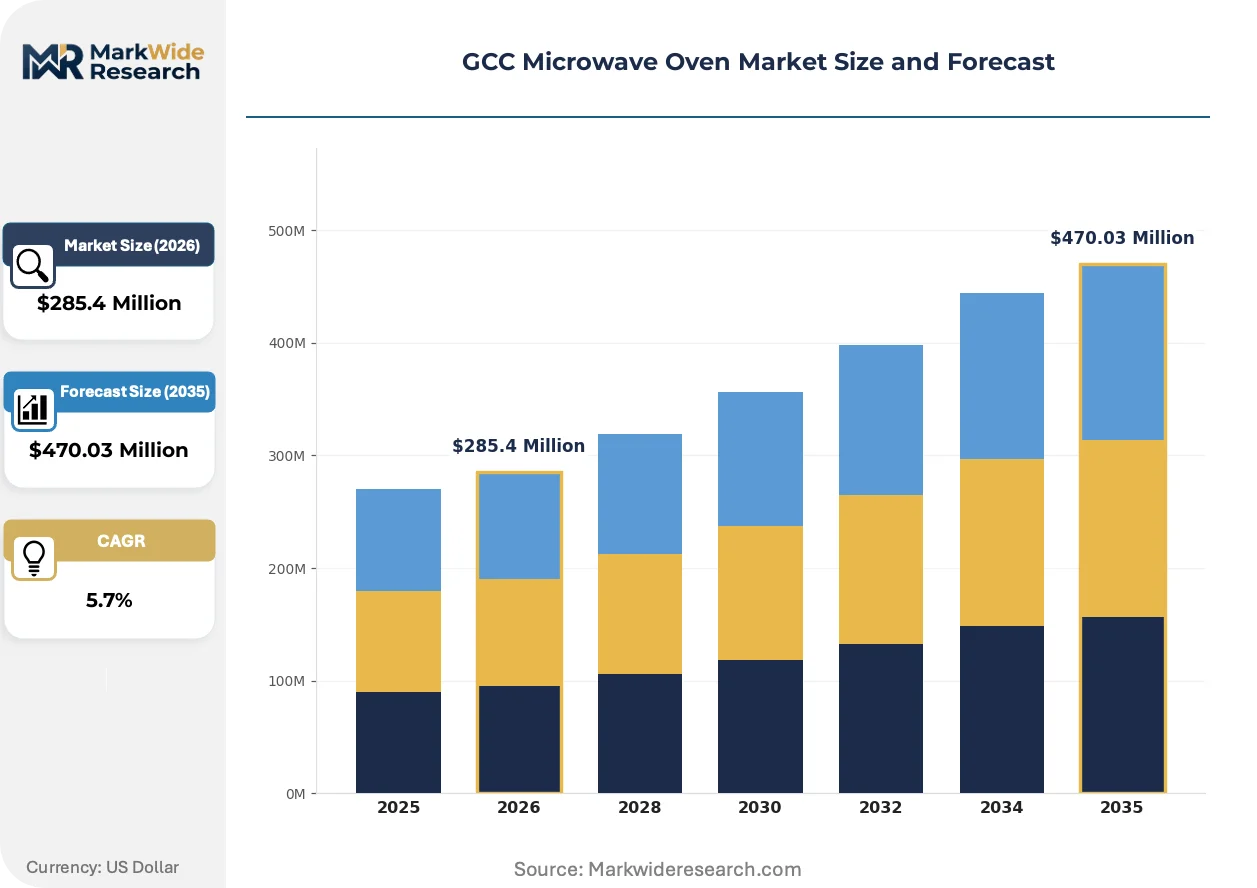
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $470.03 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solo Microwave, Grill Microwave, Convection Microwave, Over-the-Range Microwave, Countertop Microwave Technology: Inverter, Traditional, Sensor, Compact, Turntable End User: Residential, Food Service Providers, Commercial Kitchens, Hospitality, Institutional Cafeterias Distribution Channel: Online Retailers, Specialty Stores, Hypermarkets, Electronics Retail Chains, Wholesale Suppliers |
| Companies Covered | Whirlpool Corporation, Hitachi Ltd, Samsung Electronics, Sharp Corporation, Midea, LG Electronics, Electrolux AB, Hoover Limited, Panasonic Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Microwave Oven Market Shifts & Advancements
Product architecture is splitting between connected premium platforms and stripped-down commercial workhorses, with regulatory pressure on energy draw forcing divergent engineering investments.
Inverter power management is decentralizing thermal control away from fixed-output magnetrons toward variable-frequency drives that match energy input to food load. Cloud kitchen operators in Dubai's Al Quoz industrial zone are specifying these units for defrost-to-serve workflows that minimize electricity draw during off-peak hours. The shift is compressing demand for conventional solo microwave configurations in new commercial fit-outs.
SASO energy-efficiency labeling requirements are mandating graduated performance tiers that manufacturers must meet for Saudi import clearance. The regulations are forcing redesigns of magnetron housing and cavity insulation to hit prescribed wattage-per-liter thresholds. Grill and convection microwave categories face the steepest compliance cost escalation given their higher baseline power draws.
After-sales service unbundling is fragmenting buyer relationships with traditional equipment distributors. Hospitality groups in Riyadh are negotiating direct parts-and-labor contracts with third-party maintenance networks, bypassing retail channel markups. The pattern is most pronounced among Saudi hotel chains operating standardized kitchen templates across multiple properties.
GCC Microwave Oven Market Segmentation
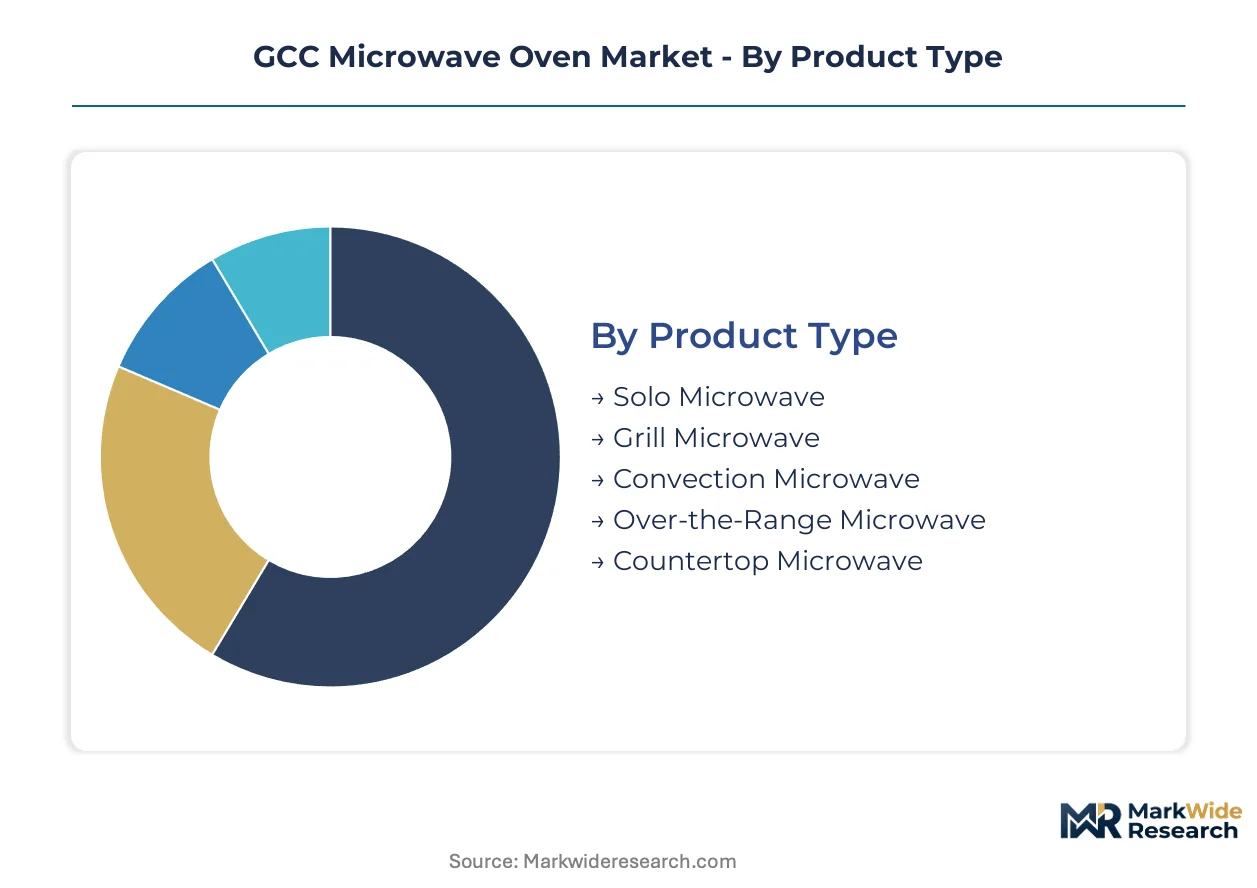
Product architecture and procurement patterns diverge sharply across buyer categories in the GCC microwave oven market. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume trades on price.
Product Type:
Commercial buyers prioritize cooking modality flexibility over pure thermal output, reshaping how manufacturers allocate R&D between single-function and dual-purpose platforms.
- Solo Microwave:Basic magnetron-based units deliver fixed-power heating through 20-30 liter cavities. Saudi hypermarket channels move these units in highest absolute volume, though ASP compression intensifies as grill and convection alternatives penetrate.
- Convection Microwave:Forced-air circulation combines with microwave energy for roasting and baking workflows. Dubai cloud kitchens specify these for menu breadth without full oven footprints, driving fastest category expansion.
- Grill Microwave:Quartz or sheath heater elements add browning capability to microwave cores. Riyadh residential buyers trade up for kebab and flatbread preparation.
- Over-the-Range Microwave:Integrated ventilation and cooktop lighting suit compact UAE apartment kitchens with space constraints.
- Countertop Microwave:Plug-and-deploy portability targets food service providers with temporary or mobile operational setups.
Solo Microwave leads on scale; Convection Microwave leads on momentum.
Technology:
Energy-efficiency mandates from SASO and ESMA are accelerating displacement of fixed-output magnetron designs across all buyer tiers.
- Inverter:Variable-frequency drives modulate power delivery to match food load rather than cycling full output. UAE hospitality procurement teams specify these for utility cost alignment and ESMA tier compliance.
- Sensor:Humidity and temperature feedback loops auto-adjust cooking duration. Saudi residential buyers in Riyadh-Jeddah corridor show willingness to pay premium for reduced supervision.
- Traditional:Fixed-power magnetron cycling remains standard in cost-engineered commercial units. Price-sensitive food service providers in Oman and Kuwait default here.
- Compact:Reduced cavity dimensions target single-person households and limited-footprint cloud kitchen stations.
- Turntable:Rotating glass platforms ensure even heating distribution; now baseline expectation rather than differentiator.
Traditional technology leads on scale; Inverter leads on momentum.
End User:
Equipment replacement cycles and specification authority sit with different stakeholders across household versus commercial deployment contexts.
- Food Service Providers:Cloud kitchen operators and quick-service chains drive equipment refresh on 3-5 year cycles. Dubai's Al Quoz and Riyadh's industrial zones concentrate demand for high-duty-cycle units.
- Residential:Household replacement stretches 7-10 years, with purchase decisions influenced by retail promotion timing and kitchen renovation schedules.
- Hospitality:Hotel chains standardize kitchen templates across properties, creating bulk procurement leverage and direct service contract negotiations.
- Commercial Kitchens:Independent restaurants balance equipment cost against menu versatility requirements.
- Institutional Cafeterias:Schools, hospitals, and corporate facilities prioritize durability and warranty coverage over feature depth.
Residential leads on scale; Food Service Providers lead on momentum.
Distribution Channel:
Channel selection determines margin capture, after-sales service bundling, and buyer relationship durability for manufacturers.
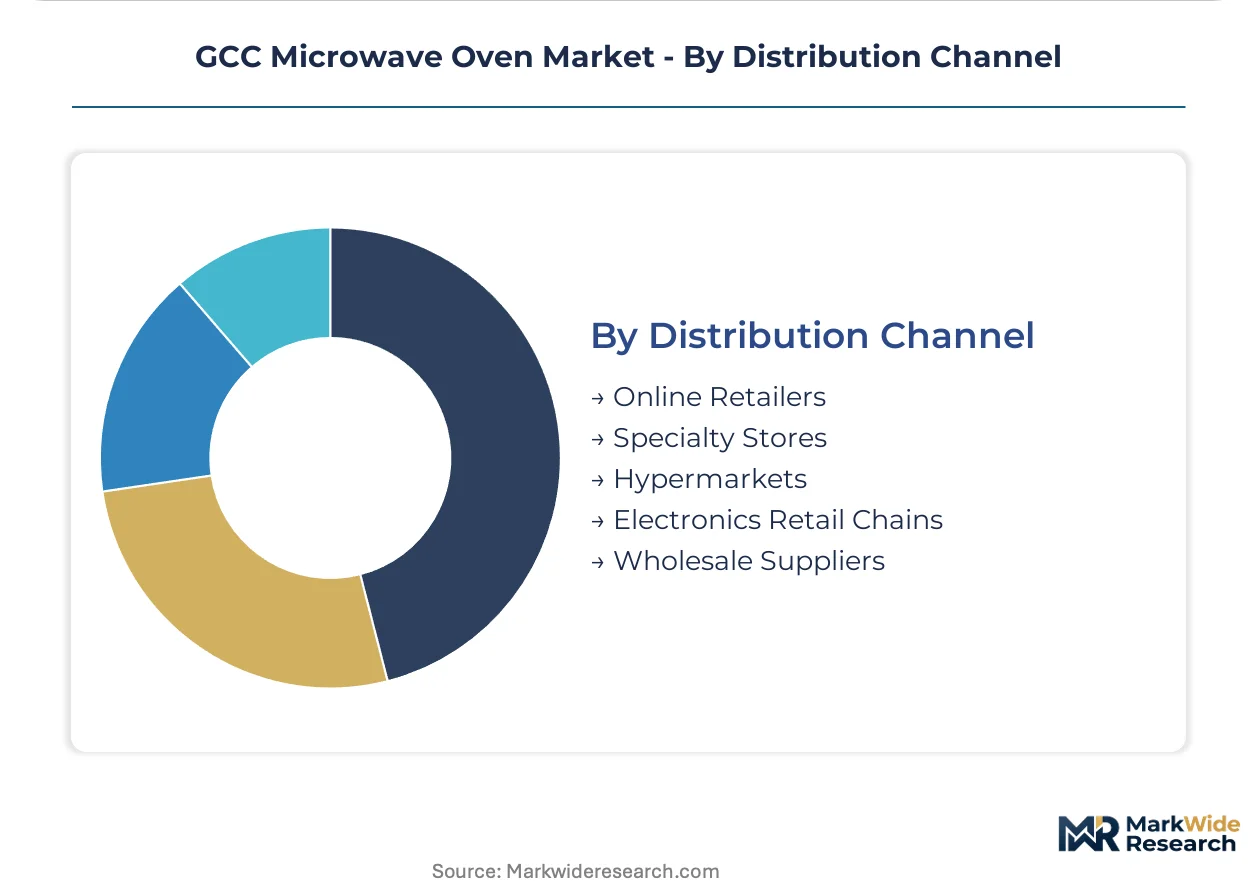
- Electronics Retail Chains:Samsung and LG anchor premium positioning through dedicated floor space and trained sales staff. Saudi chains like Jarir and Extra dominate Riyadh-Jeddah corridor household purchases.
- Online Retailers:Price transparency and comparison shopping attract tech-savvy residential buyers. Delivery logistics now cover same-day in Dubai and next-day in Riyadh.
- Hypermarkets:Carrefour and Lulu move highest solo microwave volume through promotional bundling and impulse placement.
- Specialty Stores:Kitchen design showrooms specify built-in and over-the-range units for renovation projects.
- Wholesale Suppliers:Direct relationships with food service equipment dealers bypass retail markups for hospitality and cloud kitchen procurement.
Hypermarkets lead on scale; Online Retailers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microwave oven manufacturing scaled through East Asian industrial corridors before Gulf markets emerged as high-value procurement destinations. The GCC now functions as a premium-import zone where energy-efficiency regulations and hospitality-sector expansion reshape demand patterns.
Saudi Arabia
Commercial kitchen build-outs across Riyadh's hospitality sector drive sustained equipment procurement. SASO energy-efficiency labeling requirements mandate graduated performance tiers that compress import clearance timelines for non-compliant inventory. The Riyadh-Jeddah corridor concentrates cloud kitchen clustering and retail distribution infrastructure.
United Arab Emirates
ESMA technical regulations accelerate trade-ups from solo to convection configurations among Dubai hospitality procurement teams. Dubai's Al Quoz industrial zone anchors cloud kitchen proliferation with high-duty-cycle microwave specifications. Abu Dhabi's hotel development pipeline sustains bulk equipment tenders through standardized kitchen templates.
Kuwait
Lower cloud kitchen density relative to Saudi Arabia and the UAE leaves distribution partnerships with regional food service equipment dealers underdeveloped. The country's national standards body enforces GSO harmonized safety standards without additional domestic efficiency tiers. Kuwait City retail channels move primarily solo microwave volume through hypermarket promotional cycles.
Oman
Food service provider procurement remains price-sensitive, defaulting to traditional fixed-power magnetron units. The Sultanate's consumer protection authority maintains baseline import safety protocols without SASO-equivalent efficiency mandates. Muscat's commercial kitchen fit-outs prioritize cost-engineered countertop configurations over convection platforms.
Qatar
Hospitality-sector procurement concentrates around FIFA-legacy hotel inventory and new luxury development. The Qatar General Organization for Standardization aligns with GSO frameworks while maintaining discrete import inspection protocols. Doha's food service landscape shows emerging cloud kitchen activity in industrial zone conversions.
GCC Microwave Oven Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology-tier and distribution-channel dimensions. Samsung Electronics and LG Electronics anchor the premium tier through electronics retail chain partnerships, while Midea occupies cost-engineered commercial segments. The market structure fragments across three strategic archetypes: diversified appliance conglomerates, specialized microwave manufacturers, and regional distribution-focused assemblers. Competitive moves concentrate on inverter technology licensing and direct service contract negotiations with hospitality groups bypassing traditional retail markups.
Among diversified appliance conglomerates, Whirlpool Corporation and Electrolux AB exemplify portfolio-breadth strategies spanning residential and commercial segments. Panasonic Corporation and Sharp Corporation represent specialized microwave manufacturers with historical magnetron supply relationships. Samsung Electronics anchors the premium-tier vector through trained sales staff deployment in Saudi retail chains. LG Electronics sits within the technology-differentiation archetype through inverter specialization. Midea exemplifies cost-engineered volume positioning targeting food service providers with stripped-down commercial workhorses.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Hitachi Ltd |
| Samsung Electronics |
| Sharp Corporation |
| Midea |
| LG Electronics |
| Electrolux AB |
| Hoover Limited |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ESMA-compliant inverter units and traditional fixed-power magnetrons manifests in parallel supply chain configurations. Saudi and UAE procurement teams pay efficiency premiums that cascade backward to component sourcing decisions, while cost-engineered lines for Oman and Kuwait draw from unbundled magnetron suppliers without tiered testing overhead.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs GCC microwave procurement. ESMA tier certification and after-sales service bundling separate premium inverter units from commodity solo configurations. Pricing pressure stems from steel and copper input volatility compressing margins on cost-engineered commercial lines. Food service providers in Oman and Kuwait exhibit highest price sensitivity, while Dubai hospitality groups absorb premiums for remote diagnostics integration.
Supply Chain Analysis
Magnetron supply rests on Chinese and South Korean component manufacturers with legacy fabrication relationships. Cavity steel, copper windings, and magnetron cores feed from East Asian industrial corridors. Single-gateway clearance through Jebel Ali creates bottleneck risk during Ramadan shipping windows. Distribution runs through Saudi electronics retail chains, UAE hypermarket networks, and direct wholesale relationships with cloud kitchen operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates where inverter technology maturation meets SASO efficiency mandates, compressing cost differentials between premium and mid-tier configurations.
For Market Incumbents: Deepen backward integration into magnetron housing and cavity insulation production to offset commodity metal volatility. Lock exclusive service contracts with Riyadh hotel chains bypassing retail channel markups. ESMA tier acceleration threatens fixed-power inventory obsolescence—accelerate inverter platform rollout before Q3 procurement cycles. For New Entrants and Emerging Players: SASO energy-efficiency labeling requirements in Saudi Arabia open a window for certification-first positioning against legacy importers. Target Kuwait and Oman cloud kitchen equipment dealers with stripped-down commercial workhorses. Lead with direct wholesale pricing to food service providers, undercutting electronics retail chain markups by fifteen to twenty points. For Investors and Strategic Acquirers: Consolidation pressure builds where regional distribution-focused assemblers lack inverter technology licensing and face SASO compliance cost escalation. Five-to-ten year viability favors players with captive magnetron supply relationships and direct hospitality service networks. Watch for ESMA tier enforcement tightening as signal for premium-tier market share capture acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Technology Licensing | ESMA tier compliance in UAE accelerates displacement of fixed-power magnetron platforms. |
| Direct Service Contract Negotiation | Riyadh hotel chains bypass retail markups for standardized kitchen template maintenance. |
| Magnetron Supply Reconfiguration | Qualification of alternative Asian vendors reduces single-source dependency risk. |
| Cloud Kitchen Distribution Partnership | Al Quoz and Riyadh industrial zones concentrate high-duty-cycle replacement demand. |
| Smart Connectivity Integration | IoT-enabled diagnostics open recurring-revenue contracts with multi-unit hospitality operators. |
Research Methodology
Direct dialogue with Saudi electronics retail chain buyers, UAE hospitality procurement directors, cloud kitchen operators in Dubai's Al Quoz, and Kuwaiti food service equipment dealers grounded qualitative findings. Secondary validation drew from SASO technical regulation filings, ESMA efficiency tier documentation, GSO harmonized safety standards, and customs clearance data through Jebel Ali. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-level outputs across product type, technology tier, end-user category, and distribution channel fed into analytical framework construction over the projection horizon. CAGRs derived from regression against historical appliance penetration rates, cloud kitchen build-out pipelines, and regulatory phase-in schedules. Magnetron cost curves and steel price indices informed margin compression modeling for cost-engineered product lines.
Revisions become necessary when SASO domestic manufacturing incentives redirect sourcing strategies or ESMA enforces stricter efficiency tiers ahead of published timelines. Forecasts reflect assumptions about cloud kitchen proliferation sustaining three-to-five year replacement cycles and commodity metal price stabilization. A small set of named triggers—magnetron supply disruption, Jebel Ali congestion, induction cooktop substitution acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Fully Automatic Dishwasher Market
Appliances
Conveyor Dishwasher Market
Appliances
Electric Dryers Market
Appliances
Turkey Washing Machine Market
Appliances
Residential Space Heater Market
Appliances
Mexico Washing Machine Market
Appliances
Refrigerator Door Seal Market
Appliances
Toaster Ovens Market
Appliances
Hairdryer Market
Appliances
Mobile Refrigerators Market
Appliances
Minibar Refrigerators Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
AI Washing Machine Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Household Vacuum Cleaners Market
Appliances
Bathroom Heaters Market