
 Saudi Arabia E-Commerce Market | 2026-2036
Saudi Arabia E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia E-Commerce Market Outlook
AI-powered personalization engines and last-mile logistics automation are reshaping how Saudi e-commerce platforms fulfill orders and retain customers. Amazon.sa leverages its global fulfillment infrastructure to anchor same-day delivery capabilities in Riyadh and Jeddah. Noon competes through vertical integration into owned warehousing and delivery fleets across the Kingdom. Sary specializes in B2B grocery procurement, dominating bulk supply channels for restaurants and small retailers in urban centers.
Saudi Arabia e-commerce encompasses digitally mediated transactions of goods and services conducted through web and mobile interfaces, relying on secure payment gateways, inventory management systems, and multi-modal logistics networks to connect buyers with sellers. Electronics and fashion command the largest transaction volumes, though margin pools increasingly shift toward beauty products where premium international brands command higher per-unit profitability. B2C channels sustain dominant transaction flow, while B2B platforms like Sary capture procurement digitization among Saudi SMEs seeking supply chain efficiency. E-wallet penetration accelerates fastest among payment methods, displacing cash on delivery as SAMA's regulatory framework builds consumer trust in digital financial infrastructure.
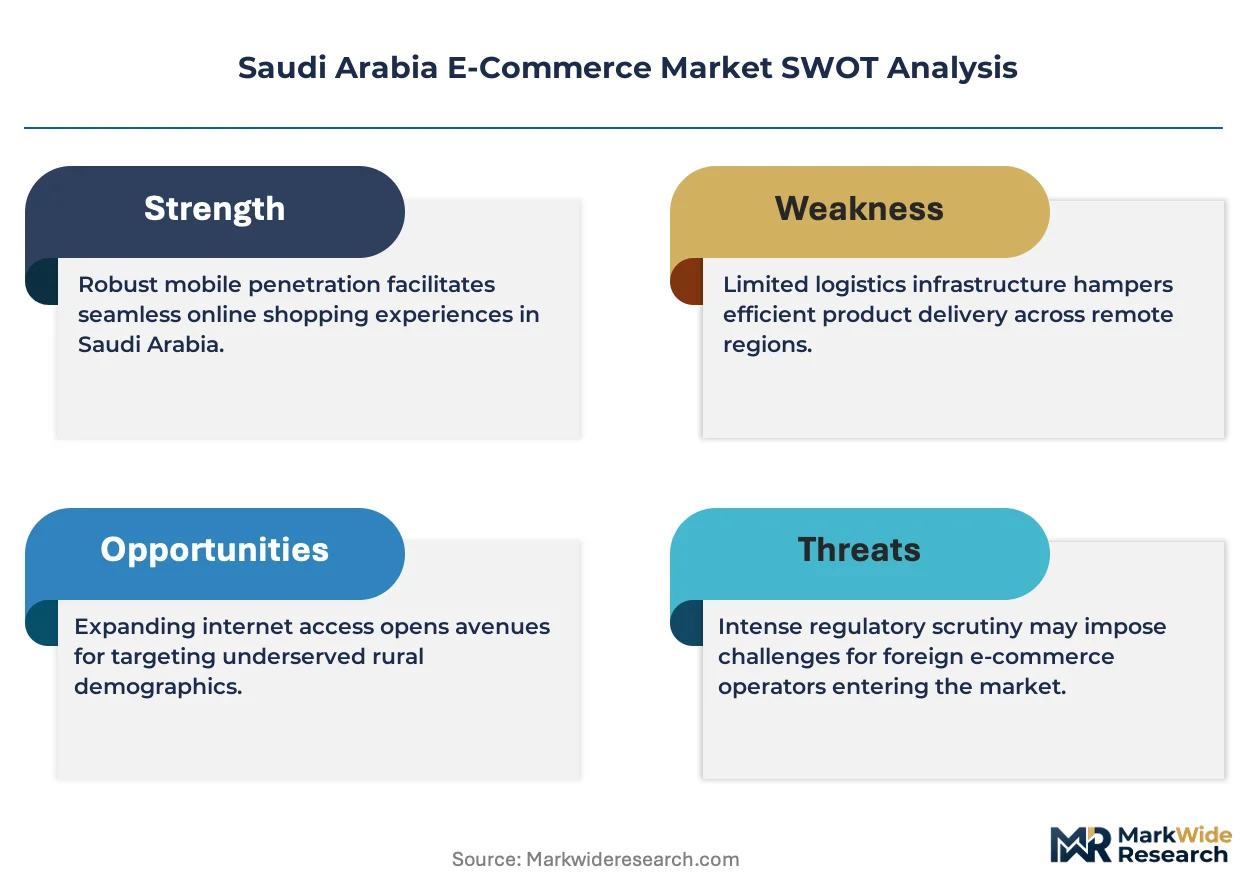
SAMA, the Saudi Central Bank, enforces payment service provider licensing and consumer protection standards that shape platform compliance costs and fintech partnership structures. The E-Commerce Law under the Ministry of Commerce mandates disclosure requirements, return policies, and data handling protocols that filter market access for cross-border sellers. GDPR-aligned data localization expectations from Saudi regulators further constrain cloud architecture choices for international platforms. Stakeholders must monitor how VAT enforcement and customs digitization under ZATCA reshape cross-border fulfillment economics and domestic platform pricing power.
Market Dynamics
SAMA's regulatory sandbox for fintech payment solutions is compressing cash-on-delivery dependency while accelerating digital wallet infrastructure deployment across urban logistics corridors.
Growth Catalysts
- Regulatory sandbox expansion:SAMA's controlled testing environment for payment service providers reduces compliance timelines for new entrants. Digital wallet operators gain accelerated market access under supervised experimentation protocols.
- Urban household digitization:Riyadh and Jeddah residents are consolidating weekly grocery purchases onto mobile-first platforms. Same-day delivery expectations now permeate food and grocery categories beyond electronics.
- Last-mile automation:Robotics-enabled fulfillment centers are reducing per-order handling costs. Automated sortation systems deployed in Saudi distribution hubs compress delivery windows for high-frequency consumables.
Market Restraints
- Cross-border VAT enforcement:ZATCA's customs digitization mandates create documentation friction for international sellers. Compliance costs filter market access for platforms without localized entity structures.
- Data localization requirements:GDPR-aligned expectations from Saudi regulators constrain cloud architecture choices. International platforms face infrastructure reconfiguration expenses to meet sovereign data storage protocols.
- Cash infrastructure persistence:Rural and semi-urban populations retain COD preference due to trust gaps in digital financial systems. Payment method fragmentation elevates operational complexity for nationwide fulfillment networks.
Strategic Opportunities
- B2B procurement digitization:Saudi SMEs in food service and retail verticals seek supply chain efficiency through centralized procurement platforms. Bulk ordering interfaces for restaurants and small retailers remain underpenetrated outside major urban centers.
- Beauty and personal care premiumization:International brand direct-to-consumer channels capture higher per-unit margins than electronics. Dedicated vertical platforms can exploit category-specific fulfillment requirements for temperature-sensitive cosmetics.
- Regulatory tailwinds from E-Commerce Law:Ministry of Commerce disclosure mandates and standardized return policies build consumer trust. Compliant domestic platforms gain competitive differentiation against informal cross-border sellers.
Industry Challenges
- Specialized logistics talent scarcity:Cold-chain operations and robotics maintenance require technical competencies in short supply. Recruitment competition with oil and gas sectors elevates compensation costs for fulfillment engineering roles.
- Legacy ERP integration complexity:Traditional retailers migrating online face system interoperability gaps between inventory management and digital storefronts. Middleware development timelines delay omnichannel deployment for established merchants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia E-Commerce Market |
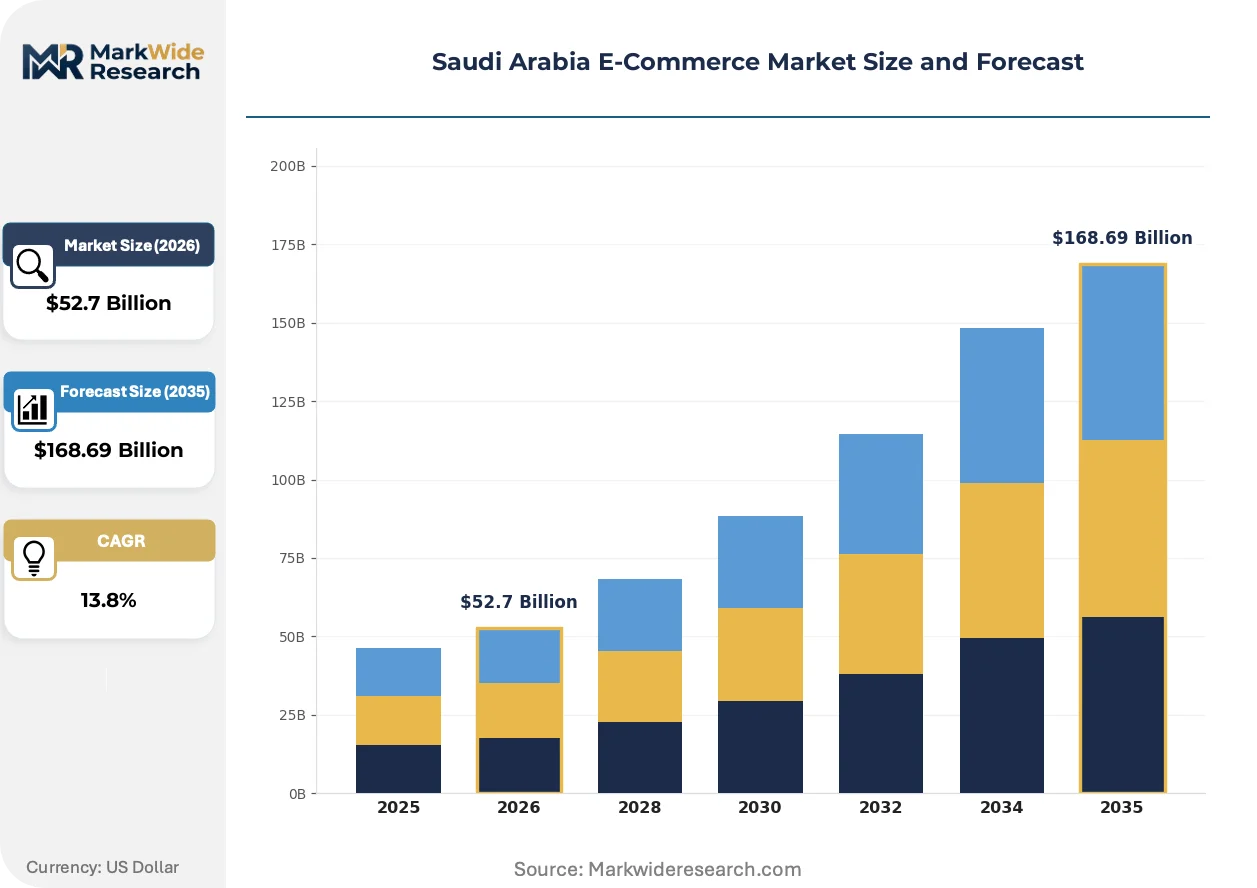
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $168.69 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Fashion, Home Goods, Beauty Products Customer Type: B2C, B2B, C2C, Marketplace Payment Method: Credit Card, Cash on Delivery, E-Wallets, Bank Transfer Delivery Model: Same-Day Delivery, Standard Shipping, Click & Collect, International Shipping |
| Companies Covered | Amazon.sa, Noon, Jarir Marketing, eXtra, Namshi, Haraj, Sary, Nana Direct, Ounass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia E-Commerce Market Strategic Shifts
Artificial intelligence and regulatory data frameworks are restructuring how Saudi e-commerce platforms anticipate demand, authenticate transactions, and configure fulfillment networks for geographic density.
Machine learning-powered demand forecasting is migrating from batch-based historical analysis to real-time pattern recognition incorporating social sentiment and weather data. Grocery platforms serving Riyadh households deploy these systems to pre-position inventory at neighborhood micro-fulfillment nodes. The shift from reactive replenishment to predictive stocking compresses last-mile delivery costs while reducing food waste from spoilage.
SAMA's consumer protection standards for payment service providers mandate transaction transparency and dispute resolution protocols. The regulation forces platform operators to restructure fintech partnership agreements around liability allocation. Domestic e-wallet providers gain compliance advantage over international payment rails lacking localized certification.
Subscription-based replenishment models are displacing episodic purchasing for household consumables. Urban Saudi households in Jeddah and Riyadh enroll in auto-delivery programs for diapers, pet food, and personal care staples. Platform operators capture predictable revenue streams while locking in customer lifetime value through reduced switching incentives.
Saudi Arabia E-Commerce Market Segmentation
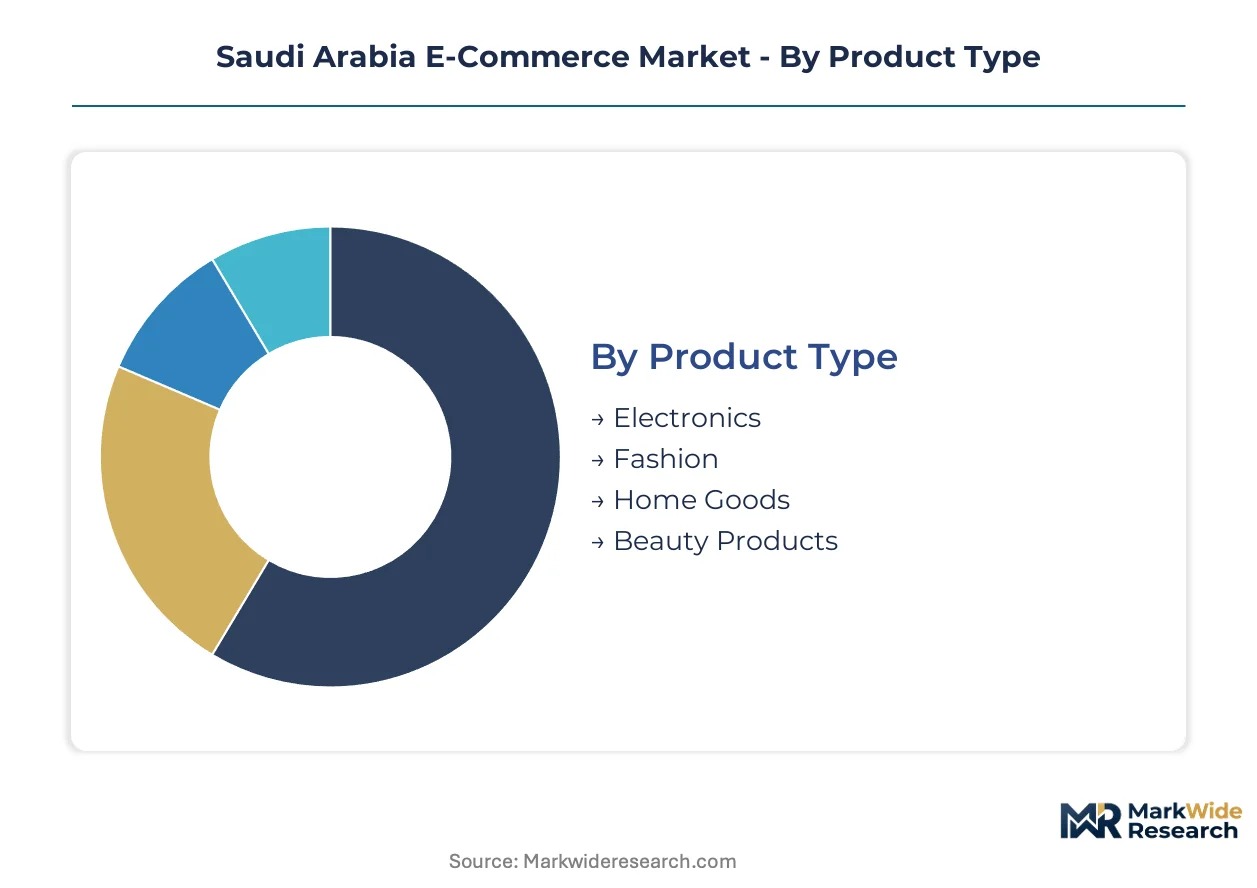
Saudi Arabia's e-commerce landscape fragments across product categories, customer relationships, payment infrastructures, and fulfillment architectures. Each segmentation dimension reveals distinct margin pools, operational complexity thresholds, and regulatory exposure profiles that shape platform strategy and investor prioritization.
Product Type:
Mature categories anchor transaction volume while emerging segments redefine profitability architecture.
- Electronics:Smartphones, laptops, and consumer appliances dominate order frequency with standardized SKUs enabling efficient warehousing. Riyadh and Jeddah households drive replacement cycles, though margin compression intensifies as Amazon.sa and Noon compete on price transparency.
- Fashion:Apparel and footwear generate high return rates due to sizing uncertainty, elevating reverse logistics costs. Urban Saudi consumers in metropolitan centers increasingly favor try-before-buy models and flexible exchange policies that strain fulfillment economics.
- Home Goods:Furniture and décor purchases concentrate around seasonal consumption peaks.
- Beauty Products:Premium international brands command superior per-unit profitability through temperature-controlled supply chains.
Electronics retains volume leadership; beauty products hold the steepest expansion curve.
Customer Type:
Cost tier stratification separates high-touch relationship models from self-service transactional platforms.
- B2C:Direct-to-consumer transactions sustain dominant revenue flow through mobile-first interfaces. Saudi households in urban corridors expect seamless checkout experiences and real-time order tracking that elevate platform technology investments.
- B2B:Procurement digitization among Saudi SMEs captures supply chain efficiency gains through bulk ordering interfaces. Restaurants and small retailers in Riyadh's commercial districts leverage Sary for inventory consolidation, reducing working capital requirements.
- C2C:Peer-to-peer selling platforms facilitate secondhand goods exchange with limited platform intervention.
- Marketplace:Third-party seller aggregation models scale inventory breadth without capital-intensive stocking.
B2C sustains revenue concentration; B2B exhibits the most rapid penetration acceleration among underserved SME segments.
Payment Method:
Application context determines payment infrastructure requirements, with mobile commerce driving digital wallet prioritization.
- E-Wallets:Digital payment platforms displace cash through SAMA's regulatory sandbox certification. STC Pay and Apple Pay penetration accelerates fastest among urban Saudi consumers seeking frictionless checkout.
- Credit Card:Traditional card networks retain preference for high-value transactions with established chargeback protections.
- Cash on Delivery:Rural and semi-urban populations retain COD preference due to trust gaps in digital financial infrastructure.
- Bank Transfer:Direct debit arrangements persist for B2B procurement and subscription renewals.
E-wallets are gaining share fastest; cash on delivery maintains residual volume in peripheral geographies.
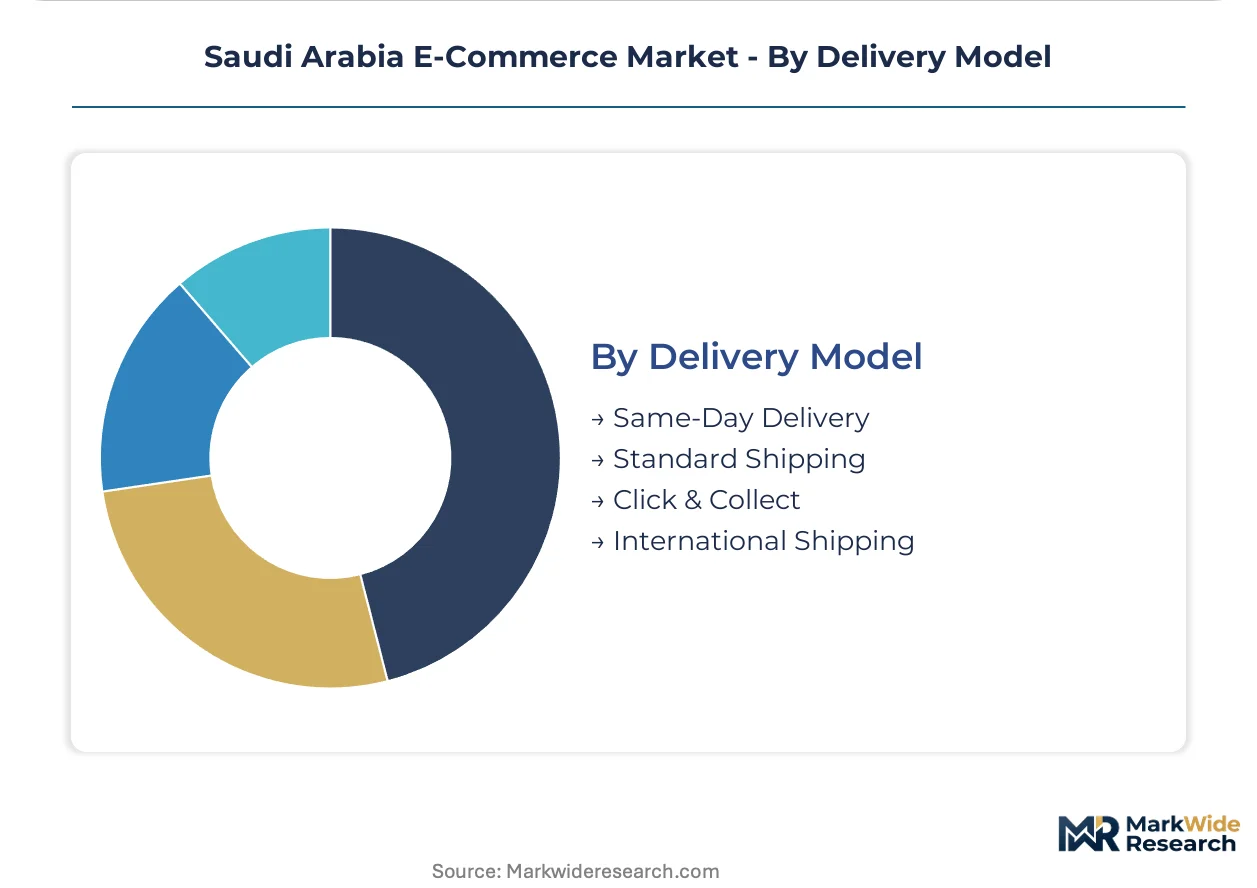
Delivery Model:
Geography dictates fulfillment network configuration, with urban density enabling speed-tier differentiation.
- Same-Day Delivery:Micro-fulfillment nodes in Riyadh and Jeddah compress delivery windows for high-frequency consumables. Grocery platforms deploy predictive stocking algorithms to pre-position inventory at neighborhood distribution points.
- Standard Shipping:Economical ground transportation serves price-sensitive consumers with flexible delivery windows.
- Click & Collect:Locker networks and retail partner pickup points reduce last-mile costs for working households.
- International Shipping:Cross-border fulfillment faces ZATCA customs digitization mandates that elevate documentation requirements.
Standard shipping retains volume leadership; same-day delivery commands the steepest capacity investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's e-commerce demand concentrates in digitally sophisticated urban households and procurement-driven SMEs seeking supply chain efficiency. Metropolitan corridors anchor transaction volume while peripheral regions exhibit lagging digital payment adoption.
Riyadh
Riyadh households drive electronics and fashion transactions through mobile-first platforms with same-day delivery expectations. SAMA's regulatory sandbox accelerates STC Pay and digital wallet penetration among capital residents. The King Abdullah Financial District clusters fintech payment providers and logistics headquarters serving nationwide fulfillment networks.
Western Region
Jeddah's port infrastructure facilitates cross-border inventory inflows for international marketplace sellers. ZATCA's customs digitization mandates reshape documentation workflows for Red Sea corridor imports. The city's commercial districts concentrate grocery platform micro-fulfillment nodes targeting urban household replenishment cycles.
Eastern Province
Dammam and Khobar industrial zones generate B2B procurement demand from petrochemical sector suppliers and construction material distributors. The Ministry of Commerce E-Commerce Law compliance requirements filter informal cross-border sellers from formal procurement channels. Jubail's manufacturing clusters drive bulk ordering interfaces for industrial consumables and MRO supplies.
NEOM Northwest
The giga-project zone incubates experimental last-mile logistics architectures and autonomous delivery pilots. Regulatory waivers under special economic zone frameworks permit testing of drone-enabled fulfillment and blockchain-based supply chain tracking. Trojena and The Line developments anchor smart city commerce infrastructure without legacy retail encumbrance.
Saudi Arabia E-Commerce Market Competitive Environment
Channel-controlling players compete with product-specialist players across fulfillment infrastructure, payment integration depth, and category-specific customer relationships. The market exhibits tiered concentration with horizontal marketplace operators anchoring volume leadership against vertical specialists capturing margin in beauty, grocery, and B2B procurement. Three archetypes dominate: global platform subsidiaries with captive logistics networks, domestic retail incumbents migrating online, and category-native digital specialists. Competitive moves center on warehouse automation investments and exclusive brand distribution agreements.
Among global platform subsidiaries, Amazon.sa and Noon exemplify fulfillment-network-driven market presence. Sary occupies a distinct position within B2B procurement digitization, anchoring supply chain efficiency plays for Saudi SME segments. These three represent the structural spectrum from horizontal scale to vertical specialization.
| Leading Market Players |
|---|
| Amazon.sa |
| Noon |
| Jarir Marketing |
| eXtra |
| Namshi |
| Haraj |
| Sary |
| Nana Direct |
| Ounass |
| Others |
Value Chain & Pricing Dynamics
Red Sea port congestion at Jeddah Islamic Port is compressing margins for cross-border inventory flows while concentrating pricing power among domestic platforms with localized warehousing. This logistics bottleneck feeds into a three-tier pricing structure across premium, standard, and economy fulfillment speeds, with urban households absorbing expedited delivery premiums.
Pricing Analysis
Cost-plus contracts with fuel indexation dominate B2B procurement arrangements between grocery platforms and restaurant suppliers. Price differentiation separates same-day delivery premiums from standard shipping tiers, with certification under SAMA's payment sandbox adding compliance-driven margin layers. Pricing pressure stems from Amazon.sa and Noon competing on electronics transparency, eroding markup headroom. Cash-on-delivery segments in peripheral regions exhibit highest price sensitivity; subscription-based replenishment households show lowest.
Supply Chain Analysis
Supplier-financing facilities extended by Sary to SME restaurant clients anchor working capital efficiency in B2B procurement channels. Inventory sourcing draws from China for electronics, Turkey for textiles, and UAE for cross-docked FMCG. Supply chain risk centers on single-source vulnerability for last-mile robotics maintenance talent. Distribution runs through micro-fulfillment nodes in Riyadh and Jeddah, with rural corridors dependent on third-party logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi e-commerce functions as a service-attach opportunity where fulfillment speed tiers and subscription replenishment layers expand faster than pure product margins. Recurring revenue from auto-delivery programs and premium delivery memberships now outpaces hardware transaction growth.
For Market Incumbents: Entrench control over cold-chain grocery logistics through captive warehousing investments in Dammam and Khobar. Counter Noon's fleet expansion by securing exclusive distribution agreements with international beauty brands seeking temperature-controlled Saudi entry. Vertical integration into robotics-enabled sortation systems defends margin position against labor cost inflation in fulfillment engineering roles.
For New Entrants and Emerging Players: Establish a beachhead in B2B procurement digitization for Eastern Province industrial consumables outside Sary's current restaurant focus. Target Jubail manufacturing clusters with MRO supply platforms offering consolidated bulk ordering interfaces. Deploy direct sales teams to petrochemical sector procurement officers as the go-to-market angle.
For Investors and Strategic Acquirers: Category-native digital specialists with captive last-mile fleets in secondary cities represent the most defensible acquisition profile. Long-term viability hinges on regulatory compliance infrastructure under SAMA and Ministry of Commerce frameworks. Watch NEOM regulatory waivers for autonomous delivery pilots as the signal indicating experimental logistics architecture maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Expansion | Neighborhood inventory pre-positioning undercuts same-day delivery costs in Riyadh and Jeddah corridors. |
| SAMA Sandbox Certification Investment | Digital wallet integration deepens customer retention through frictionless checkout experiences. |
| Exclusive Brand Distribution Agreement | Temperature-controlled supply chain capabilities unlock premium beauty category margins. |
| Subscription Replenishment Program Launch | Predictable revenue streams from household consumables reduce customer acquisition cost volatility. |
| Robotics-Enabled Sortation Deployment | Automated fulfillment centers compress per-order handling costs for high-frequency grocery transactions. |
Study Parameters
A spread of perspectives from e-commerce platform executives, logistics operations directors, fintech product managers, and grocery category buyers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from SAMA regulatory filings, ZATCA customs digitization mandates, Ministry of Commerce disclosure requirements, and hyperscaler capex disclosures. Bottom-up transaction volume estimates and top-down macroeconomic scaling were triangulated to anchor projections.
Demand-supply balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product category, customer relationship type, payment method, and delivery speed tier, with regional urban density as an additional industry-specific dimension. CAGRs were derived from trend extrapolation anchored in historical growth patterns and structural shift assumptions. Forecast inputs incorporated SAMA regulatory sandbox expansion timelines and ZATCA enforcement intensity for cross-border VAT compliance.
Stress conditions across digital wallet penetration rates, fuel cost volatility, and customs documentation friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pace and urban household digitization trajectories. Macroeconomic contraction, accelerated data localization mandates, or technological disruption in autonomous delivery would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Kuwait E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
E-Commerce Software Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
Taiwan E-Commerce Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market