
 Middle East and Africa Insulin Infusion Pumps Market | 2026-2036
Middle East and Africa Insulin Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Insulin Infusion Pumps Market Foresight
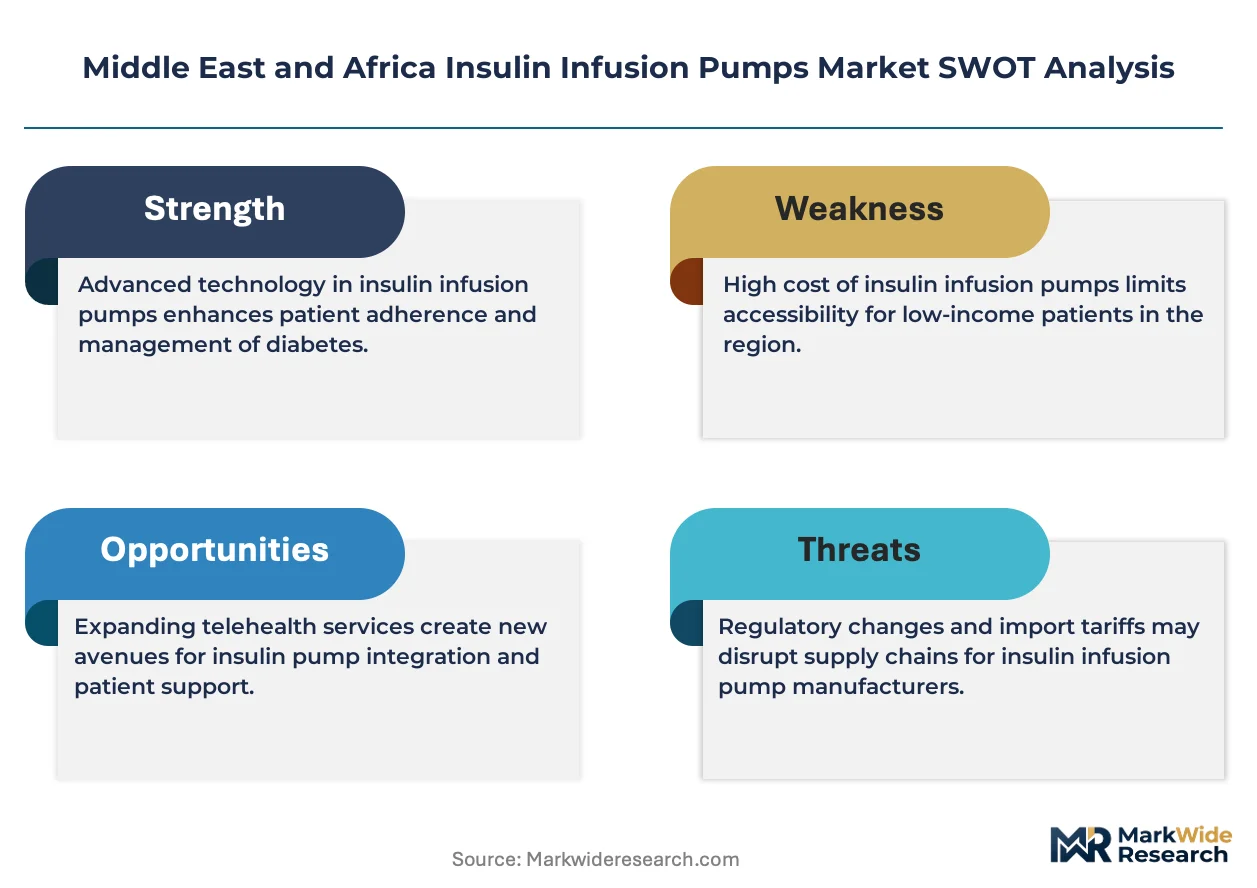
CE marking under the EU Medical Device Regulation is reorganizing competitive access for manufacturers serving Middle East and Africa markets that reference European standards. Medtronic PLC leverages its established regulatory dossiers to sustain market presence across Gulf Cooperation Council states. Becton Dickinson anchors distribution through regional medical device distributors with cold-chain capabilities. Insulet Corporation differentiates via patch pump technology that reduces training burdens for homecare users.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous catheter at variable basal rates and patient-initiated bolus doses, typically with delivery precision of 0.025 to 0.1 units per increment. Its primary purpose is to simulate physiological pancreatic insulin secretion for glycemic control in Type 1 and insulin-dependent Type 2 diabetes patients. Wearable pumps dominate current volume due to established reimbursement pathways, while sensor-augmented pumps capture expanding margin pools as closed-loop algorithms mature. Bluetooth-enabled pumps are gaining fastest traction among homecare users seeking smartphone integration for remote monitoring by caregivers.
South Africa's Health Products Regulatory Authority, Saudi Arabia's SFDA, and the UAE's Ministry of Health and Prevention enforce medical device registration, post-market surveillance, and quality management system audits that determine which manufacturers gain market access. These frameworks elevate compliance costs but also filter out substandard devices, concentrating procurement among ISO 13485-certified suppliers with regional clinical data packages. Stakeholders must monitor harmonization between Gulf Standards Organization technical regulations and national competent authority requirements to anticipate registration pathway changes.
Market Dynamics
Hospital-based diabetes management programs across tertiary care centers are accelerating pump adoption, while Saudi Arabia's SFDA and South Africa's Health Products Regulatory Authority impose stricter medical device registration requirements that filter supplier participation.
Growth Catalysts
- Government-funded diabetes initiatives:Saudi Arabia, the UAE, and South Africa channel public health budgets into device procurement for Type 1 and insulin-dependent Type 2 patients. These programs reduce out-of-pocket burdens and expand addressable populations.
- Rising private insurance coverage:Gulf Cooperation Council insurers increasingly reimburse wearable pumps and sensor-augmented systems. This reimbursement pathway removes price barriers for middle-income households seeking continuous glucose management.
- Bluetooth-enabled smartphone integration:Homecare users and caregivers demand remote monitoring capabilities. Bluetooth pumps enable real-time data sharing with clinicians, reducing emergency department visits and supporting decentralized care models.
Market Restraints
- Cold-chain distribution requirements:Insulin stability mandates temperature-controlled logistics from manufacturer to patient. Limited regional cold-chain infrastructure elevates spoilage risk and distribution costs for inland territories.
- ISO 13485 certification barriers:South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA require quality management system audits that smaller manufacturers cannot fund. This concentrates supply among established multinationals.
- Multiple daily injections as substitute:Pen-based insulin delivery remains prevalent where pump reimbursement is incomplete. Cost-conscious patients and underfunded public health systems default to cheaper injection protocols.
Strategic Opportunities
- Underpenetrated North African markets:Egypt and Morocco exhibit low pump penetration relative to diabetes prevalence. Government health modernization programs present first-mover entry points for certified suppliers.
- Closed-loop algorithm convergence:Integration of continuous glucose monitors with automated insulin delivery is maturing. Manufacturers combining these technologies can capture premium positioning in private hospital channels.
- Direct-to-patient subscription models:Patch pump specialists are piloting monthly fee structures bypassing traditional distributor markups. This channel innovation reduces patient acquisition costs and improves retention metrics.
Industry Challenges
- Endocrinologist training capacity:Pump initiation and troubleshooting require specialized clinical expertise. Shortages of diabetes specialists in secondary cities delay patient onboarding and increase device abandonment rates.
- Post-market surveillance compliance:Saudi Arabia's SFDA mandates adverse event reporting and periodic safety updates. Smaller market entrants struggle to maintain regulatory dossiers across multiple national competent authorities simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Insulin Infusion Pumps Market |
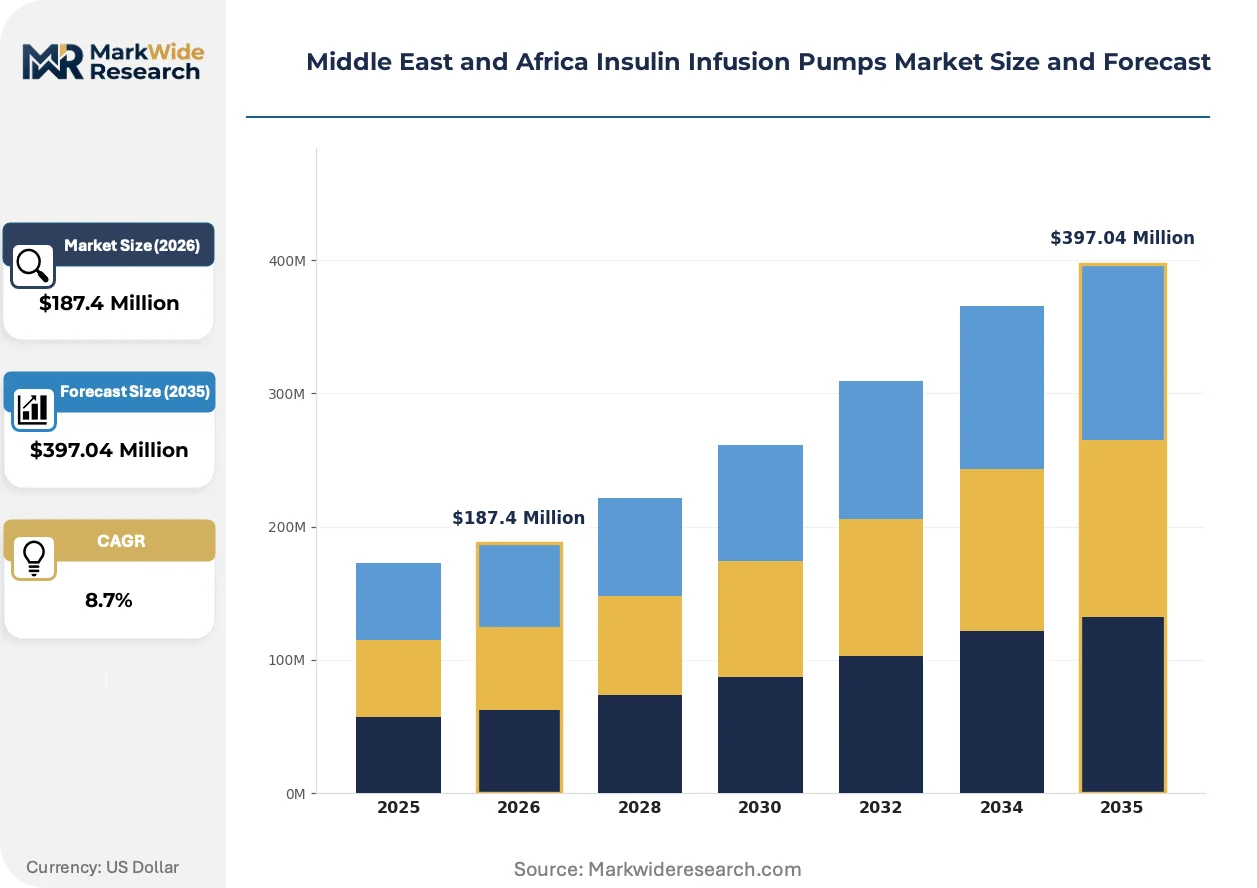
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Pumps, Implantable Pumps, Disposable Pumps, Continuous Glucose Monitors Technology: Smart Pumps, Manual Pumps, Sensor-Augmented Pumps, Bluetooth-Enabled Pumps End User: Hospitals, Homecare, Diabetes Clinics, Long-Term Care Facilities Distribution Channel: Online Sales, Retail Pharmacies, Healthcare Providers, Medical Devices Distributors |
| Companies Covered | Becton Dickinson, Tandem Diabetes Care, Medtronic PLC, Terumo Corporation, EOFLOW CO., LTD., Insulet Corporation, Roche Diabetes Care, F. Hoffmann-La Roche Ltd., Ypsomed, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Insulin Infusion Pumps Market Shifts & Advancements
Sensor-augmented pump systems are reshaping competitive positioning across Middle East and Africa markets, with algorithm-driven closed-loop capabilities separating premium offerings from basic wearable devices.
Patch pump form factors are fragmenting the traditional tethered pump segment. These disposable, tubeless devices attach directly to the body and eliminate infusion set management. Homecare users in Saudi Arabia and the UAE are adopting patch pumps at accelerating rates due to reduced training requirements. This technology is fragmenting market share concentration among legacy electromechanical suppliers by enabling new entrants with simpler manufacturing footprints.
Gulf Standards Organization technical regulations are harmonizing with national competent authority requirements across Saudi Arabia, the UAE, and Kuwait. This alignment reduces redundant conformity assessment procedures for manufacturers holding CE marking under the EU Medical Device Regulation. Multinational suppliers with established European regulatory dossiers are consolidating procurement relationships with Gulf Cooperation Council hospital groups, while regional distributors invest in local technical file preparation capabilities.
After-sales service unbundling is altering distributor economics across South Africa and Nigeria. Hospital procurement committees increasingly separate device purchase from training and maintenance contracts, enabling third-party clinical educators to compete on service quality. This disintermediation pressures traditional full-service distributors to demonstrate measurable patient outcome improvements rather than relying on exclusive territorial agreements.
Middle East and Africa Insulin Infusion Pumps Market Segmentation
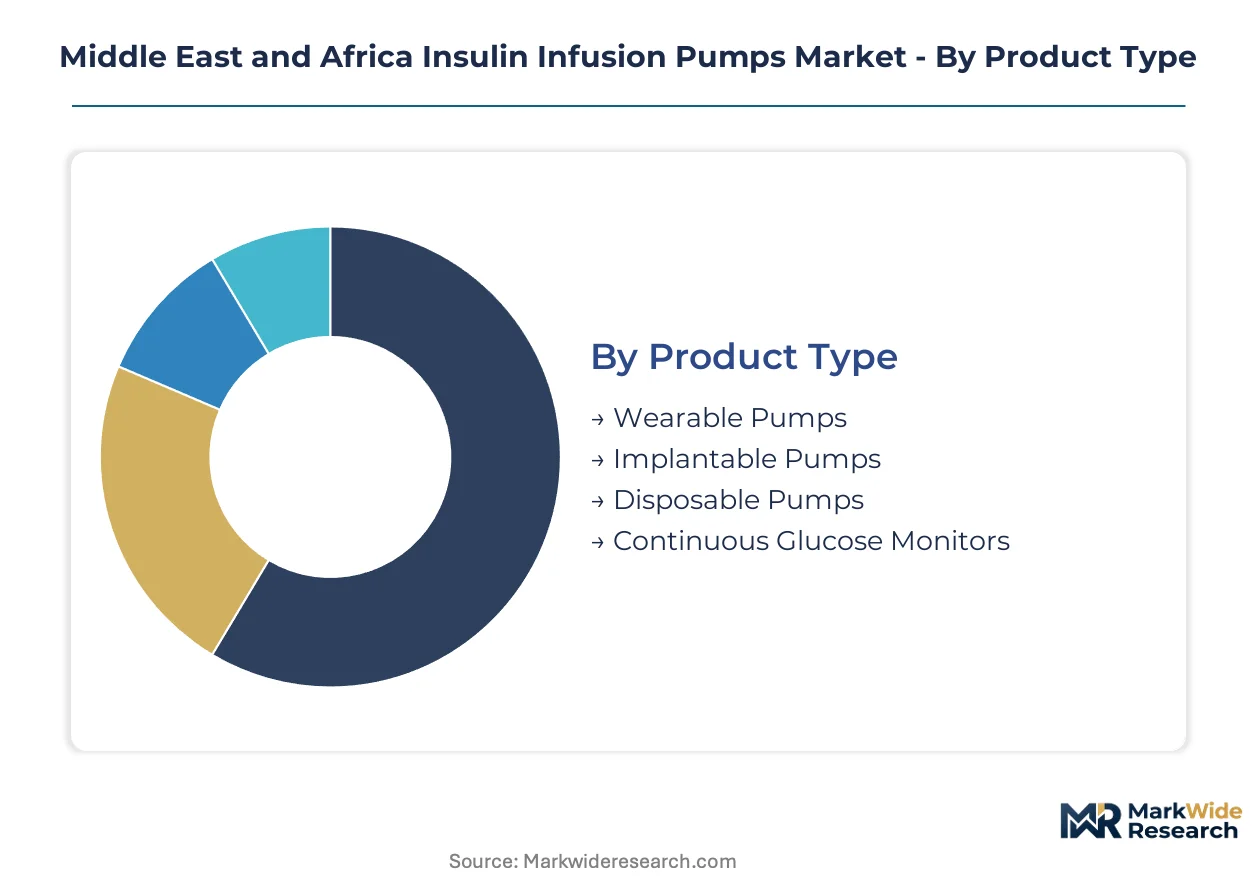
Insulin infusion pump segmentation across Middle East and Africa markets reveals distinct channel economics and reimbursement pathways. Product form factors, connectivity features, and care settings determine procurement hierarchies and margin structures for manufacturers and distributors.
Product Type:
Wearable pumps flow through hospital procurement committees and medical device distributors with cold-chain capabilities, while patch-style disposable pumps increasingly bypass traditional channels via direct-to-patient subscription models.
- Wearable Pumps:Tethered electromechanical devices with external infusion sets and programmable basal-bolus delivery. Demand concentrates in Saudi Arabian and Emirati tertiary care centers where government-funded diabetes initiatives cover device costs and consumables.
- Disposable Pumps:Tubeless patch-form devices with integrated insulin reservoirs and adhesive application. South African private insurance channels and UAE homecare segments are expanding fastest as training requirements drop and patient self-management improves.
- Implantable Pumps:Surgically placed intraperitoneal devices for highly insulin-resistant patients. Limited to specialized endocrinology centers in Cairo and Johannesburg with bariatric surgery capabilities.
- Continuous Glucose Monitors:Interstitial glucose sensors paired with pump systems or standalone use. Retail pharmacy channels in Gulf Cooperation Council states drive volume as over-the-counter availability expands.
Wearable pumps dominate installed base. Disposable pumps are where expansion concentrates.
Technology:
Connectivity tier determines pricing architecture and reimbursement eligibility across Middle East and Africa markets, with Bluetooth integration commanding premium positioning in private insurance channels.
- Smart Pumps:Microprocessor-controlled devices with dose calculators, meal databases, and predictive low-glucose suspend algorithms. Saudi Arabian SFDA-registered units capture hospital procurement preference through integrated clinical decision support.
- Bluetooth-Enabled Pumps:Wireless connectivity enabling smartphone app integration and remote caregiver monitoring. UAE homecare demand and South African private insurance reimbursement are climbing fastest as decentralized diabetes management expands.
- Sensor-Augmented Pumps:Systems linking continuous glucose monitor data to pump algorithms for semi-automated delivery adjustment. Premium positioning in Gulf private hospital channels where closed-loop capabilities justify higher reimbursement rates.
- Manual Pumps:Basic electromechanical devices without wireless connectivity or algorithmic support. Public health system procurement in Egypt and Morocco defaults to this tier where budget constraints limit technology adoption.
Manual pumps retain volume in public procurement. Bluetooth-enabled systems are expanding most quickly in private channels.
End User:
Care setting determines device specification requirements, training intensity, and after-sales service bundling across Middle East and Africa distribution networks.
- Hospitals:Acute care and tertiary diabetes management programs requiring multi-patient monitoring capabilities and EMR integration. Saudi Arabian Ministry of Health facilities and South African academic medical centers anchor procurement volume.
- Homecare:Individual patients managing diabetes outside clinical settings with caregiver remote oversight. UAE and Saudi Arabian middle-income households with private insurance coverage are driving sensor-augmented and Bluetooth-enabled adoption.
- Diabetes Clinics:Specialized outpatient facilities with endocrinologist-led pump initiation programs. Johannesburg and Cairo clinic networks concentrate training capacity and device dispensing.
- Long-Term Care Facilities:Nursing homes and assisted living centers managing elderly insulin-dependent patients. Limited penetration due to staffing constraints and preference for simpler injection protocols in underfunded facilities.
Hospitals anchor procurement volume. Homecare represents the steepest expansion trajectory as reimbursement broadens.
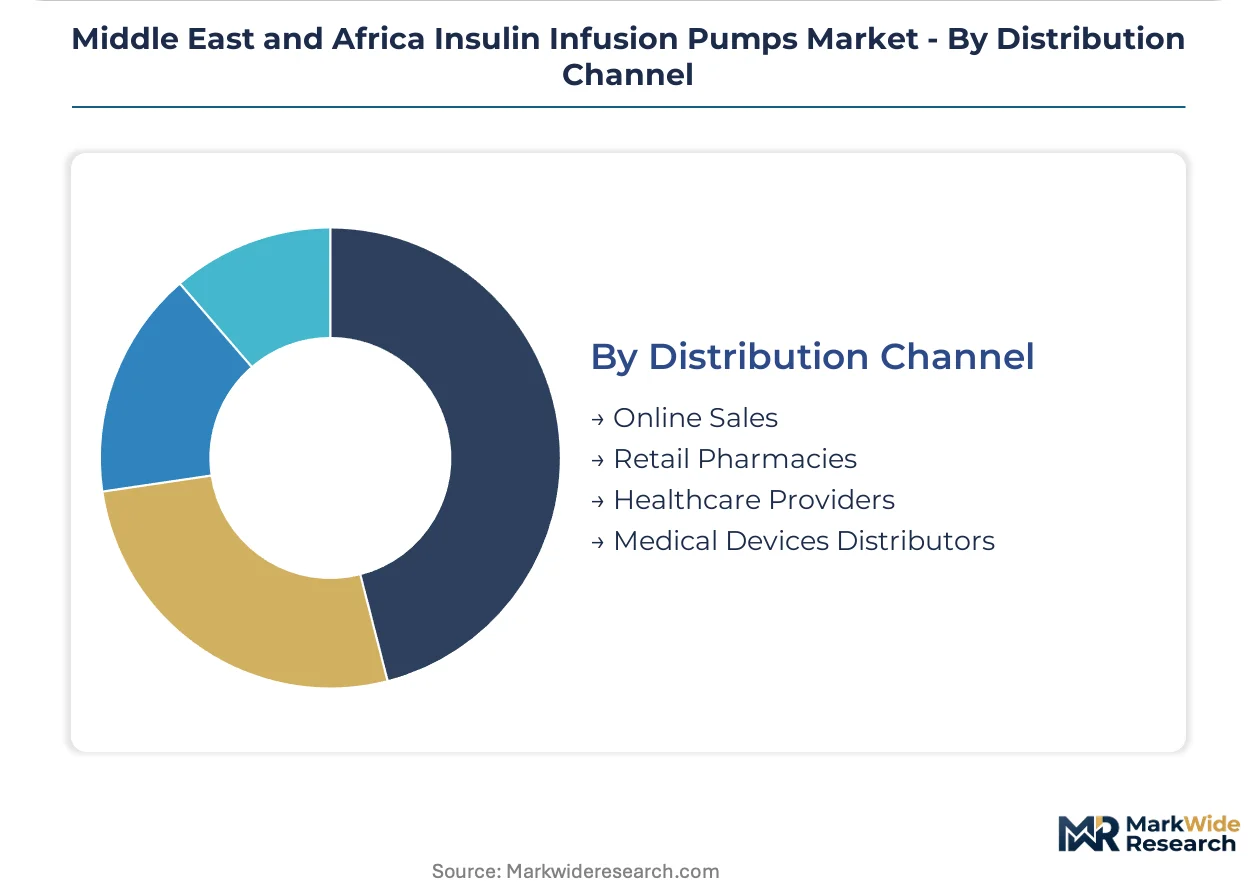
Distribution Channel:
Channel structure shapes price realization and patient access speed, with direct digital routes fragmenting traditional distributor economics.
- Medical Devices Distributors:Full-service intermediaries handling importation, cold-chain logistics, regulatory filing, and clinical training. Gulf Cooperation Council hospital procurement and South African private hospital networks depend on ISO 13485-certified distributors with SFDA and Health Products Regulatory Authority dossier capabilities.
- Healthcare Providers:Direct manufacturer relationships with hospital groups and clinic networks bypassing distributor markups. Saudi Arabian Ministry of Health tender processes and large UAE hospital chains leverage volume for preferential pricing.
- Retail Pharmacies:Community-based dispensing of consumables and select pump models. Moroccan and Egyptian urban pharmacy networks expand access where distributor infrastructure remains underdeveloped.
- Online Sales:Direct-to-patient digital channels for patch pumps and consumable refills. UAE and Saudi Arabian e-commerce penetration enables subscription models that reduce patient acquisition costs.
Medical devices distributors retain procurement dominance. Online sales are gaining share fastest among tech-enabled homecare segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded diabetes programs across Gulf Cooperation Council states and South Africa are channeling public health budgets into device procurement for insulin-dependent patients, reducing out-of-pocket burdens and expanding addressable populations for pump manufacturers.
Saudi Arabia
The Saudi Food and Drug Authority (SFDA) mandates ISO 13485 quality management system audits for medical device registration, filtering supplier participation toward established multinationals with dossier capabilities. Government-funded diabetes initiatives under the Ministry of Health cover wearable pumps and consumables for Type 1 patients. Riyadh and Jeddah tertiary care centers anchor procurement volume through hospital-based diabetes management programs.
United Arab Emirates
Private insurance reimbursement for sensor-augmented and Bluetooth-enabled pumps is climbing fastest among Gulf Cooperation Council states, removing price barriers for middle-income households. The Ministry of Health and Prevention enforces medical device registration harmonized with Gulf Standards Organization technical regulations. Dubai's private hospital networks and Abu Dhabi's academic medical centers concentrate training capacity and device dispensing for homecare segments.
South Africa
The Health Products Regulatory Authority requires post-market surveillance and periodic safety updates that smaller market entrants struggle to maintain across multiple national competent authorities simultaneously. Rising private insurance coverage supports device procurement in urban centers. Johannesburg and Cape Town clinic networks concentrate endocrinologist-led pump initiation programs, though specialist shortages in secondary cities delay patient onboarding.
Egypt
Public health system procurement defaults to manual pump tiers where budget constraints limit technology adoption, despite low pump penetration relative to diabetes prevalence. Government health modernization programs present first-mover entry points for certified suppliers with regional clinical data packages. Cairo's specialized endocrinology centers and Alexandria's academic hospitals represent the primary institutional channels for advanced device access.
Nigeria
Limited cold-chain infrastructure elevates spoilage risk and distribution costs for inland territories, constraining pump adoption outside Lagos and Abuja corridors. After-sales service unbundling is altering distributor economics as hospital procurement committees separate device purchase from training contracts. Lagos private hospital networks and Abuja's federal medical centers anchor the limited premium-tier device penetration in West Africa's largest market.
Middle East and Africa Insulin Infusion Pumps Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier capabilities and cold-chain distribution infrastructure. The supplier base concentrates among ISO 13485-certified multinationals with established SFDA and Health Products Regulatory Authority registrations, filtering out smaller manufacturers unable to fund quality management system audits. Three archetypes dominate: legacy electromechanical suppliers with tethered pump portfolios, patch pump specialists with disposable tubeless devices, and sensor-integrated system providers with closed-loop algorithms. Competitive moves center on strategic partnerships with regional medical device distributors and portfolio diversification into Bluetooth-enabled smartphone integration.
Within the legacy electromechanical tier, Medtronic PLC and Becton Dickinson occupy positions anchored by established regulatory dossiers and Gulf Cooperation Council hospital procurement relationships. Insulet Corporation exemplifies the patch pump specialist archetype, with its tubeless disposable form factor reducing training burdens for homecare users in Saudi Arabia and the UAE. These three companies represent the dominant competitive anchors across Middle East and Africa insulin infusion pump markets, differentiated by form factor strategy and channel access rather than geographic origin.
| Leading Market Players |
|---|
| Becton Dickinson |
| Tandem Diabetes Care |
| Medtronic PLC |
| Terumo Corporation |
| EOFLOW CO., LTD. |
| Insulet Corporation |
| Roche Diabetes Care |
| F. Hoffmann-La Roche Ltd. |
| Ypsomed |
| Others |
Supply & Pricing Matrix
CE marking under the EU Medical Device Regulation gates both supply qualification and price differentiation simultaneously, filtering Middle East and Africa market access toward ISO 13485-certified manufacturers while stratifying procurement tiers across Gulf Cooperation Council hospital systems and South African private insurers.
Pricing Analysis
Certification level creates the primary spread across procurement tiers, with CE-marked and SFDA-registered devices commanding premium positioning in Saudi Arabian tertiary care centers while uncertified alternatives serve price-constrained Egyptian public health systems. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and cold-chain logistics coverage. Pricing pressure stems from distributor margin compression as hospital procurement committees unbundle training contracts from device purchases. Public health buyers in Morocco and Nigeria exhibit highest price sensitivity; private insurers in the UAE demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling preferences dominate insulin reservoir and consumable procurement, with Gulf Cooperation Council distributors maintaining 60-90 day buffers against temperature excursion risks while just-in-time approaches prevail for pump hardware. Manufacturing concentrates in Ireland, Switzerland, and the United States for electromechanical assemblies; Malaysia and Mexico supply disposable infusion sets. Supply chain risk centers on single-source vulnerability for precision microfluidic components. Distribution runs through ISO 13485-certified medical device distributors with regional cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating across Middle East and Africa insulin infusion pump markets as Gulf Cooperation Council hospital procurement committees and South African medical scheme administrators centralize tender processes, squeezing distributor margins and favoring multinationals with dossier depth.
For Market Incumbents: Consolidate regulatory dossier advantages by deepening Gulf Standards Organization technical file capabilities and securing multi-year Ministry of Health tender locks in Saudi Arabia. Patch pump specialists and Bluetooth-enabled entrants threaten premium positioning; vertical integration into consumable manufacturing protects margin pools. For New Entrants and Emerging Players: Differentiate on disposable form factors and direct-to-patient subscription economics to bypass entrenched distributor relationships. North African markets—particularly Egypt and Morocco—offer most penetrable white space given low pump penetration and health modernization program funding. Target diabetes clinic networks in secondary South African cities with simplified training protocols. For Investors and Strategic Acquirers: Carve-out targets emerge from regional medical device distributors with SFDA and Health Products Regulatory Authority registrations but limited manufacturer exclusivities. Long-term viability hinges on closed-loop algorithm maturation and sensor integration capabilities. Watch for reimbursement expansion signals in Nigerian private insurance channels as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR certification accelerates Gulf Cooperation Council market access through harmonized technical standards. |
| Hospital System Partnership | Direct relationships with Saudi Arabian Ministry of Health facilities secure volume commitments and tender preferences. |
| Software Companion Development | Bluetooth-enabled smartphone apps enable remote monitoring and differentiate homecare offerings in UAE markets. |
| Reimbursement Strategy | Private insurance formulary placement in South African medical schemes removes patient price barriers. |
| Backward Integration | In-house insulin reservoir manufacturing reduces cold-chain spoilage exposure and distributor dependency. |
Research Methodology
The analysis maps wearable pumps, patch pumps, sensor-augmented systems, and continuous glucose monitors, each validated through endocrinologists, hospital procurement managers, biomedical engineers, and medical device distributors. Primary interviews with industry stakeholders combined with secondary validation from SFDA registration databases, Health Products Regulatory Authority filings, Gulf Standards Organization technical regulations, and hospital procurement records. Bottom-up and top-down triangulation anchored volume and value estimates.
Consistency checks validated outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product form factor, connectivity tier, care setting, and distribution channel. CAGRs derived from installed base growth, replacement cycles, and technology conversion rates. Forecast inputs incorporated reimbursement expansion trajectories and regulatory harmonization timelines.
The analysis sits within stated boundaries; outcomes outside sustained government diabetes program funding or cold-chain infrastructure investment would require recalibration. Forecasts reflect documented assumptions regarding SFDA and Health Products Regulatory Authority registration pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Indonesia Diabetes Care Devices Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market