

Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market Insights
Germany's automotive testing corridor from Munich to Stuttgart is narrowing the gap between prototype validation and mass-production readiness for interoperability equipment. Keysight Technologies leverages its RF and power-electronics heritage to dominate high-frequency protocol analysis for CCS and CHAdeMO interfaces. Siemens anchors its position through digital-twin integration, coupling hardware-in-the-loop test benches with cloud-based compliance reporting. Robert Bosch competes by extending its automotive sensor expertise into charging-communication stress-testing for Tier-1 supplier programs.
Onboard charger and DC fast-charging interoperability test equipment comprises specialized instrumentation that validates power conversion, communication protocol handshake, and grid-integration performance across multiple charging standards including CCS, CHAdeMO, and GB/T, typically operating at voltage ranges from 200V to 1000V DC with power levels exceeding 350kW. This equipment ensures that electric vehicles and charging infrastructure achieve functional compatibility before regulatory type approval and commercial deployment. Test simulators and communication analyzers capture the strongest margin pools as protocol complexity outpaces hardware commoditization, while application demand tilts toward electric buses and fleet operations where downtime costs amplify the value of pre-certification testing. Technology segmentation reveals CCS as the dominant protocol architecture in Western markets, with GB/T retaining captive demand in China and AV charging systems emerging as a specialized niche for autonomous fleet depots.
FDA oversight of electromagnetic compatibility in medical-adjacent vehicle applications, EPA tailpipe-equivalent standards for zero-emission vehicle mandates, and FCC Part 15 rules governing power-line communication frequencies collectively shape product design and market access requirements for test equipment sold into North American certification workflows. In Europe, the EU AI Act's impending conformity-assessment frameworks for autonomous charging interfaces will add new validation layers to existing CE marking and MDR-aligned quality systems. Stakeholders must monitor how protocol fragmentation between CCS2 and emerging megawatt-charging standards forces test-equipment architectures toward modular, software-upgradable platforms rather than fixed-configuration hardware.
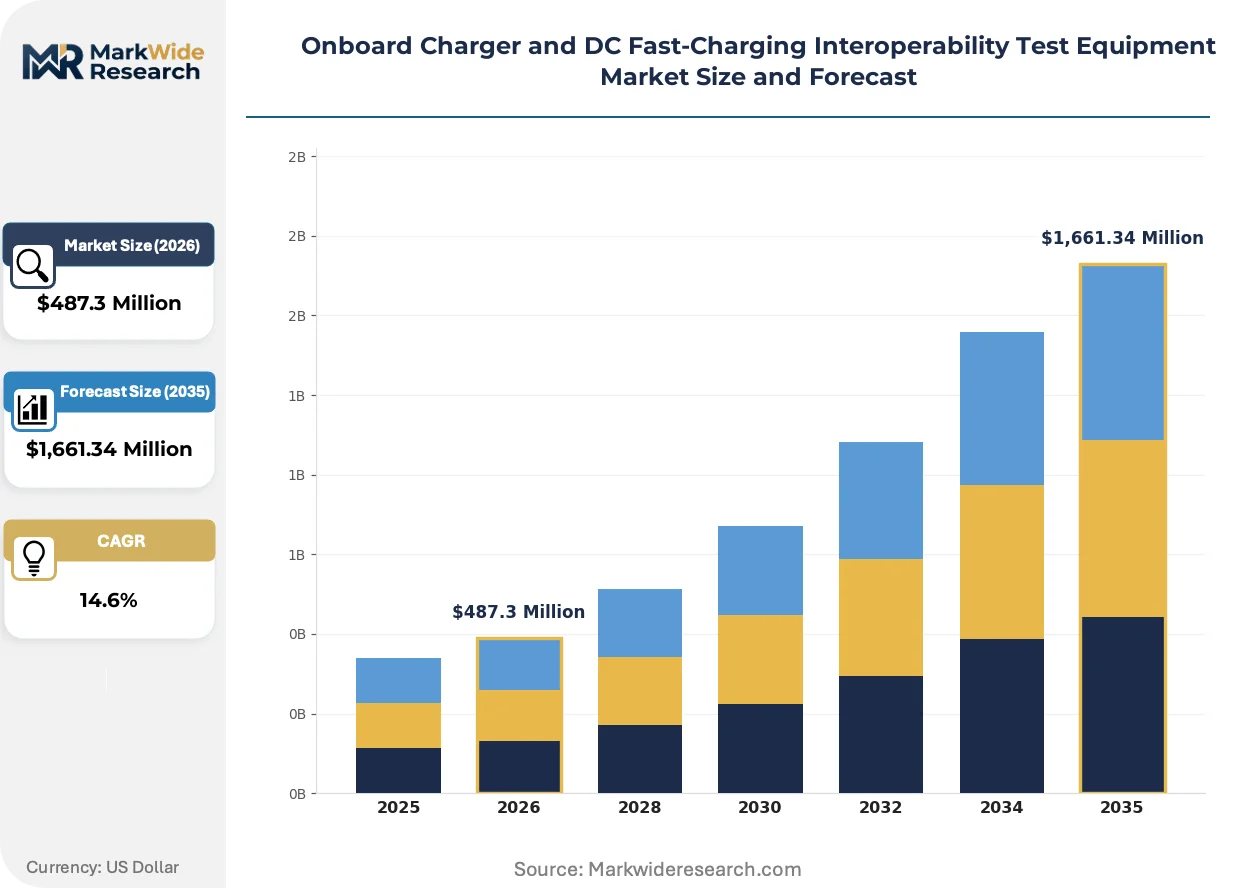
Market Dynamics
Protocol fragmentation between CCS2 and emerging megawatt-charging standards is forcing test-equipment architectures toward modular, software-upgradable platforms rather than fixed-configuration hardware, compressing replacement cycles and elevating R&D spend across the supplier base.
Growth Catalysts
- ISO 15118-20 mandates:The KBA in Germany now requires bidirectional power-flow validation for type approval, expanding test-equipment scope from unidirectional handshake verification to full V2G protocol stress-testing.
- Electric bus fleet procurement:Municipal transit authorities in California and New York specify pre-certified charging compatibility, creating captive demand for high-throughput test benches that validate multiple vehicle-charger pairings simultaneously.
- Silicon carbide power modules:Widespread adoption in 800V onboard chargers is elevating switching-frequency test requirements, pulling RF-domain instrumentation expertise into what was historically a DC-power electronics discipline.
Market Restraints
- High-voltage component supply concentration:Gallium nitride semiconductors for 1000V test simulators source primarily from Japanese and Chinese foundries, exposing equipment manufacturers to export-control volatility and foundry allocation constraints.
- Certification timeline compression:The EU AI Act's impending conformity-assessment frameworks for autonomous charging interfaces will add validation layers atop existing CE marking and MDR-aligned quality systems, extending product-to-market intervals.
- Fixed-configuration hardware obsolescence:Rapid protocol evolution renders capital-intensive single-standard test benches economically unviable before depreciation cycles complete, straining mid-tier equipment lessors.
Strategic Opportunities
- Autonomous fleet depot charging:AV charging systems for commercial trucking and robotaxi operations require specialized interoperability validation for unmanned connector engagement and payment-automation protocols, creating a premium test-equipment niche.
- India PLI scheme alignment:Domestic EV manufacturing incentives are attracting component suppliers to Gujarat and Tamil Nadu, generating greenfield demand for localized test-equipment deployment and technical training infrastructure.
- Digital-twin integration:Cloud-based compliance reporting coupled with hardware-in-the-loop simulation is enabling remote certification workflows, opening subscription-service revenue models for test-equipment vendors.
Industry Challenges
- Protocol-engineering talent scarcity:Deep expertise in CCS powerline communication and CHAdeMO CAN bus arbitration resides with a narrow cohort of specialists concentrated in Stuttgart, Munich, and Tokyo engineering clusters.
- Multi-standard capex burden:Simultaneous support for CCS, CHAdeMO, GB/T, and emerging NACS protocols requires parallel test-bench investments that strain R&D budgets at Tier-2 equipment suppliers.
- Cross-border certification reciprocity gaps:Type-approval data packages accepted by the KBA lack mutual recognition with China's MIIT homologation requirements, forcing redundant test campaigns for dual-market vehicle programs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market Trends and Innovations
Test-equipment architectures are migrating from hardware-centric fixed configurations toward software-defined platforms that accommodate protocol evolution through firmware updates rather than capital replacement.
Modular power-electronics architectures are migrating from proprietary analog control systems to open-source digital twin frameworks. Tier-1 automotive suppliers in Germany and South Korea now specify hardware-in-the-loop compatibility as a procurement prerequisite, collapsing the distinction between prototype validation and production-line testing. This convergence is compressing equipment refresh cycles from seven years to three while elevating software licensing to roughly one-third of total contract value.
The EU AI Act's risk-based classification system for autonomous charging interfaces will mandate algorithmic transparency documentation by 2026. Equipment manufacturers must now embed interpretability logging into communication analyzers to satisfy notified-body review protocols. Western European test houses are responding by recruiting machine-learning validation specialists and retrofitting existing benches with audit-trail capabilities.
Fleet operators now bundle interoperability certification into vehicle procurement contracts rather than accepting manufacturer self-declaration. Large commercial buyers in California and Texas negotiate direct relationships with third-party test laboratories, disintermediating OEM quality departments. This shift concentrates contract volume with laboratories offering same-day turnaround on protocol regression testing, marginalizing smaller regional providers lacking 24-hour staffing.
Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market Segmentation
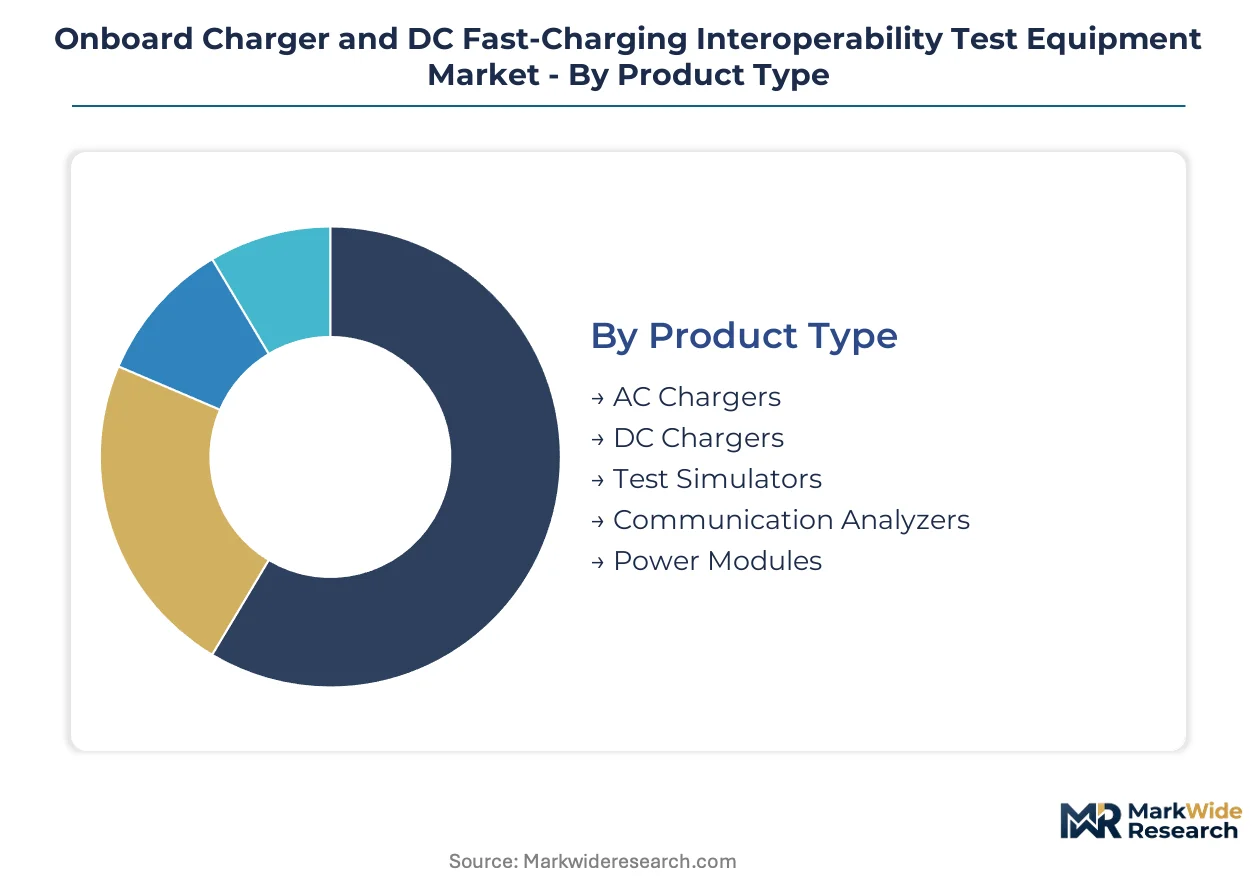
Test-equipment purchasing patterns diverge sharply by stakeholder technical maturity and certification burden. Segmentation reveals how protocol complexity concentrates margin in communication-layer instrumentation while hardware commoditization erodes power-electronics pricing.
Product Type:
Use-case spectrum spans prototype bench validation through production-line stress-testing, with procurement criteria shifting from technical flexibility to throughput speed across the development cycle.
- Test Simulators:Hardware-in-the-loop platforms replicate vehicle-side or infrastructure-side charging behavior under fault conditions. Fleet operators in California and Texas negotiate direct laboratory relationships for same-day regression testing, bypassing OEM quality departments.
- Communication Analyzers:Protocol-capture instruments decode CCS powerline communication and CHAdeMO CAN bus arbitration at physical and application layers. Germany's KBA type-approval mandates for ISO 15118-20 bidirectional validation expand analyzer scope from handshake verification to full V2G stress-testing.
- AC Chargers:Lower-voltage validation equipment for residential and workplace charging interoperability.
- DC Chargers:High-power test systems for public fast-charging infrastructure certification.
- Power Modules:Silicon carbide-based switching components for 800V onboard charger validation.
Established volume favors test simulators; emerging adoption favors communication analyzers.
Technology:
Protocol architectures fragment across regional regulatory regimes, forcing multi-standard capex commitments from equipment suppliers serving dual-market vehicle programs.
- CCS:Combined Charging System dominates Western markets with ISO 15118-2 and -20 protocol stacks. Germany's automotive testing corridor from Munich to Stuttgart anchors high-frequency protocol analysis demand as the KBA enforces rigorous DC fast-charging compatibility type-approval.
- GB/T:Chinese national standard retains captive domestic demand with distinct physical connector and communication specifications. Cross-border certification reciprocity gaps with KBA requirements force redundant test campaigns for manufacturers pursuing dual-market homologation.
- CHAdeMO:Japanese-developed standard with established presence in Asian markets and legacy fleet infrastructure.
- Tesla Supercharger:Proprietary network opening to third-party vehicles, creating new interoperability validation requirements.
- AV Charging Systems:Autonomous vehicle charging interfaces for unmanned connector engagement and payment automation.
Revenue concentration sits with CCS; steepest expansion trajectory belongs to AV charging systems.
Application:
Validation intensity correlates with downtime cost exposure, amplifying test-equipment value in commercial fleet contexts against consumer vehicle programs.
- Fleet Operations:Municipal transit authorities in California and New York specify pre-certified charging compatibility, driving demand for high-throughput benches validating multiple vehicle-charger pairings simultaneously. Downtime costs amplify procurement budgets for comprehensive pre-deployment testing.
- Electric Buses:Heavy-duty transit applications with extended dwell times and high-power charging requirements. Procurement teams now bundle interoperability certification into vehicle contracts rather than accepting manufacturer self-declaration.
- Electric Vehicles:Passenger car onboard charger and charging port validation for retail markets.
- E-Mobility Infrastructure:Public and private charging network equipment certification.
- Charging Stations:Fixed infrastructure interoperability testing for network operators.
Contract volume concentrates in fleet operations; technology investment flows toward electric buses.
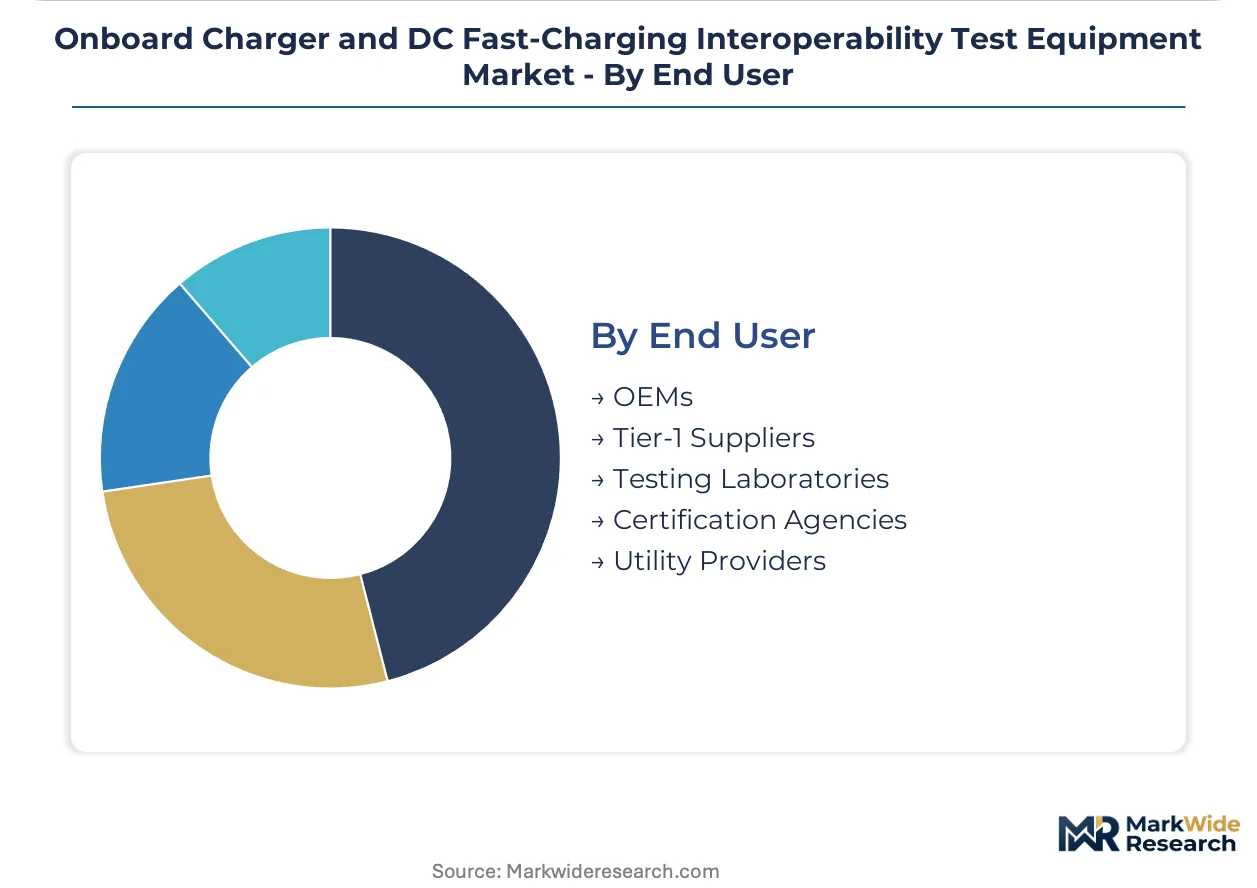
End User:
Procurement authority is shifting from OEM quality departments to direct laboratory relationships as large commercial buyers seek audit independence.
- Testing Laboratories:Third-party validation facilities offering protocol regression testing with 24-hour staffing. Same-day turnaround capability concentrates contract volume with larger providers, marginalizing smaller regional operators.
- OEMs:Electric vehicle manufacturers building internal validation capacity for prototype-to-production workflows. Procurement teams represent the fastest-growing buyer segment driven by tightening ISO 15118 and CCS certification mandates.
- Tier-1 Suppliers:Component manufacturers integrating charging hardware into vehicle platforms.
- Certification Agencies:Notified bodies conducting regulatory type-approval testing.
- Utility Providers:Grid operators validating vehicle-to-grid interoperability and bidirectional power flow.
Established relationships anchor testing laboratories; emerging budget authority shifts to OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test-equipment manufacturing clusters in Germany, the United States, Japan, China, and South Korea concentrate the bulk of protocol-validation capacity and R&D investment for high-voltage charging systems.
Germany
The KBA enforces ISO 15118-20 bidirectional power-flow validation for type approval, expanding test-equipment scope from unidirectional handshake verification to full V2G protocol stress-testing. Munich-Stuttgart corridor laboratories anchor high-frequency protocol analysis demand as OEMs accelerate 800V onboard charger development cycles.
United States
EPA zero-emission vehicle mandates and California Air Resources Board fleet procurement rules drive municipal transit authorities to specify pre-certified charging compatibility. Silicon Valley and Detroit engineering clusters concentrate RF-domain instrumentation expertise pulled into DC-power electronics disciplines by silicon carbide adoption.
Japan
METI standardization frameworks for CHAdeMO protocol evolution sustain domestic test-equipment demand while export markets fragment. Nagoya and Tokyo engineering clusters retain deep expertise in CAN bus arbitration and legacy fleet infrastructure validation.
China
MIIT homologation requirements for GB/T standards create captive domestic demand with distinct physical connector specifications. Cross-border certification reciprocity gaps with European KBA requirements force redundant test campaigns for manufacturers pursuing dual-market vehicle programs.
South Korea
Domestic EV manufacturing scale and government-backed battery supply chain investments generate concentrated demand for production-line test benches. Seoul-Incheon corridor facilities specify hardware-in-the-loop compatibility as procurement prerequisite, collapsing distinction between prototype validation and mass-production testing.
Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market Competitive Landscape
Measurement-instrument specialists and industrial-automation conglomerates split the market between high-margin protocol-analysis tools and integrated test-bench systems. Three archetypes dominate: RF-domain instrumentation heritage players, digital-twin platform integrators, and automotive sensor-technology extenders. Consolidation pressure elevates M&A activity for communication-analyzer capabilities while modular software-defined architectures force portfolio diversification away from fixed-configuration hardware.
Within the instrumentation tier, Keysight Technologies and HORIBA exemplify RF-domain heritage positions, while Siemens occupies a digital-twin integration archetype. Robert Bosch anchors the automotive-technology extension segment. These three represent distinct strategic responses to protocol fragmentation forcing equipment architectures toward software-upgradable platforms.
| Leading Market Players |
|---|
| Keysight Technologies |
| Siemens |
| ABB |
| Robert Bosch |
| Schneider Electric |
| Delta Electronics |
| Intertek |
| TÜV SÜD |
| HORIBA |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride semiconductor foundries in Japan and China anchor upstream supply for 1000V test simulators, concentrating pricing power with equipment manufacturers who control RF-domain instrumentation expertise while squeezing margin at mid-tier assemblers dependent on spot-market component sourcing.
Pricing Analysis
ISO 15118-20 mandates dictate the pricing tier structure across the test-equipment market. Three-tier pricing structure across premium, standard, and economy levels separates full V2G protocol validation suites from handshake-only verification tools and basic power-electronics benches. Price differentiation stems from certification grade alignment with KBA type-approval requirements and geographic delivery cost differentials. Pricing pressure stems from silicon carbide module commoditization in 800V onboard charger segments. Tier-2 equipment lessors exhibit highest price sensitivity due to compressed depreciation cycles; OEM procurement teams show lowest sensitivity where downtime avoidance justifies premium positioning.
Supply Chain Analysis
Silicon carbide substrates from Japan, gallium nitride wafers from China, and precision RF components from Germany feed into test-equipment manufacturing clusters. Raw material dependencies center on wide-bandgap semiconductors, high-voltage capacitors, and specialized signal-conditioning hardware. Single-source vulnerability concentrates in Japanese GaN foundry capacity allocated across automotive and telecommunications demand. Distribution runs through direct OEM procurement contracts and third-party laboratory equipment leasing channels with regional service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where software-defined architectures displace fixed-configuration hardware, with the CCS-to-NACS protocol transition accelerating winner-take-most dynamics among vendors controlling modular firmware-upgrade pathways.
For Market Incumbents: Harden defensive positioning through backward integration into silicon carbide power module design and captive certification laboratory partnerships in Germany's Munich-Stuttgart corridor. The threat of Chinese equipment vendors leveraging domestic GB/T standard capture demands preemptive investment in ISO 15118-20 V2G validation capabilities before regulatory mandates expand. For New Entrants and Emerging Players: Build out specialized communication analyzer offerings targeting autonomous fleet depot charging applications in California and Texas, where unmanned connector engagement protocols create validation gaps incumbent platforms have not addressed. White-space concentration sits with AV charging system interoperability testing; go-to-market traction requires direct relationships with municipal transit procurement authorities specifying pre-certified compatibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital-twin platform specialists lacking automotive domain credibility. Long-term viability over the next decade hinges on software licensing revenue exceeding hardware sales as refresh cycles compress. Acquisition target archetype: modular HIL bench providers with cloud-native compliance reporting. The signal to watch is NACS protocol adoption velocity among non-Tesla OEMs as inflection indicator for multi-standard capex burden relief.| Strategic Initiative | Industry Significance |
|---|---|
| Digital-Twin Platform Integration | Cloud-based compliance reporting enables remote certification workflows for KBA type-approval. |
| Software-Defined Architecture Migration | Firmware-upgradable platforms extend equipment lifecycles amid CCS2 and megawatt-charging fragmentation. |
| Backward Integration into SiC Modules | In-house power semiconductor design secures supply for 800V onboard charger validation benches. |
| Autonomous Fleet Depot Partnership | Unmanned connector engagement protocols open premium niches beyond passenger vehicle testing. |
| India Technical Training Infrastructure | PLI scheme alignment creates localized deployment demand for Gujarat and Tamil Nadu manufacturing clusters. |
Research Methodology
A standing panel of OEM platform engineers, third-party laboratory technical directors, Tier-1 supplier procurement managers, and certification agency notified-body representatives provided ongoing calibration across primary interview cycles. Secondary validation drew from KBA type-approval filings, EPA zero-emission vehicle mandate documentation, SEC equipment manufacturer disclosures, and ISO protocol revision drafts. Bottom-up and top-down triangulation reconciled equipment shipment data with OEM R&D budget allocations.
Scenario-bracketing framed analytical approach across the projection horizon, modeling segmentation dimensions spanning product type, protocol technology, application intensity, and end-user procurement authority. CAGRs were derived from equipment refresh cycle compression rates and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated silicon carbide adoption curves in 800V architectures and ISO 15118-20 bidirectional validation scope expansion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed equipment vendors or accelerated NACS protocol unification would shift outcomes substantially. Cross-checking against IHS Markit vehicle production databases and KBA homologation statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.