
 Electronic Test Instrument Market | 2026-2036
Electronic Test Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Test Instrument Market Analytics
Direct distribution partnerships between instrument makers and semiconductor foundries is reconfiguring how calibration services and firmware updates reach end users. Keysight Technologies leverages its in-house foundry relationships to anchor premium oscilloscope sales in Asia-Pacific manufacturing corridors. Rohde & Schwarz sustains dominance in RF testing through dedicated aerospace channel programs. Tektronix competes on software-defined architecture roadmaps that extend instrument lifecycle value.
Electronic test instruments comprise calibrated measurement devices that quantify electrical parameters including voltage, current, impedance, and spectral composition with precision typically spanning microvolts to kilovolts and hertz to terahertz frequencies; their primary purpose is verifying design integrity, production quality, and regulatory compliance across engineered systems. Oscilloscopes and spectrum analyzers represent mature margin pools where replacement cycles and bandwidth upgrades generate recurring revenue, while software-defined instruments capture the fastest structural expansion as virtualization collapses hardware refresh costs. Multimeters occupy a commoditized tier where Asian manufacturing scales compress pricing, and hybrid architectures bridge legacy analog installations toward digital measurement platforms without full infrastructure replacement.
FCC equipment authorization rules in the United States, EU CE marking under the EMC Directive, and China's GB standards administered by SAMR collectively shape electromagnetic compatibility testing demand and dictate instrument certification requirements for market access. RoHS substance restrictions and REACH chemical protocols in Europe force manufacturers to redesign probe assemblies and solder compositions. Stakeholders must monitor how software-defined instrument architectures interact with evolving cybersecurity frameworks in connected test environments.
Market Dynamics
Software-defined instrument architectures are collapsing hardware refresh cycles while semiconductor fabs in Taiwan and South Korea demand precision measurement tools at unprecedented bandwidth thresholds, forcing vendors to restructure firmware delivery and calibration service models around foundry co-location.
Growth Catalysts
- EU AI Act compliance mandates:Automated electromagnetic compatibility testing workflows now require certified instruments, expanding replacement demand across German automotive and industrial electronics manufacturing corridors.
- China's 5G base station rollout:Massive domestic infrastructure deployment drives concentrated procurement of vector network analyzers and spectrum analyzers for RF component verification.
- Electric vehicle inverter testing:Silicon carbide and gallium nitride power electronics in EV drivetrains demand higher-voltage, higher-frequency measurement capabilities than legacy test benches provide.
Market Restraints
- Probe assembly input costs:RoHS substance restrictions and REACH chemical protocols in Europe force redesign of solder compositions and cable materials, compressing margins on mid-tier multimeter lines.
- Precision component supply concentration:High-bandwidth oscilloscope front-end amplifiers and ultra-stable reference sources depend on specialized foundry capacity concentrated in Taiwan and South Korea.
- Legacy analog infrastructure lock-in:Aerospace and defense test installations carry decades-old GPIB-based systems that resist full digital migration without complete rack replacement.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and telecom equipment assembly create greenfield test instrument demand in Bengaluru and Hyderabad corridors.
- Cloud-native test orchestration:Containerized measurement software enables remote instrument pooling across distributed R&D sites, collapsing capital intensity for mid-size enterprises.
- Battery cell formation testing:Gigafactory-scale lithium-ion production lines require high-channel-count data acquisition systems for electrochemical impedance spectroscopy during cell conditioning.
Industry Challenges
- RF/mmWave calibration expertise scarcity:Sub-6 GHz and terahertz measurement accuracy demands specialized metrology skills that outpace university pipeline output in all major manufacturing regions.
- Cybersecurity certification complexity:Connected test environments must satisfy IEC 62443 industrial security standards and customer-specific IT/OT segmentation requirements, extending sales cycles.
- Legacy GPIB-to-Ethernet protocol bridging:Hybrid architectures attempting incremental digital upgrades face synchronization jitter and timing precision degradation that invalidates high-frequency measurements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Test Instrument Market |
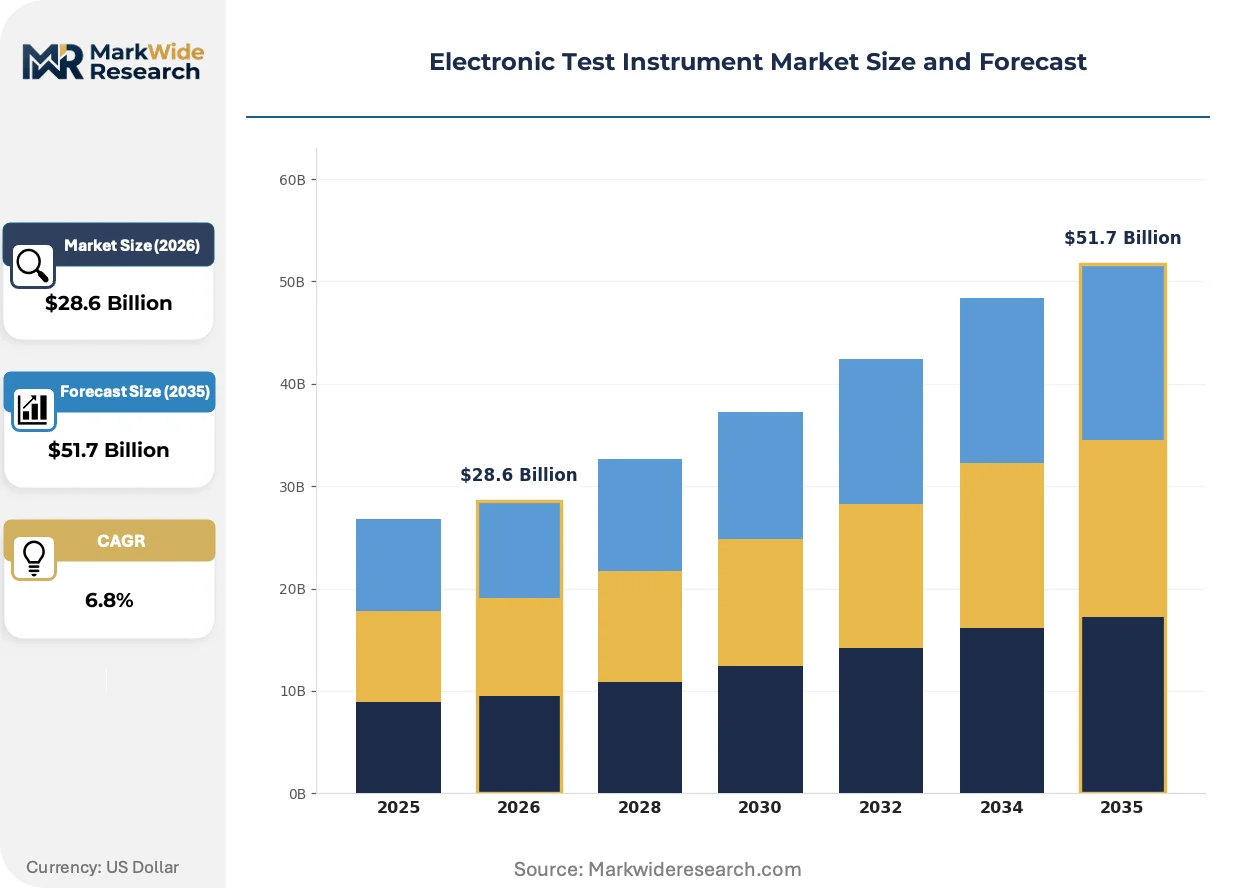
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multimeters, Oscilloscopes, Spectrum Analyzers, Function Generators Technology: Analog, Digital, Hybrid, Software-Defined End User: Manufacturing, Telecommunications, Automotive, Aerospace Application: Electronics Testing, Telecommunications Testing, Power System Testing, RF Testing |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Tektronix, Fluke Corporation, National Instruments, Anritsu Corporation, Yokogawa Electric Corporation, Fortive Corporation, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Test Instrument Market Evolving Landscape
Virtualization of instrument functionality is collapsing the traditional hardware-software boundary, enabling subscription-based access to measurement capabilities and compressing the economic rationale for capital-intensive bench equipment ownership across R&D and production environments.
Software-defined radio architectures are digitizing RF test workflows by replacing discrete hardware signal generators with reprogrammable FPGA-based waveform synthesis. 5G base station manufacturers in China and South Korea now specify SDR-based conformance test systems for protocol validation. This digitization is compressing capital equipment refresh timelines from seven-year cycles to three-year software license renewals.
The EU AI Act's risk-based classification system for automated decision-making systems is mandating documented measurement traceability for electromagnetic compatibility self-certification workflows. Industrial electronics vendors in Germany must now demonstrate instrument calibration chains to notified bodies. High-end spectrum analyzer sales into automated test equipment racks are accelerating as manufacturers pre-empt audit exposure.
Foundry-direct distribution partnerships are displacing traditional channel intermediaries for high-volume precision instrument procurement. Semiconductor fabs in Taiwan now negotiate enterprise-wide calibration service contracts bundled with oscilloscope and probe purchases. This consolidation is visible most acutely in Hsinchu Science Park, where direct vendor relationships anchor multi-year equipment refresh roadmaps tied to process node transitions.
Electronic Test Instrument Market Segmentation
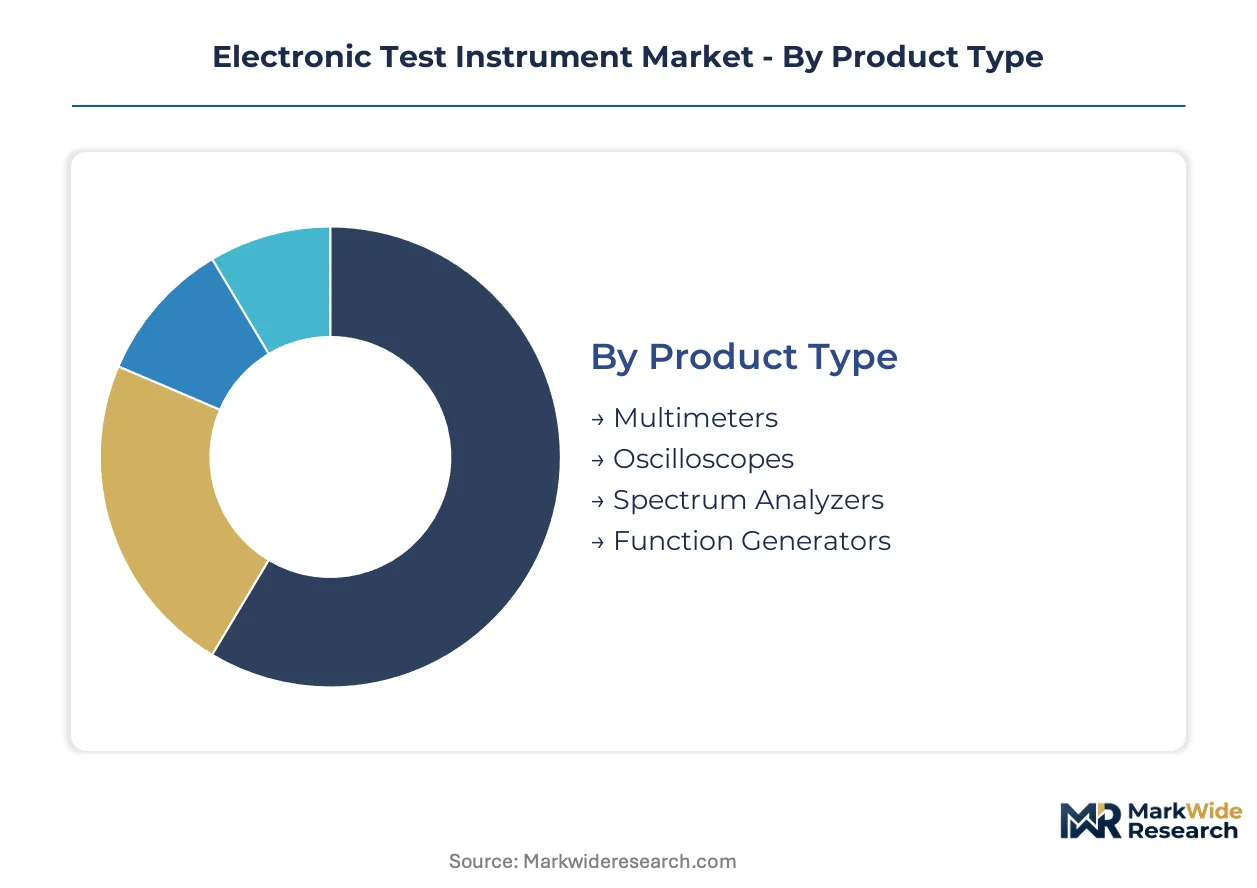
Electronic test instrument segmentation reveals how calibration service intensity, firmware update frequency, and probe replacement cycles vary dramatically across product architectures and end-use environments. Understanding these patterns enables vendors to align service revenue models with equipment deployment profiles.
Product Type:
After-sales service intensity escalates with measurement precision requirements, bandwidth thresholds, and probe wear rates across instrument categories.
- Oscilloscopes:High-bandwidth front-end amplifiers and precision ADC architectures demand annual calibration cycles and probe replacement programs. Semiconductor fabs in Taiwan negotiate enterprise-wide service contracts bundled with multi-year equipment refresh roadmaps.
- Spectrum Analyzers:RF and millimeter-wave measurement chains require specialized metrology expertise and traceable reference sources. German automotive EMC testing facilities drive replacement demand as EU AI Act compliance mandates documented measurement chains.
- Multimeters:Commoditized measurement devices with compressed margins and minimal service attachment rates.
- Function Generators:Signal synthesis instruments with moderate calibration intervals and standardized probe interfaces.
Oscilloscopes hold the largest share; momentum sits with spectrum analyzers.
Technology:
Cost tier stratification separates capital-intensive hardware ownership from subscription-based capability access across architecture generations.
- Software-Defined:FPGA-based waveform synthesis and containerized measurement software collapse hardware refresh cycles from seven years to three-year license renewals. 5G base station manufacturers in China and South Korea specify SDR-based conformance test systems for protocol validation.
- Digital:Precision ADC architectures with embedded processing and Ethernet-native connectivity for automated test equipment integration.
- Hybrid:Bridge architectures connecting legacy GPIB installations to modern digital backplanes without full rack replacement.
- Analog:Legacy architectures concentrated in aerospace and defense test installations with decades-old infrastructure lock-in.
Digital architectures dominate installed base; software-defined platforms are expanding most quickly.
End User:
Application-specific compliance regimes and measurement bandwidth requirements concentrate demand across industrial verticals.
- Telecommunications:Vector network analyzers and spectrum analyzers for RF component verification in China's domestic 5G base station rollout. Massive infrastructure deployment drives concentrated procurement with compressed delivery timelines.
- Automotive:Silicon carbide and gallium nitride inverter testing for electric vehicle drivetrains demands higher-voltage, higher-frequency measurement capabilities than legacy benches provide.
- Manufacturing:Production line integration with automated test equipment racks and statistical process control systems.
- Aerospace:Decades-old GPIB-based systems resist full digital migration without complete rack replacement, creating hybrid architecture demand.
Telecommunications commands the largest procurement volume; automotive shows the steepest expansion trajectory.
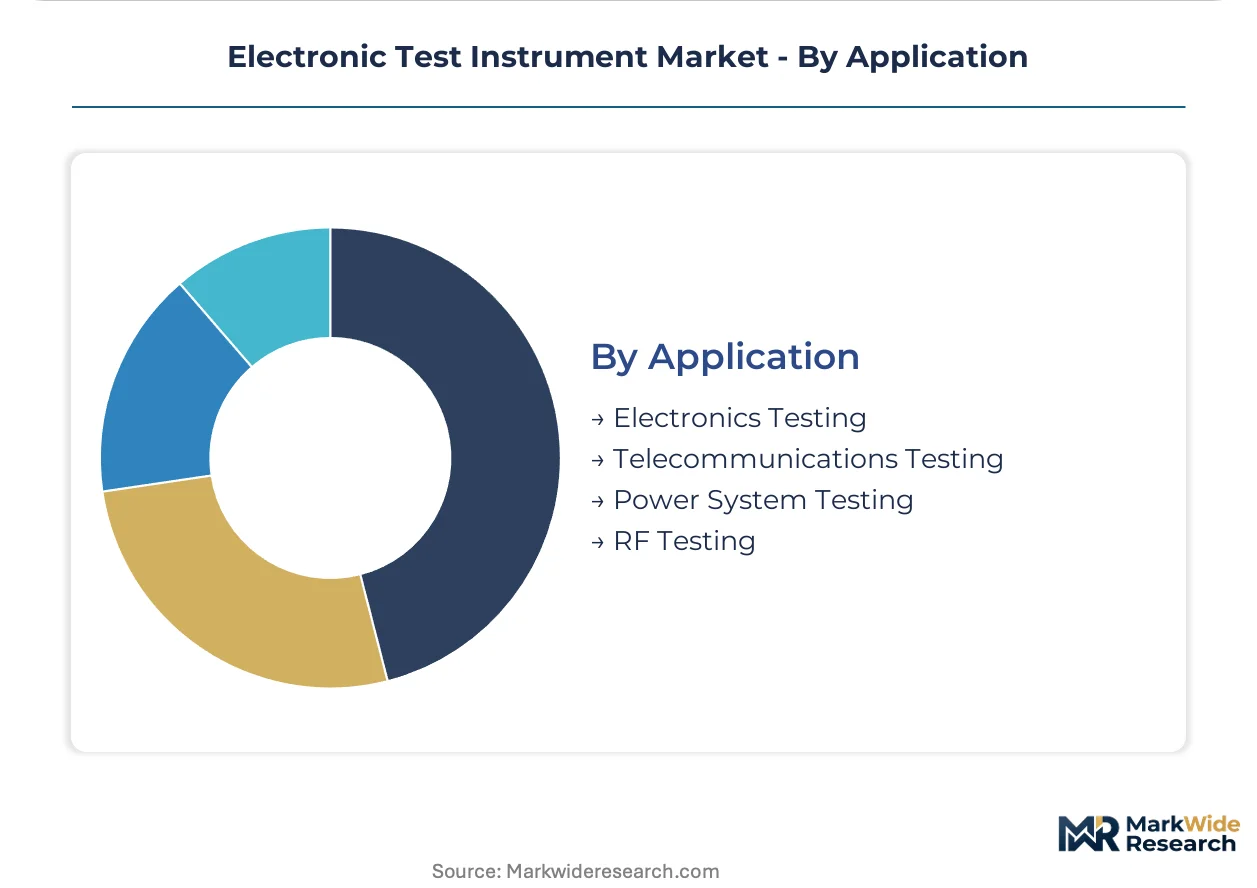
Application:
Volume concentration and margin profiles diverge sharply between standardized production testing and specialized R&D characterization workflows.
- RF Testing:Sub-6 GHz and terahertz measurement accuracy demands specialized metrology skills that outpace university pipeline output. RF/mmWave calibration expertise scarcity extends sales cycles and elevates service pricing power.
- Power System Testing:Gigafactory-scale lithium-ion production lines require high-channel-count data acquisition for electrochemical impedance spectroscopy during cell conditioning.
- Electronics Testing:General-purpose verification across consumer and industrial electronics with standardized instrument configurations.
- Telecommunications Testing:Protocol validation and conformance certification for network equipment deployment.
RF Testing generates the highest service revenue intensity; Power System Testing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taichung high-speed rail corridor underwrites Taiwan's dominance in precision test instrument procurement, shuttling calibration engineers between semiconductor fabrication clusters. This infrastructure backbone enables same-day service response times that anchor multi-year enterprise contracts.
United States
FCC equipment authorization rules for 5G mmWave devices drive spectrum analyzer refresh cycles at defense contractors in Maryland and California. The Inflation Reduction Act's clean energy tax credits accelerate EV inverter testing demand across Michigan and Ohio automotive corridors. Austin's emerging semiconductor hub attracts instrument vendors establishing calibration facilities for local fab operations.
Germany
EU AI Act compliance mandates documented measurement traceability for automated EMC self-certification workflows. The KBA enforces stricter electromagnetic compatibility verification for automotive electronics exported from Stuttgart and Munich manufacturing basins. Fraunhofer research institutes in Dresden partner with instrument makers on terahertz measurement standardization protocols.
China
MIIT's domestic 5G base station deployment targets concentrate vector network analyzer procurement in Shenzhen and Chengdu telecom equipment hubs. SAMR-administered GB standards for electromagnetic compatibility testing force instrument recertification for market access. Hefei's memory chip fabrication expansion drives oscilloscope demand for wafer-level probe testing.
South Korea
MFDS-equivalent telecom equipment certification requirements for 6G research prototypes elevate spectrum analyzer specifications at Samsung and SK Hynix R&D campuses. Government-backed K-Chips Act funding expands Pyeongtaek and Yongin fab capacity, triggering bundled instrument service contracts. Busan's RF component manufacturing cluster sources high-frequency test systems for 5G antenna module verification.
India
BIS certification mandates for imported electronic test equipment create compliance friction that domestic assembly partnerships resolve. The PLI scheme for semiconductor and telecom equipment manufacturing generates greenfield instrument demand in Bengaluru and Hyderabad corridors. Delhi-Mumbai Industrial Corridor infrastructure projects attract calibration service providers establishing regional hubs.
Electronic Test Instrument Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision front-end modules and reference sources. The vendor base stratifies between full-stack measurement platform providers, modular instrument architects, and discrete component fabricators. Three archetypes dominate: vertically integrated platform vendors with captive foundry relationships, software-defined architecture specialists licensing virtualization stacks, and precision analog component houses supplying front-end amplifiers. Competitive intensity concentrates on M&A activity absorbing calibration service networks and strategic partnerships binding foundry procurement to multi-year refresh roadmaps.
Among US-based platform vendors, Keysight Technologies and National Instruments exemplify divergent architectural bets—one anchoring premium hardware ownership models, the other advancing modular software-defined configurations. Rohde & Schwarz, a German GmbH-structured entity, occupies a position representing European precision RF specialization with aerospace channel depth. These three names illustrate how geographic origin and corporate structure map to distinct competitive postures without prescribing specific strategic actions or market shares.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Tektronix |
| Fluke Corporation |
| National Instruments |
| Anritsu Corporation |
| Yokogawa Electric Corporation |
| Fortive Corporation |
| AMETEK |
| Others |
Value Network & Pricing Analysis
The Kaohsiung-Taichung high-speed rail corridor underwrites Taiwan's dominance in precision test instrument procurement, shuttling calibration engineers between semiconductor fabrication clusters. This infrastructure backbone enables same-day service response times that anchor multi-year enterprise contracts, compressing logistics costs for high-bandwidth oscilloscope shipments while amplifying price premiums for vendors with localized service networks.
Pricing Analysis
Volume-discount tiering structures separate enterprise foundry contracts from mid-tier manufacturing procurement and spot-market academic purchases. Pricing stratifies across premium, standard, and economy tiers based on calibration certification grade and after-sales bundling intensity. Cost compression in the mid-tier multimeter segment is intensifying because RoHS-compliant probe assembly redesigns inflate input costs without commensurate performance gains. Semiconductor fabs in Taiwan and South Korea exhibit the lowest price sensitivity, prioritizing bandwidth specifications and service response times over unit economics.
Supply Chain Analysis
Export-control regime restrictions on high-bandwidth ADCs and precision reference sources limit flows from US and European component houses to Chinese system integrators. Front-end amplifier modules draw from specialized foundry capacity concentrated in Taiwan, South Korea, and the United States. Single-source vulnerability pervades the ultra-stable frequency reference market, where atomic clock subassemblies rest on three qualified suppliers. Distribution runs through direct vendor-foundry partnerships in Hsinchu and Pyeongtaek, displacing traditional distributor intermediaries for high-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through semiconductor foundry consolidation in Taiwan and South Korea, where enterprise procurement teams negotiate multi-year calibration bundles that commoditize hardware margins. This fragmentation among instrument vendors faces consolidated demand from fewer, larger fab operators.
For Market Incumbents: Build captive calibration service networks as the defensive moat against software-defined entrants collapsing hardware refresh cycles. Incumbents should deepen backward integration into precision front-end amplifier production to secure supply continuity from Taiwan foundries. Channel control through direct foundry relationships in Hsinchu Science Park represents the critical lever for defending service revenue attachment rates. For New Entrants and Emerging Players: India's PLI scheme corridors in Bengaluru and Hyderabad present geographic underpenetration where greenfield fab construction outpaces established vendor service infrastructure. New entrants should target battery cell formation testing applications in gigafactory-scale lithium-ion production, where high-channel-count data acquisition demand exceeds incumbent capacity. A calibration-service-first go-to-market angle bypasses capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant precision measurement divisions lacking foundry-direct distribution relationships. Long-term viability in this market hinges on software-defined architecture roadmaps that compress customer capital intensity while extending vendor recurring revenue windows. Watch for inflection signals in 6G research prototype certification requirements at South Korean R&D campuses, which will elevate spectrum analyzer specifications and trigger replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry-Direct Distribution Partnership | Keysight's Hsinchu enterprise contracts anchor multi-year refresh roadmaps tied to process node transitions. |
| Software-Defined Architecture Migration | FPGA-based waveform synthesis at 5G base station manufacturers compresses capital cycles to license renewals. |
| Calibration Service Network Acquisition | Absorbing regional metrology providers extends same-day response coverage along Taiwan's high-speed rail corridor. |
| RF/mmWave Expertise Development | Fraunhofer partnerships on terahertz standardization protocols address metrology skill scarcity in German automotive EMC testing. |
| Cloud-Native Test Orchestration Platform | Containerized measurement software enables remote instrument pooling across distributed R&D sites in mid-size enterprises. |
Research Methodology
Initial hypotheses were tested against primary input from test instrument product managers, semiconductor fab procurement directors, calibration service technicians, and EMC compliance engineers at automotive OEMs, then refined through secondary validation. SEC 10-K filings, MIIT equipment authorization databases, customs trade records for precision ADC imports, and Fraunhofer research partnership disclosures provided quantitative anchors. Bottom-up equipment shipment data from foundry capital expenditure disclosures triangulated against top-down market sizing from regulatory certification volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product architecture, end-use vertical, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression rates and software license renewal velocity. Industry-specific forecast inputs included 5G base station deployment trajectories from MIIT procurement data and EV inverter testing demand from IRA clean energy credit utilization patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by software-defined architecture specialists or Chinese state-backed instrument ventures would shift outcomes. Material shifts in Taiwan Strait logistics continuity or EU AI Act enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Diamond Tester Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Automated Ultrasonic Testing Market