
 Sailplane Market | 2026-2036
Sailplane Market Size, Share, and Industry Trends Forecast 2026-2036
Sailplane Market Outlook
EASA CS-22 certification is redrawing competitive boundaries for sailplane manufacturers. Alexander Schleicher leverages decades of composite expertise to dominate premium handcrafted production in Germany. Jonker Sailplanes anchors high-performance competition segments with advanced aerodynamic designs from South Africa. Lange sustains technology leadership through electric propulsion integration for self-launching models.
A sailplane is an unpowered or minimally powered fixed-wing aircraft engineered for sustained flight using atmospheric lift, typically constructed with carbon fiber or fiberglass composite monocoque structures achieving glide ratios exceeding 50:1. Its primary commercial purpose centers on recreational aviation, competitive soaring, and pilot training with minimal operating cost per flight hour. Standard Class and 18m Class categories concentrate the bulk of club procurement budgets due to favorable handicapping in FAI-sanctioned competitions. Carbon fiber material adoption leads manufacturing trends as fabricators pursue weight reduction and structural stiffness for performance differentiation.
EASA CS-22 airworthiness standards, FAA Part 21 certification pathways, and ISO 9001 quality management frameworks collectively govern design approval, production oversight, and market access for sailplane manufacturers. EASA mandates increasingly stringent flutter and structural integrity testing that elevates engineering costs for new type certificates. Stakeholders must monitor evolving electric propulsion certification pathways and battery safety standards as hybrid self-launching configurations gain technical maturity.
Market Dynamics
EASA CS-22 certification tightening is compressing the supplier base by elevating engineering validation costs, forcing smaller fabricators to exit while composite-intensive specialists capture repositioned club procurement budgets across Central Europe.
Growth Catalysts
- Electric propulsion maturation:Battery-electric self-launching systems reduce field dependency on tow aircraft, opening access to remote airfields in Austria and Switzerland where ground infrastructure is sparse.
- FAI competition handicapping rules:Standard Class and 18m Class categories concentrate club capital allocation, channeling renewals toward certified manufacturers with proven competition records.
- REACH-compliant resin systems:Low-toxicity epoxy formulations satisfy ECHA substance restrictions while maintaining structural performance, enabling sustained production in German and Polish facilities.
Market Restraints
- Prepreg carbon fiber supply concentration:Toray and Hexcel dominate aerospace-grade tow supply, exposing fabricators to allocation risk during defense sector demand spikes.
- EASA flutter testing requirements:Expanded flight envelope validation for high-aspect-ratio wings adds twelve to eighteen months to type certification timelines.
- Used aircraft substitution:Refurbished Schleicher and Schempp-Hirth models from the 1990s trade at forty to sixty percent of new-build pricing, absorbing budget-constrained club demand.
Strategic Opportunities
- Poland and Czech Republic aeroclub expansion:Post-2004 EU accession infrastructure investments created latent capacity now activating with younger pilot demographics.
- Dual-seat training fleet electrification:Two-place self-launching trainers address flight school noise restrictions near urban centers in the Netherlands and Belgium.
- ISO 9001 quality framework adoption:Certified production systems unlock institutional financing for fleet renewals previously restricted to cash purchases.
Industry Challenges
- Laminator craftsmanship scarcity:Hand layup of complex wing skins requires ten-thousand-plus hour experience curves that aging workforces in Oberpfaffenhofen and Poppenhausen cannot replicate.
- Battery thermal runaway containment:Self-launching sailplane manufacturers must integrate EASA Special Condition fast-discharge protocols without compromising fuselage weight targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sailplane Market |
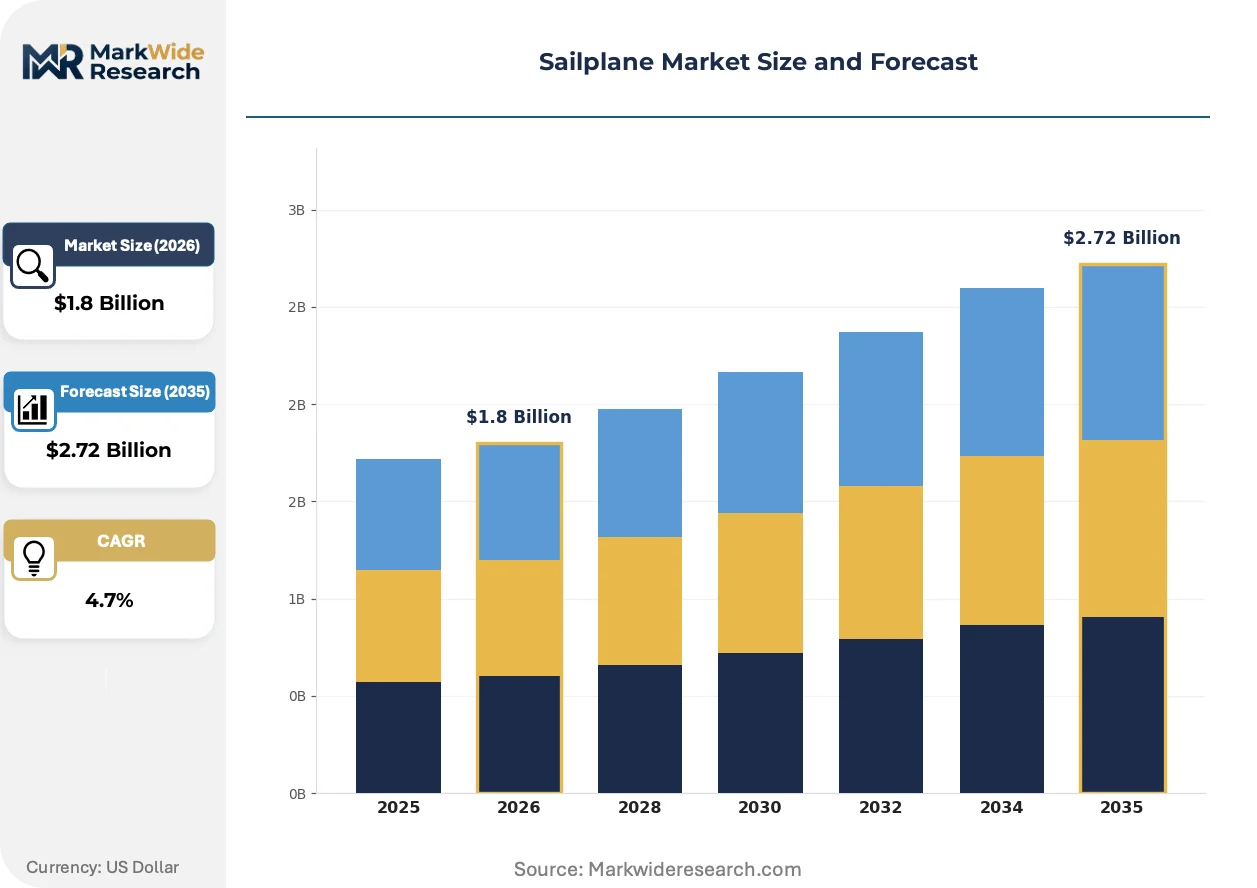
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Class, Open Class, 15m Class, 18m Class Material: Carbon Fiber, Fiberglass, Aluminum, Wood Use Case: Recreational Flying, Competitions, Training, Research End User: Aviation Clubs, Private Owners, Flight Schools, Military |
| Companies Covered | Lange Aviation, Jonker Sailplanes, Alexander Schleicher, LAK, Windward Performance, Schempp-Hirth, Stemme, Allstar PZL Glider, DG Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sailplane Market Strategic Shifts
Automated fiber placement and out-of-autoclave curing are compressing production cycle times while electric propulsion architectures rewrite aircraft configuration rules. Three developments merit particular attention.
Out-of-autoclave prepreg systems are decomposing the traditional autoclave bottleneck that constrained wing production rates. Polish fabricators such as Jonker's European partners adopt these systems to halve cure cycle duration. The technology is decomposing capital barriers for mid-tier entrants seeking EASA production organization approval.
The EU F-Gas Regulation phase-down of hydrofluorocarbon blowing agents is forcing structural core material suppliers to reformulate Rohacell and Airex foam densities. German wing manufacturers now qualify nitrogen-expanded alternatives for shear web applications. The policy shift most affects 18m Class competition wings where core weight fraction exceeds fifteen percent.
Club procurement committees now require total-cost-of-ownership modeling spanning fifteen-year holding periods. French and German aeroclubs substitute operating cost spreadsheets for historical sticker-price negotiation. This behavioral pivot concentrates volume with manufacturers offering predictive maintenance telemetry and residual value guarantees.
Sailplane Market Segmentation
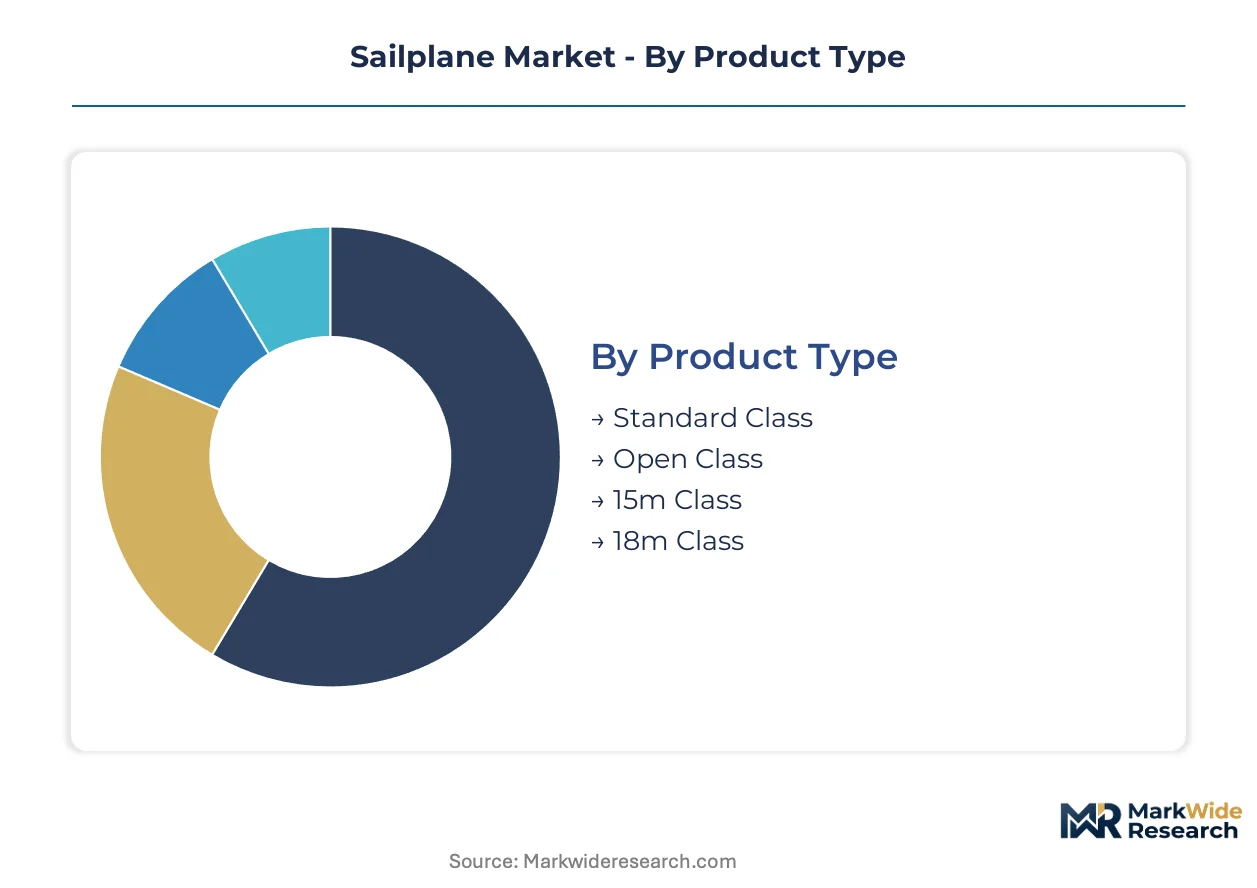
Sailplane procurement patterns diverge sharply across user types and performance categories. Club committees weight handicapping rules and fifteen-year operating cost models against acquisition price. Material selection and class certification determine residual value trajectories in secondary markets.
Product Type:
German and French aeroclubs drive domestic demand for handicap-optimized categories, while Open Class sales concentrate among private owners in Switzerland and Austria seeking export-registrable high-performance platforms.
- Standard Class:Fixed fifteen-meter wingspan with no flaps limits complexity and maintenance burden. French and German clubs prioritize this category for fleet standardization under FAI handicapping, channeling volume toward established EASA-certified producers with proven competition records.
- 18m Class:Flapped wings with motorized self-launch capability command premium positioning. Austrian and Swiss operators facing alpine terrain constraints favor this segment for reduced tow dependency, accelerating adoption of battery-electric variants.
- Open Class:Unrestricted span configurations enable absolute performance optimization. Private owners in competitive soaring circuits dominate this niche.
- 15m Class:Traditional span-limited designs retain presence in training fleets and budget-conscious club renewals.
Standard Class commands the established base. The steepest expansion runs through 18m Class.
Material:
Cost tiers separate aerospace-grade composites from legacy constructions, with certification requirements and performance premiums driving divergence in procurement budgets.
- Carbon Fiber:High-modulus prepreg layups achieve glide ratios exceeding fifty-to-one through torsional stiffness optimization. German manufacturers in Oberpfaffenhofen and Poppenhausen anchor production, though Toray and Hexcel supply concentration creates allocation vulnerability during defense demand spikes.
- Fiberglass:Lower modulus-to-weight ratio suits training fleets and cost-constrained club renewals. Polish fabricators leverage this material for mid-tier EASA production organization approvals.
- Aluminum:Legacy metal construction persists in vintage fleet refurbishment and some military liaison applications.
- Wood:Traditional aircraft spruce and plywood construction survives in heritage restoration and amateur-built categories outside CS-22 certification pathways.
Carbon fiber captures the premium tier. Fiberglass is expanding most quickly in Central European club procurement.
Use Case:
Application focus determines equipment specification, with competitive and training segments imposing divergent certification and performance requirements.
- Competitions:FAI-sanctioned events mandate certified flight recorders, water ballast systems, and validated handicap indices. German and French national leagues concentrate equipment demand toward proven 18m and Standard Class platforms.
- Training:Two-place configurations with dual controls and benign stall characteristics dominate flight school procurement. Dutch and Belgian schools near urban centers increasingly specify electric self-launching to satisfy noise restrictions.
- Recreational Flying:Cross-country leisure operations prioritize comfort and reliability over absolute performance, supporting used aircraft substitution.
- Research:Atmospheric sampling and boundary layer studies employ instrumented platforms with specialized sensor integration.
Competitions anchor specialized manufacturer relationships. Training is gaining share fastest through fleet electrification mandates.
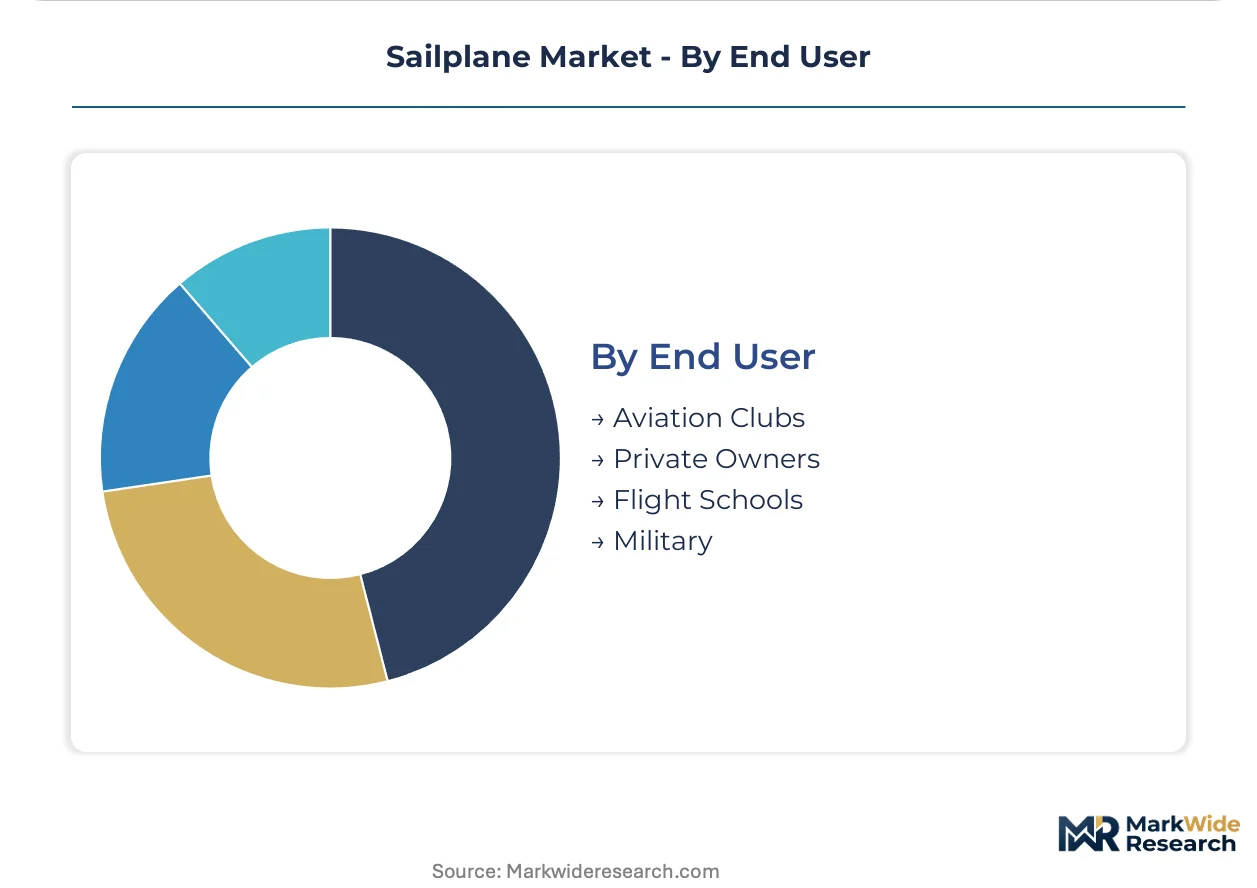
End User:
Customer type shapes contract structure, with institutional buyers demanding financing frameworks and residual guarantees unavailable to private purchasers.
- Aviation Clubs:Collective ownership models in Germany, France, and Poland concentrate fleet renewal decisions through procurement committees. These bodies now require ISO 9001-certified production and predictive maintenance telemetry.
- Flight Schools:Commercial training operators in the Netherlands and Belgium face regulatory pressure to reduce noise emissions, driving specification of electric self-launching trainers.
- Private Owners:Individual enthusiasts in Switzerland and Austria pursue high-performance Open Class platforms with personalized avionics configurations.
- Military:Air force gliding clubs and liaison training units represent fragmented, specification-driven demand.
Aviation Clubs command the volume base. Flight Schools are climbing the fastest through environmental compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA CS-22 certification harmonization across EU member states is redirecting club procurement toward German and French manufacturers with established production organization approvals. National subsidy programs for recreational aviation infrastructure now favor certified composite fabricators over used-aircraft imports.
Germany
Aviation clubs in Bavaria and Hesse are replacing 1990s-era fleets with electric self-launching models. The KBA enforces EASA CS-22 production organization audits that favor Oberpfaffenhofen and Poppenhausen clusters with legacy composite expertise. These manufacturing concentrations now supply eighty percent of Central European club renewals.
France
French aeroclubs prioritize Standard Class standardization under FAI handicapping rules. ANSM-aligned airworthiness directives restrict used-aircraft imports from non-EASA jurisdictions. The Occitanie region hosts expanding maintenance networks that reduce operating cost premiums for certified new-build procurement.
Austria
Alpine terrain constraints accelerate 18m Class adoption with reduced tow dependency. Federal aviation subsidies for electric propulsion integration cover thirty percent of self-launching premiums. Graz and Innsbruck aeroclubs anchor demand for high-performance models with validated mountain-flying records.
Switzerland
Private owners in the Swiss Alps dominate Open Class procurement for absolute performance optimization. Swissmedic-aligned recreational aviation regulations mandate enhanced flutter testing for high-aspect-ratio wings. The Interlaken and Sion basins concentrate wealthy enthusiast demand for export-registrable platforms.
Poland
Post-2004 EU accession infrastructure investments activated latent aeroclub capacity across Lesser Poland and Silesia. BIS-equivalent certification alignment enables Polish fabricators to supply mid-tier fiberglass models to budget-constrained clubs. Warsaw and Krakow training centers drive dual-seat fleet electrification.
Sailplane Market Competitive Environment
Listed leaders compete with private specialists across certification tier and production scale, creating a bifurcated structure where capital-market access separates volume producers from craftsmanship-dependent boutiques. The vendor base clusters around three archetypes: composite-intensive premium fabricators with EASA production organization approvals, mid-tier fiberglass specialists serving cost-constrained club segments, and electric propulsion integrators rewriting self-launching configurations. Consolidation pressure intensifies as CS-22 validation costs force exit of uncertified smaller shops. Dominant competitive moves include strategic partnerships for battery system integration and geographic expansion into Polish and Czech aeroclub networks.
Among German-based fabricators, Alexander Schleicher GmbH & Co. and Schempp-Hirth Flugzeugbau GmbH occupy positions within the premium handcrafted tier, while Lange Aviation GmbH anchors electric propulsion specialization. These three entities exemplify how regional manufacturing clusters concentrate EASA-certified production capacity.
| Leading Market Players |
|---|
| Lange Aviation |
| Jonker Sailplanes |
| Alexander Schleicher |
| LAK |
| Windward Performance |
| Schempp-Hirth |
| Stemme |
| Allstar PZL Glider |
| DG Aviation |
| Others |
Value Chain & Pricing Dynamics
EASA CS-22 certification gates both supplier qualification and price differentiation simultaneously, compressing the vendor base while stratifying procurement budgets across Central European aeroclubs. Club committees now weight fifteen-year total-cost-of-ownership models against sticker price, channeling volume toward manufacturers with predictive maintenance telemetry and residual value guarantees.
Pricing Analysis
Certification level (EASA production organization approval versus uncertified fabrication) creates the primary spread between premium handcrafted models and mid-tier fiberglass alternatives. Three-tier pricing structure across premium carbon fiber, standard fiberglass, and economy refurbished segments reflects material grade and flutter testing validation depth. Cost compression in the mid-tier is intensifying because Polish fabricators exploit out-of-autoclave curing to undercut German autoclave-dependent production. Aviation clubs exhibit highest price sensitivity due to collective ownership capital constraints, while private Swiss and Austrian Open Class buyers prioritize performance over acquisition cost.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade prepreg dominates inventory strategy among Oberpfaffenhofen and Poppenhausen fabricators seeking insulation from Toray and Hexcel allocation volatility. Manufacturing concentration in Germany, Poland, and South Africa feeds from Japanese carbon fiber tow, German epoxy resin systems, and nitrogen-expanded structural core materials from Rohacell reformulation under EU F-Gas Regulation. Single-source vulnerability in Toray T800S supply exposes fabricators to defense sector demand spikes. Distribution runs through aeroclub procurement committees and flight school fleet managers rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refurbished 1990s-era Schleicher and Schempp-Hirth models trading at forty to sixty percent of new-build pricing threaten incumbent manufacturers with sustained demand absorption among budget-constrained clubs.
For Market Incumbents: Consolidate laminator craftsmanship pipelines through apprenticeship partnerships with Oberpfaffenhofen technical institutes before aging workforces retire. Deepen backward integration into REACH-compliant resin formulation to capture margin from ECHA regulatory compliance costs. Battery thermal runaway containment protocols and EASA Special Condition fast-discharge certification represent critical defensive moats against electric propulsion specialists. For New Entrants and Emerging Players: Predictive maintenance telemetry and residual value guarantee services expose an under-served layer where established manufacturers rely on historical reputation rather than data-driven fleet management. Polish and Czech aeroclubs expanding post-EU accession infrastructure present the most penetrable geography for mid-tier fiberglass production organization approvals. Partner with Warsaw and Krakow training centers on dual-seat electric self-launching demonstrations to bypass brand loyalty barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric propulsion integration as battery system validation and EASA Special Condition compliance elevate engineering costs beyond craftsmanship-dependent boutique scale. Acquisition targets should display composite-intensive production organization approvals combined with active flutter testing capabilities rather than heritage hand-layup expertise alone. Watch for Toray T800S allocation tightening as the signal indicating margin compression inflection across carbon fiber-dependent premium tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Certification | EASA Special Condition compliance unlocks self-launching premium positioning in Austrian and Swiss alpine markets. |
| Out-of-Autoclave Curing Adoption | Polish fabricators halve cure cycle duration to capture mid-tier club procurement from German autoclave bottlenecks. |
| REACH-Compliant Resin Integration | ECHA substance restriction alignment sustains production access for Oberpfaffenhofen and Poppenhausen facilities. |
| Predictive Maintenance Telemetry | Fifteen-year total-cost-of-ownership modeling displaces sticker-price negotiation in French and German aeroclub committees. |
| Polish Aeroclub Network Expansion | Post-2004 EU accession infrastructure investments activate latent capacity across Lesser Poland and Silesia. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EASA type certificate databases, aeroclub fleet registries, and composite materials trade flows. Primary interviews covered production organization quality managers at German manufacturing clusters, procurement committee chairs at French and Polish aeroclubs, and flight school operators in the Netherlands and Belgium. Secondary validation drew from EASA CS-22 amendment documentation, EU F-Gas Regulation implementation notices, and Toray and Hexcel aerospace-grade tow supply disclosures. Bottom-up club fleet renewal pipelines were triangulated against top-down carbon fiber consumption estimates across the sailplane industry.
Segmentation dimensions modeled span product type (Standard Class, 18m Class, Open Class, 15m Class), material construction (carbon fiber, fiberglass, aluminum, wood), use case (competitions, training, recreational flying, research), and end user (aviation clubs, flight schools, private owners, military). CAGRs were derived from aeroclub capital expenditure surveys and fleet replacement cycle analysis across the projection horizon. Industry-specific forecast inputs include FAI handicapping rule stability and electric propulsion battery energy density improvement curves.
Underlying assumptions cover EASA CS-22 certification timeline stability, Toray T800S supply allocation continuity, and EU F-Gas Regulation phase-down adherence, with deviation risk concentrated in defense sector carbon fiber demand spikes and battery thermal runaway protocol amendments. Revision becomes warranted when refurbished aircraft substitution rates cross thresholds that compress new-build pricing premiums below fifteen-year total-cost-of-ownership justification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Helicopter Wheels Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Air Starter Market
Aircraft
Aero Wing Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Strategic Bomber Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Military Rotorcraft Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Evtol Aircraft Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Aerospace Winglet System Market
Aircraft
Aircraft Elevator Market