
 North America and Europe Medical Foods Market | 2026-2036
North America and Europe Medical Foods Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Medical Foods Market Intelligence
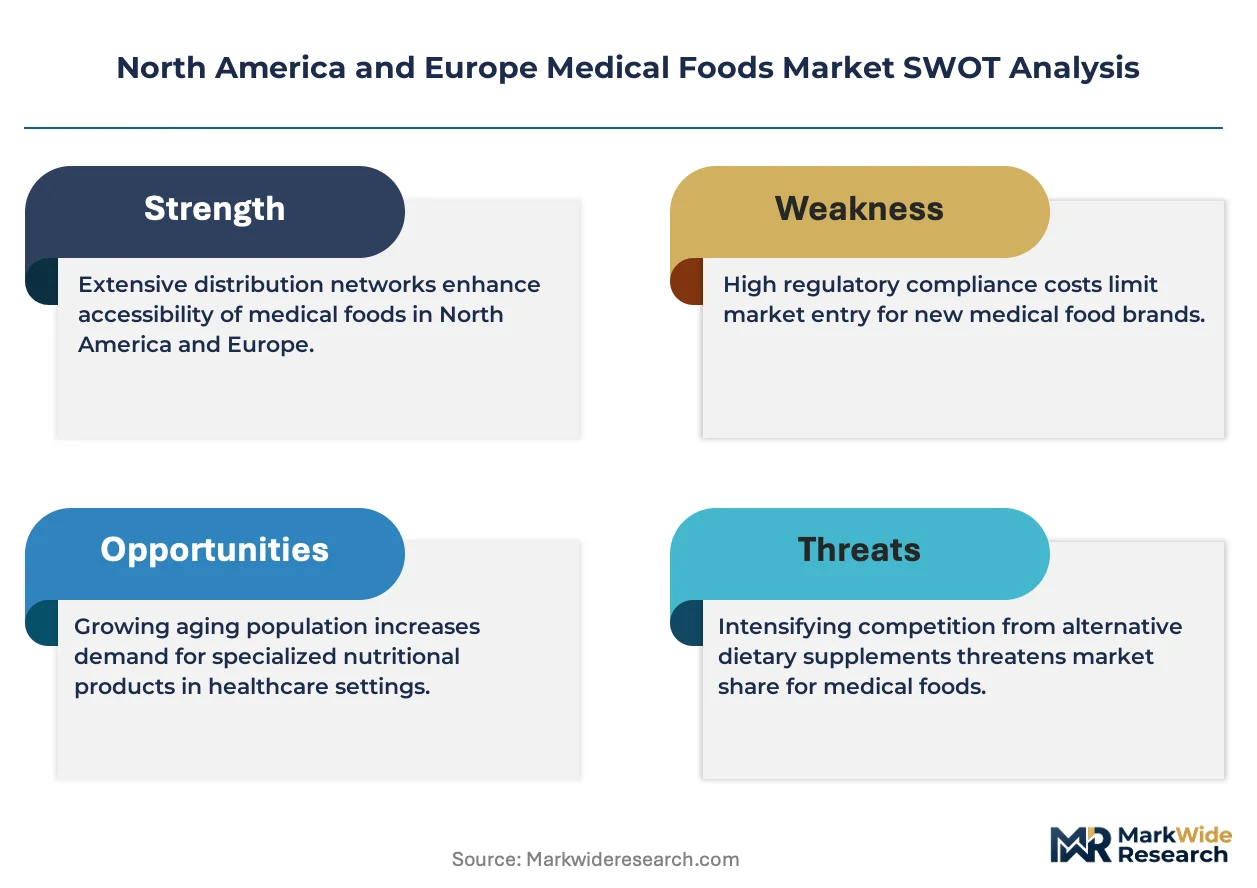
Plant-derived protein isolates are consolidating share from traditional dairy-based matrices in medical food formulations. Abbott leverages its enteral nutrition infrastructure to sustain hospital formulary dominance across the United States. Danone anchors European metabolic disorder portfolios through specialized formula pipelines. Nestle competes on pediatric rare-disease nutrition with tightly controlled distribution networks.
Medical foods constitute formulated nutritional products administered under physician supervision to manage disease-specific nutritional requirements, typically containing precise amino acid profiles, micronutrient densities, and caloric distributions manufactured through spray-drying or liquid emulsion processes. Their primary purpose is to address impaired nutrient absorption, metabolic pathway deficiencies, or elevated nutritional demands that standard diet cannot satisfy. Oral nutritional supplements capture the dominant revenue pool due to reimbursement alignment with outpatient care transitions, while specialized formulas for inherited metabolic disorders command premium positioning. Home healthcare end users represent the fastest-expanding channel as post-acute care shifts away from institutional settings.
The FDA exercises oversight through its medical food enforcement discretion policy, while the European Food Safety Authority evaluates health claims under the Nutrition and Health Claims Regulation, and Germany's Federal Institute for Drugs and Medical Devices maintains stringent compositional standards for reimbursable products. These frameworks elevate barriers for new entrants lacking clinical trial infrastructure or pharmacovigilance capabilities. Stakeholders must monitor evolving reimbursement parity between medical foods and prescription therapeutics as payers reassess coverage categories.
Market Dynamics
Home healthcare providers are accelerating medical food prescribing as post-acute care transitions away from institutional settings, reshaping distribution infrastructure and reimbursement negotiations across both continents.
Growth Catalysts
- FDA orphan drug pathway overlap:The FDA's guidance convergence with rare-disease frameworks streamlines development timelines for metabolic disorder formulations in the United States.
- Germany's clinical nutrition corridor:Concentrated prescribing networks in Bavaria and North Rhine-Westphalia generate demand density for reimbursable specialized formulas.
- Spray-drying process advances:Precision amino acid encapsulation technologies improve bioavailability profiles for inherited metabolic condition patients.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings compress margin predictability for traditional formulation suppliers.
- EFSA health claim substantiation:The European Food Safety Authority's evidentiary requirements extend approval timelines for novel medical food indications.
- Hospital formulary concentration:United States institutional procurement consolidation limits access for smaller manufacturers lacking Abbott-scale enteral infrastructure.
Strategic Opportunities
- Poland's underpenetrated metabolic clinics:Eastern European reimbursement harmonization creates first-mover positioning for rare-disease nutrition portfolios.
- Plant-derived protein convergence:Pea and rice isolate blending with precision fermentation outputs enables dairy-free premium positioning.
- Remote patient monitoring integration:Telehealth platforms in the United States are embedding medical food adherence tracking into chronic care workflows.
Industry Challenges
- Clinical nutritionist certification bottlenecks:Specialized metabolic dietitian training programs in France and Italy produce insufficient prescriber capacity.
- Pharmacovigilance system integration:Medical food adverse event reporting requirements diverge from pharmaceutical standards, complicating compliance architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Medical Foods Market |
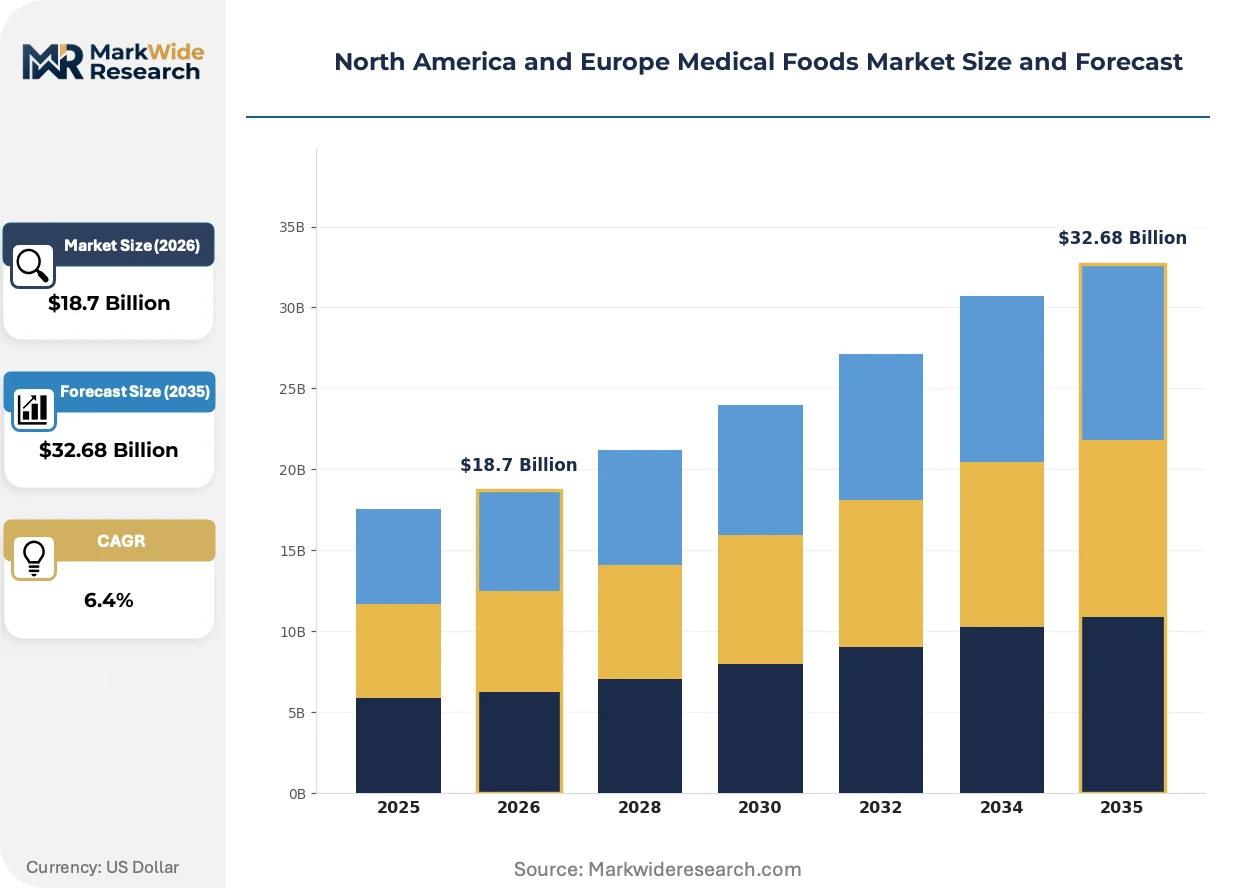
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Nutrition Drinks, Nutritional Supplements, Protein Powders, Specialized Formulas, Oral Nutritional Supplements Application: Metabolic Disorders, Gastrointestinal Conditions, Neurological Disorders, Immune Modulation, Cardiovascular Health End User: Hospitals, Home Healthcare, Long-Term Care Facilities, Rehabilitation Centers, Specialized Clinics Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Direct Sales, Healthcare Providers |
| Companies Covered | Abbott, Nestle, Danone, Fresenius Kabi AG, Mead Johnson & Company, LLC, Targeted Medical Pharma, Inc., Primus Pharmaceuticals, Inc., Medtrition, Inc., Baxter International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Medical Foods Market Strategic Shifts & Innovations
Formulation science and reimbursement architecture are evolving in parallel, with protein source diversification and regulatory precision defining competitive differentiation across the North American and European medical foods landscape.
Precision fermentation-derived protein isolates are consolidating share from traditional dairy-based matrices in medical food formulations. Pediatric metabolic disorder clinics in Germany and the Netherlands are adopting these alternatives at accelerated pace. This shift is consolidating premium positioning for manufacturers with microbial production capabilities while compressing commodity whey dependence.
The EU's evolving FSGP framework is tightening compositional substantiation requirements for specialized nutrition products. German BfArM standards are propagating across member states, elevating clinical trial burdens. Inherited metabolic disorder formulas face the steepest compliance ramps, with manufacturers restructuring pharmacovigilance operations to maintain market access.
Home healthcare prescribing is displacing hospital-centric distribution for stable chronic conditions. United States Medicare Advantage plans and United Kingdom integrated care systems are reimbursing domiciliary medical food delivery. This pattern is most visible in geriatric rehabilitation corridors across Florida, Arizona, and Spain's Mediterranean coast.
North America and Europe Medical Foods Market Segmentation
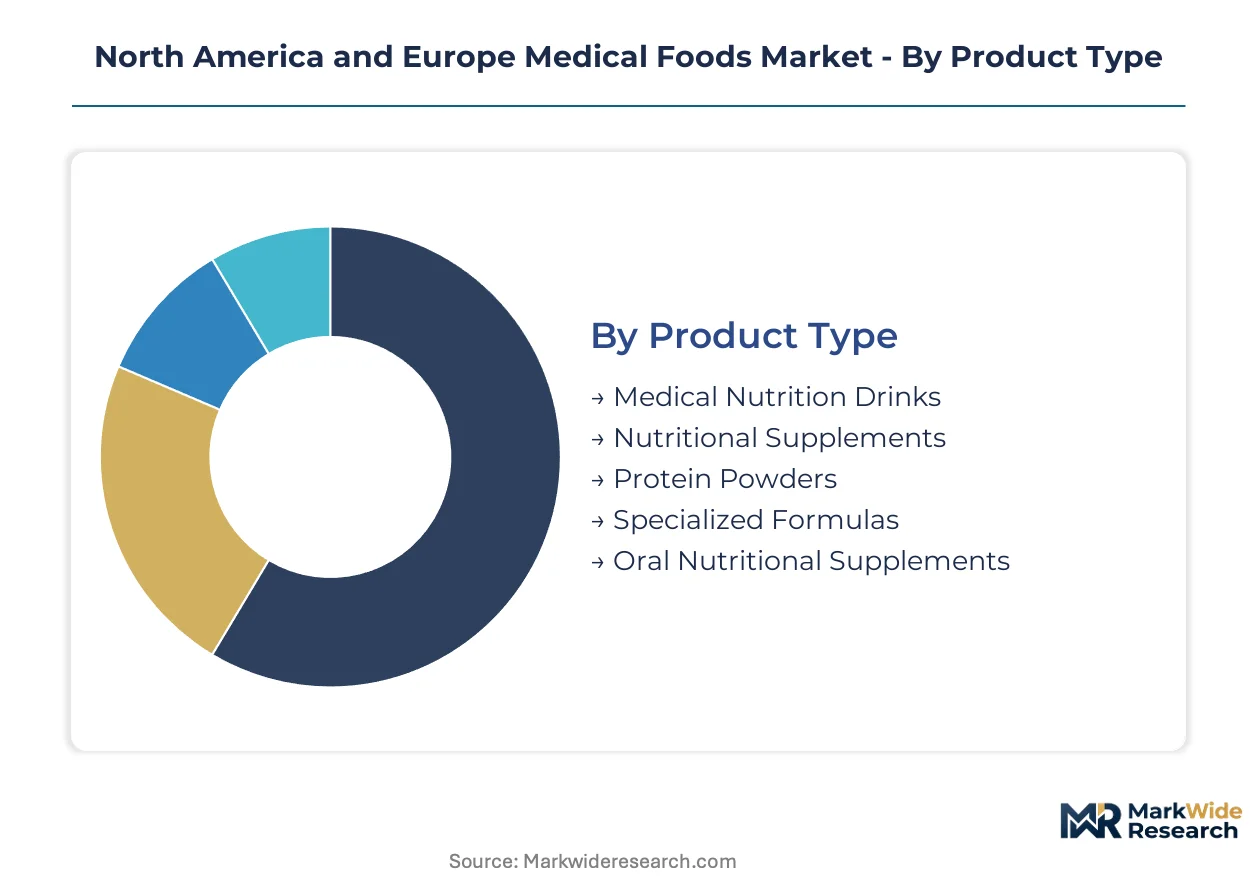
Medical foods demand fragments across formulation types, disease indications, and care settings. Each segment carries distinct reimbursement codes, prescriber relationships, and manufacturing requirements. Understanding these divides reveals where margin pools concentrate and where channel control matters most.
Product Type:
Customization intensity varies from commodity protein isolates to precision amino acid matrices engineered for single-gene disorders.
- Specialized Formulas:Engineered amino acid profiles address phenylketonuria, maple syrup urine disease, and urea cycle defects. German metabolic clinics and US pediatric genetic centers drive concentrated prescribing. FDA orphan drug pathway convergence accelerates development timelines for rare-disease indications.
- Oral Nutritional Supplements:Standardized macronutrient compositions target malnutrition in geriatric and post-surgical populations. Medicare Advantage plans in Florida and Arizona rehabilitate patients through domiciliary delivery programs. Reimbursement alignment with outpatient care transitions sustains volume leadership.
- Medical Nutrition Drinks:Liquid emulsion formulations with defined caloric densities for dysphagia and critical care recovery.
- Nutritional Supplements:Micronutrient-dense tablets and capsules bridging dietary gaps in oncology and chronic kidney disease.
- Protein Powders:Plant-derived isolates from pea and rice gaining share in dairy-intolerant patient populations.
Leading the category by volume: Oral Nutritional Supplements. Growing fastest: Specialized Formulas.
Application:
Disease-specific nutritional requirements span enzymatic deficiencies, inflammatory pathologies, and neurodegenerative protein metabolism disruptions.
- Metabolic Disorders:Inherited enzyme deficiencies demand lifelong amino acid-modified nutrition. Bavaria's clinical nutrition corridor and US academic medical centers concentrate prescriber expertise. EFSA health claim substantiation requirements extend approval timelines for novel indications.
- Gastrointestinal Conditions:Elemental and semi-elemental formulas bypass compromised absorption in Crohn's disease and short bowel syndrome. Home healthcare providers in Spain's Mediterranean coast and UK integrated care systems displace hospital-centric distribution.
- Neurological Disorders:Ketogenic and medium-chain triglyceride formulations for epilepsy and Alzheimer's disease management.
- Immune Modulation:Immunonutrition with arginine, omega-3 fatty acids, and nucleotides for surgical and trauma recovery.
- Cardiovascular Health:Sodium-restricted and lipid-modified formulas supporting heart failure and post-MI rehabilitation protocols.
Dominant by revenue: Metabolic Disorders. Steepest expansion trajectory: Gastrointestinal Conditions.
End User:
Care setting determines reimbursement pathway, with institutional procurement consolidating against fragmented home healthcare prescribing.
- Home Healthcare:Post-acute transitions drive fastest channel expansion across United States Medicare Advantage and UK domiciliary care programs. Remote patient monitoring platforms embed adherence tracking into chronic care workflows. Telehealth prescribing reduces dependency on hospital formulary gatekeepers.
- Hospitals:Enteral nutrition infrastructure dominates acute care procurement through Abbott-scale distribution networks. United States institutional consolidation limits access for smaller manufacturers lacking formulary relationships.
- Long-Term Care Facilities:Skilled nursing facilities managing protein-energy malnutrition in frail elderly populations.
- Rehabilitation Centers:Post-stroke and orthopedic recovery programs requiring texture-modified and hypercaloric nutrition.
- Specialized Clinics:Metabolic genetics, gastroenterology, and neurology practices with prescriber certification requirements.
Largest volume channel: Hospitals. Fastest-expanding: Home Healthcare.
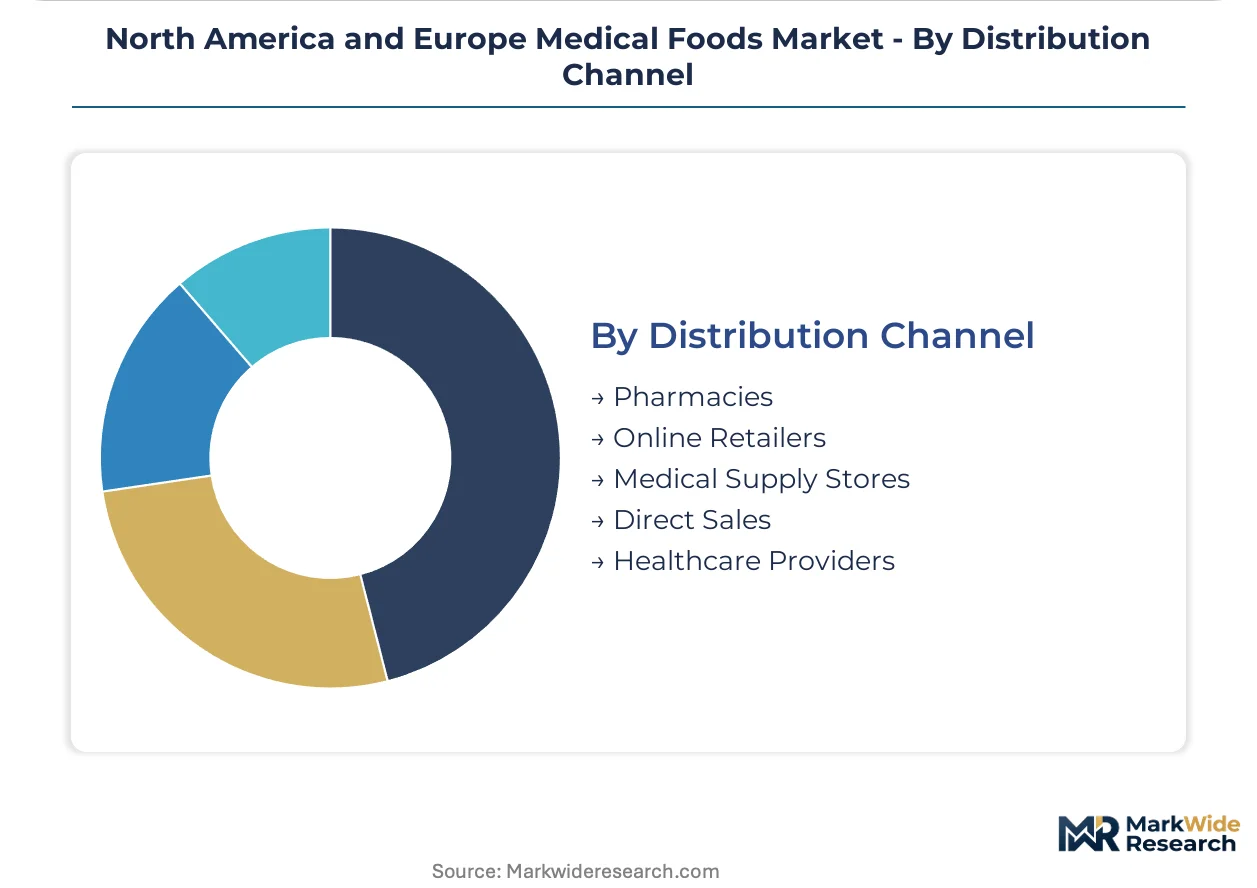
Distribution Channel:
Channel control separates pharmacy-reimbursed medical foods from cash-pay wellness products, with digital platforms eroding traditional gatekeeper roles.
- Healthcare Providers:Physician-supervised dispensing anchors reimbursement integrity for metabolic disorder formulations. Direct prescriber relationships in Germany's North Rhine-Westphalia corridor sustain premium positioning. Clinical nutritionist certification bottlenecks in France and Italy constrain prescriber capacity expansion.
- Pharmacies:Community and hospital pharmacies process insurance claims for reimbursable specialized nutrition. Poland's underpenetrated metabolic clinics present first-mover opportunities for rare-disease portfolio distribution.
- Online Retailers:Direct-to-patient platforms expanding in stable chronic conditions with established prescribing protocols.
- Medical Supply Stores:Durable medical equipment channels for enteral feeding pumps and associated formula delivery.
- Direct Sales:Manufacturer field forces targeting metabolic genetics clinics and specialized dietitian networks.
Highest volume pathway: Healthcare Providers. Gaining share fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Free State of Bavaria hosts Europe's densest cluster of metabolic genetics clinics, concentrating prescriber expertise and specialized formula reimbursement pathways that draw manufacturers into the clinical nutrition corridor.
United States
Medicare Advantage plans in Florida and Arizona rehabilitate geriatric patients through domiciliary medical food delivery programs. The FDA maintains enforcement discretion over medical food classification while overlapping with orphan drug pathways for rare-disease formulations. Boston's academic medical centers anchor pediatric metabolic disorder prescribing networks.
Germany
Bavaria and North Rhine-Westphalia generate concentrated demand density for reimbursable specialized formulas through integrated metabolic clinic networks. The Federal Institute for Drugs and Medical Devices enforces stringent compositional standards that propagate across EU member states. Heidelberg's university hospital corridor trains certified clinical nutritionists at insufficient rates.
United Kingdom
Integrated care systems in England displace hospital-centric distribution with domiciliary medical food reimbursement for stable chronic conditions. The National Health Service evaluates specialized nutrition through NICE technology appraisals. London's metabolic genetics centers concentrate prescriber capacity for inherited enzyme deficiencies.
Netherlands
Pediatric metabolic disorder clinics in Rotterdam and Amsterdam accelerate adoption of precision fermentation-derived protein isolates. The Dutch Healthcare Authority negotiates reimbursement rates for specialized nutrition alongside pharmaceutical therapeutics. Utrecht's university medical center anchors national dietitian certification programs.
Spain
Mediterranean coast home healthcare providers expand medical food prescribing for post-surgical and geriatric rehabilitation patients. The Spanish Agency for Medicines and Health Products aligns specialized nutrition oversight with EU FSGP framework evolution. Barcelona's hospital networks consolidate enteral nutrition procurement.
North America and Europe Medical Foods Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with hospital formulary gatekeepers consolidating procurement around established enteral infrastructure while home healthcare channels fragment access. The vendor base organizes into three strategic archetypes: diversified nutrition conglomerates with pediatric rare-disease portfolios, enteral feeding specialists leveraging acute care distribution networks, and metabolic disorder pure-plays targeting certified prescriber relationships. Dominant competitive moves include backward integration into precision fermentation protein production and strategic partnerships with telehealth platforms embedding adherence tracking.
Among diversified nutrition conglomerates, Abbott and Nestle occupy positions reflecting contrasting geographic emphases, with the former anchoring United States hospital formulary relationships and the latter concentrating European metabolic disorder portfolios. Danone sits within the specialized formula tier, exemplifying premium positioning through rare-disease pipeline depth. These three entities represent the structural division between acute care infrastructure dependence and certified prescriber channel control.
| Leading Market Players |
|---|
| Abbott |
| Nestle |
| Danone |
| Fresenius Kabi AG |
| Mead Johnson & Company, LLC |
| Targeted Medical Pharma, Inc. |
| Primus Pharmaceuticals, Inc. |
| Medtrition, Inc. |
| Baxter International |
| Others |
Cost & Logistics Intelligence
Specialized formula certification tiers bifurcate the North America and Europe medical foods landscape into premium reimbursed channels and cash-pay commodity segments, with FDA orphan drug pathway alignment and German BfArM compositional standards elevating clinical trial costs that concentrate pricing power among incumbents while compressing margins for undifferentiated oral nutritional supplements.
Pricing Analysis
Volume leadership in oral nutritional supplements trades against margin concentration in specialized metabolic disorder formulas, with Medicare Advantage reimbursement codes and German statutory health insurance frameworks anchoring premium positioning for certified products. Price differentiation rests on clinical trial substantiation depth and prescriber certification requirements rather than commodity protein input costs. Pricing pressure intensifies in standard enteral nutrition as hospital formulary consolidation favors Abbott-scale suppliers with captive distribution infrastructure. Home healthcare channels exhibit lowest price sensitivity due to adherence-linked outcomes contracting, while long-term care facilities face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Germany's North Rhine-Westphalia corridor and Florida's geriatric rehabilitation belt operate hub-and-spoke patterns for temperature-controlled medical food logistics. Manufacturing concentrates in Germany, the Netherlands, and the United States, with spray-drying facilities clustered near academic medical centers for clinical trial coordination. Raw material dependencies include whey protein concentrates from dairy cooperatives, precision fermentation-derived isolates from microbial production platforms, and amino acid matrices from pharmaceutical-grade chemical suppliers. Single-source vulnerability in peptide encapsulation technologies elevates risk exposure. Distribution runs through healthcare provider direct dispensing for metabolic disorders and pharmacy networks for stable chronic conditions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in certified clinical nutritionist training programs prop pricing power for manufacturers with established prescriber relationships, as insufficient dietitian pipeline capacity in France and Italy bottlenecks competitive entry.
For Market Incumbents: Cement formulary dominance through backward integration into precision fermentation protein production, capturing margin from dairy commodity volatility while securing microbial isolate supply for pediatric metabolic disorder portfolios. Expand telehealth platform partnerships to embed adherence tracking into Medicare Advantage workflows, preempting channel displacement by digital-native entrants. Prioritize pharmacovigilance system upgrades ahead of EU FSGP framework tightening to maintain German reimbursement eligibility. For New Entrants and Emerging Players: Precision fermentation-derived protein technologies offer wedge positioning in dairy-free specialized formulas, with Poland's underpenetrated metabolic clinics presenting lowest competitive density for rare-disease portfolio establishment. Target gastrointestinal condition applications where home healthcare displacement of hospital distribution has fragmented incumbent channel control. Pursue direct-to-patient digital platforms with remote monitoring integration to bypass formulary gatekeeper consolidation. For Investors and Strategic Acquirers: Re-rating potential sits with metabolic disorder pure-plays given FDA orphan drug pathway convergence accelerating development timelines and compressing regulatory risk premiums. Long-term viability hinges on reimbursement parity maintenance between medical foods and pharmaceutical therapeutics across the analysis window. Monitor EFSA health claim substantiation backlog as inflection indicator for European approval velocity and portfolio monetization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Captive microbial protein supply secures margin insulation from dairy commodity swings for German metabolic clinics. |
| Telehealth Platform Partnership | Adherence tracking integration into Florida Medicare Advantage workflows displaces hospital-centric distribution. |
| Clinical Nutritionist Certification Program | Proprietary training pipelines in France and Italy alleviate prescriber bottlenecks constraining market expansion. |
| EU FSGP Compliance Infrastructure | Pharmacovigilance system upgrades preserve German BfArM reimbursement eligibility for inherited disorder formulas. |
| Poland Distribution Network Establishment | First-mover positioning in underpenetrated metabolic clinics captures Eastern European reimbursement harmonization benefits. |
Research Approach
Multi-period observation of FDA medical food enforcement discretion policy evolution, German BfArM reimbursement code modifications, and Medicare Advantage domiciliary care expansion anchored the trend analysis, supplemented by interviews with metabolic genetics clinicians, hospital formulary directors, specialized dietitian network coordinators, and home healthcare procurement managers. Secondary validation drew from FDA orphan drug pathway guidance documents, EFSA health claim substantiation databases, German statutory health insurance reimbursement catalogs, and CMS Medicare Advantage plan benefit filings. Bottom-up prescribing volume estimates triangulated against top-down manufacturer revenue allocations.
Segment-weighting approaches modeled product type fragmentation across specialized formulas, oral nutritional supplements, and medical nutrition drinks, cross-referenced against application dimensions spanning metabolic disorders, gastrointestinal conditions, and neurological indications. End-user channel splits between home healthcare, hospitals, and long-term care facilities informed distribution pathway assumptions. CAGRs were derived from prescribing volume trajectories indexed to reimbursement policy shifts and prescriber certification pipeline constraints. Forecast inputs incorporated spray-drying process yield improvements and precision fermentation protein isolate adoption curves.
Several conditions sit outside the modeled scope, including speculative regulatory reclassification of medical foods as pharmaceuticals, catastrophic dairy commodity supply disruptions, and pandemic-scale clinical trial suspension events. Forecasts reflect assumptions regarding reimbursement parity maintenance and prescriber training program expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Essential Fatty Acids Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Vegan DHA Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Brominated Vegetable Oil Market