
 Rubber Block Market | 2026-2036
Rubber Block Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Block Market Outlook
Advanced compounding with silica-reinforced formulations is reshaping durability specifications across industrial rubber block applications. ExxonMobil leverages its integrated polybutadiene supply chain to serve high-load bearing segments in North American construction markets. Kumho Petrochemical anchors synthetic rubber block production through its South Korean petrochemical complexes, while Sri Trang Agro-Industry dominates natural rubber sourcing from Thai plantation networks into block processing facilities.
Rubber blocks are molded or extruded elastomeric solids, typically formulated from natural polyisoprene or synthetic styrene-butadiene compounds with Shore A hardness ratings between 40 and 90, engineered to absorb mechanical shock, dampen vibration, or create resilient load-bearing interfaces in industrial equipment and building systems. Natural rubber blocks command premium positioning in heavy-duty vibration dampening for manufacturing machinery due to superior tensile strength and elastic recovery, while recycled rubber blocks from post-consumer tire feedstock capture volume share in cost-sensitive construction flooring applications where performance tolerances permit lower purity grades. Synthetic rubber blocks, particularly those derived from nitrile and EPDM polymers, concentrate margin pools in automotive sealant and insulation channels requiring oil resistance and thermal stability beyond natural rubber capabilities.
REACH registration requirements administered by ECHA mandate full substance disclosure for imported synthetic rubber blocks entering European manufacturing supply chains, while EPA Toxic Substances Control Act reporting governs pre-manufacture notification for novel rubber compounds in United States industrial distribution. China's SAMR enforces GB standards on rubber block compression set and aging resistance for domestic construction and automotive certification. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across these jurisdictions, as regulatory timelines for fluorinated processing aid phase-outs will force reformulation decisions in specialty synthetic rubber block grades within the next compliance cycle.
Market Dynamics
REACH compliance deadlines and GB standard revisions are forcing simultaneous reformulation of synthetic rubber compounds across European and Chinese manufacturing supply chains, compressing product development timelines while opening specification windows for compliant alternatives.
Growth Catalysts
- Electric vehicle battery isolation systems:Automotive manufacturers in Germany and Japan are expanding rubber block procurement for thermal management and vibration dampening in high-density battery packs. This application demands Shore A hardness ratings above 70 with sustained performance at elevated operating temperatures.
- Southeast Asian processing concentration:Thailand and Indonesia process raw natural rubber into block form for export, creating integrated feedstock-to-block supply efficiencies that lower landed costs for tire producers in consuming markets.
- Silica-reinforced compounding:Advanced formulations with precipitated silica are extending service life in industrial load-bearing applications, enabling specification upgrades in heavy machinery and construction equipment channels.
Market Restraints
- Natural rubber price volatility:Hevea brasiliensis latex prices fluctuate with monsoon patterns and plantation labor availability in Thai and Indonesian sourcing regions, compressing margins for block processors without forward contracting capabilities.
- EPDM supply concentration:Ethylene-propylene-diene monomer rubber block production clusters in South Korean and Saudi petrochemical complexes, creating single-source dependency risks for automotive sealant manufacturers requiring oil-resistant grades.
- Recycled feedstock quality inconsistency:Post-consumer tire crumb rubber exhibits variable Shore A hardness and compression set performance, limiting adoption in precision vibration isolation applications where specification tolerance is narrow.
Strategic Opportunities
- Indian industrial infrastructure buildout:Domestic construction machinery and material handling equipment production is expanding in Gujarat and Tamil Nadu manufacturing corridors, creating localized demand for natural rubber block vibration dampening solutions.
- Per- and polyfluoroalkyl substance phase-out:ECHA regulatory timelines for fluorinated processing aid restrictions will force reformulation decisions in specialty synthetic grades, opening specification windows for bio-based processing alternatives.
- Digital procurement platforms:Industrial distributors are deploying B2B marketplaces with real-time Shore A hardness and compression set data transparency, compressing buyer search costs and enabling direct mill-to-factory relationships outside traditional channel structures.
Industry Challenges
- Compound formulation expertise scarcity:Rubber technologists with cross-training in polymer science and automotive thermal management specifications are concentrated at legacy tire manufacturers, limiting formulation innovation at mid-scale block processors.
- Compression set certification timelines:GB standard testing protocols for aging resistance require 168-hour heat exposure cycles, extending product qualification periods for Chinese construction certification and delaying revenue recognition on new compound introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Block Market |
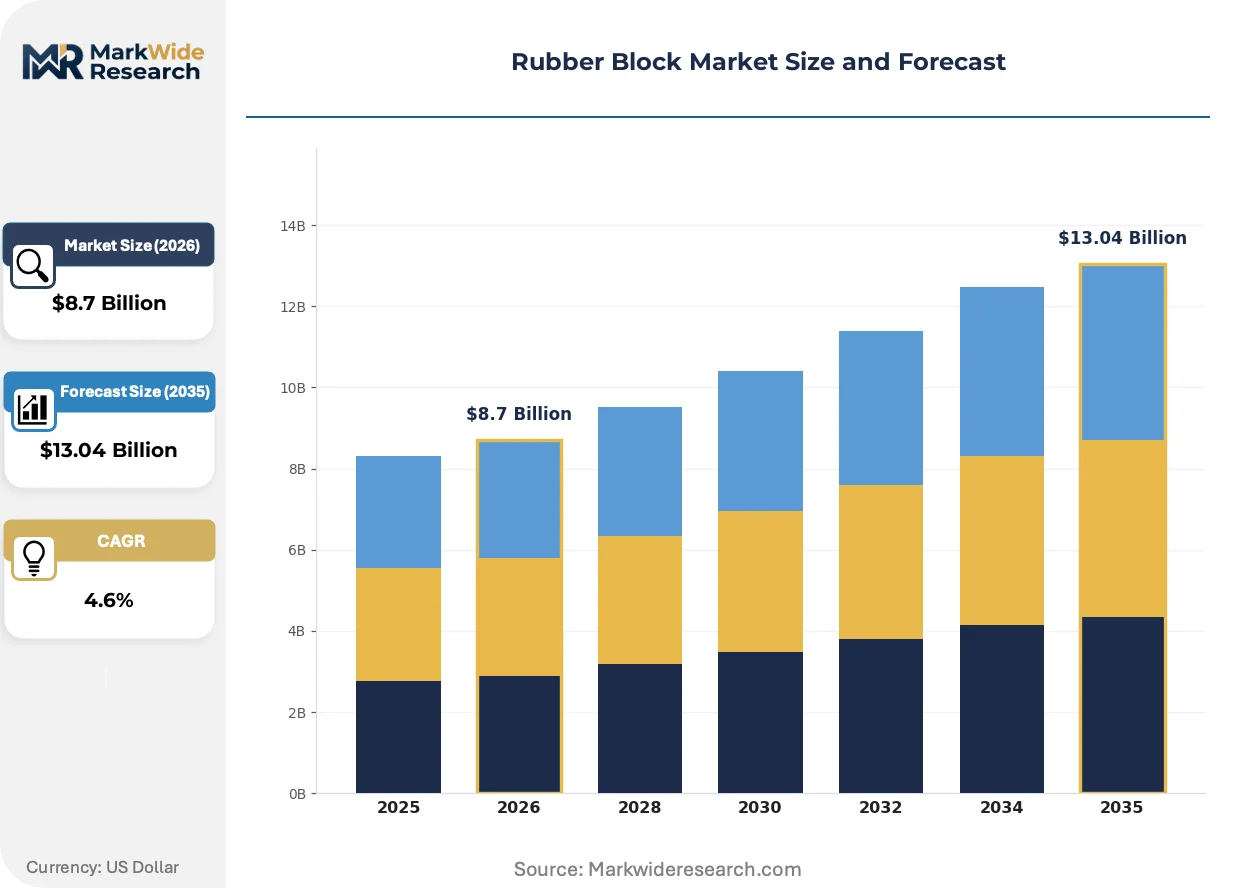
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
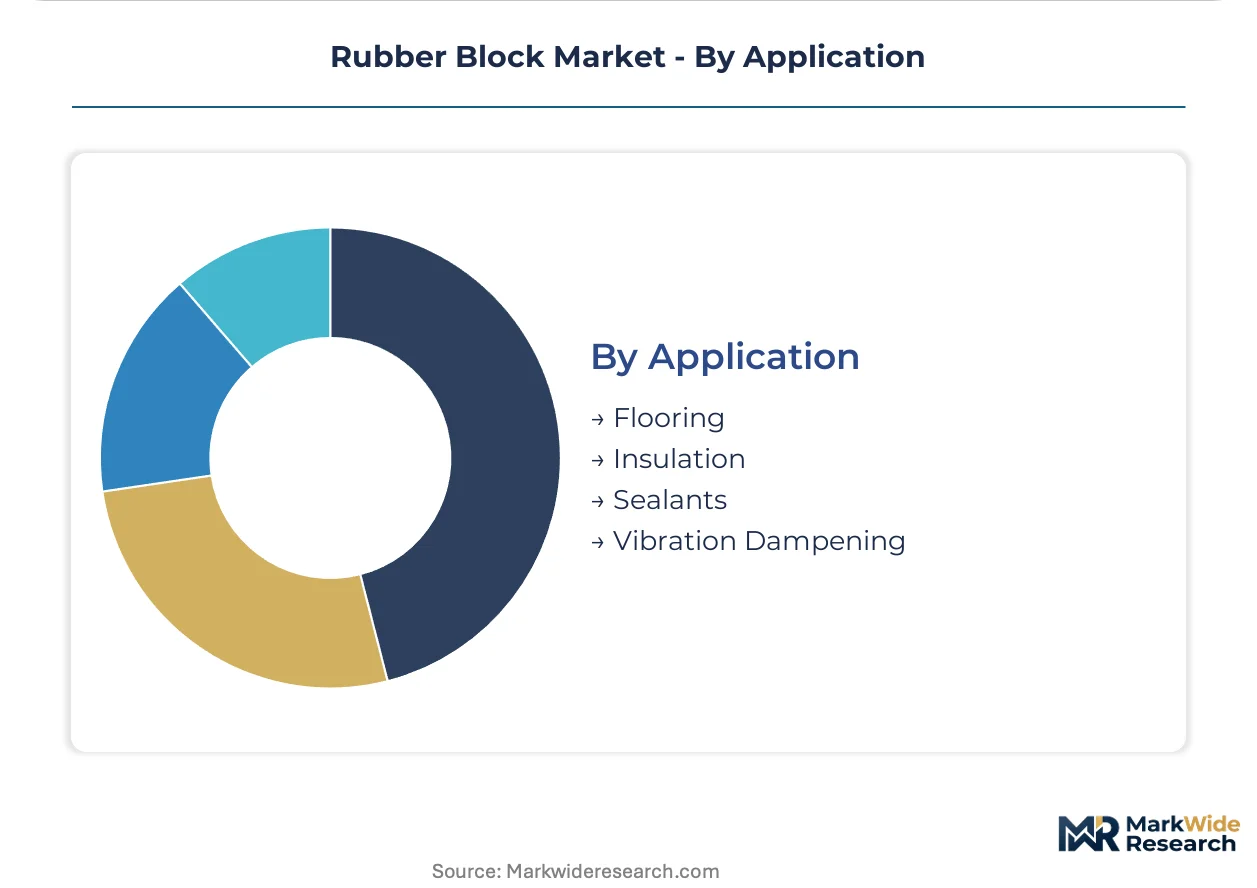
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Recycled Rubber, Foam Rubber End User: Construction, Automotive, Manufacturing, Sports Form: Solid, Liquid, Granular, Sheet Application: Flooring, Insulation, Sealants, Vibration Dampening |
| Companies Covered | ExxonMobil Corporation, ARLANXEO, Synthos, Kumho Petrochemical, Sinopec, Dow, JSR Corporation, Sri Trang Agro-Industry, Southland Holding Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Block Market Strategic Shifts
Compound intelligence systems and automated Shore A hardness testing are digitizing quality assurance workflows across rubber block manufacturing, compressing specification deviation detection from batch-level to continuous monitoring.
Machine vision inspection coupled with laser profilometry is digitizing surface defect detection in extruded rubber block production lines. Tier-1 automotive suppliers in Stuttgart and Nagoya manufacturing clusters are adopting these systems at pilot scale. The technology is digitizing quality documentation for REACH substance disclosure requirements, reducing manual inspection labor while tightening dimensional tolerance bands.
EPA Toxic Substances Control Act pre-manufacture notification requirements are tightening disclosure thresholds for novel nitrile rubber copolymers entering US industrial distribution. Compounders must submit full substance identity and exposure data before commercial introduction. Specialty synthetic block grades with modified acrylonitrile content are most affected, with formulators accelerating existing compound registrations to precede enforcement phase-in.
Buyer consolidation among North American construction equipment OEMs is compressing supplier qualification cycles and unbundling after-sales technical service from material supply contracts. Procurement teams at Caterpillar and Deere manufacturing divisions now demand standalone compound performance guarantees with penalty clauses for Shore A hardness drift. This pattern is most visible in Illinois and Iowa manufacturing corridors where centralized sourcing functions have displaced regional distributor relationships.
Rubber Block Market Segmentation
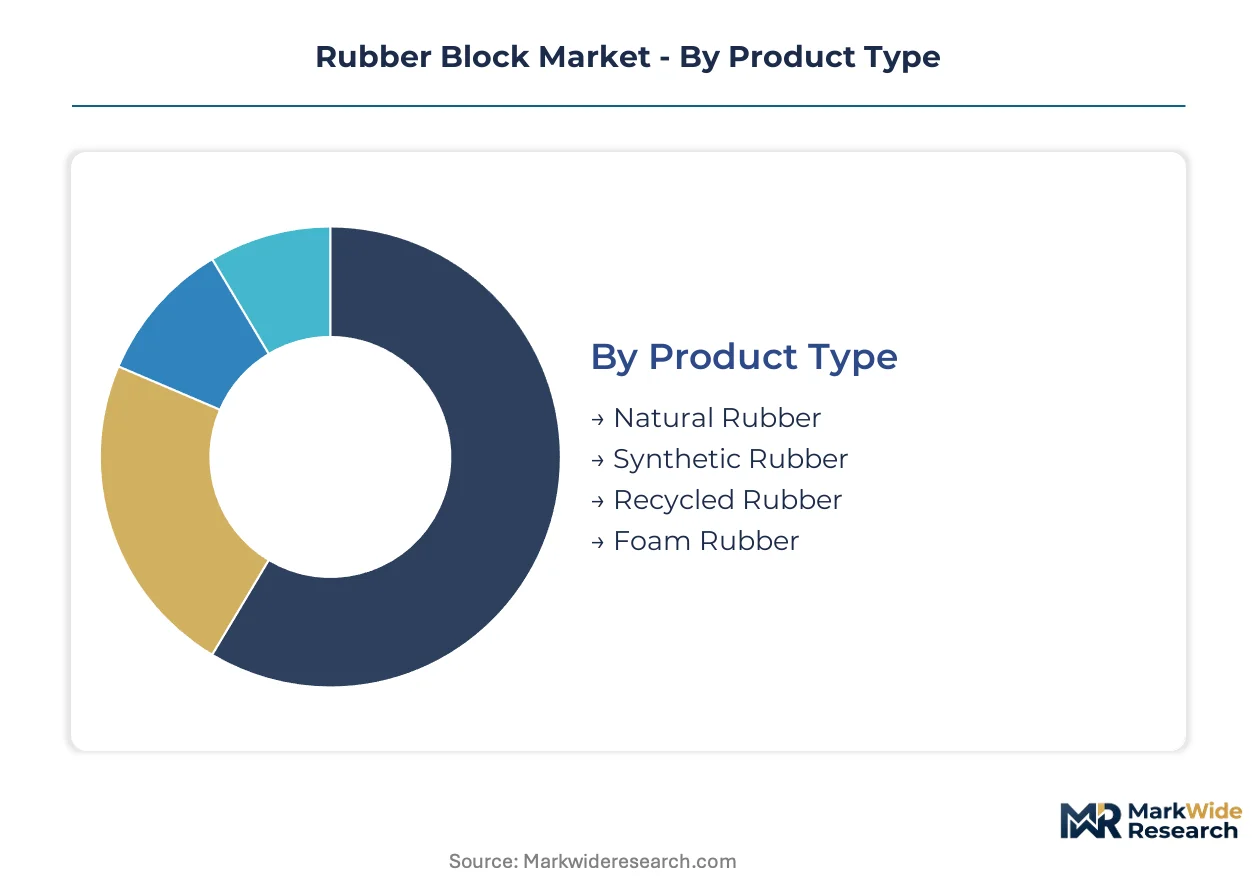
Rubber block procurement patterns diverge sharply across product chemistry, end-use specifications, and physical form factors. Technical service intensity varies by segment, with automotive and industrial buyers demanding compound customization support that commodity construction channels rarely require.
Product Type:
After-sales technical service intensity peaks with synthetic rubber blocks, where compounders must troubleshoot Shore A hardness drift and compression set failures in the field.
- Synthetic Rubber:Nitrile and EPDM polymer blocks deliver oil resistance and thermal stability for automotive sealant channels. German and Japanese EV battery manufacturers specify these grades for isolation systems operating above 70 Shore A hardness at elevated temperatures.
- Natural Rubber:Polyisoprene formulations with superior tensile strength and elastic recovery dominate heavy-duty vibration dampening for manufacturing machinery. Thai and Indonesian plantation-to-block supply chains concentrate feedstock sourcing for this premium positioning.
- Recycled Rubber:Post-consumer tire crumb blocks serve cost-sensitive construction flooring where lower purity grades meet performance tolerances.
- Foam Rubber:Cellular elastomer structures provide lightweight cushioning and acoustic absorption in building systems and transport interiors.
By volume, natural rubber leads due to established tire industry demand. By growth pace, synthetic rubber is climbing the fastest on EV thermal management requirements.
End User:
Cost tier stratification separates specification-intensive automotive and manufacturing buyers from price-elastic construction and sports segments.
- Automotive:Battery isolation systems and underhood sealants demand REACH-compliant synthetic compounds with documented substance disclosure. Stuttgart and Nagoya manufacturing clusters drive procurement for thermal-stable grades.
- Manufacturing:Vibration dampening for heavy machinery requires natural rubber blocks with certified compression set performance under GB standard testing protocols.
- Construction:Load-bearing pads and flooring applications absorb volume share of recycled rubber blocks where Shore A tolerance bands are wider.
- Sports:Playground surfacing and athletic matting utilize foam and recycled rubber for impact absorption at lower price points.
By volume, construction leads through infrastructure buildout. By growth pace, automotive is gaining share fastest on electrification trends.
Form:
Supply concentration around extrusion and molding capabilities favors solid block production, while liquid and granular forms serve specialized compounding niches.
- Solid:Molded or extruded elastomeric blocks constitute the standard delivery format for industrial load-bearing and vibration isolation. South Korean petrochemical complexes anchor synthetic solid block capacity.
- Sheet:Continuous rolled forms enable fabrication of gaskets, pads, and custom shapes for OEM equipment channels.
- Liquid:Uncured rubber compounds support in-situ casting and repair applications where block dimensions must match existing infrastructure.
- Granular:Crumb rubber feedstock supplies playground surfacing and molded product manufacturers with intermediate processing material.
By volume, solid blocks dominate industrial procurement. By growth pace, sheet forms are expanding most quickly on gasket fabrication demand.
Application:
Margin pools concentrate in specification-critical insulation and sealant channels, while flooring and vibration dampening compete on scale economies.
- Vibration Dampening:Natural rubber blocks with Shore A 70-90 ratings isolate manufacturing machinery and heavy equipment. Gujarat and Tamil Nadu industrial corridors in India are emerging demand centers for these solutions.
- Sealants:EPDM and nitrile synthetic blocks provide oil-resistant sealing for automotive and industrial fluid systems. EPA TSCA pre-manufacture notification requirements govern novel copolymer introductions in US distribution.
- Flooring:Recycled rubber blocks and sheets serve commercial and residential construction with cost-driven material selection.
- Insulation:Thermal and acoustic barrier applications in building systems and transport equipment utilize foam rubber and specialized synthetic compounds.
By volume, flooring leads through construction sector absorption. By growth pace, vibration dampening shows the steepest expansion trajectory on industrial infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai plantation networks feed natural rubber block exports to tire manufacturers in Germany and Japan, while South Korean petrochemical complexes anchor synthetic rubber block supply for North American construction markets.
Germany
Stuttgart manufacturing clusters drive procurement of high-Shore-A synthetic rubber blocks for electric vehicle battery isolation systems. ECHA REACH registration requirements mandate full substance disclosure for imported compounds entering European supply chains. Bavarian automotive suppliers are expanding technical service capabilities to troubleshoot compression set performance in thermal management applications.
China
SAMR-enforced GB standards on compression set and aging resistance govern domestic construction and automotive certification timelines. Provincial industrial corridors in Jiangsu and Zhejiang process imported natural rubber feedstock into block form for domestic tire manufacturers. Shanghai-based compounders are accelerating reformulation schedules to meet volatile organic compound limits on synthetic rubber grades.
United States
EPA Toxic Substances Control Act pre-manufacture notification requirements tighten disclosure thresholds for novel nitrile rubber copolymers entering industrial distribution. Illinois and Iowa manufacturing corridors host centralized sourcing functions at construction equipment OEMs demanding standalone compound performance guarantees. Midwestern distributors are deploying B2B procurement platforms with real-time Shore A hardness data transparency.
Thailand
Sri Trang Agro-Industry plantation networks dominate natural rubber sourcing into block processing facilities for export to consuming markets. Monsoon-driven latex price volatility compresses margins for processors lacking forward contracting capabilities. Bangkok-region processing clusters supply premium-grade natural rubber blocks to German automotive and Japanese industrial machinery channels.
Japan
Nagoya manufacturing clusters specify REACH-compliant synthetic rubber blocks with documented thermal stability for underhood sealant applications. METI industrial standards guide compound qualification protocols for domestic automotive certification. Osaka-based tire manufacturers are expanding procurement of Thai-sourced natural rubber blocks for heavy-duty vibration dampening solutions.
Rubber Block Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into petrochemical-integrated synthetic rubber producers, plantation-linked natural rubber processors, and regional compounding specialists serving construction and industrial niches. Three strategic archetypes dominate: upstream-integrated feedstock controllers, specification-driven automotive compounders, and cost-optimized recycled rubber processors. Capacity expansion in Southeast Asian natural rubber processing and backward integration into plantation networks represent the dominant competitive moves reshaping supply-side positioning.
Among petrochemical-integrated synthetic rubber producers, ExxonMobil Corporation and Kumho Petrochemical occupy positions as upstream-integrated feedstock controllers leveraging captive polybutadiene and styrene-butadiene supply chains. Within the natural rubber processing tier, Sri Trang Agro-Industry exemplifies plantation-to-block vertical integration, anchoring Thai feedstock concentration for export-oriented tire industry supply. These three companies represent the structural poles around which mid-scale compounders and regional distributors organize their competitive positioning.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| ARLANXEO |
| Synthos |
| Kumho Petrochemical |
| Sinopec |
| Dow |
| JSR Corporation |
| Sri Trang Agro-Industry |
| Southland Holding Lonza |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in South Korean EPDM polymer production is pressuring synthetic rubber block margins while compressing procurement timelines for automotive compounders seeking thermal-stable grades. This utilization dynamic forces Thai natural rubber processors to accelerate forward contracting to lock in plantation feedstock before monsoon-driven price spikes.
Pricing Analysis
Formulation-generation pricing gaps separate silica-reinforced synthetic blocks from conventional carbon-black compounds and from experimental bio-based alternatives. Three-tier pricing structure across premium certified, standard industrial, and economy recycled grades dominates procurement, with REACH compliance and GB standard certification acting as the primary price differentiation drivers. Cost compression in economy recycled tiers is intensifying because post-consumer tire crumb quality inconsistency limits specification-grade applications. Construction flooring buyers exhibit the highest price sensitivity, while German and Japanese automotive OEMs prioritize thermal performance guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Thai natural rubber processors supplying European tire manufacturers, straining working capital for mid-scale block compounders. Geographic supply concentration rests on Thailand and Indonesia for natural rubber feedstock, South Korea and Saudi Arabia for EPDM synthetic polymers, and Germany and Japan for specification-grade automotive compounds. Raw material dependencies draw from Hevea brasiliensis latex, petrochemical-derived butadiene, and precipitated silica reinforcing agents. Single-source vulnerability around South Korean EPDM production clusters threatens automotive sealant manufacturers. Distribution runs through petrochemical-integrated producers to regional compounders, then to industrial distributors or direct mill-to-factory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle battery isolation demand is disrupting rubber block procurement patterns, with ECHA fluorinated processing aid phase-out timelines forcing simultaneous reformulation across European and Chinese supply chains.
For Market Incumbents: Entrench specification-grade positioning by deepening backward integration into Thai plantation networks and accelerating REACH-compliant compound registrations ahead of enforcement phase-in. Synthetic rubber producers must defend against bio-based substitute entrants by locking in long-term offtake agreements with Stuttgart and Nagoya automotive clusters. Capacity addition in Gujarat and Tamil Nadu manufacturing corridors offers geographic hedge against Southeast Asian feedstock volatility. For New Entrants and Emerging Players: Mid-market Indian industrial machinery manufacturers represent the most penetrable entry point for natural rubber block vibration dampening solutions, as domestic production buildout outpaces local compounder technical service capabilities. Recycled rubber construction flooring in North American cost-sensitive channels offers volume scale with lower certification barriers. Direct B2B marketplace engagement with real-time Shore A hardness data transparency enables bypass of established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic rubber block production as silica-reinforced formulation R&D and automated quality assurance systems displace legacy batch processing. Five-to-ten-year viability favors plantation-integrated natural rubber processors with forward contracting capabilities and specification-driven automotive compounders with ECHA registration moats. Monitor EPDM supply concentration in South Korean petrochemical complexes as a potential inflection signal for single-source risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Networks | Thai feedstock control locks in premium natural rubber block margins against monsoon price volatility. |
| Silica-Reinforced Formulation Scale-Up | Advanced compounding extends service life for heavy machinery applications in Indian industrial corridors. |
| REACH-Compliant Compound Registration | ECHA substance disclosure moats protect automotive supply positions in Stuttgart manufacturing clusters. |
| Digital Procurement Platform Deployment | B2B marketplaces with real-time Shore A data compress buyer search costs outside traditional channels. |
| Joint Venture in EPDM Capacity Diversification | Saudi petrochemical partnerships reduce single-source dependency for oil-resistant automotive sealant grades. |
Study Parameters
Desk research of customs trade data, petrochemical industry association reports, and regulatory filing databases preceded structured interviews with rubber technologists, automotive Tier 1 procurement managers, industrial distributor channel heads, and ECHA compliance officers. Primary fieldwork with Thai plantation network operators and South Korean petrochemical complex engineers was cross-validated against secondary sources including SEC 10-K disclosures and SAMR GB standard documentation. Bottom-up natural rubber latex volume flows and top-down synthetic polymer capacity utilization were triangulated to anchor market sizing.
Assumptions held fixed include ECHA fluorinated processing aid phase-out timelines, SAMR enforcement intensity on volatile organic compound limits, and Hevea brasiliensis plantation yield trends across the analysis window. Segmentation dimensions modeled encompass product chemistry tier, end-use industry vertical, Shore A hardness specification band, and regional production cluster. CAGRs were derived from elasticity-adjusted demand projections for electric vehicle battery isolation systems and industrial machinery vibration dampening. Forecast inputs incorporated monsoon pattern variability for natural rubber pricing and EPDM petrochemical feedstock cost curves.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles, construction equipment capital expenditure, or plantation labor availability would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and substitution elasticity between natural and synthetic grades. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Isoprene Rubber Market
Rubber
Liquid Silicone Rubber Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Global Automotive Elastomers Market
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Rubber Carbon Black Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Isobutylene Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Carboxylated Nitrile Rubber Market
Rubber
Rubber Molding Market
Rubber
Rubber Choppers Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Nitrile Elastomers Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market