
 Mobile Light Tower Market | 2026-2036
Mobile Light Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Light Tower Market Analysis
China is tilting toward expanded manufacturing capacity for mobile light tower components, with domestic foundries and LED assembly lines scaling output for export markets. Atlas Copco leverages its compressor and power equipment heritage to anchor premium positioning in rental channels across Europe and North America. Generac Power Systems sustains technology leadership through in-house genset integration that reduces third-party dependency. Wacker Neuson specializes in compact, towable designs that dominate urban construction and event applications where site access limits larger units.
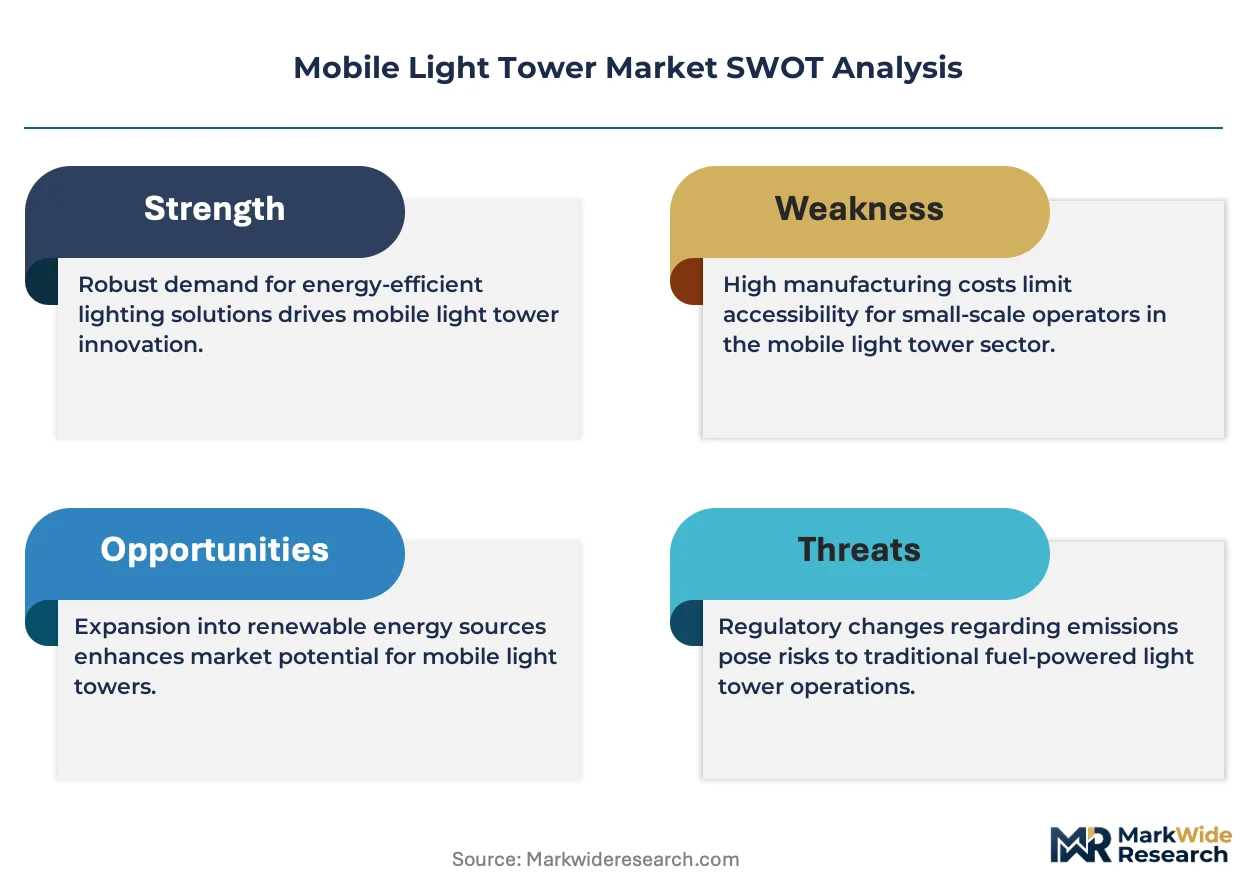
Mobile light towers are self-contained illumination systems mounted on trailers or skids, typically integrating a generator, mast assembly, and lamp bank capable of elevating luminaires to heights exceeding nine meters for area coverage in off-grid environments. Diesel light towers retain the largest installed base but face margin compression as hybrid and solar architectures capture preference in emission-sensitive jurisdictions. Solar light towers represent the fastest-expanding product category, driven by falling photovoltaic panel costs and battery energy density improvements that extend runtime without refueling. Emergency Services as an end-user segment commands premium pricing due to NFPA certification requirements and 24-hour deployment specifications that standard construction rentals do not match.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe compel engine downsizing or electrification, reshaping R&D budgets toward hybrid powertrains and battery-electric platforms. OSHA workplace illumination mandates and CE marking requirements under the EU Machinery Directive establish baseline product standards that determine market access for non-compliant imports. Stakeholders must monitor rental fleet telematics adoption, as usage-based billing and predictive maintenance contracts redefine customer relationships and equipment turnover cycles.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing diesel light tower margins and redirecting R&D capital toward hybrid powertrains and solar-battery architectures across North American rental fleets.
Growth Catalysts
- EPA Tier 4 Final:These US emissions standards force engine downsizing and electrification, accelerating fleet turnover toward cleaner architectures in construction and emergency services.
- Solar-hybrid technology:Falling photovoltaic panel costs and improved battery energy density extend runtime without refueling, capturing preference in emission-sensitive jurisdictions.
- Infrastructure stimulus:United States federal spending on roads, bridges, and utilities expands the addressable fleet base for rental channel deployment.
Market Restraints
- Steel and aluminum input volatility:Mast assembly and trailer chassis fabrication faces raw material cost swings that compress equipment margins before pricing adjustments transmit.
- LED module supply concentration:Premium diode sourcing clusters in East Asian foundries, exposing North American and European assemblers to single-region disruption risk.
- NFPA certification complexity:Emergency services segment requirements for 24-hour deployment specifications create product development friction that slows new entrant qualification.
Strategic Opportunities
- Urban event applications:Compact, towable designs dominate city construction and temporary illumination where site access limits larger units.
- Telematics-enabled billing:Usage-based rental contracts and predictive maintenance services redefine customer relationships and equipment turnover cycles.
- CE marking expansion:EU Machinery Directive compliance opens distribution into European rental channels seeking emission-compliant alternatives to legacy diesel stock.
Industry Challenges
- Electrification skill gaps:Field service networks lack technicians trained on battery-electric powertrain diagnostics and high-voltage safety protocols.
- Hybrid integration complexity:Synchronizing diesel genset, photovoltaic input, and battery management systems extends engineering validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Light Tower Market |
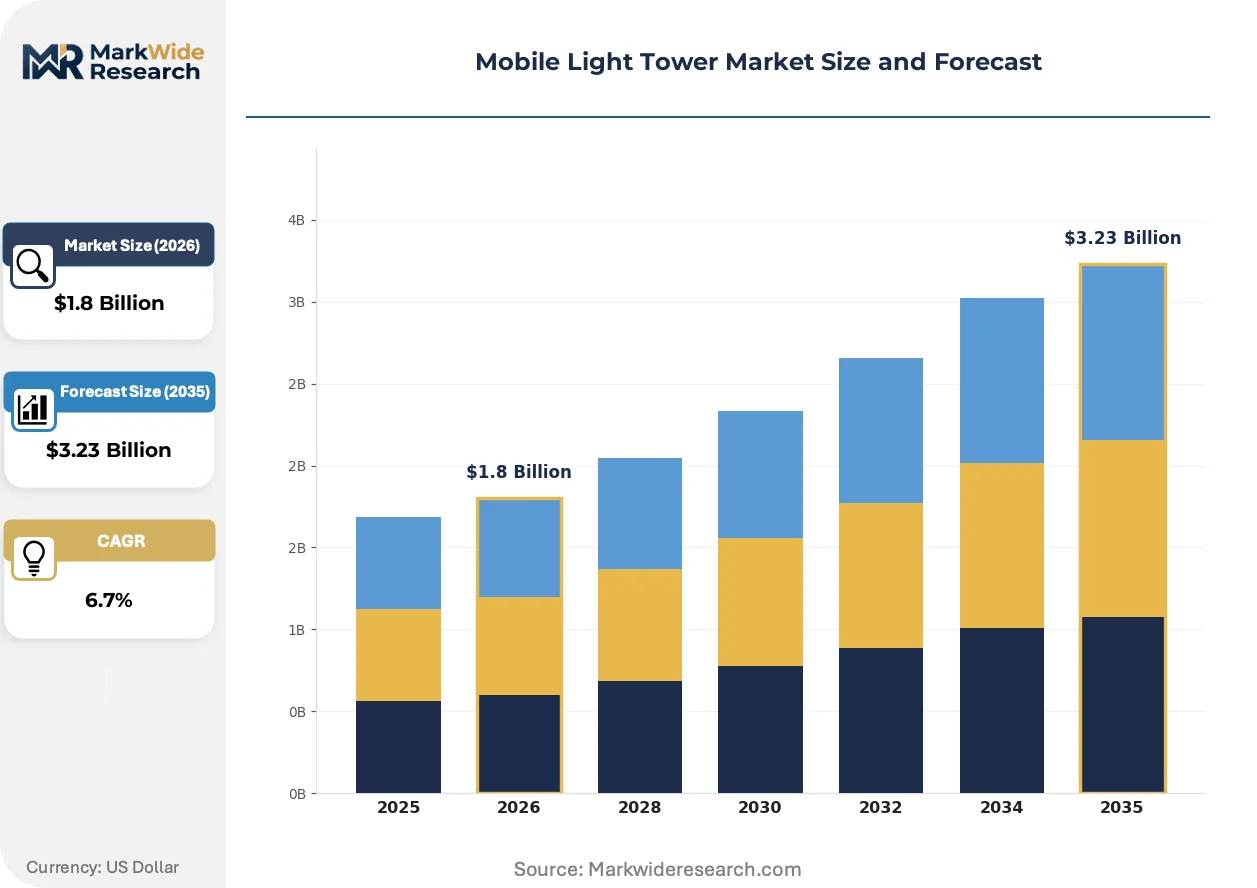
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Light Towers, Diesel Light Towers, Hybrid Light Towers, Electric Light Towers End User: Construction, Mining, Events, Emergency Services Installation: Static Installation, Mobile Installation, Temporary Installation, Permanent Installation Application: Outdoor Lighting, Emergency Lighting, Construction Lighting, Traffic Safety |
| Companies Covered | Atlas Copco, Generac Power Systems, Allmand Bros, Terex Corporation, Doosan Portable Power, Wacker Neuson, Caterpillar, United Rentals, Italtower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Light Tower Market Emerging Trajectories
Product architectures are pivoting from conventional diesel gensets toward electrified platforms, while procurement and rental models absorb digital telemetry that restructures how utilization translates to revenue.
LED luminaire technology is migrating from metal-halide lamp banks in mobile light towers. Construction rental fleets in the United States are accelerating this substitution as operating cost advantages compound. The shift compresses maintenance revenue streams for traditional lamp suppliers while expanding addressable market for semiconductor lighting manufacturers.
EU Stage V regulations in Europe compel engine redesigns toward hybrid architectures or full electrification. These standards reshape competitive positioning by disqualifying non-compliant imports from machinery rental tenders. Manufacturers serving German and French markets are responding with downsized powertrains and battery-electric prototypes.
Equipment-as-a-service contracts are displacing traditional capital purchase in North American rental channels. United Rentals and similar fleet operators now bundle maintenance, telemetry, and uptime guarantees into per-hour billing structures. This transformation concentrates buying power among large rental houses and compresses sales cycles for direct equipment procurement.
Mobile Light Tower Market Segmentation
Mobile light tower procurement patterns diverge sharply across powertrain technologies, end-use environments, and deployment duration. Equipment specification varies by whether towers serve intermittent event duty or continuous industrial operations.
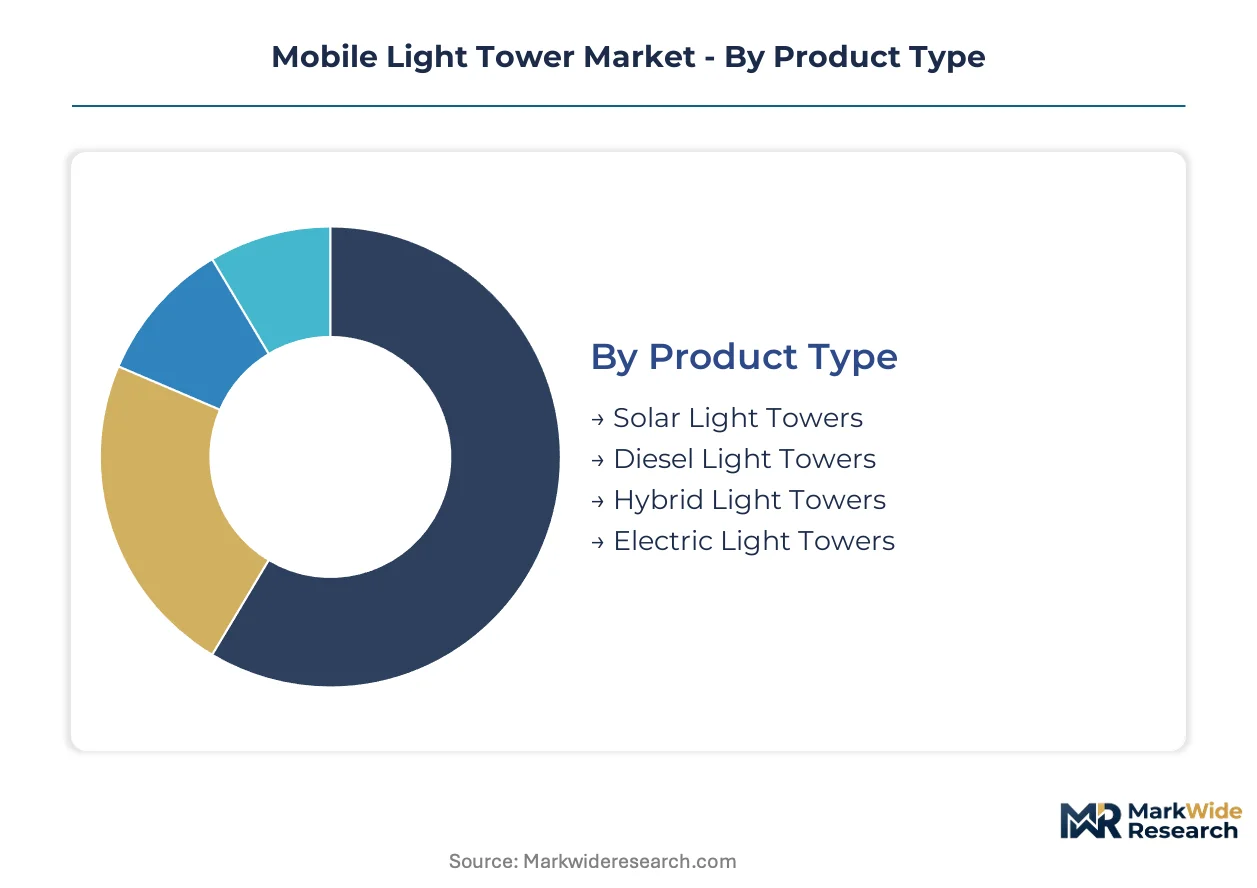
Product Type:
Power source architecture determines capital cost, fuel logistics, and regulatory compliance exposure across rental and direct purchase channels.
- Diesel Light Towers:Conventional genset-powered units with metal-halide or LED lamp banks dominate legacy fleet composition. United States construction rental pools retain substantial diesel inventory despite EPA Tier 4 Final compliance costs compressing margins on new unit production.
- Solar Light Towers:Photovoltaic panel arrays paired with lithium-ion battery storage eliminate refueling cycles and exhaust emissions. Falling module costs and energy density improvements accelerate preference in California emission-sensitive jurisdictions and remote site deployments lacking fuel logistics.
- Hybrid Light Towers:Dual-mode architectures synchronize diesel genset backup with solar-battery primary power to extend runtime flexibility.
- Electric Light Towers:Grid-tethered or battery-electric designs eliminate combustion entirely for urban event and short-duration construction applications.
Diesel units command the established base. The steepest expansion runs through solar architectures.
End User:
Customer verticals impose distinct performance specifications, certification requirements, and procurement contract structures.
- Construction:Rental fleet operators and general contractors drive volume procurement for roadbuilding, commercial development, and utility work. United States infrastructure stimulus expands addressable fleet deployment across state transportation departments and municipal contracting.
- Emergency Services:Fire departments, disaster response agencies, and utility restoration crews require NFPA-certified 24-hour runtime specifications and rapid deployment trailers. Premium pricing reflects certification complexity and uptime guarantees that standard construction rentals do not match.
- Mining:Open-pit and underground extraction operations demand explosion-rated fixtures and extreme-duty mast assemblies for 24/7 illumination.
- Events:Concert promoters and festival operators prioritize compact towable designs with low noise signatures for temporary urban deployments.
Construction verticals absorb the highest unit volumes. Emergency services capture the most favorable pricing structures.
Installation:
Deployment permanence shapes trailer specification, anchoring requirements, and power infrastructure integration.
- Mobile Installation:Highway-towable trailers with telescoping masts dominate rental channel turnover. United States equipment yards standardize on single-axle and dual-axle towable configurations compatible with standard pickup truck hitches for rapid site repositioning.
- Temporary Installation:Skid-mounted or trailer-anchored units deployed for 30-90 day construction phases balance mobility with semi-fixed positioning.
- Static Installation:Fixed-position towers without highway mobility serve dedicated yard lighting or permanent facility perimeter illumination.
- Permanent Installation:Hardwired grid connections and concrete foundations eliminate generator noise for long-term municipal and industrial site lighting.
Mobile configurations anchor rental fleet procurement. Temporary installations are gaining share fastest in infrastructure project contracting.
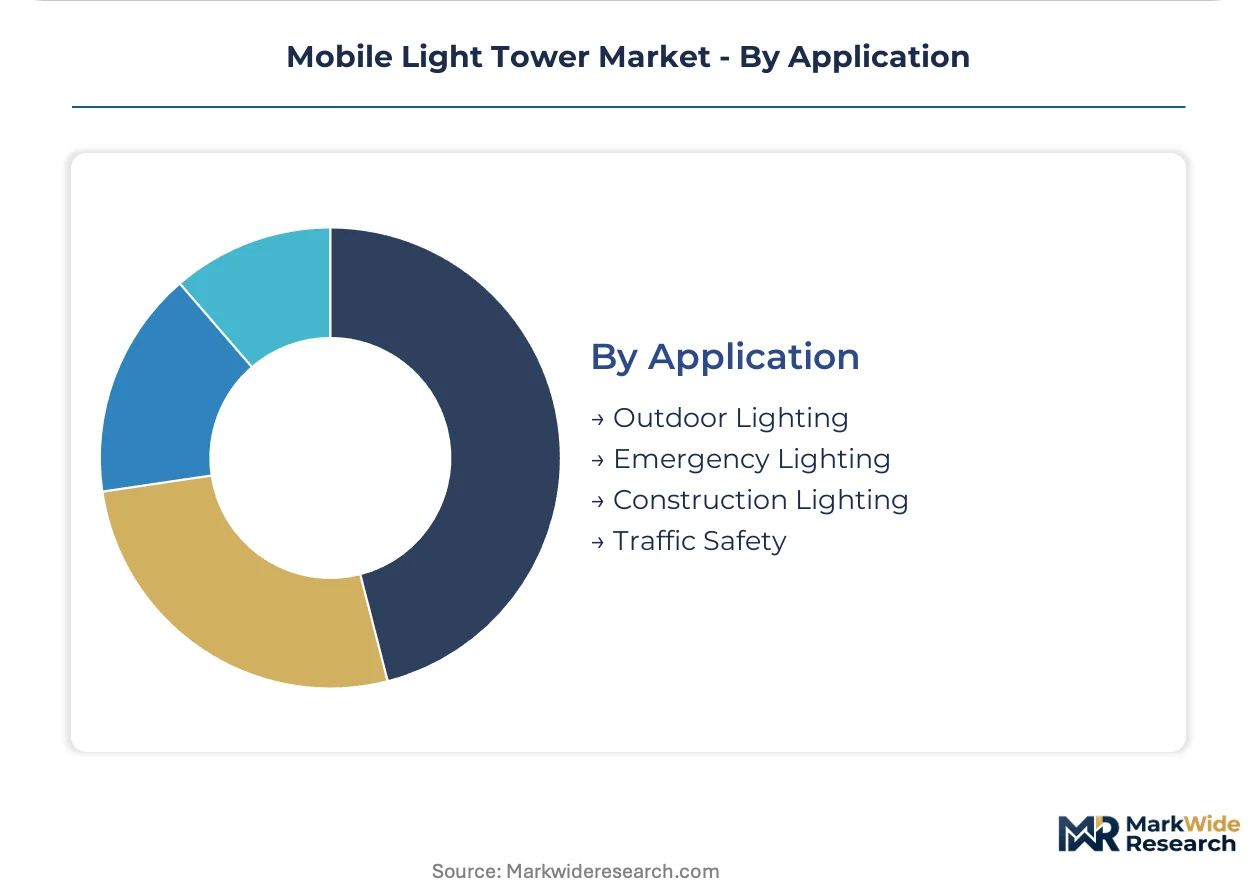
Application:
Illumination purpose dictates lumen output, beam spread patterns, and runtime redundancy requirements.
- Construction Lighting:High-lumen LED banks with 360-degree coverage illuminate earthmoving, concrete pouring, and structural assembly across multi-acre work zones. OSHA workplace illumination mandates establish minimum foot-candle requirements that determine fixture count and mast height specification.
- Emergency Lighting:Rapid-deployment units with battery backup and satellite communication integration serve disaster response and grid outage restoration. NFPA 1901 and 1906 standards govern fire apparatus compatibility and electrical system isolation.
- Outdoor Lighting:General-purpose area illumination for parking lots, material yards, and recreational facilities prioritizes operational cost efficiency over specialized certification.
- Traffic Safety:Directional arrow boards and sequential warning lights integrate with light tower masts for highway work zone compliance.
Construction lighting commands the dominant application share. Emergency lighting applications are climbing the fastest on disaster preparedness investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in China now supply mast assemblies and LED modules to assemblers across three continents. Demand formation concentrates in jurisdictions with active infrastructure programs and stringent emission protocols.
United States
Infrastructure stimulus legislation drives state transportation department fleet renewals from California to Texas. EPA Tier 4 Final standards compel rental operators toward hybrid and solar-battery architectures. Equipment yards in Illinois and Ohio accelerate turnover of legacy diesel inventory.
Germany
Rental channel consolidation in Bavaria and North Rhine-Westphalia deepens specification requirements for CE-marked emission-compliant units. EU Stage V regulations disqualify non-compliant imports from machinery tenders. Stuttgart-area engineering firms prototype battery-electric platforms for municipal contracting.
China
Domestic foundries in Jiangsu and Zhejiang provinces scale output of telescoping mast assemblies for export markets. The Ministry of Ecology and Environment enforces dual carbon goals that redirect domestic fleet procurement toward photovoltaic-hybrid designs. Yangtze River Delta LED packaging plants supply diode modules to North American assemblers.
India
National highway expansion and smart city programs generate demand for mobile illumination across Maharashtra and Karnataka state projects. Bureau of Indian Standards certification requirements filter import competition. Gujarat-based fabricators assemble towable units for domestic rental channels and Middle East export.
United Arab Emirates
Mega-project construction in Dubai and Abu Dhabi sustains premium-tier procurement for 24-hour continuous-duty specifications. MOHAP and municipal safety regulators enforce workplace illumination standards that exceed baseline OSHA equivalents. Sharjah industrial zones host assembly operations serving Gulf Cooperation Council rental markets.
Mobile Light Tower Market Vendor Landscape
Diversified industrial conglomerates and specialized portable power fabricators split the market into distinct capability tiers. Consolidation pressure concentrates buying power among multi-regional rental houses while fragmenting manufacturing supply across component specialists. Equipment-as-a-service contracts and telematics-enabled uptime guarantees now constitute primary competitive vectors alongside hardware specification.
Among the diversified industrial tier, Atlas Copco and Generac Power Systems exemplify archetypes that leverage captive power equipment heritage to anchor premium positioning. Wacker Neuson occupies a position within the specialized compact equipment segment. These named entities represent strategic poles—integrated power systems capability versus towable design specialization—around which procurement decisions in rental and direct-purchase channels organize.
| Leading Market Players |
|---|
| Atlas Copco |
| Generac Power Systems |
| Allmand Bros |
| Terex Corporation |
| Doosan Portable Power |
| Wacker Neuson |
| Caterpillar |
| United Rentals |
| Italtower |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit steel mast and LED module cost volatility directly into North American equipment pricing, concentrating margin pressure on diesel-hybrid assemblers while amplifying price differentiation between EPA-certified and non-compliant inventory pools.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the Mobile Light Tower Market. Three-tier pricing structure across premium, standard, and economy levels separates NFPA-certified emergency services units from construction rental fleet specifications and basic event-duty models. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in standard-tier diesel units is intensifying because engine redesign compliance expenses outpace pricing power recovery. Municipal rental channels exhibit highest price sensitivity; disaster response agencies demonstrate lowest sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Steel coil and aluminum extrusion feedstock anchoring mast fabrication draws from foundry capacity concentrated in China, Germany, and India. Lithium-ion battery cells, LED diode modules, and telescoping hydraulic cylinders constitute critical component dependencies. Single-source vulnerability clusters around Yangtze River Delta LED packaging plants serving North American assemblers. Distribution runs through national rental house networks and regional equipment yards rather than direct OEM sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar-hybrid technology penetration sits below twenty percent of installed base, positioning the Mobile Light Tower Market as an early-cycle expansion story with infrastructure stimulus and emission compliance timelines as the dominant adoption accelerants.
For Market Incumbents: Build captive genset integration moats by deepening backward integration into engine control systems and battery management firmware. Atlas Copco and Generac Power Systems exemplify this defensive posture. Consolidate regional service networks to offset electrification skill gaps threatening field support quality. Threat vector: pure-play solar entrants with photovoltaic supply chain control bypassing diesel heritage entirely. For New Entrants and Emerging Players: Urban event applications in emission-restricted California and Northeast corridor municipalities represent the most penetrable entry point given access constraints and noise ordinances disqualifying legacy diesel inventory. Solar-battery architectures with sub-60 dB signatures unlock municipal contracting channels. Go-to-market angle: telematics-enabled per-hour billing contracts displacing capital purchase friction for festival operators and film production coordinators. For Investors and Strategic Acquirers: Component-specialist assemblers with captive LED sourcing relationships and Yangtze River Delta manufacturing partnerships offer the most attractive acquisition profile for long-term viability across a five-to-ten-year electrification horizon. Signal to watch: rental fleet telematics penetration rates crossing fifty percent as indicator of usage-based billing model maturity and equipment-as-a-service contract standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Integration | Synchronizes diesel genset backup with solar-battery primary power to extend runtime flexibility for remote deployments. |
| Telematics Platform Deployment | Enables usage-based rental billing and predictive maintenance contracts that redefine customer relationships across United Rentals-scale fleets. |
| NFPA Certification Investment | Unlocks premium pricing in emergency services vertical where 24-hour runtime specifications command favorable contract structures. |
| LED Module Supply Agreement | Secures diode sourcing from Jiangsu and Zhejiang foundries to mitigate single-region disruption exposure. |
| CE Marking Pathway Completion | Opens European rental channel access as EU Stage V regulations disqualify non-compliant imports from machinery tenders. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with rental fleet managers, OEM product directors, and municipal procurement officers; and secondary validation through EPA compliance filings, EU Stage V regulatory databases, and customs records tracking mast assembly trade flows. Bottom-up unit economics triangulated against top-down infrastructure spending projections.
Forecast inputs span powertrain technology substitution curves, rental fleet turnover cycles, and emission regulation phase-in schedules across the analysis window. Segmentation dimensions modeled include power source architecture, end-user vertical, and deployment permanence. CAGRs were derived from equipment shipment trajectories and capital expenditure patterns specific to construction and emergency services procurement channels.
Stress conditions across steel input costs, battery cell availability, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure stimulus continuity and photovoltaic cost decline curves. Cross-checking against rental house fleet disclosure filings and state transportation department procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
North America Drilling Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
US Aerial Work Platform Market