
 Global Roti Maker Market | 2026-2036
Global Roti Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Roti Maker Market Outlook
A capital-intensity divergence between automated and manual product lines is rotating competitive advantage toward manufacturers with captive supply chains. TTK Prestige Ltd. leverages its integrated foundry and coating facilities to control aluminum and non-stick surface costs. Bajaj Electricals anchors its position through dense after-sales networks across Indian metros and tier-2 cities. Philips competes on thermal-control IP, sustaining premium positioning in European and Gulf markets through precision heating algorithms.
A roti maker is an electromechanical or manual kitchen appliance designed to flatten dough and apply controlled heat to produce unleavened flatbread, typically operating at plate temperatures between 200°C and 250°C with pressing mechanisms that yield uniform thickness. The device automates the most labor-intensive phase of traditional flatbread preparation, serving household consumers and commercial foodservice operators seeking output consistency. Electric roti makers dominate value generation due to higher unit economics and replacement-part streams, while manual variants retain volume leadership in price-sensitive South Asian rural markets. Stainless steel construction commands preference in commercial channels for durability compliance, though aluminum variants penetrate faster in household segments where thermal efficiency and lower weight drive purchase decisions.
The US Consumer Product Safety Commission governs electrical safety certification, while India's BIS mandates ISI marking for domestic heating appliances, and the EU's CE marking requires electromagnetic compatibility and low-voltage directive compliance for European market entry. These frameworks elevate compliance costs for new entrants but protect incumbents with established testing relationships and localized production. Stakeholders must monitor evolving energy-labeling requirements and raw-material tariff shifts that could redraw cost-competitive manufacturing locations.
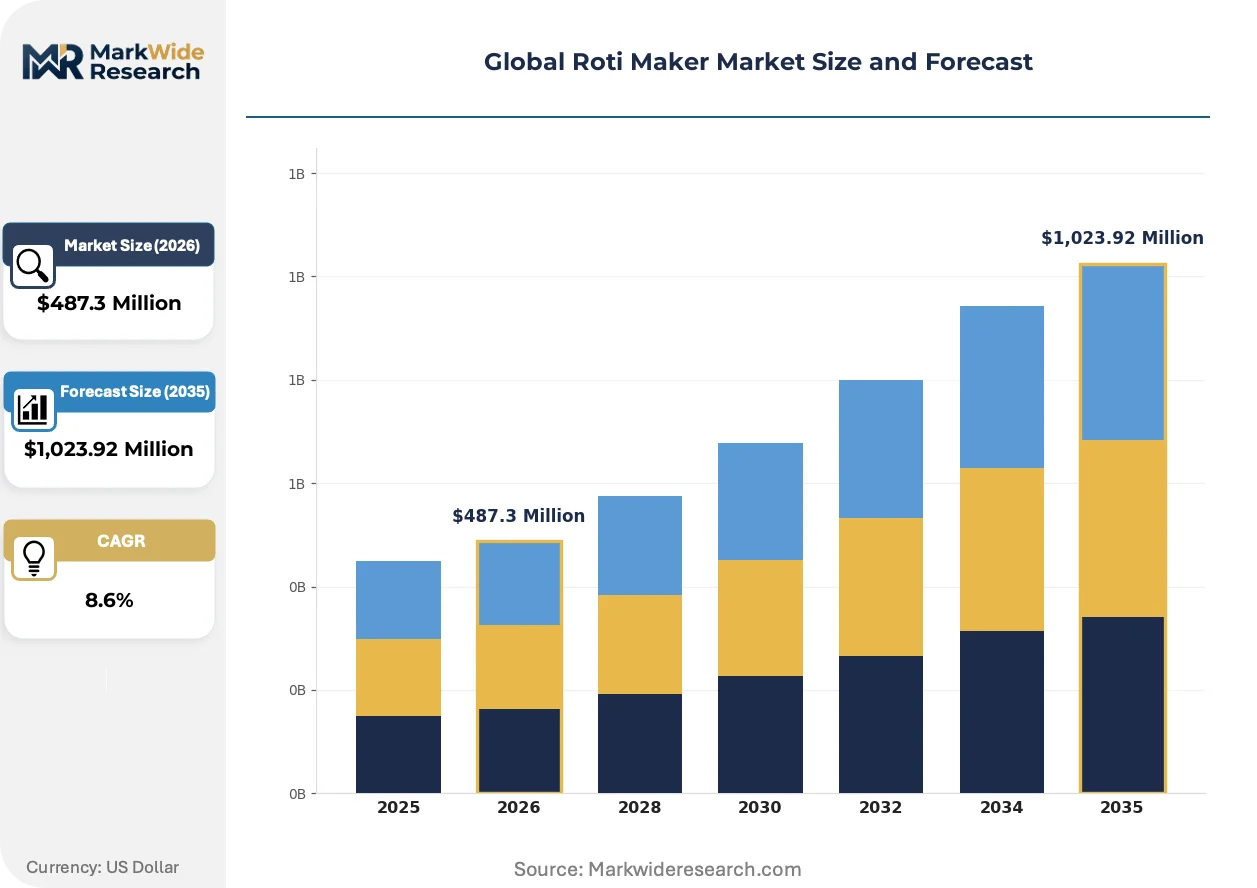
Market Dynamics
The European Commission's Ecodesign Directive is compressing thermal efficiency tolerances for electric roti makers, forcing manufacturers to redesign heating elements and insulation systems ahead of compliance deadlines. This regulatory pressure is accelerating R&D spend across the supply base while culling non-compliant product lines from European distribution channels.
Growth Catalysts
- Energy-efficiency mandates:The EU Ecodesign Directive is pulling replacement demand toward induction-compatible and thermostatically controlled units in Germany, France, and the Netherlands.
- Dual-income household formation:Urban Indian households are automating traditional food preparation, with automated flatbread appliances penetrating tier-1 and tier-2 cities at accelerating rates.
- Diaspora community expansion:North American South Asian populations in Texas, California, and New Jersey are driving demand for voltage-compatible electric units with North American safety certifications.
Market Restraints
- Aluminum price volatility:Cast aluminum plate costs fluctuate with LME pricing, compressing margins for manufacturers without long-term smelter contracts or captive foundry capacity.
- Manual product substitution:Low-cost manual presses retain volume dominance in rural South Asian markets where electrification remains inconsistent and price elasticity is extreme.
- Certification fragmentation:Divergent electrical safety standards across the US CPSC, India's BIS, and EU CE marking create compliance cost stacking for multi-region product strategies.
Strategic Opportunities
- Smart kitchen integration:Wi-Fi-enabled roti makers with app-based temperature profiling are opening premium positioning in Gulf Cooperation Council households with high smart-appliance penetration.
- Commercial foodservice expansion:Quick-service Indian restaurants in the UK and Canada are adopting high-throughput electric units with stainless steel construction for durability compliance.
- India's PLI scheme:Production-linked incentives for domestic appliance manufacturing are attracting component localization investments that reduce import duty exposure.
Industry Challenges
- Thermal control engineering scarcity:Precision heating algorithm development requires specialized electromechanical talent concentrated in European and East Asian industrial clusters.
- After-sales network density:Repair technician availability lags unit sales growth in emerging urban markets, creating warranty fulfillment bottlenecks and brand reputation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Roti Maker Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Roti Maker, Manual Roti Maker, Non-Stick Roti Maker, Multi-Functional Roti Maker End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Direct Sales Material: Stainless Steel, Aluminum, Ceramic, Plastic |
| Companies Covered | TTK Prestige Ltd., Bajaj Electricals, Zimplistic India Pvt Ltd., Sunflame Enterprises Pvt. Ltd., Wonderchef, Jaipan Industries Ltd., Morphy Richards, Philips, Havells, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Roti Maker Market Strategic Shifts
Intelligent thermal management systems are displacing fixed-wattage heating elements across premium product tiers, while regulatory pressure on energy consumption is forcing material science advances in plate construction and insulation design.
Induction-compatible aluminum-ceramic composite plates are decomposing the traditional bifurcation between electric and stovetop-compatible product categories. Dual-income households in Mumbai, Bangalore, and Dubai are adopting these hybrid units at rates exceeding pure electric models. The technology is decomposing manufacturer SKU portfolios and compressing development timelines for region-specific variants.
REACH substance restrictions on perfluorinated compounds are eliminating certain non-stick coating chemistries from European market eligibility. Manufacturers serving Germany and France are accelerating ceramic and sol-gel coating qualifications to maintain product registration. The directive is most acutely affecting mid-tier brands without in-house coating formulation capabilities.
Direct-to-consumer channel expansion is fragmenting traditional appliance retail dependence in North America and Gulf markets. Amazon, Noon, and specialized South Asian e-commerce platforms are capturing share from brick-and-mortar ethnic grocery chains. This shift is most visible in the UAE and Saudi Arabia, where logistics infrastructure supports same-day delivery of small electrics.
Global Roti Maker Market Segmentation
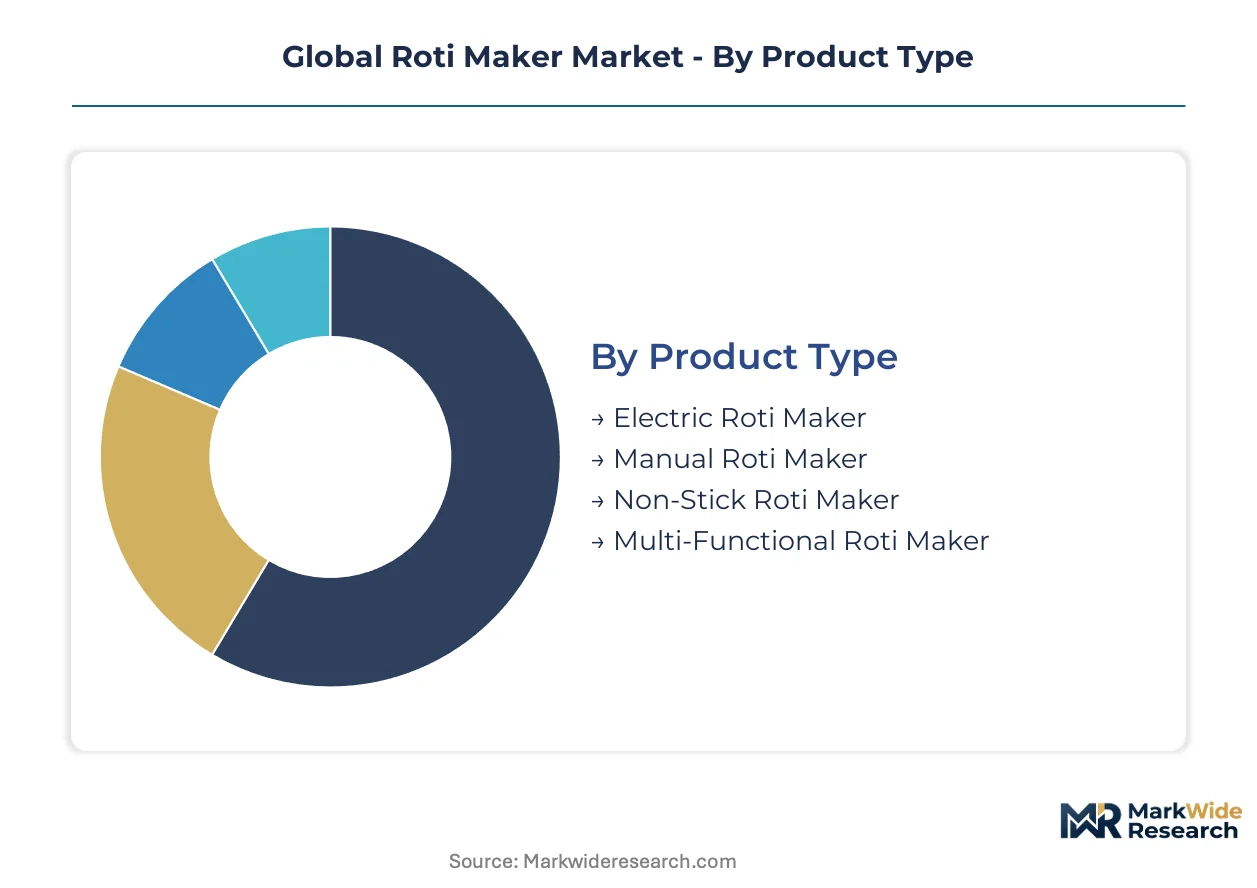
Segmentation in the roti maker market reveals divergent margin structures across automation levels and material choices. Manufacturers allocate R&D spend disproportionately toward segments where thermal control IP and coating chemistry command pricing power.
Product Type:
Margin pools concentrate in electric variants where replacement-part streams and thermal algorithm licensing sustain recurring revenue.
- Electric Roti Maker:These units deploy thermostatically controlled heating elements operating between 200°C and 250°C with precision pressing mechanisms. Demand clusters in urban Indian households and North American diaspora communities where dual-income families automate traditional preparation. Energy-efficiency mandates from the EU Ecodesign Directive are pulling replacement cycles toward induction-compatible models in Germany and France.
- Manual Roti Maker:Hand-operated presses with cast aluminum or steel plates require no electrical infrastructure. Rural South Asian markets retain volume dominance where electrification remains inconsistent and price elasticity is extreme.
- Non-Stick Roti Maker:Coated plates using ceramic or sol-gel formulations respond to REACH substance restrictions on perfluorinated compounds in European markets.
- Multi-Functional Roti Maker:Hybrid units combining roti pressing with griddle or toaster functions target space-constrained urban kitchens in Mumbai and Dubai.
The dominant share belongs to electric roti makers, while multi-functional variants are gaining share fastest through premium positioning in Gulf Cooperation Council households.
End User:
Application-driven cost structures separate high-volume commercial specifications from household durability requirements.
- Households:Residential units prioritize compact footprints and thermal efficiency over throughput. Urban Indian tier-1 and tier-2 cities drive replacement of manual griddles with automated appliances as kitchen modernization accelerates.
- Restaurants:Quick-service Indian restaurants in the UK and Canada specify stainless steel construction and high-throughput electric units for durability compliance under commercial use conditions.
- Catering Services:Mobile food preparation demands portable units with rapid heat recovery and voltage compatibility across deployment locations.
- Food Trucks:Space-constrained operators in Texas and California require compact electric units with North American safety certifications from the US Consumer Product Safety Commission.
Households retain the largest installed base, though restaurants are expanding most quickly through commercial foodservice adoption in diaspora-heavy markets.
Distribution Channel:
Channel economics favor direct relationships where logistics infrastructure supports same-day delivery and reduced retail margin extraction.
- Online Retailers:Amazon, Noon, and specialized South Asian e-commerce platforms fragment traditional appliance retail dependence. The UAE and Saudi Arabia exhibit the most visible shift where logistics networks enable rapid fulfillment of small electrics.
- Supermarkets:Mass-market channels in Indian metros and tier-2 cities stock entry-level electric and manual variants for price-sensitive consumers.
- Specialty Stores:Ethnic grocery chains in New Jersey and California serve diaspora communities with voltage-compatible units and regional recipe support.
- Direct Sales:Manufacturer-owned channels in India leverage dense after-sales networks for warranty fulfillment and repair technician deployment.
Online retailers command the steepest expansion trajectory, while direct sales defend margin position through service attachment in established urban markets.
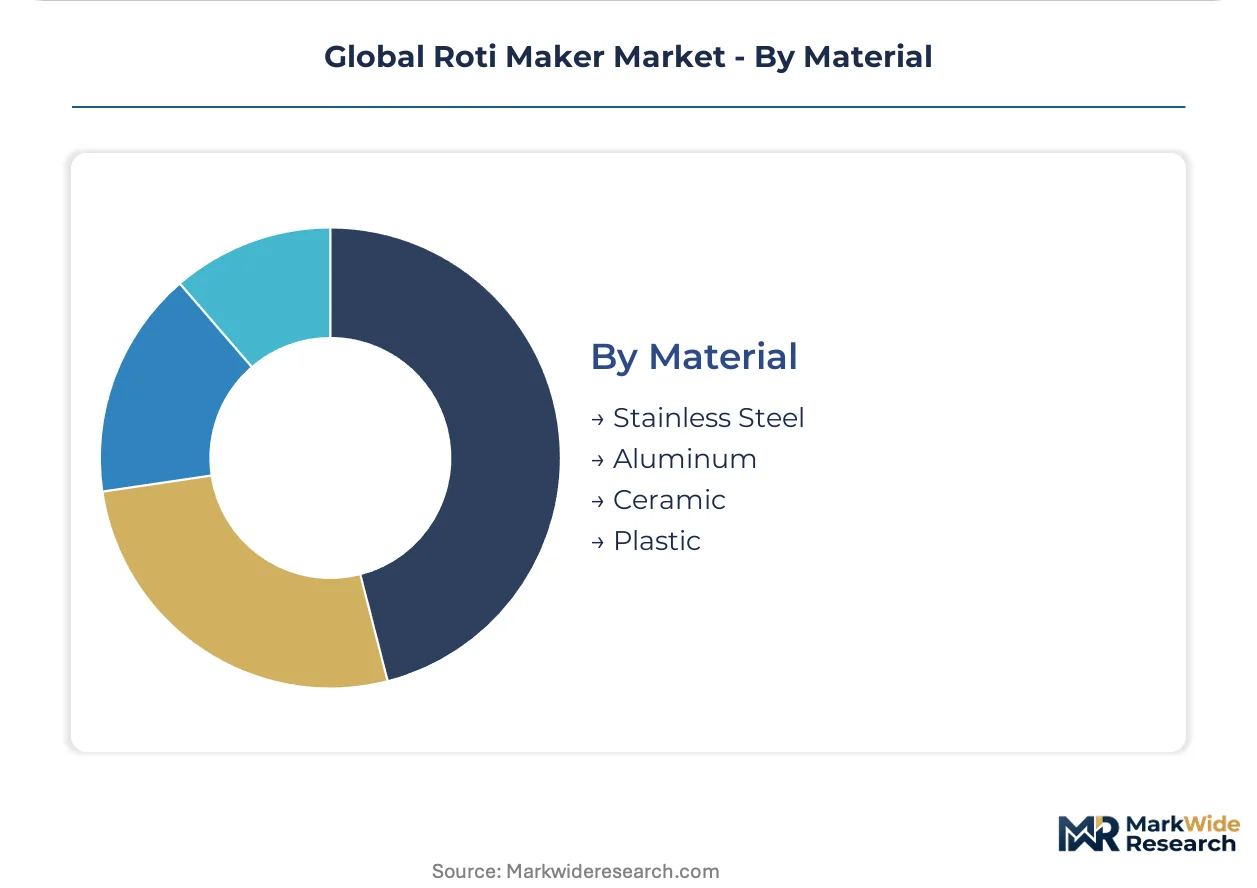
Material:
Raw material cost volatility and regulatory compliance requirements differentiate procurement strategies across construction types.
- Stainless Steel:Commercial channels mandate this construction for durability compliance and food safety certification. Quick-service operators in Canada and the UK specify grade 304 or 316 for corrosion resistance under high-throughput conditions.
- Aluminum:Cast aluminum plates dominate household segments where thermal efficiency and lower weight drive purchase decisions. LME price fluctuations compress margins for manufacturers without captive foundry capacity or long-term smelter contracts.
- Ceramic:Ceramic and sol-gel coatings replace perfluorinated formulations eliminated by REACH restrictions in European markets.
- Plastic:Exterior housings and handle components reduce unit weight and manufacturing cost for entry-level manual variants in price-sensitive rural markets.
Aluminum holds the dominant share by unit volume, while stainless steel is climbing the fastest through commercial channel specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in roti makers tilt heavily toward India as the dominant manufacturing source, with finished units and component kits shipped to diaspora concentrations in North America, the Gulf, and Europe. Trade volumes concentrate through three primary corridors: India-UAE re-export hubs, direct India-US container routes, and India-UK air freight for premium electric variants.
India
Urban kitchen modernization in Mumbai, Bangalore, and Delhi-NCR accelerates replacement of manual griddles with automated appliances as dual-income households expand. The Bureau of Indian Standards mandates ISI marking for domestic heating appliances, elevating compliance costs for new entrants while protecting established testing relationships. Manufacturing clusters in Gujarat and Tamil Nadu concentrate aluminum casting and non-stick coating capacity for both domestic consumption and export assembly.
United States
Diaspora communities in Texas, California, and New Jersey drive demand for voltage-compatible electric units with North American safety certifications. The US Consumer Product Safety Commission governs electrical safety certification, creating compliance cost stacking for multi-region product strategies. Distribution runs through ethnic grocery chains in Edison and Fremont alongside Amazon's direct-to-consumer channel expansion.
Germany
Energy-efficiency mandates from the European Commission's Ecodesign Directive pull replacement demand toward induction-compatible and thermostatically controlled units. REACH substance restrictions on perfluorinated compounds eliminate certain non-stick coating chemistries, accelerating ceramic and sol-gel coating qualifications. Industrial clusters in North Rhine-Westphalia house testing laboratories and regional distribution hubs serving Central European markets.
United Arab Emirates
Gulf Cooperation Council households with high smart-appliance penetration adopt Wi-Fi-enabled roti makers with app-based temperature profiling. MOHAP and SFDA alignment on product safety standards streamlines registration across GCC markets. Dubai's logistics infrastructure supports same-day delivery of small electrics through Noon and Amazon, fragmenting traditional appliance retail dependence.
United Kingdom
Quick-service Indian restaurants in London, Birmingham, and Manchester adopt high-throughput electric units with stainless steel construction for durability compliance. The UK's post-Brexit regulatory framework maintains CE marking alignment for electromagnetic compatibility while adding UKCA marking requirements. Commercial foodservice expansion concentrates procurement decisions through regional equipment distributors serving the Midlands and Southeast England.
Global Roti Maker Market Competitive Environment
Concentration sits with integrated manufacturers possessing captive foundry capacity and dense after-sales networks. The vendor base splits between large diversified appliance conglomerates and specialized kitchen equipment fabricators. Three archetypes dominate: vertically integrated specialists controlling aluminum and coating costs, premium thermal-control IP holders, and scale-driven mass-market producers. Competitive moves center on component localization investments and smart kitchen integration partnerships.
Among Indian-based integrated manufacturers, TTK Prestige Ltd. and Bajaj Electricals exemplify the foundry-control archetype, while Philips occupies a position representing premium thermal-control IP holders in European and Gulf markets. These three anchors illustrate how competitive advantage rotates toward supply chain captivity and algorithmic heating precision across distinct price tiers.
| Leading Market Players |
|---|
| TTK Prestige Ltd. |
| Bajaj Electricals |
| Zimplistic India Pvt Ltd. |
| Sunflame Enterprises Pvt. Ltd. |
| Wonderchef |
| Jaipan Industries Ltd. |
| Morphy Richards |
| Philips |
| Havells |
| Others |
Value Chain & Pricing Dynamics
Sixty-day aluminum inventory cycles at Gujarat foundries compress margin buffers for manufacturers lacking long-term smelter contracts, concentrating pricing power with integrated producers while forcing spot-market buyers into defensive procurement postures. This lead-time asymmetry between captive supply chains and merchant purchasers directly shapes tier-level pricing outcomes across household and commercial product lines.
Pricing Analysis
The customization-premium spread separates configured-to-order commercial units with stainless steel construction and ISI certification from standard household electric variants. Three-tier pricing structure across premium, standard, and economy levels reflects thermal-control algorithm sophistication and coating chemistry compliance with REACH restrictions. Cost compression in entry-level electric tiers is intensifying because aluminum LME volatility feeds directly into plate manufacturing economics. Rural South Asian households exhibit extreme price sensitivity, while Gulf Cooperation Council buyers purchasing Wi-Fi-enabled units demonstrate minimal elasticity to premium positioning.
Supply Chain Analysis
Strategic stockpile preferences dominate among integrated manufacturers maintaining sixty-to-ninety-day aluminum ingot reserves, while just-in-time procurement characterizes smaller fabricators dependent on Tamil Nadu coating subcontractors. Manufacturing gravity centers on India, China, and Vietnam, with component sourcing drawing from Gujarat foundries, Guangdong heating element suppliers, and Indonesian plastic molding operations. Single-source vulnerability concentrates in precision thermostat procurement from East Asian industrial clusters. Distribution runs through Dubai re-export hubs for Gulf and African markets, direct India-US container routes for North American diaspora demand, and Amazon's fulfillment network for direct-to-consumer penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens across this market as dual-income household formation and diaspora community expansion create geographically dispersed demand niches underserved by standardized product portfolios. The competitive landscape rewards specialized positioning over scale-driven mass-market dominance.
For Market Incumbents: Shield core margin pools by deepening backward integration into aluminum casting and ceramic coating formulation, insulating against LME volatility and REACH compliance cost stacking. Prioritize certification maintenance with BIS, CE marking, and US CPSC to erect regulatory barriers against emerging Asian competitors. Dense after-sales network deployment across Indian tier-2 cities remains essential for warranty fulfillment differentiation.
For New Entrants and Emerging Players: Differentiate on smart kitchen integration and app-based thermal profiling to capture premium positioning in Gulf Cooperation Council households with high connected-appliance penetration. Target North American diaspora communities in Texas and California with voltage-compatible units certified to US CPSC standards, exploiting ethnic grocery channel fragmentation and Amazon direct-to-consumer logistics. White-space availability concentrates in commercial foodservice specification for quick-service Indian restaurants in Canada and the UK.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance cost stacking and R&D intensity for thermal-control algorithms favor scaled integrated manufacturers over fragmented component assemblers. Acquisition targets should display captive foundry capacity or established coating chemistry partnerships. The signal to watch is India's PLI scheme disbursement velocity, which will indicate whether domestic component localization accelerates sufficiently to redraw cost-competitive manufacturing locations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Casting | Captive foundry capacity insulates margin compression from LME volatility and secures plate supply continuity. |
| Smart Kitchen Platform Partnership | Wi-Fi-enabled thermal profiling opens premium positioning in Gulf Cooperation Council connected households. |
| REACH-Compliant Coating Qualification | Ceramic and sol-gel formulations maintain European market eligibility as perfluorinated compounds face elimination. |
| Commercial Foodservice Specification | Stainless steel construction for UK and Canadian quick-service restaurants diversifies beyond household saturation. |
| India PLI-Linked Component Localization | Domestic manufacturing incentives reduce import duty exposure and strengthen cost position for export assembly. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of BIS certification registries, EU Ecodesign Directive compliance filings, and aluminum trade flow databases, supplemented by customs records from India, UAE, and US ports. Primary interviews engaged product development directors at integrated appliance manufacturers, procurement leads at commercial foodservice operators, channel managers at ethnic grocery chains, and regulatory affairs specialists familiar with CE marking and US CPSC pathways. Bottom-up unit shipment estimates from Gujarat and Tamil Nadu manufacturing clusters were triangulated against top-down consumer expenditure patterns in Mumbai, Dallas, and London.
Segmentation dimensions modeled include automation level (electric, manual, hybrid), construction material (aluminum, stainless steel, ceramic composite), end-use application (household, restaurant, catering, food truck), and distribution channel (online retail, supermarket, specialty store, direct sales). CAGRs were derived from regression analysis against macroeconomic indicators and demographic projections across the analysis window. Industry-specific forecast inputs incorporated dual-income household formation rates in Indian urban centers and diaspora population growth in North American metropolitan statistical areas.
The analysis sits within stated boundaries; outcomes outside sustained aluminum price stability, regulatory compliance timeline adherence, and logistics infrastructure investment would require recalibration. Forecasts reflect documented assumptions regarding energy-efficiency mandate implementation velocity and smart appliance adoption curves. Revision becomes warranted when REACH substance restriction enforcement intensity or India's PLI scheme disbursement velocity crosses thresholds that materially alter manufacturing cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Ice Cube Tray Market