
 Alcopop Market | 2026-2036
Alcopop Market Size, Share, and Industry Trends Forecast 2026-2036
Alcopop Market Analysis
Premium alcopop formulations is shifting away from commodity-grade flavored malt beverages as ingredient transparency and craft positioning command higher retail price points. Diageo PLC leverages its global spirits infrastructure to extend premium ready-to-drink lines across multiple continents. Suntory Holdings Limited anchors its competitive stance through Japanese whisky-barrel finishing techniques applied to canned cocktails. Bacardi Limited differentiates via rum-authenticity messaging that distances its portfolio from artificial-flavor perceptions.
Alcopops are ready-to-drink beverages blending distilled spirits, malt liquor, or wine with carbonated water, sweeteners, and flavoring agents, typically packaged in single-serve aluminum cans or glass bottles with alcohol content ranging from four to seven percent by volume, designed for immediate consumption without mixing equipment. Pre-mixed drinks leads volume contribution due to cocktail-convenience appeal among time-constrained consumers. Online Retail represents the fastest-growing distribution pathway as direct-to-age-verified platforms circumvent traditional three-tier system constraints. Cider occupies mature positioning in European markets where apple-fermentation heritage limits innovation premiums.
Regulators including the FDA, TTB, and EU-wide food safety authorities enforce alcohol content disclosure, allergen labeling, and marketing restrictions targeting underage consumers, which elevates compliance costs but also creates barrier-to-entry protection for established operators. The EU Green Deal packaging directives and evolving single-use plastic levies are reshaping material specifications across export-bound production. Stakeholders must monitor flavor additive approval pipelines and excise tax reclassification risks that could recategorize malt-based products into higher-tariff spirit brackets.
Market Dynamics
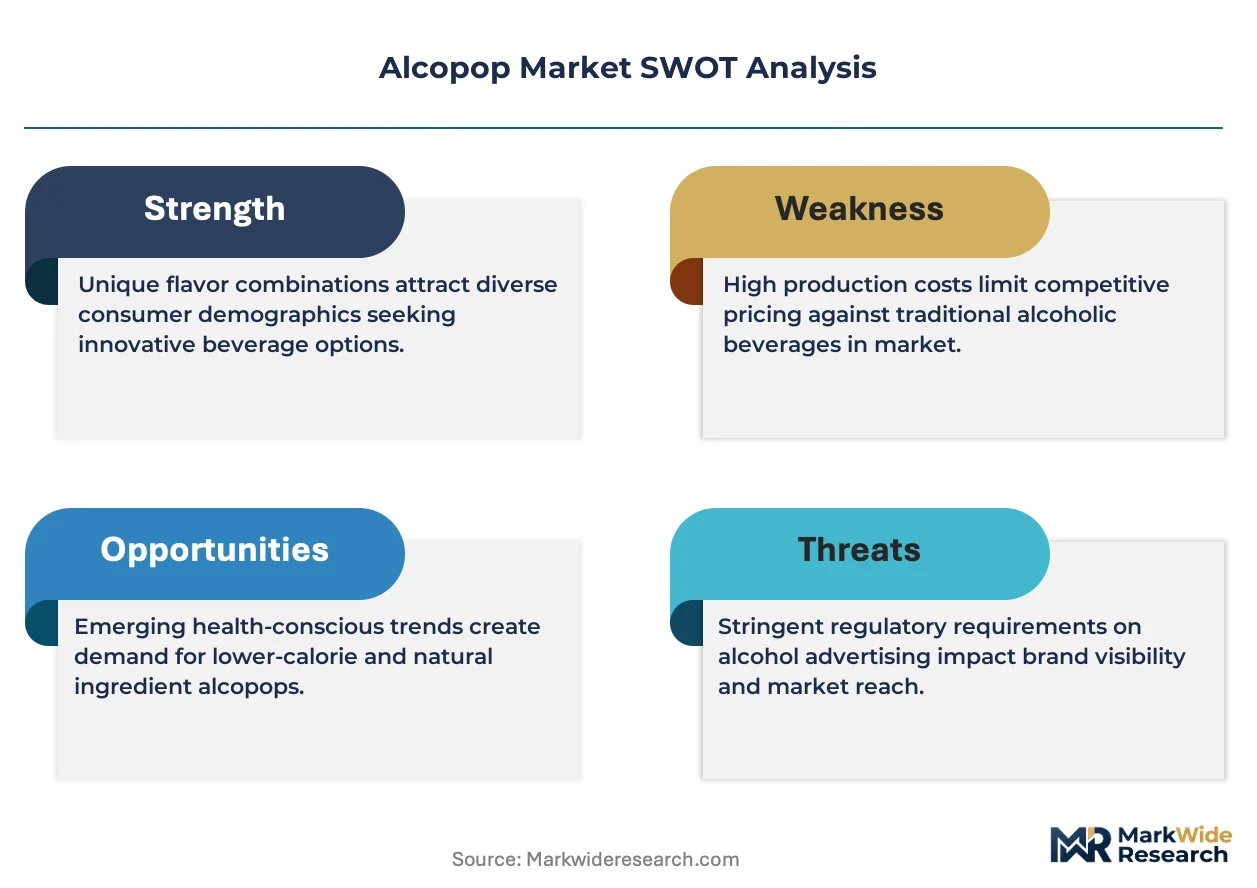
Regulatory fragmentation across sugar-content thresholds and labeling mandates is compressing formulation flexibility while elevating compliance costs for ready-to-drink alcoholic beverage producers.
Growth Catalysts
- Flavor Additive Pipeline Expansions:Novel botanical extracts and natural fermentation-derived sweeteners are widening permissible ingredient palettes under evolving FDA and EFSA frameworks.
- Single-Serve Packaging Convenience:Aluminum canning lines optimized for 250-355ml formats are capturing on-the-go consumption occasions among urban young adult demographics.
- Direct-to-Consumer Channel Liberalization:Age-verified e-commerce platforms in the United States are circumventing traditional three-tier distribution constraints and capturing margin previously allocated to wholesalers.
Market Restraints
- Excise Tax Reclassification Risk:Malt-based formulations face potential recategorization into higher-tariff spirit brackets under TTB and state-level alcohol tax codes, compressing price competitiveness against spirits-based competitors.
- Input Cost Volatility in Aluminum:Primary aluminum ingot prices and can-sheet availability from concentrated smelter geographies are introducing margin unpredictability for single-serve packaging.
- Sugar Content Ceiling Constraints:Hard caps on caloric density under Health Canada and select US state beverage regulations are limiting formulation sweetness profiles that historically drove repeat purchase.
Strategic Opportunities
- Japanese Whisky-Barrel Finishing Techniques:Oak-aging innovations adapted from premium spirits are creating differentiation premiums in canned cocktail formats previously dominated by neutral alcohol bases.
- EU Green Deal Packaging Compliance:Early alignment with circular-economy material specifications and deposit-return scheme compatibility is securing shelf access in German and Scandinavian retail channels.
- Non-Alcoholic Adjacent Formulations:Zero-ABV botanical seltzers using shared production infrastructure are capturing incremental occasion expansion among moderation-minded consumers.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise bridging beverage alcohol stability and clean-label natural ingredient performance commands premium compensation and extended recruitment cycles.
- Cross-Jurisdictional Labeling Harmonization:Divergent allergen disclosure requirements between FDA, TTB, and EU-wide food safety authorities are forcing SKU proliferation and inventory fragmentation.
- Cold-Chain Integrity for Wine-Based Formulations:Temperature-sensitive RTD categories face spoilage risk and insurance cost escalation in last-mile distribution networks lacking refrigerated capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcopop Market |
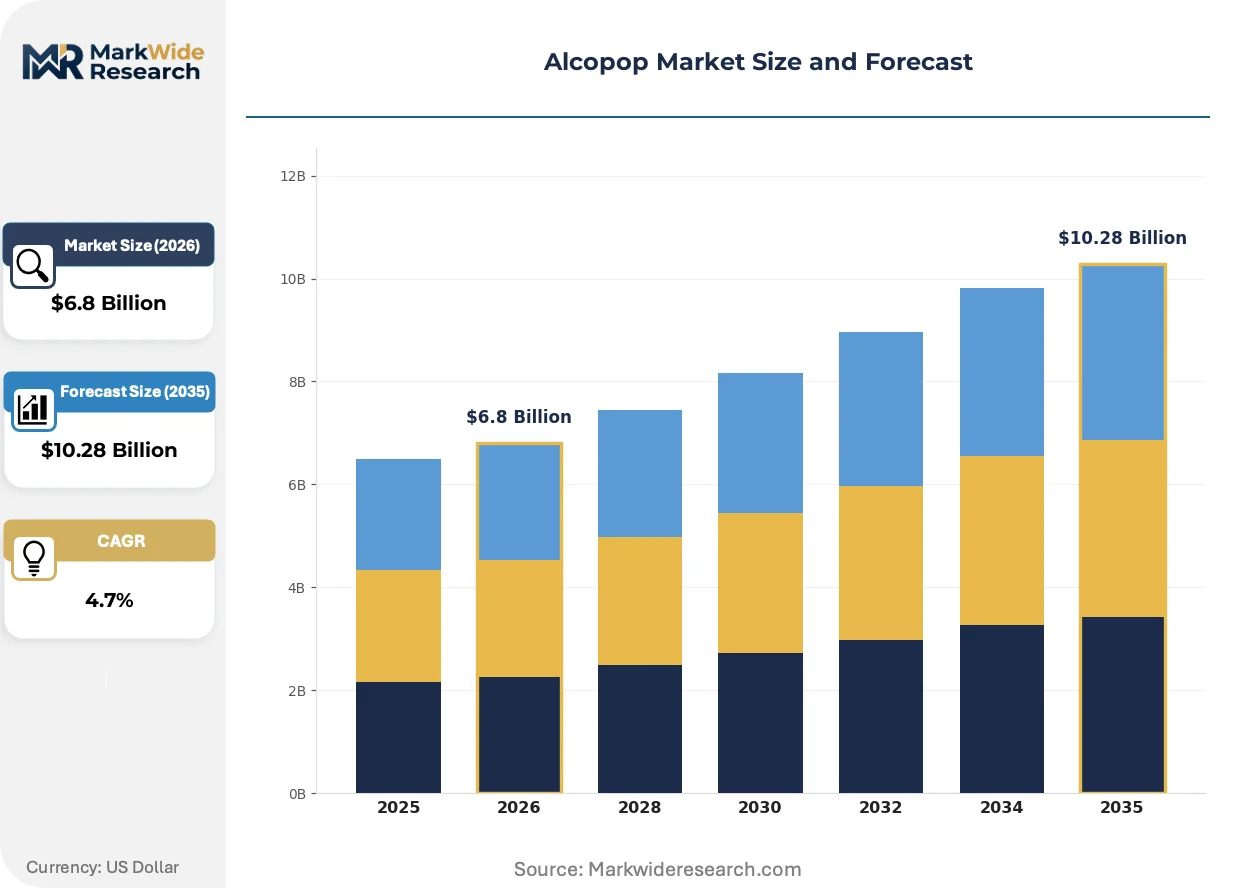
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cider, Flavored Beer, Pre-Mixed Drinks, Wine Coolers Distribution Channel: Online Retail, Convenience Stores, Supermarkets, Bars End User: Young Adults, College Students, Social Drinkers, Partygoers Flavor Profile: Citrus, Berry, Tropical, Herbal |
| Companies Covered | Diageo PLC, Asahi Group Holdings, Ltd., Suntory Holdings Limited, Anheuser-Busch InBev SA/NV, Molson Coors Brewing Company, Bacardi Limited, Mike's Hard Lemonade Co., Halewood International Limited, Pernod Ricard SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcopop Market Emerging Trajectories
Active fermentation science and packaging material science are converging to reshape how ready-to-drink alcoholic beverages achieve shelf stability, sensory differentiation, and environmental compliance simultaneously.
Precision fermentation-derived flavor compounds are converging with traditional distillation bases to enable clean-label positioning without sacrificing taste intensity or batch consistency. Mid-tier producers in the United States and Germany are piloting these biomanufactured inputs at commercial scale. This convergence is compressing the cost gap between artificial-flavor legacy formulations and premium natural-positioned competitors.
The EU Green Deal packaging directives and evolving single-use plastic levies are mandating recycled-content minimums and extended producer responsibility schemes for beverage containers. Aluminum can producers are retooling lines to accommodate higher post-consumer scrap ratios without compromising pressure integrity. Export-bound production from United Kingdom and Netherlands facilities is most affected, with reformulation of adhesive labels and liner compounds underway to meet ECHA substance restrictions.
Young adult beverage buyers are rotating toward occasion-based variety purchasing rather than brand loyalty, compressing SKU lifecycle duration and amplifying demand for limited-release flavor rotations. Convenience retailers in the United States are responding with modular cooler configurations that accommodate rapid brand turnover. This behavioral shift is most visible in coastal metropolitan markets where craft-positioned RTD entrants capture trial through social-media-driven launch cycles.
Alcopop Market Segmentation
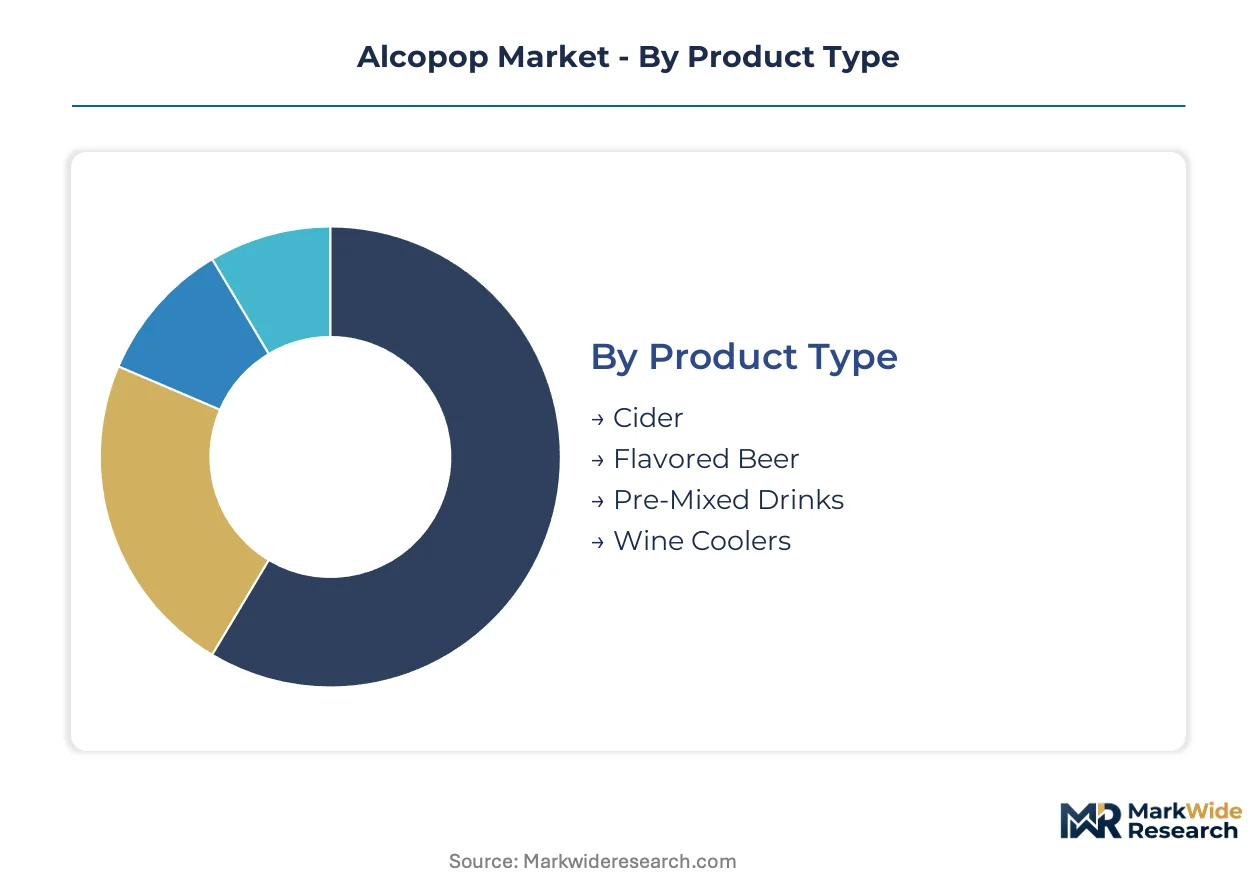
Alcopop producers navigate distinct demand pockets across consumption occasions, retail formats, and demographic cohorts. Segmentation reveals where formulation investments concentrate versus where channel access determines competitive survival.
Product Type:
Volume concentration favors single-serve convenience formats, while premium extraction rates diverge sharply across base alcohol categories.
- Pre-Mixed Drinks:Blended spirits or malt bases with carbonated mixers packaged in aluminum cans, alcohol content typically four to seven percent ABV. Young adult professionals in United States coastal metros drive repeat purchase through cocktail-convenience positioning that eliminates home mixing equipment.
- Cider:Apple or pear-fermented bases with residual sweetness, historically dominant in United Kingdom and Irish markets. European heritage markets constrain innovation premiums due to ingrained regional taste preferences and commoditized price floors.
- Flavored Beer:Adjunct-laden malt beverages with fruit or botanical infusions targeting entry-level drinkers. Regulatory scrutiny from TTB classification debates compresses margin predictability.
- Wine Coolers:Wine-based formulations with carbonation and flavoring, requiring refrigerated distribution infrastructure. Temperature-sensitive spoilage risk elevates insurance and logistics costs in last-mile networks.
Mature deployment sits with Cider. Newer deployment is concentrated in Pre-Mixed Drinks.
Distribution Channel:
Margin capture varies dramatically between age-verified direct platforms and traditional three-tier wholesale routes.
- Online Retail:Direct-to-consumer platforms with integrated age-verification bypassing distributor markups. United States regulatory liberalization in select states enables margin retention previously allocated to wholesale tiers.
- Convenience Stores:Impulse-oriented refrigerated single-serve placement in high-foot-traffic urban locations. Shelf space negotiations favor established brand portfolios with proven velocity metrics.
- Supermarkets:Multi-pack and variety-pack positioning for planned-purchase occasions. EUDR and EU Green Deal packaging compliance requirements reshape supplier qualification criteria in German and Dutch retail.
- Bars:On-premise draft and bottled formats with markup multiples supporting premium positioning. Labor cost inflation in service sectors compresses pour-cost targets for beverage managers.
Volume concentration remains with Supermarkets. Steepest expansion trajectory belongs to Online Retail.
End User:
Occasion-based purchasing patterns fragment brand loyalty across demographic micro-segments with divergent sweetness and ABV preferences.
- Young Adults:Urban professionals aged 25-34 prioritizing portability and Instagram-compatible packaging aesthetics. Social media-driven trial behavior compresses SKU lifecycle duration.
- College Students:Price-sensitive cohort with elevated sensitivity to multi-pack value propositions and entry-point ABV levels. Campus proximity marketing faces regulatory restrictions in select jurisdictions.
- Social Drinkers:Moderation-minded consumers rotating across beverage categories based on occasion formality. Zero-ABV adjacent formulations capture incremental share.
- Partygoers:Event-centric bulk purchasers favoring large-format packaging for shared consumption contexts. Seasonal demand spikes around festival and holiday calendars.
Established loyalty patterns sit with Social Drinkers. Emerging deployment concentrates in Young Adults.
Flavor Profile:
Clean-label natural positioning commands retail premiums against artificial-flavor legacy formulations facing regulatory pressure.
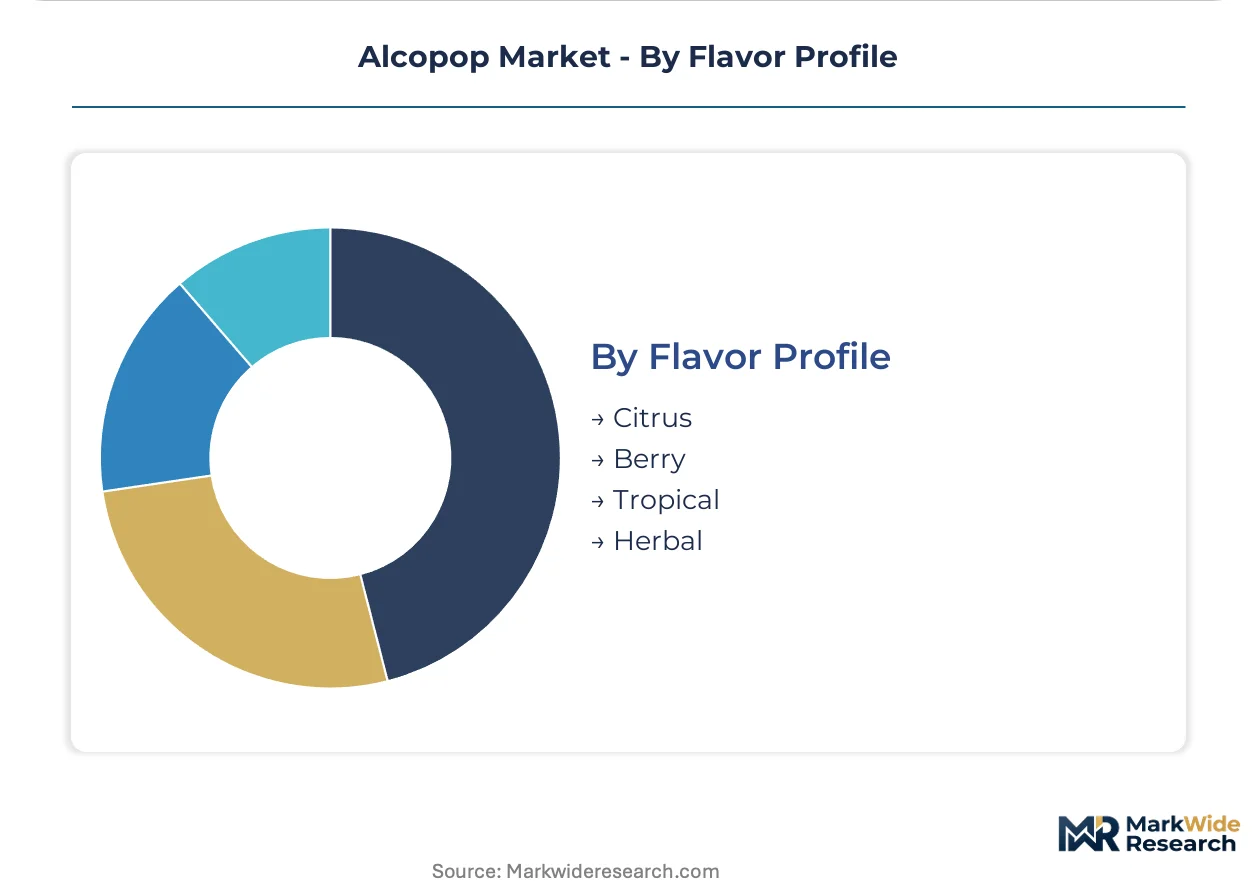
- Citrus:Lemon, lime, and grapefruit-derived profiles with established consumer acceptance across malt and spirits bases. FDA and EFSA flavor additive approval pipelines influence permissible extract sources.
- Berry:Strawberry, raspberry, and blackberry infusions targeting female-skewing demographics. Precision fermentation-derived alternatives narrow cost gaps with artificial counterparts.
- Tropical:Mango, pineapple, and passionfruit positioning for summer seasonal programming and vacation-occasion marketing. Supply chain concentration in Southeast Asian fruit processing regions introduces input volatility.
- Herbal:Botanical and spice-infused profiles aligned with wellness-adjacent moderation trends. Formulation stability challenges in aluminum can packaging limit shelf-life extension.
Commodity-scale deployment sits with Citrus. Premium extraction concentrates in Herbal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Miami and Los Angeles coastal metros concentrate flavored malt beverage innovation labs and limited-release launch cycles that set consumption patterns for domestic markets.
United States
Young adult professionals in coastal cities drive cocktail-convenience demand through single-serve aluminum formats. TTB classification debates over malt-based versus spirits-based taxation create regulatory uncertainty for formulation decisions. Chicago and Austin convenience retail channels prioritize rapid SKU rotation to capture social-media-driven trial behavior.
Japan
Whisky-barrel finishing techniques from premium spirits traditions migrate into canned cocktail production for export markets. METI guidelines on alcohol content labeling and marketing restrictions shape domestic compliance frameworks. Tokyo and Osaka metropolitan clusters host innovation centers where oak-aging protocols adapt to RTD scale.
Germany
EU Green Deal packaging directives force recycled-content minimums on aluminum can production for export-bound facilities. ECHA substance restrictions on adhesive compounds and liner materials drive reformulation of label specifications. Bavarian and North Rhine-Westphalia production corridors retool canning lines to meet circular-economy deposit-return scheme compatibility.
United Kingdom
Cider heritage markets in rural England and Wales constrain premium pricing power due to commoditized apple-fermentation traditions. Food Standards Agency allergen disclosure requirements elevate labeling compliance costs for cross-channel export formulations. London-based brand incubators pilot precision fermentation-derived flavor compounds for clean-label positioning.
Australia
Wine-based RTD formulations face cold-chain integrity challenges in last-mile distribution across vast interior geographies. TGA-aligned state-level beverage regulations enforce alcohol content ceilings that limit sweetness profiles driving repeat purchase. Sydney and Melbourne urban clusters concentrate direct-to-consumer platform development with integrated age-verification systems.
Alcopop Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the alcopop value chain, with integrated beverage conglomerates operating captive canning facilities while craft-positioned entrants contract-manufacture through third-party packers. Market structure tilts toward consolidated multinational control of shelf space and distribution infrastructure, though regional specialists retain loyalty in heritage cider markets. Three archetypes dominate: spirits-forward premium positioners, malt-based volume players, and botanical-clean-label insurgents. Competitive intensity concentrates on flavor pipeline velocity and age-verified e-commerce channel capture.
Within the spirits-forward tier, Diageo PLC and Bacardi Limited exemplify global infrastructure leverage for premium RTD extension across multiple continents. Suntory Holdings Limited anchors Japanese whisky-authenticity positioning through barrel-finishing differentiation. These three occupy positions where heritage distillation credibility transfers into canned format premiums, though each faces distinct regulatory navigation across FDA, TTB, and EU-wide food safety frameworks.
| Leading Market Players |
|---|
| Diageo PLC |
| Asahi Group Holdings, Ltd. |
| Suntory Holdings Limited |
| Anheuser-Busch InBev SA/NV |
| Molson Coors Brewing Company |
| Bacardi Limited |
| Mike's Hard Lemonade Co. |
| Halewood International Limited |
| Pernod Ricard SA |
| Others |
Supply Flow & Price Mechanics
Captive canning infrastructure anchors pricing power for integrated beverage conglomerates while contract-manufacturing dependence compresses margin retention for craft-positioned entrants. Diageo PLC and Anheuser-Busch InBev SA/NV leverage in-house aluminum canning lines to buffer against primary aluminum ingot volatility, whereas third-party packers pass through sheet-price escalations that erode price competitiveness in the flavored malt beverage tier.
Pricing Analysis
Value-based pricing anchored to occasion-convenience premiums separates pre-mixed drinks from commodity-grade cider positioning. Three-tier pricing structure across premium barrel-finished, standard malt-based, and economy flavored beer levels reflects ingredient transparency gradients and ABV thresholds. Pricing pressure stems from TTB reclassification debates that threaten malt-based formulations with spirit-tier excise rates. College students exhibit highest price sensitivity toward multi-pack value propositions, while young adult professionals absorb premium positioning for Instagram-compatible packaging aesthetics.
Supply Chain Analysis
Dual-sourcing requirements for aluminum can-sheet qualification are mandating supplier redundancy across United States, Germany, and Japan production corridors. Raw material dependencies center on primary aluminum ingots, natural fermentation-derived sweeteners, and precision fermentation flavor compounds. Single-source vulnerability concentrates in Southeast Asian tropical fruit processing for mango and passionfruit extracts. Distribution runs through age-verified direct-to-consumer platforms circumventing traditional three-tier wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive canning and barrel-finishing infrastructure defines competitive survival as input cost volatility and regulatory fragmentation intensify. Players securing upstream control over aluminum sheet supply and oak-aging protocols capture pricing power unavailable to contract-manufacturing dependent entrants.
For Market Incumbents: Anchor shelf-space dominance through rapid SKU rotation capabilities that match young adult variety-seeking behavior. Invest in Japanese whisky-barrel finishing infrastructure to defend premium positioning against botanical-clean-label insurgents. Secure EUDR-compliant packaging specifications early to lock German and Scandinavian retail access before deposit-return scheme deadlines compress competitor qualification windows. For New Entrants and Emerging Players: Enter via direct-to-consumer age-verified platforms in United States states with liberalized three-tier bypass regulations. Target herbal and botanical flavor profiles where formulation expertise scarcity limits incumbent replication speed. Deploy precision fermentation-derived ingredients to narrow cost gaps with artificial-flavor legacy formulations while capturing clean-label premiums. For Investors and Strategic Acquirers: Exit pathways concentrate in spirits-forward premium positioners with transferable distillation credibility into canned formats. Five-to-ten year viability favors producers with integrated canning infrastructure and EU Green Deal packaging compliance already operational. Monitor TTB classification rulings on malt-based taxation as the inflection signal that would recategorize competitive economics across the pre-mixed drinks segment.| Strategic Initiative | Industry Significance |
|---|---|
| Barrel-Finishing Infrastructure Investment | Japanese whisky-aging protocols adapted to RTD scale command premium shelf positioning against neutral alcohol bases. |
| Direct-to-Consumer Platform Launch | Age-verified e-commerce circumvents three-tier distributor markups and captures margin in United States coastal metros. |
| EU Green Deal Packaging Compliance | Recycled-content aluminum can specifications secure German retail access under circular-economy deposit-return schemes. |
| Precision Fermentation Partnership | Biomanufactured flavor compounds enable clean-label positioning without sacrificing batch consistency or taste intensity. |
| Herbal Formulation Pipeline Expansion | Botanical-infused profiles aligned with wellness-adjacent moderation trends capture premium extraction in aluminum formats. |
Methodological Framework
Multi-period observation of SKU velocity metrics, regulatory filing trajectories, and aluminum price indices anchored the trend analysis, supplemented by interviews with brand managers at multinational beverage conglomerates, category buyers at United States convenience retail chains, flavor chemists at contract manufacturing facilities, and regulatory affairs leads navigating FDA and TTB frameworks. Secondary validation drew from SEC 10-K filings, TTB label approval databases, ECHA substance restriction updates, and Nielsen retail audit data. Bottom-up channel volume builds triangulated against top-down macroeconomic consumption models.
Input-output matrices mapped formulation cost structures through packaging specifications across product type, distribution channel, flavor profile, and end-user demographic dimensions. CAGRs were derived from segmented growth trajectory modeling over the projection horizon. Industry-specific forecast inputs incorporated excise tax reclassification probability scenarios and EU Green Deal packaging directive implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under TTB malt-to-spirit reclassification or aluminum supply disruption conditions. Deviation in FDA flavor additive approval pipelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Wine Box Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Asia-Pacific Wine Market