
 Beer Fermenter Market | 2026-2036
Beer Fermenter Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Fermenter Market Outlook
The EU Green Deal is expanding sustainability requirements across beverage manufacturing equipment, compelling brewers to retrofit energy-intensive fermentation systems. GEA Group leverages its process engineering heritage to dominate large-scale industrial installations across European markets. Alfa Laval anchors its position through heat exchange integration within fermentation skids, reducing thermal energy consumption. Krones competes on turnkey brewery line integration, bundling fermenters with downstream packaging automation.
A beer fermenter is a sealed or open vessel, typically constructed from 304 or 316-grade stainless steel with polished interior surfaces below 0.8 micrometers Ra, designed to facilitate controlled yeast metabolism for ethanol and flavor compound production. Conical-bottom geometries enable efficient yeast harvesting and trub separation, while jacketed walls permit glycol-mediated temperature regulation within 0.5 degrees Celsius precision. Closed fermenters command the premium tier due to pressure-rated construction for carbonation control and oxygen exclusion, whereas craft brewery demand gravitates toward small-batch units with hybrid manual-automated temperature systems that balance capital constraints against reproducibility needs.
FDA food-contact substance regulations and EU REACH compliance frameworks govern stainless steel alloy composition and surface finish certification, directly determining market access for equipment imports. The EPA's effluent guidelines for brewery wastewater further shape fermenter cleaning-in-place system specifications, pushing adoption of closed-loop caustic recovery. Stakeholders must monitor evolving carbon border adjustment mechanisms and their projected impact on stainless steel input costs and equipment pricing structures.
Market Dynamics
EU Green Deal mandates on embodied carbon are forcing stainless steel suppliers and fermenter fabricators to requalify material sourcing and energy-intensive polishing processes, compressing margins across mid-tier equipment categories.
Growth Catalysts
- EU MDR surface finish standards:German and Czech craft breweries are retrofitting open fermenters to closed, pressure-rated vessels to meet hygiene certification requirements for export markets.
- Alfa Laval heat exchange integration:Jacketed fermenters with embedded glycol loops reduce thermal energy consumption by 15-20 percent, accelerating replacement cycles in energy-intensive facilities.
- Brazil craft brewery clusters:São Paulo and Minas Gerais states are expanding automated fermentation capacity to serve premium export contracts demanding batch-to-batch consistency.
Market Restraints
- Nickel alloy price volatility:316-grade stainless steel input costs fluctuate with Indonesian and Philippine ore export restrictions, squeezing fabricator margins on fixed-price contracts.
- EU carbon border adjustment mechanism:Pending CBAM implementation on steel imports threatens to raise landed costs for Asian-sourced fermenter shells by 8-12 percent.
- Closed-system technical complexity:Pressure vessel certification under ASME Boiler and Pressure Vessel Code extends lead times 6-10 weeks versus open fermenters.
Strategic Opportunities
- India FSSAI craft beverage expansion:Maharashtra and Karnataka state governments are licensing microbreweries under relaxed excise frameworks, creating first-mover equipment demand.
- Modular skid-mounted fermentation:Plug-and-play units with pre-integrated CIP systems reduce installation downtime, appealing to brewpub operators with limited technical staff.
- EPA effluent guideline retrofit mandates:US craft breweries face 2026 compliance deadlines for wastewater treatment, driving bundled fermenter-CIP system upgrades.
Industry Challenges
- ASME welder certification scarcity:Qualified pressure vessel fabricators command 30-40 percent wage premiums, constraining capacity expansion at mid-size equipment shops.
- Legacy DDC system integration:Breweries with 1990s-era programmable logic controllers face protocol incompatibility with modern IoT-enabled temperature monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Fermenter Market |
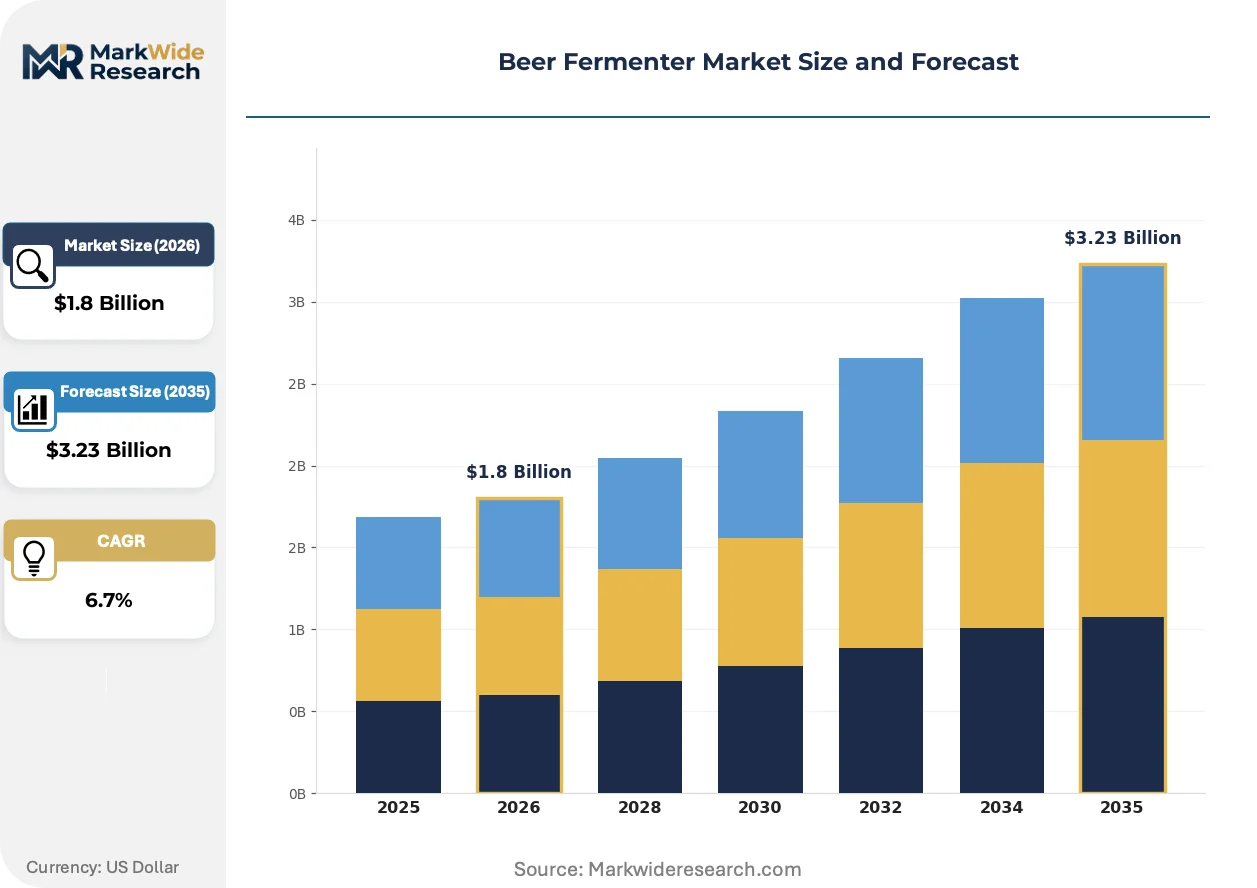
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Fermenters, Closed Fermenters, Cylindrical Fermenters, Conical Fermenters Size: Small Batch, Medium Batch, Large Batch, Industrial Scale Technology: Temperature Control, Automated Systems, Manual Control, Hybrid Systems End User: Craft Breweries, Commercial Breweries, Homebrewers, Beverage Manufacturers |
| Companies Covered | GEA Group, Sartorius, Bioengineering AG, Pierre Guerin, Eppendorf, Thermo Fisher Scientific, Applikon Biotechnology, Krones, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Fermenter Market Strategic Shifts
Digital fermentation monitoring and predictive yeast health analytics are compressing the traditional brewmaster-intuitive model, replacing subjective assessment with sensor-driven process control across production scales.
Single-use bioreactor film liners adapted from pharmaceutical manufacturing are consolidating into pilot-scale craft brewing for rapid strain prototyping and contamination-risk reduction. Colorado and Oregon brewpubs are deploying 50-200 liter disposable systems to test wild yeast variants without cross-contamination protocols. This technology is consolidating equipment utilization rates by eliminating CIP cycles between experimental batches.
EU F-Gas Regulation phase-down on hydrofluorocarbon refrigerants is forcing glycol chiller retrofits in jacketed fermenter installations. German equipment fabricators are qualifying propane and ammonia-based secondary cooling loops to maintain 0.5 degree Celsius precision without high-GWP working fluids. Czech and Polish breweries with aging 2010-era cooling infrastructure face accelerated replacement timelines to avoid regulatory penalties.
Direct equipment financing through brewery-as-a-service platforms is displacing traditional CAPEX-heavy ownership models among sub-5,000 hectoliter annual production facilities. California and Texas-based craft operators are leasing fermenter capacity with bundled maintenance and temperature monitoring subscriptions. This shift concentrates demand with equipment lessors who standardize on specific manufacturer platforms to minimize spare parts complexity.
Beer Fermenter Market Segmentation
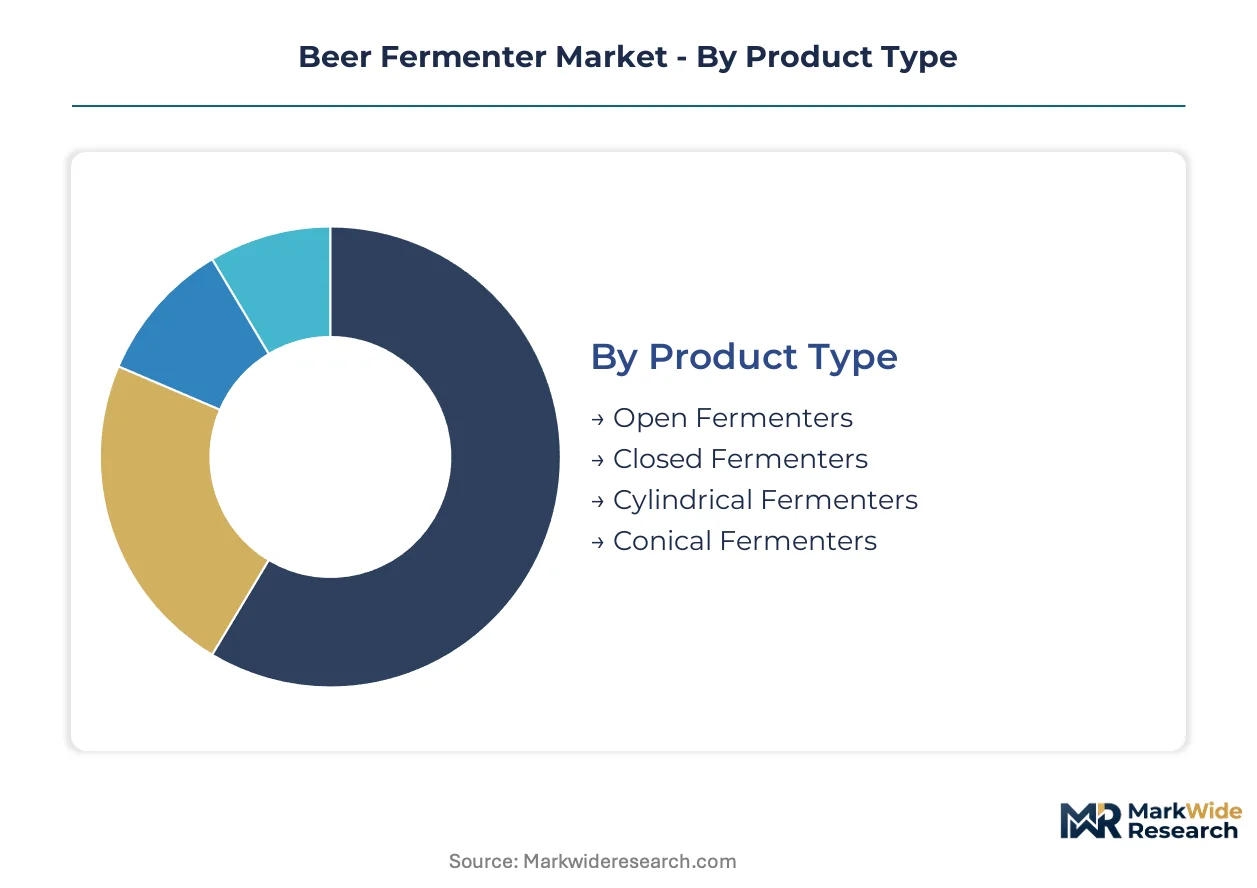
Equipment specification diverges sharply across production scales, with hygiene mandates and energy efficiency targets fragmenting demand into distinct technical tiers. Fabricators must align material grades and automation levels to specific regulatory thresholds governing each end-use category.
Product Type:
Supply concentration clusters around pressure-rated vessel fabrication, where ASME certification requirements limit qualified production capacity to specialized metalworking regions.
- Closed Fermenters:Pressure-rated 304/316-grade stainless steel construction with polished interiors below 0.8 micrometers Ra enables carbonation control and oxygen exclusion. German and Czech craft breweries are retrofitting open systems to closed vessels to meet EU MDR export hygiene standards.
- Conical Fermenters:Geometric bottom angles between 60-70 degrees facilitate yeast harvesting and trub separation efficiency. São Paulo craft clusters specify conical units with precision glycol jackets for premium export contract consistency.
- Open Fermenters:Traditional rectangular or round vessels without pressure rating serve heritage ale production in Belgium and UK specialty operations.
- Cylindrical Fermenters:Straight-walled designs with flat or dished bottoms occupy economy tier installations where yeast recovery is secondary to capital cost minimization.
Closed fermenters absorb the bulk of installed capacity; conical fermenters are expanding most quickly.
Size:
Cost tier stratification separates capital-intensive industrial installations from modular craft configurations with diverging financing structures.
- Industrial Scale:Vessels exceeding 5,000 hectoliters integrate with turnkey brewery lines and automated CIP systems. GEA Group dominates European large-scale installations through process engineering integration.
- Small Batch:Units below 500 hectoliters balance manual oversight with hybrid temperature controls for craft operators with constrained technical staff. California and Texas brewpubs increasingly lease capacity through equipment-as-a-service platforms.
- Medium Batch:500-2,000 hectoliter configurations serve regional craft brands scaling toward distribution contracts.
- Large Batch:2,000-5,000 hectoliter vessels bridge craft and commercial production thresholds with semi-automated monitoring.
Industrial scale units command the highest absolute revenue; small batch configurations are climbing the fastest.
Technology:
Application requirements determine automation depth, with precision fermentation protocols driving sensor integration intensity.
- Temperature Control:Glycol-jacketed vessels with 0.5 degree Celsius precision regulation anchor quality consistency mandates. Alfa Laval embeds heat exchange loops reducing thermal energy consumption.
- Automated Systems:IoT-enabled monitoring platforms with predictive yeast health analytics compress brewmaster-intuitive models. German fabricators face protocol incompatibility integrating legacy 1990s-era DDC controllers.
- Hybrid Systems:Manual-automated combinations balance capital constraints against reproducibility needs for sub-5,000 hectoliter operators.
- Manual Control:Basic thermostat and valve configurations persist in heritage production and developing market entry installations.
Temperature control systems anchor current installed base; automated systems are gaining share fastest.
End User:
Customer type dictates specification intensity, with regulatory exposure and batch consistency requirements scaling across production categories.
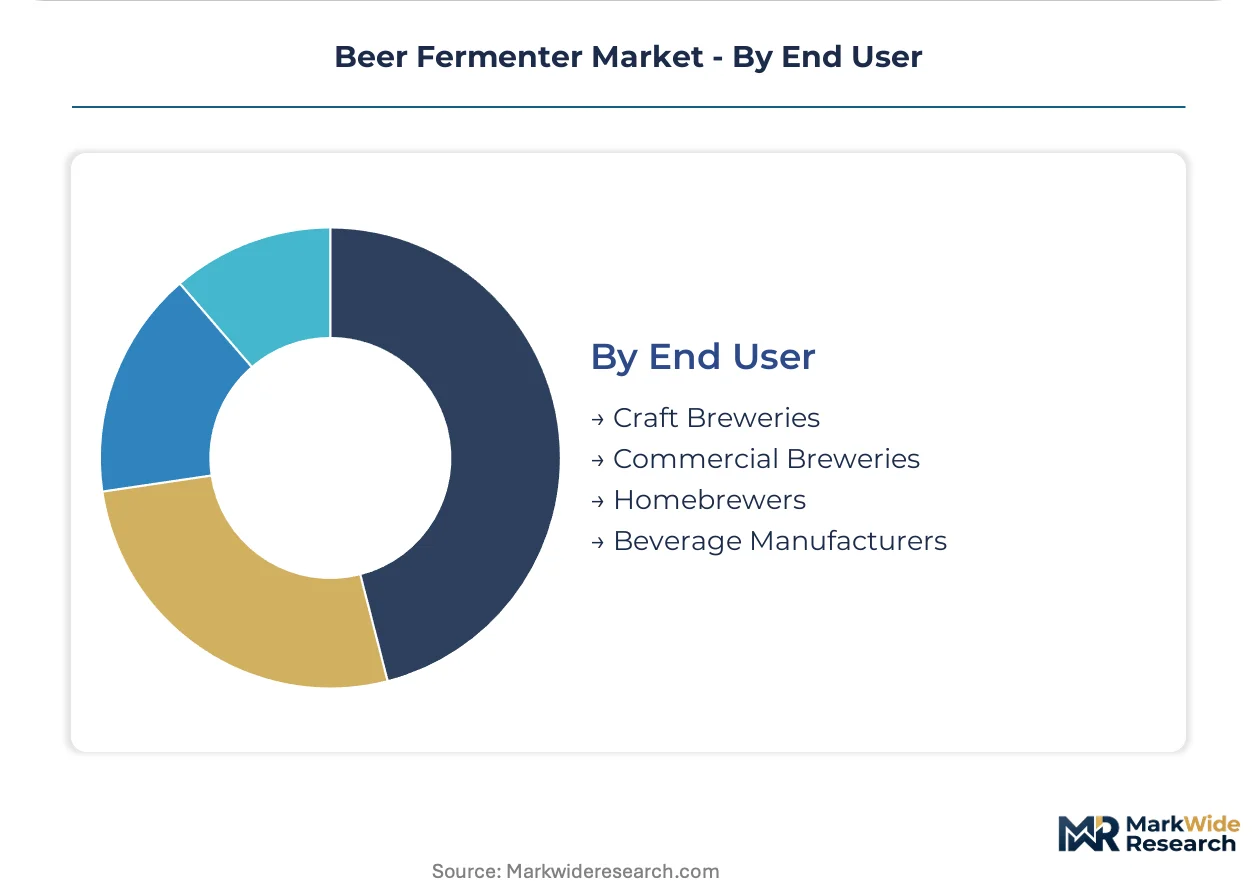
- Craft Breweries:Sub-50,000 hectoliter annual production facilities prioritize flexibility for experimental strains and seasonal rotation. Colorado and Oregon operators deploy single-use bioreactor film liners for wild yeast prototyping without CIP cycles.
- Commercial Breweries:Large-scale producers demand ASME-certified pressure vessels with integrated packaging line automation. Krones bundles fermenters with downstream systems for turnkey efficiency.
- Beverage Manufacturers:Diversified producers require multi-purpose vessels accommodating beer, cider, and hard seltzer fermentation with rapid changeover protocols.
- Homebrewers:Entry-level stainless or plastic vessels with basic airlock systems serve enthusiast segments with minimal regulatory exposure.
Commercial breweries absorb the bulk of installed capacity; craft breweries are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European fermenter demand through its dense cluster of industrial-scale breweries and precision equipment fabricators serving export markets.
United States
California and Texas craft brewery clusters are retrofitting aging fermentation capacity to meet EPA effluent guidelines for 2026 compliance deadlines. The FDA food-contact substance regulations govern stainless steel surface finish certifications for equipment imports. Colorado brewpubs deploy single-use bioreactor film liners for wild yeast prototyping without cross-contamination protocols.
Germany
Bavarian fabricators dominate large-scale industrial installations through process engineering integration and turnkey brewery line expertise. EU MDR surface finish standards and EU Green Deal embodied carbon mandates are forcing requalification of energy-intensive polishing processes. Munich and Stuttgart industrial zones concentrate ASME-certified pressure vessel production for premium closed fermenter exports.
Brazil
São Paulo and Minas Gerais craft brewery clusters are expanding automated fermentation capacity to serve premium export contracts demanding batch-to-batch consistency. ANVISA pharmaceutical-grade equipment standards are migrating into beverage manufacturing specifications for hygiene certification. Southern Brazilian fabricators face margin pressure from nickel alloy price volatility tied to Indonesian ore export restrictions.
India
Maharashtra and Karnataka state governments are licensing microbreweries under relaxed FSSAI excise frameworks, creating first-mover equipment demand for modular skid-mounted systems. The country's national food safety regulator is drafting craft beverage equipment standards aligned with EU MDR hygiene benchmarks. Bangalore and Mumbai metropolitan brewpubs prioritize plug-and-play fermenter units with pre-integrated CIP systems.
Czech Republic
Plzeň and Prague heritage breweries are retrofitting open fermenters to closed, pressure-rated vessels to meet EU MDR export hygiene standards for international distribution. EU F-Gas Regulation phase-down on hydrofluorocarbon refrigerants is forcing glycol chiller retrofits in jacketed fermenter installations. Czech fabricators with aging 2010-era cooling infrastructure face accelerated replacement timelines to avoid regulatory penalties.
Beer Fermenter Market Competitive Environment
The competitive structure tilts toward diversified process engineering conglomerates with beverage sector verticals. Equipment fabrication concentrates among stainless steel specialists with ASME Boiler and Pressure Vessel Code certification capabilities. Three archetypes dominate: integrated process engineering houses, heat exchange technology specialists, and packaging automation bundlers. Geographic expansion through regional fabrication partnerships and technology licensing for modular skid systems represent the dominant competitive vectors.
Within the integrated engineering tier, GEA Group and Krones exemplify turnkey brewery line positioning, while Alfa Laval occupies the thermal systems integration archetype. GEA Group leverages its process engineering heritage across European large-scale installations. Krones competes on downstream packaging automation bundling with fermentation skids. Alfa Laval anchors its position through heat exchange integration reducing thermal energy consumption in jacketed vessels.
| Leading Market Players |
|---|
| GEA Group |
| Sartorius |
| Bioengineering AG |
| Pierre Guerin |
| Eppendorf |
| Thermo Fisher Scientific |
| Applikon Biotechnology |
| Krones |
| Alfa Laval |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal embodied carbon mandates gate qualified supply and premium-tier pricing access for ASME-certified pressure vessels, compressing fabricator margins while concentrating pricing power with integrated engineering houses possessing verified low-carbon steel sourcing.
Pricing Analysis
Yield-guarantee pricing anchors premium-tier contracts, where throughput commitments and uptime penalties replace per-unit transactional models. Three-tier pricing structure across ASME-certified premium, CE-marked standard, and non-certified economy levels differentiates craft brewery capital constraints from industrial scale mandates. Cost compression in mid-tier equipment intensifies because nickel alloy price volatility squeezes fixed-price contract profitability. Small-batch craft operators exhibit highest price sensitivity, while commercial breweries with export hygiene mandates absorb premium vessel costs.
Supply Chain Analysis
Regional distribution centers in Munich, Stuttgart, and Bavarian industrial zones anchor hub-and-spoke patterns for European large-scale installations. Stainless steel supply concentrates in Germany, Italy, and Czech Republic fabrication clusters, with 316-grade alloy feedstock drawing from Indonesian and Philippine ore channels. Single-source vulnerability in ASME welder certification scarcity constrains capacity expansion at mid-size equipment shops. Distribution runs through turnkey brewery line integrators bundling fermenters with downstream packaging automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU carbon border adjustment mechanism implementation represents a consolidation play, forcing margin-compressed mid-tier fabricators toward acquisition or exit as landed cost premiums reshape competitive economics.
For Market Incumbents: Deepen backward integration into low-carbon stainless steel sourcing to defend ASME-certified production capacity against emerging modular skid competitors. Prioritize certification investment in EU MDR surface finish compliance to capture Czech and German craft brewery retrofit demand. Channel control through equipment-as-a-service platforms locks in small-batch operator relationships and reduces spare parts complexity.
For New Entrants and Emerging Players: Begin with Maharashtra and Karnataka microbrewery licensing waves under India's relaxed FSSAI excise frameworks, where first-mover equipment demand for plug-and-play CIP-integrated units outpaces established supplier presence. Target modular skid-mounted fermentation configurations appealing to brewpub operators with limited technical staff. Pursue direct equipment financing partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: EPA effluent guideline retrofit mandates hitting 2026 compliance deadlines is the leading indicator that bundled fermenter-CIP system upgrade cycles will concentrate demand with integrated solution providers. The five-to-ten year viability window favors acquiring ASME-certified pressure vessel fabricators with established welder certification pipelines rather than greenfield capacity builds. Watch for single-use bioreactor film liner adoption rates in Colorado and Oregon pilot-scale deployments as the signal for technology substitution risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Steel | EU CBAM implementation threatens 8-12 percent landed cost premiums on Asian-sourced shells. |
| Modular Skid-Mounted System Development | Pre-integrated CIP configurations reduce installation downtime for brewpub operators with constrained technical staff. |
| Equipment-as-a-Service Platform Launch | California and Texas craft operators increasingly lease capacity with bundled maintenance subscriptions. |
| ASME Welder Certification Pipeline Investment | Qualified pressure vessel fabricators command 30-40 percent wage premiums, constraining competitor expansion. |
| Single-Use Bioreactor Film Liner Qualification | Colorado and Oregon brewpubs deploy 50-200 liter disposable systems for wild yeast prototyping without CIP cycles. |
Study Parameters
Independent corroboration across fermentation equipment fabricators, craft brewery operations directors, and commercial brewery procurement leads underwrites the qualitative findings. Primary interviews with ASME-certified welders, process engineering consultants, and stainless steel alloy suppliers combined with secondary validation from EU MDR regulatory filings, EPA effluent guideline documentation, and SEC 10-K disclosures for diversified process engineering conglomerates. Bottom-up demand modeling from state-level microbrewery licensing data and top-down triangulation against capital expenditure surveys anchored volume estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from price mix effects. Segmentation dimensions modeled include product type, production scale tier, automation depth, and end-use category. CAGRs derive from weighted average of historical replacement cycle analysis and forward-looking regulatory compliance deadline impacts. Forecast inputs incorporate nickel alloy price volatility scenarios and EU CBAM implementation timing assumptions.
Underlying measurement precision varies by segment; industrial scale and automated system categories carry tighter precision than small-batch manual configurations. Forecasts reflect documented assumptions regarding regulatory implementation schedules and raw material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Distillers Malt Market
Alcoholic Beverages
Global Food-Grade Alcohol Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Built-In Wine Coolers Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Irish Whiskey Market