
 Coconut Alcohol Market | 2026-2036
Coconut Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Alcohol Market Analysis
Premium beverage brands is redrawing demand patterns in coconut alcohol as hospitality groups and mixology-focused retailers expand shelf space for tropical spirits. Malibu leverages its established beach-lifestyle positioning to sustain volume across North American and European retail channels. Bacardi competes through integrated rum-coconut blending capabilities that anchor its portfolio in Caribbean sourcing networks. Thai Coconut Public Company Limited dominates upstream supply with plantation-to-bottle control over raw coconut material flows.
Coconut alcohol denotes ethanol distilled from fermented coconut sap or blended with coconut-derived flavor compounds, typically achieving 20-40% ABV with characteristic ester profiles from tropical yeast strains. The product serves beverage formulation, culinary extraction, and personal care solvent applications across commercial manufacturing. Flavored Coconut leads product type revenue given its alignment with ready-to-drink cocktail trends, while Organic Coconut captures expanding margin pools from clean-label certification requirements. Beverages anchors end-use volume through tropical cocktail programs, though Personal Care segments register faster structural growth from natural preservative demand in Southeast Asian cosmetics manufacturing.
EU REACH compliance and FDA labeling standards govern coconut alcohol import access into major Western markets, with EFSA additive thresholds shaping flavor compound formulation choices for European-bound shipments. Thailand's central agricultural regulator enforces coconut origin certification that affects export eligibility for integrated distillers. Stakeholders must monitor evolving biofuel diversion policies that could tighten fermentation feedstock availability across tropical supply basins.
Market Dynamics
The EU Green Deal's sustainable agriculture requirements are forcing coconut alcohol distillers to restructure upstream sourcing relationships and certify carbon footprints across tropical supply basins.
Growth Catalysts
- EU Green Deal compliance mandates:European import standards for bio-based solvents create certified demand channels for sustainably harvested coconut ethanol, rewarding early-adopter distillers with preferential tariff treatment.
- Ready-to-drink cocktail formulation:Beverage manufacturers are expanding tropical-flavored product lines, pulling coconut alcohol volumes into pre-mixed spirits categories previously dominated by neutral grain ethanol.
- Thailand's integrated processing clusters:Plantation-to-bottle infrastructure in Samut Sakhon and Surat Thani provinces compresses logistics costs and secures year-round sap supply for export-focused distilleries.
Market Restraints
- Fermentation feedstock competition:Biofuel diversion policies in Indonesia and the Philippines are tightening coconut sap availability, forcing distillers to compete with biodiesel refiners for raw material access.
- EFSA additive thresholds:European flavor compound restrictions limit ester profile customization for coconut alcohol bound for EU beverage markets, constraining product differentiation.
- Synthetic coconut flavor substitution:Laboratory-derived lactones and esters from petrochemical feedstocks undercut natural coconut alcohol pricing in mass-market personal care applications.
Strategic Opportunities
- Clean-label cosmetics manufacturing:Southeast Asian formulators are replacing synthetic preservatives with coconut alcohol-derived natural alternatives, opening margin-rich solvent contracts.
- Carbon certification premiums:EU Green Deal-aligned carbon border adjustments reward coconut alcohol producers with verified low-emission fermentation processes.
- Direct-to-mixologist distribution:Specialty spirits distributors are bypassing traditional retail channels to place craft coconut rums directly in high-end bar programs across London, New York, and Singapore.
Industry Challenges
- Yeast strain IP licensing:Proprietary tropical yeast cultures optimized for coconut sap fermentation are locked behind exclusive biotech licensing agreements, limiting new entrant access.
- Legacy equipment retrofit costs:Stainless steel fermentation tanks designed for grain ethanol require material upgrades to handle coconut sap's higher acidity and mineral content.
- Multi-jurisdiction labeling synchronization:Simultaneous FDA, EFSA, and Thai FDA compliance creates documentation bottlenecks for exporters serving multiple regulatory regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Alcohol Market |
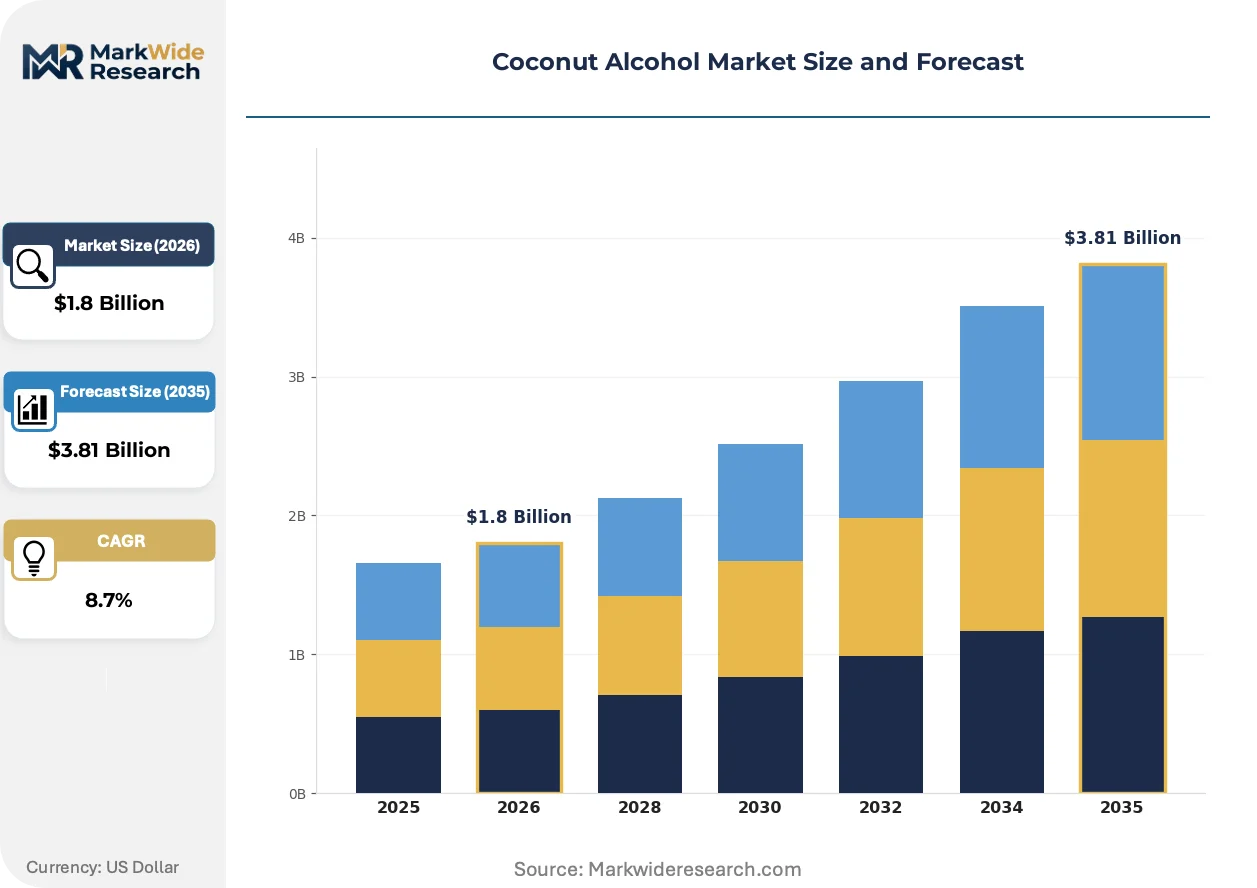
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Coconut, Flavored Coconut, Blended Coconut, Organic Coconut End Use: Beverages, Culinary, Personal Care, Pharmaceuticals Packaging Type: Bottles, Cans, Tetra Packs, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Island Distillers, Bacardi, Hunter Distilleries, Thai Coconut Public Company Limited, Aluna Coconut Rum, St. Lucis Distillers Group of Companies, Malibu, Worthy Park Estate, Demerara Distilleries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Alcohol Market Emerging Trajectories
Precision fermentation technologies and regulatory carbon accounting are rewriting production economics for coconut alcohol, while demand-side purchasing consolidation is compressing supplier margins.
Enzymatic sap clarification is bifurcating the upstream processing tier. Membrane filtration systems replace traditional heat-based concentration, preserving volatile esters that define premium spirit character. Thai and Vietnamese distillers adopting cold-clarification are capturing price premiums in European craft cocktail channels while heat-processed volumes commoditize in bulk solvent markets.
REACH registration deadlines for imported bio-based solvents are tightening documentation requirements for coconut alcohol entering EU cosmetics manufacturing. ECHA substance evaluation protocols now demand full supply chain traceability from plantation through distillation. German and Dutch formulators are consolidating supplier lists to pre-registered producers with complete dossier compliance, excluding smaller tropical distillers from contract consideration.
Mixology-focused retailers are consolidating shelf space around story-driven tropical spirits, displacing legacy rum-coconut blends without provenance narratives. Specialty beverage buyers in Melbourne, Copenhagen, and Los Angeles now require single-origin certification and harvest-date transparency as standard procurement criteria. This specification creep favors integrated plantation-distillery operations over commodity traders.
Coconut Alcohol Market Segmentation
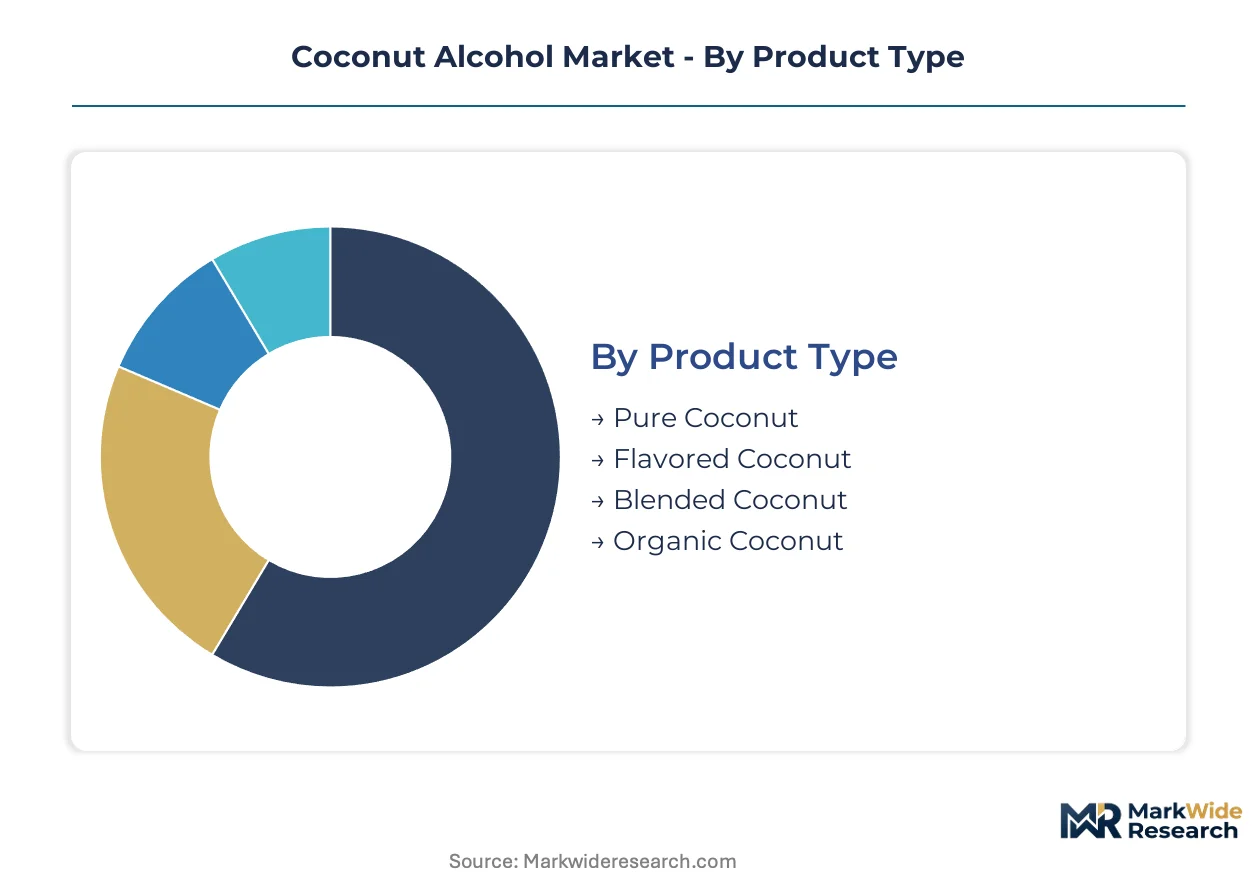
Coconut alcohol producers face divergent substitution threats across product tiers. Synthetic flavor compounds and grain-based ethanol alternatives exert pressure on commodity segments while certified organic and provenance-verified lines defend margin pools through regulatory differentiation.
Product Type:
Synthetic lactone substitutes from petrochemical feedstocks threaten mass-market segments most aggressively, forcing natural-origin segments to justify premiums through certification and traceability infrastructure.
- Flavored Coconut:Ethanol bases infused with coconut-derived ester compounds achieve 20-40% ABV with characteristic tropical aromatic profiles. Ready-to-drink cocktail manufacturers in Thailand and the Philippines concentrate procurement here, pulling volume as RTD shelf space expands in North American and European retail. EFSA additive thresholds constrain ester customization for EU-bound shipments, limiting formulation flexibility.
- Organic Coconut:Sap harvested from certified pesticide-free plantations with full chain-of-custody documentation. German and Dutch cosmetics formulators drive demand, replacing synthetic preservatives in natural skincare lines. EU Green Deal carbon accounting rewards producers with verified low-emission fermentation, creating tariff advantages at European ports.
- Pure Coconut:Unblended ethanol distilled directly from fermented coconut sap without additive compounds.
- Blended Coconut:Coconut-derived ethanol mixed with neutral grain spirits or other agricultural ethanol sources.
Flavored Coconut anchors the volume base while Organic Coconut gains share at the steepest rate.
End Use:
Application-level profitability splits sharply between regulated pharmaceutical grades and price-pressured personal care commodities.
- Beverages:Tropical cocktail programs and craft spirit formulations requiring specific ester profiles. Mixology-focused retailers in Melbourne, Copenhagen, and Los Angeles now mandate single-origin certification as standard procurement criteria, favoring integrated plantation-distillery operations.
- Personal Care:Natural solvent and preservative applications in Southeast Asian cosmetics manufacturing. Synthetic coconut flavor substitution from laboratory-derived lactones undercuts pricing in mass-market applications, compressing margins for non-certified producers.
- Culinary:Extraction solvent for flavor compounds and food-grade alcohol applications.
- Pharmaceuticals:High-purity ethanol meeting pharmacopeial standards for drug formulation and medical disinfectants.
Beverages commands the largest revenue pool while Personal Care expands most quickly on natural preservative substitution trends.
Packaging Type:
Format selection tracks channel requirements and shelf-life demands across diverging end-use specifications.
- Bottles:Glass and PET containers for premium spirits and pharmaceutical grades. Specialty stores and direct-to-mixologist distributors favor this format for brand storytelling and provenance display.
- Cans:Aluminum packaging for ready-to-drink cocktail formats targeting convenience retail and outdoor consumption occasions.
- Tetra Packs:Aseptic cartons for bulk culinary and industrial solvent applications.
- Pouches:Flexible film packaging for travel retail and sample-size personal care formulations.
Bottles dominate value capture while Cans climb fastest on RTD category growth.
Distribution Channel:
Channel strategy determines margin retention and brand control intensity for producers at varying scale.
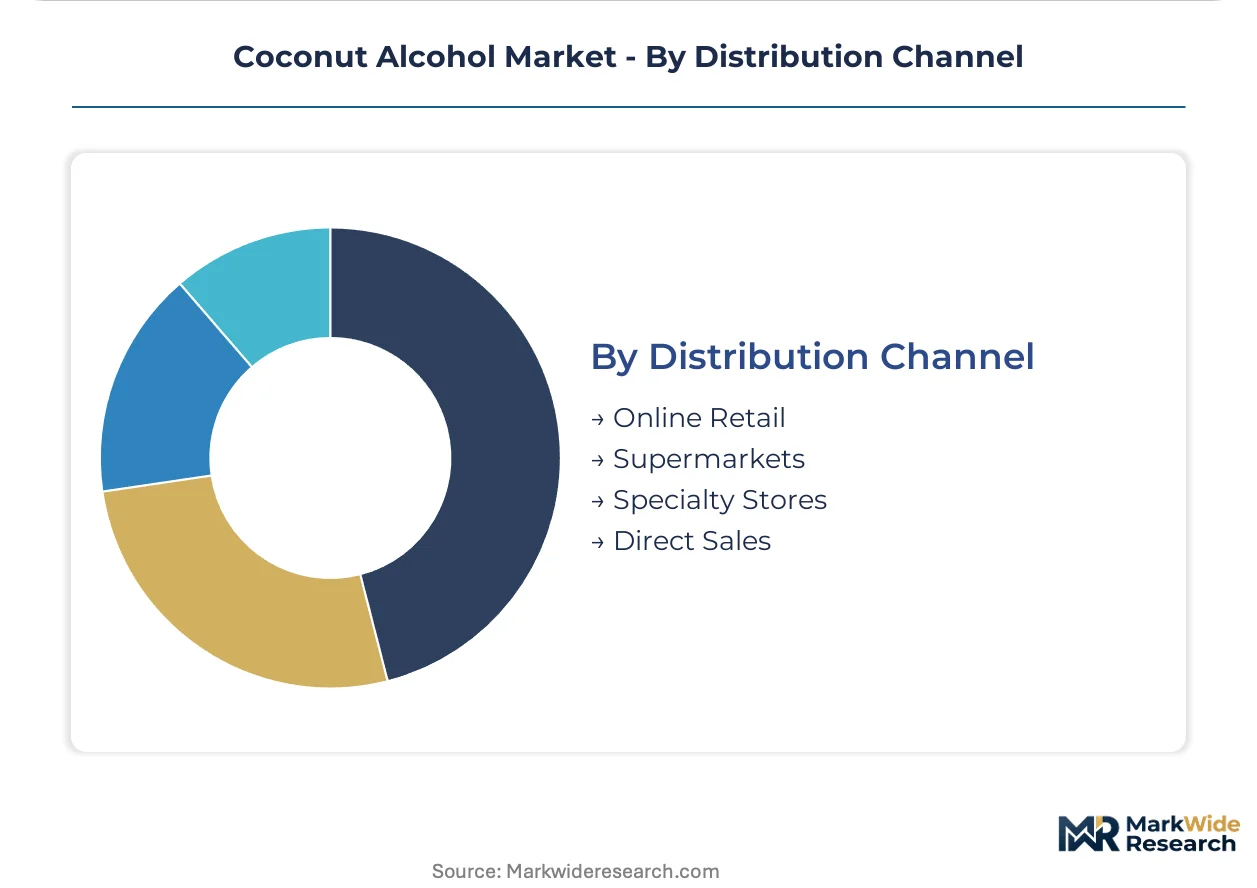
- Specialty Stores:Curated spirits retailers and mixology-focused independents in London, New York, and Singapore. Direct relationships with bar programs enable premium pricing and harvest-date transparency that commodity channels cannot replicate.
- Online Retail:E-commerce platforms capturing direct consumer access for craft and certified organic lines. Documentation bottlenecks from multi-jurisdiction labeling requirements create compliance friction for smaller distillers.
- Supermarkets:Mass retail placement for standard-grade flavored and blended products.
- Direct Sales:Plantation-to-customer contracts for bulk pharmaceutical and cosmetics manufacturing buyers.
Specialty Stores capture the highest margin per liter while Online Retail scales fastest on digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Bangkok's deep-water container terminals anchor Thailand's export dominance, moving bulk coconut alcohol to European cosmetics formulators and North American beverage distributors under streamlined customs protocols.
Thailand
Samut Sakhon and Surat Thani provinces host plantation-to-bottle clusters that compress logistics costs for export-focused distilleries. The central agricultural regulator enforces coconut origin certification affecting EU-bound shipment eligibility. Cold-clarification membrane filtration systems in Surat Thani preserve volatile esters for premium European craft cocktail channels.
United States
FDA labeling standards govern import access for coconut alcohol entering beverage and personal care formulations. Mixology-focused retailers in Los Angeles and New York now mandate single-origin certification as standard procurement criteria. Specialty spirits distributors bypass traditional retail channels to place craft coconut rums directly in high-end bar programs.
Germany
EFSA additive thresholds shape flavor compound formulation choices for European-bound coconut alcohol shipments. German cosmetics formulators consolidate supplier lists to pre-registered producers with complete REACH dossier compliance. The Port of Hamburg handles bulk solvent imports for natural preservative applications in clean-label skincare manufacturing.
Netherlands
EU Green Deal carbon border adjustments reward producers with verified low-emission fermentation processes. Rotterdam's bio-based chemical hub distributes coconut alcohol-derived solvents to cosmetics manufacturers across the Benelux region. Dutch formulators replace synthetic preservatives with natural alternatives, opening margin-rich contract opportunities for certified exporters.
Philippines
Biofuel diversion policies tighten coconut sap availability as distillers compete with biodiesel refiners for raw material access. Traditional heat-based concentration methods in Quezon Province commoditize volumes for bulk solvent markets. The Department of Agriculture monitors feedstock flows between fermentation and energy conversion applications.
Coconut Alcohol Market Vendor Landscape
Listed leaders compete with private specialists across certification and provenance vectors, producing a tiered structure where scale-driven multinationals anchor volume while plantation-integrated operators capture premium margins. Three archetypes dominate: integrated plantation-distilleries with captive raw material supply, global spirits conglomerates with rum-coconut blending capabilities, and craft specialists targeting mixology channels. Capacity expansion and carbon certification investments represent the dominant competitive moves as EU Green Deal compliance reshapes sourcing standards.
Within the integrated plantation tier, Thai Coconut Public Company Limited exemplifies upstream control over raw material flows from harvest through distillation. Among global spirits conglomerates, Bacardi and Malibu occupy positions defined by established Caribbean sourcing networks and beach-lifestyle brand positioning. These three entities represent distinct strategic approaches to navigating fermentation feedstock competition and regulatory carbon accounting requirements.
| Leading Market Players |
|---|
| Island Distillers |
| Bacardi |
| Hunter Distilleries |
| Thai Coconut Public Company Limited |
| Aluna Coconut Rum |
| St. Lucis Distillers Group of Companies |
| Malibu |
| Worthy Park Estate |
| Demerara Distilleries Limited |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon certification gates both supplier qualification and price differentiation simultaneously, forcing distillers to invest in traceability infrastructure that separates premium organic tiers from commoditized heat-processed volumes. This regulatory filter compresses margins for non-certified producers while rewarding early adopters with preferential tariff treatment at European ports.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with beverage manufacturers securing long-term offtake agreements for standard-grade blended coconut alcohol while craft spirits distributors pay spot premiums for single-origin certified lines. Price differentiation hinges on organic certification status and cold-clarification processing method, with membrane-filtered volumes commanding substantial markups in European mixology channels. Cost compression in mass-market personal care segments is intensifying as synthetic lactone substitutes from petrochemical feedstocks undercut natural-origin pricing. Pharmaceutical and cosmetics formulators show least price sensitivity, prioritizing REACH dossier completeness and harvest-date transparency over per-liter cost.
Supply Chain Analysis
Just-in-time sap delivery from plantation clusters in Thailand's Samut Sakhon and Surat Thani provinces competes with strategic stockpiling by integrated distillers buffering against monsoon season supply interruptions. Geographic supply concentration centers on Thailand, Indonesia, and the Philippines, with fermentation feedstock flows increasingly diverted to biodiesel refiners under biofuel mandate policies. Raw material dependencies encompass coconut sap, proprietary tropical yeast strains, and stainless steel fermentation equipment upgraded for acidic sap handling. Single-source vulnerability from plantation-to-bottle concentration in Surat Thani Province creates disruption risk from extreme weather events. Distribution runs through deep-water container terminals at Bangkok and Rotterdam, with specialty spirits bypassing traditional retail through direct-to-mixologist channels in London, New York, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of integrated plantation-distillery operations with full REACH dossier compliance defines competitive advantage in this market, as German and Dutch cosmetics formulators consolidate supplier lists around pre-registered producers with verified low-emission fermentation processes.
For Market Incumbents: Secure carbon certification premiums by accelerating EU Green Deal compliance investments before border adjustment mechanisms fully phase in, and lock in long-term sap supply contracts with Thai plantation cooperatives before biofuel diversion policies tighten feedstock availability further. Synthetic flavor substitution in mass-market personal care segments threatens pricing power, making backward integration into cold-clarification membrane filtration capacity the priority defensive lever. For New Entrants and Emerging Players: Direct-to-mixologist distribution gaps in Copenhagen, Melbourne, and Singapore offer white-space entry points where incumbents under-serve story-driven provenance requirements. The most penetrable segment sits in craft cocktail channels mandating single-origin certification, where specialty spirits distributors bypass retail entirely. A focused go-to-market angle targets harvest-date transparency and small-batch fermentation narratives that commodity traders cannot replicate. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with under-monetized coconut processing assets lacking independent distillation capabilities and export registration. Long-term viability favors plantation-integrated operators with captive sap supply and existing EU import clearance, positioned to capture structural shift toward natural preservatives in Southeast Asian cosmetics manufacturing. The signal to watch is EFSA additive threshold tightening, which would accelerate consolidation toward dossier-complete producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive sap supply from Thai cooperatives secures feedstock priority ahead of biodiesel competition. |
| REACH Dossier Completion | Full ECHA substance registration unlocks German and Dutch cosmetics formulator supplier lists. |
| Cold-Clarification Capacity Expansion | Membrane filtration systems in Surat Thani capture European craft cocktail price premiums. |
| Direct-to-Mixologist Distribution Partnerships | Bypassing retail channels places craft coconut rums directly in London and New York bar programs. |
| Carbon Certification Investment | Verified low-emission fermentation processes qualify for EU Green Deal tariff advantages at Rotterdam. |
Methodological Framework
The analysis maps flavored coconut, organic coconut, pure coconut, and blended coconut product tiers, each validated through plantation managers, distillery operations directors, cosmetics formulators, and specialty spirits distributors. Primary interviews with Thai Coconut Public Company Limited upstream controllers, Bacardi blending specialists, and German REACH consultants combined with secondary validation from ECHA substance databases, Thai FDA export registrations, and EU customs import classifications. Bottom-up volume builds from plantation sap yield estimates triangulate against top-down beverage industry ethanol consumption benchmarks.
Consistency checks against external trade flow data and customs valuation records validated projection outputs across the analysis window. Segmentation dimensions modeled encompass product type, end-use application, packaging format, and distribution channel, with additional granularity on certification grade and processing method. CAGRs derived from historical volume trajectories and elasticity-adjusted demand curves incorporate biofuel diversion policy scenarios and EFSA additive threshold evolution as industry-specific forecast inputs.
Material uncertainties — fermentation feedstock competition from biodiesel mandates, EFSA flavor compound restriction tightening, and synthetic lactone substitution rates in personal care — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory implementation timing and clean-label cosmetics adoption curves. Revision becomes warranted when biofuel diversion policy intensity crosses thresholds that structurally reallocate coconut sap supply away from distillation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Guerbet Alcohols Market