
 Greenhouse Heaters Market | 2026-2036
Greenhouse Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse Heaters Market Outlook
A shortage of certified HVAC technicians with greenhouse-specific expertise is redrawing competitive boundaries across the sector. Munters leverages its decades of climate systems integration to sustain premium positioning in large-scale installations. L.B. White Company anchors the North American market through portable propane heater specialization for mid-size operations. Hort Americas competes on channel control, stocking specialized equipment for commercial growers across diverse regional climates.
Greenhouse heaters are thermal management devices engineered to maintain optimal growing temperatures typically between 18°C and 24°C for sensitive crops, utilizing combustion, electric resistance, or hydronic heat distribution methods. These systems prevent frost damage, extend growing seasons, and enable year-round production in controlled environment agriculture. Electric technology segments are capturing margin pools where grid decarbonization aligns with grower sustainability commitments, while natural gas fuel types still dominate installed base economics in regions with pipeline infrastructure. Commercial growers represent the most structurally concentrated end user segment, with research institutions forming a smaller but specification-influential demand pocket.
The EPA regulates combustion emissions from propane and natural gas greenhouse heaters under stationary source standards, while OSHA sets workplace exposure limits for carbon monoxide in enclosed agricultural facilities. The EU F-Gas Regulation and national building codes in member states constrain refrigerant-based heat pump alternatives, indirectly shaping heater technology selection. Stakeholders must monitor evolving carbon pricing mechanisms and utility rebate programs that will determine total cost of ownership calculations across fuel type choices.
Market Dynamics
The EU F-Gas Regulation and tightening carbon pricing mechanisms are forcing a technology transition away from high-emission combustion systems toward heat pump and electric alternatives, compressing margins for incumbent equipment suppliers while opening premium positioning for climate-integrated system architects.
Growth Catalysts
- Almería Vegetable Cluster Expansion:Spain's concentrated protected agriculture zone requires reliable thermal infrastructure for year-round tomato and pepper production, driving replacement cycles and capacity additions.
- Grid Decarbonization Alignment:Electric resistance and heat pump technologies capture specification share where renewable electricity procurement meets grower sustainability certification requirements.
- Netherlands Climate-Controlled Acreage Growth:Dutch commercial operators expand high-tech greenhouse square footage for export-oriented floriculture and specialty crops, sustaining demand for precision thermal management.
Market Restraints
- Natural Gas Infrastructure Lock-In:Regions with established pipeline networks face sunk-cost economics that slow fuel-switching timelines despite carbon price exposure.
- Certified Technician Scarcity:The shortage of HVAC specialists with greenhouse-specific climate integration skills constrains installation capacity and extends project lead times.
- Heat Pump Refrigerant Constraints:EU F-Gas phasedown schedules limit available working fluids for low-temperature heat pump alternatives, indirectly preserving combustion equipment demand.
Strategic Opportunities
- Research Institution Specification Influence:University agricultural extension programs and plant science facilities shape equipment standards that propagate to commercial grower procurement.
- Utility Rebate Program Capture:Electrification incentive structures in decarbonizing jurisdictions create total-cost-of-ownership advantages for electric technology segments.
- Service Contract Attachment:Predictive maintenance and thermal performance guarantees offer recurring revenue streams beyond equipment sale margins.
Industry Challenges
- Legacy System Integration Complexity:Retrofit installations must interface with existing climate control infrastructure, requiring custom engineering and commissioning.
- Multi-Regulatory Compliance Burden:Equipment must simultaneously satisfy EPA stationary source emissions standards, OSHA carbon monoxide exposure limits, and evolving state-level building codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse Heaters Market |
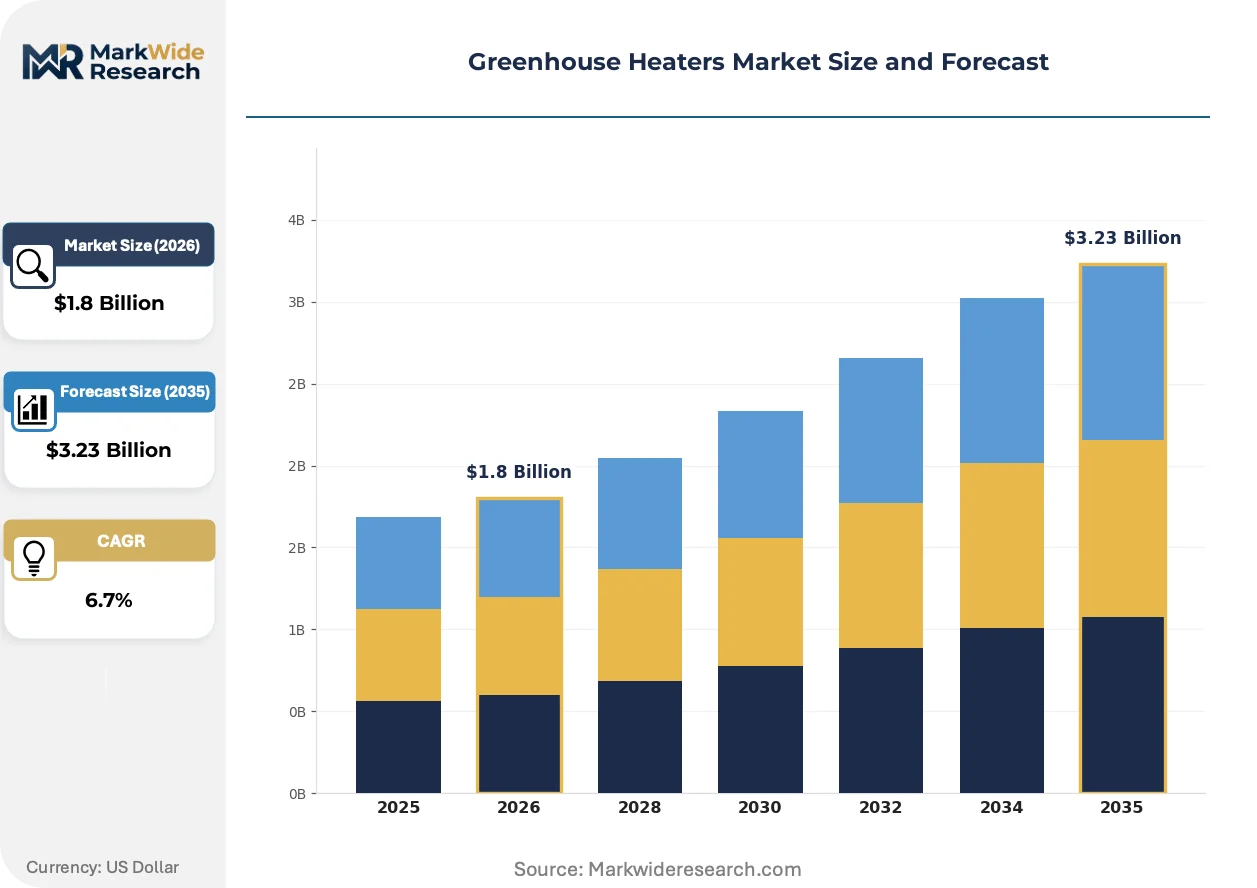
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Convection, Radiant, Hot Water, Electric Fuel Type: Natural Gas, Propane, Biofuels, Electricity End User: Commercial Growers, Residential Hobbyists, Agricultural Producers, Research Institutions Size: Small, Medium, Large, Custom |
| Companies Covered | Lumigrow, Inc., Logiqs B.V., Richel Group SA, Hort Americas, LLC, L.B. White Company, LLC, Argus Control Systems Ltd., Agra Tech, Inc., Munters, Certhon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse Heaters Market Strategic Shifts
Heat pump technology is decomposing the traditional combustion-dominated competitive structure, while regulatory carbon accounting and buyer procurement sophistication accelerate specification shifts toward integrated climate systems.
Modular heat pump architectures are decomposing the centralized boiler paradigm in mid-scale greenhouse operations. Commercial growers in the 5-20 hectare range are adopting distributed thermal units that match zone-specific load profiles. This topology is decomposing the equipment-supplier value chain by elevating controls integration and thermal engineering services over standalone hardware margins.
The EU Green Deal's carbon border adjustment mechanism and national building code revisions are tightening operational emissions accountability for agricultural heating. Dutch growers face mounting compliance costs for natural gas consumption, redirecting capital toward electric alternatives and thermal storage. Spanish operators in Almería are accelerating solar-thermal hybrid configurations to preempt regulatory exposure.
Buyer procurement is consolidating through agricultural cooperative purchasing alliances and integrated greenhouse construction contracts. Large-scale protected agriculture developers in the Netherlands now specify climate systems through engineering-procurement-construction channels rather than direct equipment sourcing. This channel migration compresses distributor margins while rewarding suppliers with turnkey integration capabilities and regional service density.
Greenhouse Heaters Market Segmentation
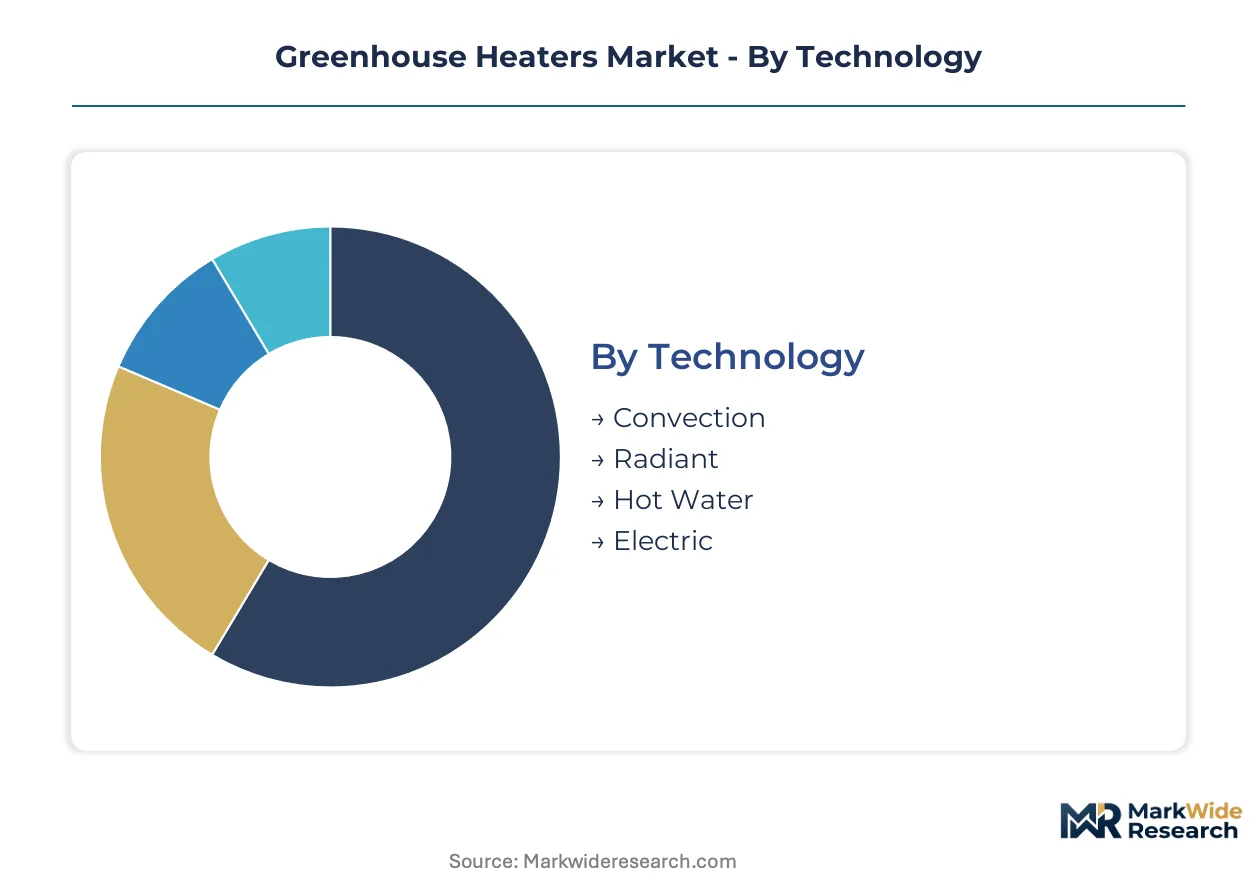
Greenhouse heater procurement patterns diverge sharply across technology and fuel categories, with regulatory carbon accounting and infrastructure availability creating distinct substitution pressures that reshape competitive positioning. Equipment specification increasingly follows end-use scale and certification requirements rather than pure thermal economics.
Technology:
Radiant and convection systems face intensifying displacement pressure from electrified alternatives as carbon pricing mechanisms tighten operational cost differentials across the EU and North American markets.
- Convection:These systems distribute heated air through forced circulation, achieving rapid temperature uniformity in poly-tunnel structures. Dutch commercial operators in the Westland region specify convection units for rapid response to external weather shocks, though rising natural gas costs erode their historical cost advantage.
- Radiant:Infrared emitters target crop canopy zones directly, reducing the thermal mass requiring conditioning. Spanish growers in Almería deploy radiant configurations for tomato and pepper production, cutting fuel consumption by 30% versus air-heating alternatives in high-transpiration environments.
- Hot Water:Hydronic distribution through perimeter piping enables precise zone control and integrates with thermal storage buffers.
- Electric:Resistance and heat pump architectures eliminate on-site combustion, aligning with grid decarbonization trajectories and organic certification requirements.
Convection retains volume leadership; electric holds the steepest expansion curve.
Fuel Type:
Cost tier stratification separates pipeline-connected operators from those dependent on delivered fuels, with carbon border adjustments compressing margins for fossil-dependent segments.
- Natural Gas:Pipeline infrastructure in the Netherlands and Belgium sustains installed-base dominance for large-scale operations. Dutch growers face mounting compliance costs under the EU Green Deal's emissions trading scheme, redirecting capital toward hybrid configurations.
- Electricity:Grid-connected resistance and heat pump systems capture specification share where renewable procurement contracts meet sustainability certification requirements. German commercial operators leverage industrial electricity tariffs to offset higher capital costs.
- Propane:Delivered fuel suits remote installations lacking pipeline access, particularly in North American rural markets.
- Biofuels:Biomass pellet and biogas combustion offers carbon-neutral thermal output for operations with captive feedstock supply.
Natural gas dominates installed capacity; electricity gains share fastest.
End User:
Customer type determines specification complexity, with research institutions and commercial growers driving divergent technology roadmaps through procurement influence.
- Commercial Growers:Large-scale protected agriculture operators in the 10+ hectare range specify integrated climate systems through engineering-procurement-construction channels. Dutch and Spanish cooperatives consolidate purchasing power, compressing distributor margins while rewarding turnkey service capabilities.
- Research Institutions:University agricultural extension programs and plant science facilities demand precision thermal control for experimental reproducibility. Wageningen University specifications propagate to commercial grower procurement through demonstration effects.
- Agricultural Producers:Mid-scale operations balance capital constraints against yield protection requirements.
- Residential Hobbyists:Small-scale greenhouse operators prioritize portability and installation simplicity over thermal efficiency optimization.
Commercial growers command volume concentration; research institutions shape specification trajectories.
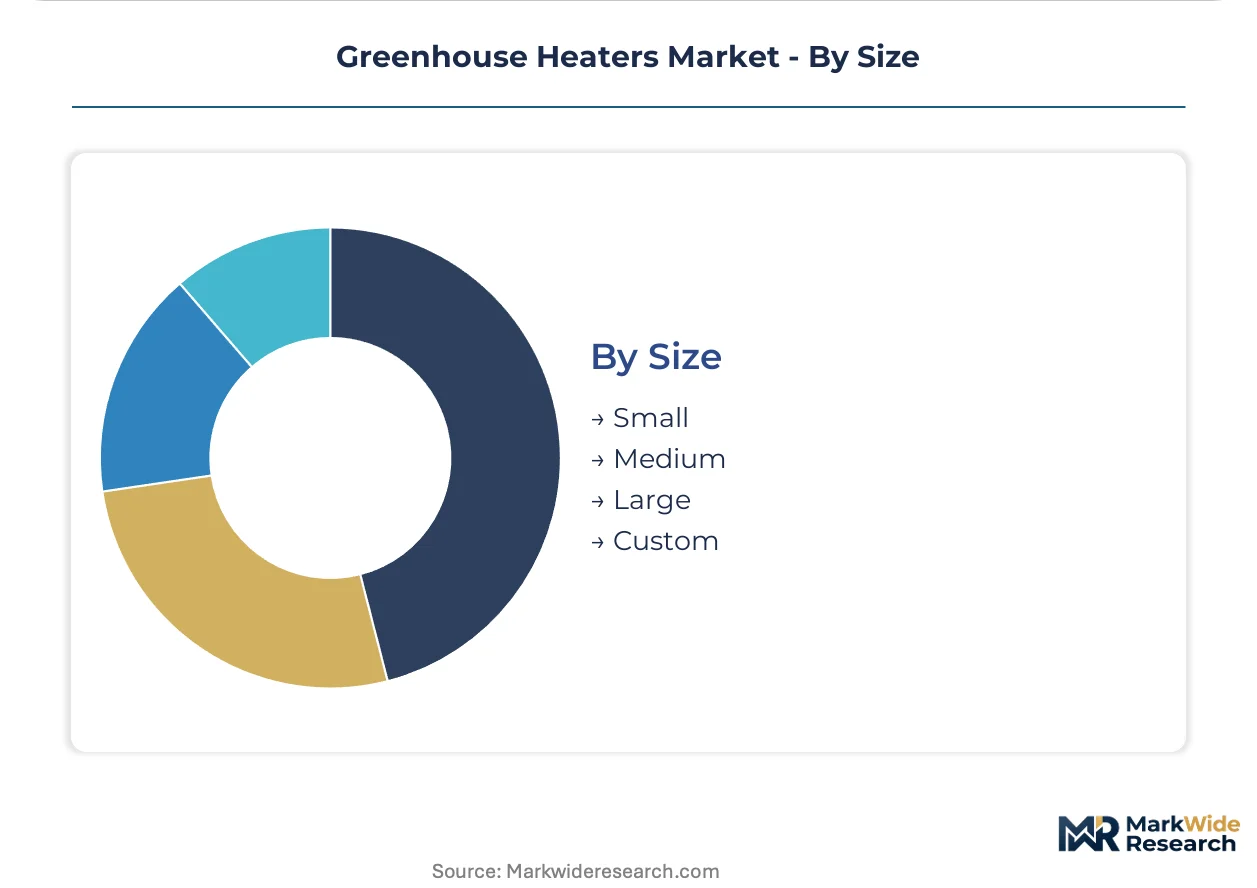
Size:
Scale-based procurement patterns concentrate manufacturing economies in medium-format equipment while custom engineering captures premium margins at installation extremes.
- Large:Centralized boiler and distribution systems serve operations exceeding 20 hectares, requiring thermal engineering services beyond standalone hardware supply. Netherlands-based climate system integrators dominate this segment through regional service density.
- Custom:Retrofit installations and specialty crop requirements demand site-specific thermal load calculations and controls integration. Spanish solar-thermal hybrid configurations exemplify this segment's engineering-intensive character.
- Medium:Standardized 50-200 kW units serve the 5-20 hectare sweet spot with balanced capital and operating economics.
- Small:Portable propane and electric units target residential and small commercial applications with minimal installation complexity.
Medium-format equipment sustains manufacturing scale; custom configurations climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch commercial growers deploy centralized boiler systems for precision climate control, while Spanish operators favor solar-thermal hybrids; North American mid-scale farms rely on portable propane units for flexibility.
Netherlands
Westland and Aalsmeer greenhouse clusters drive concentrated demand for large-scale hydronic distribution systems. The EU Green Deal's emissions trading scheme tightens compliance costs for natural gas consumption. Wageningen University research programs propagate equipment specifications to commercial growers through demonstration networks.
Spain
Almería's protected agriculture zone sustains year-round tomato and pepper production requiring reliable thermal infrastructure. National building code revisions under EU F-Gas Regulation constrain refrigerant-based alternatives. Solar-thermal hybrid configurations accelerate across Andalusian cooperatives to preempt carbon border adjustment exposure.
United States
Mid-scale protected agriculture operations in California and Florida specify portable heating solutions for seasonal flexibility. EPA stationary source standards regulate combustion emissions from propane and natural gas equipment. Central Valley vegetable producers balance capital constraints against frost protection requirements.
Germany
Commercial operators in Lower Saxony and Bavaria leverage industrial electricity tariffs to offset higher capital costs for heat pump installations. The national carbon pricing mechanism tightens operational cost differentials against fossil alternatives. Research institutions at Hohenheim University shape precision thermal control specifications.
Canada
Greenhouse vegetable producers in Ontario and British Columbia face extended heating seasons demanding robust thermal infrastructure. Federal carbon pricing and provincial building codes accelerate electrification timelines. Leamington's concentrated protected agriculture cluster sustains replacement cycles for climate-controlled acreage.
Greenhouse Heaters Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in greenhouse thermal management. Climate system integrators capture premium margins through turnkey engineering-procurement-construction capabilities. Equipment fabricators compete on manufacturing scale and regional service density. Strategic moves concentrate on portfolio diversification toward electrified alternatives and geographic expansion into high-growth protected agriculture clusters.
Within the climate integration tier, Munters exemplifies premium positioning through decades of systems integration expertise. L.B. White Company anchors North American market presence through portable equipment specialization. Hort Americas occupies a channel-control position stocking specialized equipment for diverse regional climates.
| Leading Market Players |
|---|
| Lumigrow, Inc. |
| Logiqs B.V. |
| Richel Group SA |
| Hort Americas, LLC |
| L.B. White Company, LLC |
| Argus Control Systems Ltd. |
| Agra Tech, Inc. |
| Munters |
| Certhon |
| Others |
Value Chain & Pricing Dynamics
Heat pump refrigerant substitution under EU F-Gas phasedown schedules simultaneously redraws component sourcing geography toward Asian chemical manufacturers and compresses pricing power for European incumbent equipment suppliers locked into legacy combustion portfolios.
Pricing Analysis
Long-term offtake contracts dominate procurement for Dutch commercial growers and Spanish cooperative alliances, insulating large-scale operators from spot volatility while mid-scale buyers face project-based pricing with 15-30% premiums for turnkey installation and commissioning services. Price differentiation separates CE-certified integrated climate systems from economy-tier standalone heaters lacking thermal storage compatibility. Cost compression in the natural gas equipment tier intensifies as carbon border adjustments erode operational economics against electric alternatives. Research institutions exhibit lowest price sensitivity due to grant-funded procurement, while residential hobbyists drive volume at economy price points.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for liquefied natural gas shipments to European greenhouse clusters elevates energy security premiums in contract pricing for Dutch and Spanish operators. Component manufacturing concentrates in Germany for precision hydronic controls, China for heat pump compressors, and the Netherlands for climate integration systems. Supply chains draw from copper tubing, aluminum heat exchangers, and semiconductor-based variable frequency drives. Single-source vulnerability concentrates in low-temperature refrigerant supply from Japanese chemical specialists. Distribution runs through engineering-procurement-construction channels for large installations and agricultural cooperative purchasing alliances for mid-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The greenhouse heaters market sits at a technology disruption inflection driven by EU Green Deal carbon pricing mechanisms that compress combustion equipment margins while elevating electrified alternatives.
For Market Incumbents: Compound service contract attachment rates to offset hardware margin compression from electrification transitions. Deepen backward integration into thermal storage buffer manufacturing to capture value migrating from standalone heaters toward integrated climate systems. Defend against modular heat pump entrants by embedding predictive maintenance algorithms into legacy hydronic installations.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in the Netherlands opens specification access to Dutch commercial growers consolidating procurement through cooperative channels. Target Spain's Almería solar-thermal hybrid retrofit segment where incumbent service density remains thin. Pursue university agricultural extension demonstration partnerships to propagate equipment specifications toward commercial grower procurement.
For Investors and Strategic Acquirers: The market sits at an early-cycle electrification phase that favors climate-integrated system architects over standalone equipment fabricators. Long-term viability accrues to platforms combining thermal engineering services with regional installation density. Acquisition targets should demonstrate utility rebate program capture capabilities and turnkey commissioning expertise. Watch EU ETS carbon price trajectories as the signal for combustion equipment demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Licensing | Accelerates electrified portfolio diversification for combustion-dependent incumbents facing EU ETS compliance costs. |
| Regional Service Network Expansion | Captures recurring maintenance revenue from Dutch Westland and Almería greenhouse clusters requiring thermal performance guarantees. |
| Utility Rebate Program Partnerships | Creates total-cost-of-ownership advantages for electric technology segments in German and Canadian decarbonizing jurisdictions. |
| Solar-Thermal Hybrid Integration | Preempts carbon border adjustment exposure for Spanish cooperatives while differentiating against pure electric competitors. |
| Research Institution Demonstration Alliances | Propagates equipment specifications from Wageningen University and Hohenheim facilities to commercial grower procurement channels. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EU ETS regulatory filings, F-Gas Regulation implementation reports, and greenhouse operator procurement databases. Primary interviews engaged climate system integrators, commercial grower cooperative procurement managers, HVAC contractor technical leads, and agricultural extension researchers across the Netherlands, Spain, Germany, and North America. Secondary validation drew from national building code revisions, utility electrification incentive program disclosures, and protected agriculture acreage statistics. Bottom-up equipment shipment data triangulates against top-down energy consumption modeling for thermal management in controlled environment agriculture.
Segmentation dimensions modeled span technology type, fuel source, end-user scale, and installation format across the projection horizon. Value outputs integrate capital equipment, installation services, and recurring maintenance contract streams. CAGRs derive from regression analysis against carbon price trajectory scenarios and renewable electricity penetration assumptions. Industry-specific forecast inputs include greenhouse construction permit data from Dutch municipalities and solar-thermal hybrid adoption rates from Andalusian agricultural cooperatives.
Underlying assumptions cover EU ETS price continuity, grid decarbonization trajectories, and refrigerant supply availability, with deviation risk concentrated in F-Gas Regulation enforcement timing and utility rebate program duration. Practitioners should keep alternative scenarios live as national carbon pricing mechanisms and heat pump technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Electric Pruning Shears Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Industrial Potato Graders Market
Agricultural Equipment
Stock Tanks Market