
 Smart Rice Transplanter Market | 2026-2036
Smart Rice Transplanter Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Rice Transplanter Market Insights
Multi-source component sourcing is repositioning supply chain economics for smart rice transplanter manufacturers. KUBOTA leverages its captive hydraulics production to control cost volatility across Asian markets. YANMAR Holdings anchors its position through deep R&D investment in sensor-assisted planting depth algorithms. Mahindra & Mahindra competes on manufacturing scale, extending its India-centric assembly model into Bangladesh and Sri Lanka.
A smart rice transplanter is a precision agricultural machine that automates seedling insertion into paddy fields using GPS guidance, hydraulic transplanting arms, and real-time soil resistance sensors to achieve consistent planting depth and spacing. Its commercial purpose centers on eliminating yield loss from uneven manual planting while reducing labor dependency during narrow seasonal windows. Fully automatic units command the dominant margin pool as large agricultural firms prioritize throughput over capital outlay, while GPS-based technology leads adoption curves where satellite infrastructure supports sub-inch accuracy. Electric propulsion variants represent the fastest-growing product category, though battery energy density constraints currently limit their deployment to smaller field plots.
Japan's METI enforces JIS standards for autonomous agricultural machinery safety interlocks, directly shaping product design cycles for exporters targeting developed Asian markets. China's MIIT mandates connectivity protocols for IoT-enabled farm equipment, creating compliance barriers that filter non-domestic suppliers from government subsidy programs. India's CEA rural electrification benchmarks indirectly determine viable operating regions for electric transplanter deployment. Stakeholders must weigh certification sequencing across these overlapping regulatory regimes before committing to regional manufacturing footprints.
Market Dynamics
Labor scarcity across Southeast Asian rice belts is compressing seasonal planting windows and forcing equipment procurement decisions toward autonomous systems that eliminate yield variability from manual methods.
Growth Catalysts
- Japan's METI smart agriculture roadmaps:Subsidy frameworks for precision farming equipment accelerate fleet turnover in Kyushu and Tohoku prefectures.
- Sensor-assisted planting depth algorithms:Real-time soil resistance monitoring reduces replanting rates and seedling mortality in compacted paddy conditions.
- Vietnam's Mekong Delta cooperative consolidation:Collective purchasing power enables smallholder access to capital-intensive transplanting systems previously reserved for commercial estates.
Market Restraints
- Battery energy density constraints:Lithium-ion cell limitations restrict electric transplanter operating range to sub-5 hectare plots.
- China's MIIT connectivity mandates:IoT protocol compliance requirements filter non-domestic suppliers from government subsidy eligibility.
- Hydraulic component supply concentration:Captive production at major Japanese manufacturers limits third-party sourcing flexibility for emerging assemblers.
Strategic Opportunities
- Bangladesh's Brahmaputra delta mechanization gap:Minimal existing transplanting equipment penetration creates first-mover positioning for autonomous system vendors.
- Sri Lanka's estate sector consolidation:Large tea-to-rice conversion plantations seek throughput-maximizing equipment for newly irrigated acreage.
- India's PLI scheme for agricultural machinery:Domestic manufacturing incentives reduce landed cost disadvantages for regional assembly operations.
Industry Challenges
- Cross-border certification sequencing:JIS safety interlock requirements and MIIT connectivity protocols demand parallel compliance tracks.
- Legacy fleet retrofit complexity:Mechanical transplanting arms lack standardized mounting interfaces for sensor integration.
- Field technician scarcity:Hydraulic-electronic hybrid systems require diagnostic capabilities absent in traditional agricultural equipment service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Rice Transplanter Market |
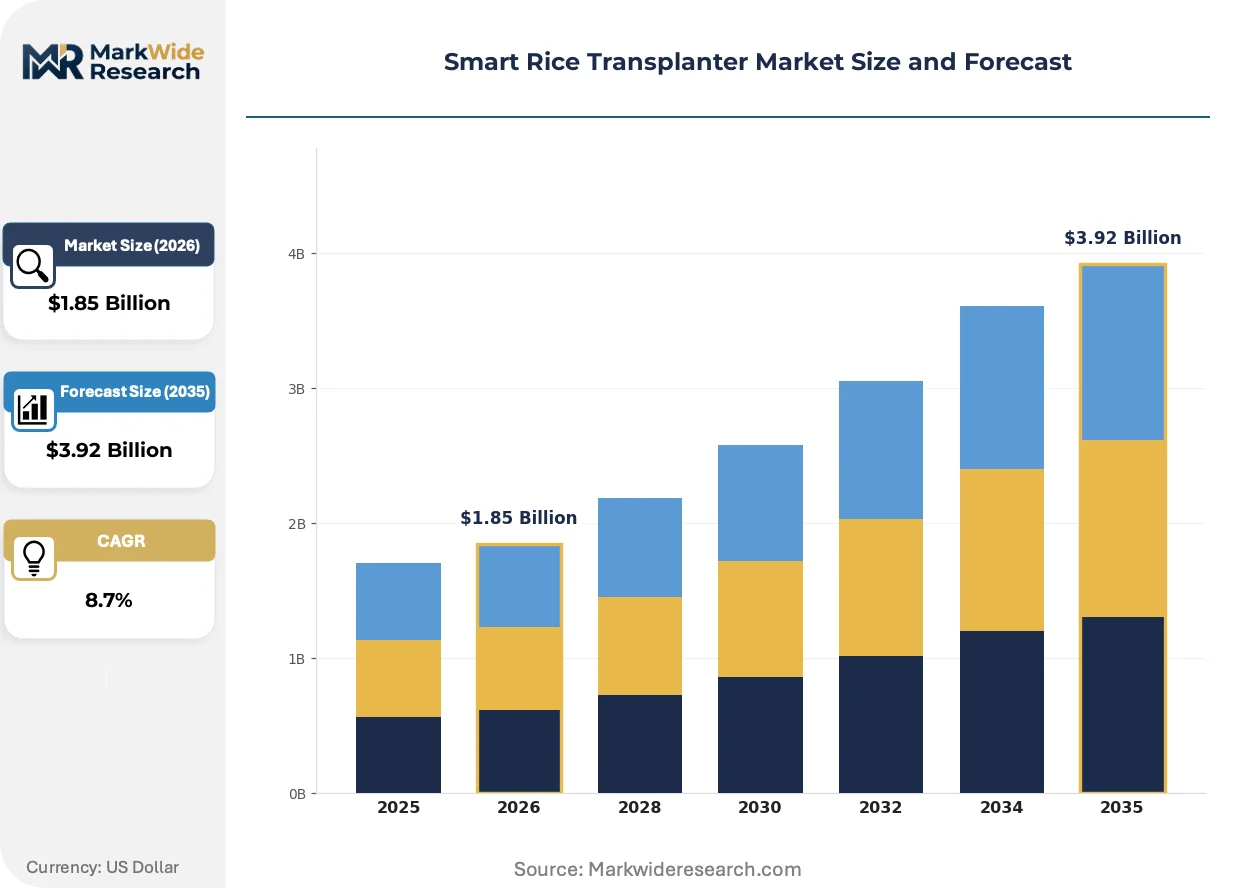
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, Electric Technology: GPS-Based, Sensor-Assisted, Autonomous, IoT-Enabled End User: Smallholder Farmers, Large Agricultural Firms, Cooperatives, Research Institutions Distribution Channel: Direct Sales, Online Retail, Agricultural Equipment Dealers, Trade Shows |
| Companies Covered | ISEKI, Mahindra & Mahindra, KUBOTA, Escorts Kubota, Mitsubishi Agricultural Machinery, FJ Dynamics Technology, Daedong, TYM Corporation, YANMAR Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Rice Transplanter Market Trends and Innovations
Autonomous navigation systems and electric propulsion architectures are redefining equipment specifications across Asian rice production zones, with regulatory mandates accelerating technology substitution cycles.
Electric propulsion variants are electrifying the sub-compact transplanter category. Battery-powered drive trains eliminate hydraulic fluid contamination risks in sensitive paddy ecosystems. Small-scale cooperative buyers in Vietnam and Indonesia are prioritizing these units despite range limitations. The technology is electrifying competitive positioning around total cost of ownership rather than upfront capital expenditure.
China's MIIT mandates connectivity protocols for IoT-enabled farm equipment. The regulation creates compliance barriers that filter non-domestic suppliers from government subsidy programs. Equipment manufacturers must embed domestic communication modules and data sovereignty architectures. Export-oriented assemblers targeting Chinese state procurement channels are restructuring firmware development cycles around these requirements.
Cooperative-led fleet purchasing is displacing individual smallholder acquisition patterns. Collective buying power enables access to capital-intensive autonomous systems through shared depreciation models. Equipment utilization rates under cooperative ownership reach 800+ annual operating hours versus 200-300 for individual holdings. This concentration is most visible in Vietnam's Mekong Delta, where district-level agricultural collectives aggregate demand across 500-2000 hectare planting zones.
Smart Rice Transplanter Market Segmentation
Equipment specification choices in the smart rice transplanter market carry distinct capital implications for buyers across Asian rice belts. Procurement decisions hinge on balancing automation depth against field size constraints and subsidy eligibility requirements.
Product Type:
Capital intensity escalates sharply across this dimension, with autonomous systems commanding multiples of manual unit pricing.
- Manual:Basic mechanical transplanting arms without electronic guidance. Demand persists in Bangladesh's Brahmaputra delta where electrification gaps limit powered alternatives.
- Semi-Automatic:Hydraulically assisted planting mechanisms requiring operator steering. Smallholder clusters in Indonesia's Java highlands favor these units for intermediate plot sizes.
- Fully Automatic:GPS-guided transplanting systems with automated row navigation and depth calibration. Large agricultural firms across Vietnam's Mekong Delta prioritize throughput over capital outlay during compressed seasonal windows.
- Electric:Battery-powered drive trains eliminating hydraulic fluid contamination in sensitive paddy ecosystems. Cooperative buyers in Vietnam and Indonesia accept range limitations for reduced operating costs.
Most installed capacity flows through Fully Automatic systems. Expansion is steepest in Electric variants.
Technology:
Technology selection determines compliance pathways across Japan's METI roadmaps and China's MIIT mandates.
- GPS-Based:Satellite-dependent positioning achieving sub-inch planting accuracy. Deployment concentrates in Japan's Kyushu prefecture where infrastructure supports precision agriculture.
- Sensor-Assisted:Real-time soil resistance monitoring for adaptive depth control. Compact conditions in Vietnam's Mekong Delta drive adoption where replanting rates must be minimized.
- Autonomous:Self-navigating systems eliminating operator presence requirements. Large agricultural estates in Sri Lanka's converted tea-to-rice plantations seek labor-independent throughput.
- IoT-Enabled:Connectivity modules transmitting operational data to centralized fleet management platforms. China's MIIT mandates these architectures for government subsidy eligibility.
Sensor-Assisted systems dominate current installations. IoT-Enabled configurations are climbing the fastest as regulatory mandates accelerate.
End User:
Customer type shapes purchasing aggregation patterns and equipment utilization economics.
- Smallholder Farmers:Individual plot operators below 5 hectares. Manual and semi-automatic units predominate given capital constraints and irregular field geometries.
- Large Agricultural Firms:Commercial estates managing contiguous acreage above 500 hectares. These buyers command premium pricing for fully automatic systems with 24-hour operational capability.
- Cooperatives:Collective ownership structures aggregating demand across 500-2000 hectare zones. Vietnam's Mekong Delta collectives achieve 800+ annual operating hours through shared depreciation models.
- Research Institutions:Agricultural universities and government trial stations. Limited volume but disproportionate influence on regional variety recommendations and subsidy criteria.
Cooperative purchasing channels capture the steepest volume expansion. Large Agricultural Firms retain the dominant share of premium system deployments.
Distribution Channel:
Channel structure reflects equipment complexity and the scarcity of qualified service technicians.
- Direct Sales:Manufacturer-to-buyer transactions for large fleet orders. Japanese manufacturers favor this channel for autonomous system deployments requiring customized training protocols.
- Online Retail:Digital platforms for spare parts and compact manual units. Limited penetration for complete systems given installation and warranty service requirements.
- Agricultural Equipment Dealers:Regional distributors providing field service and parts inventory. These intermediaries dominate in India's fragmented state-level procurement markets.
- Trade Shows:Seasonal exhibitions concentrated around pre-planting windows. Vietnam's Mekong Delta hosts the most significant regional events for cooperative bulk purchasing.
Agricultural Equipment Dealers handle the majority of transaction volume. Direct Sales channels are expanding most quickly for autonomous system categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta dominates procurement volume for autonomous transplanting systems as cooperative consolidation accelerates fleet turnover across Southeast Asian rice belts.
Vietnam
Cooperative-led purchasing in the Mekong Delta aggregates demand across 500-2000 hectare zones, achieving 800+ annual operating hours through shared depreciation models. The Ministry of Agriculture and Rural Development subsidizes precision farming equipment for district-level agricultural collectives. Can Tho and An Giang provinces host the densest concentration of fully automatic system deployments.
Japan
Large agricultural firms in Kyushu and Tohoku prefectures prioritize throughput-maximizing equipment during compressed seasonal windows. METI enforces JIS standards for autonomous agricultural machinery safety interlocks, directly shaping product design cycles for domestic and export markets. Fukuoka prefecture anchors sensor-assisted planting depth algorithm development through concentrated R&D partnerships.
China
State procurement channels drive IoT-enabled transplanter adoption as agricultural mechanization targets intensify under MIIT connectivity mandates. Equipment manufacturers must embed domestic communication modules and data sovereignty architectures to access government subsidy programs. Jiangsu and Heilongjiang provinces concentrate manufacturing capacity for both domestic supply and regional export.
India
The PLI scheme for agricultural machinery reduces landed cost disadvantages for regional assembly operations targeting Bangladesh and Sri Lanka. CEA rural electrification benchmarks indirectly determine viable operating regions for electric transplanter deployment across eastern and southern states. Punjab and Haryana lead fleet adoption among large agricultural estates managing contiguous acreage above 500 hectares.
Indonesia
Smallholder clusters in Java highlands favor semi-automatic units for intermediate plot sizes where capital constraints limit fully automatic procurement. The Ministry of Agriculture's mechanization programs prioritize cooperative formation to replicate Vietnamese fleet purchasing models. West Java's Cianjur and Bandung districts concentrate equipment demonstration trials and technician training infrastructure.
Smart Rice Transplanter Market Competitive Landscape
Global majors compete with regional champions across certification sequencing and captive component supply, producing a tiered structure where Japanese manufacturers control hydraulic system integration while Indian and Korean assemblers compete on manufacturing scale. Three archetypes dominate: integrated hydraulics producers with backward control over critical subsystems, R&D-intensive sensor algorithm developers, and scale-driven regional assemblers leveraging domestic manufacturing incentives. Competitive moves concentrate on parallel JIS-MIIT compliance tracks and cooperative fleet purchasing channel capture.
Among Japanese integrated manufacturers, KUBOTA and YANMAR Holdings anchor the premium tier through captive production capabilities and algorithm development concentration. Mahindra & Mahindra occupies a scale-driven position extending India-centric assembly into neighboring South Asian markets. These three exemplify the strategic divergence between subsystem control, software differentiation, and manufacturing footprint expansion that defines competitive positioning across Asian rice production zones.
| Leading Market Players |
|---|
| ISEKI |
| Mahindra & Mahindra |
| KUBOTA |
| Escorts Kubota |
| Mitsubishi Agricultural Machinery |
| FJ Dynamics Technology |
| Daedong |
| TYM Corporation |
| YANMAR Holdings |
| Others |
Pricing and Supply Chain Analysis
Hydraulic component costs cascade through three pricing tiers as Japanese integrated manufacturers leverage captive production to buffer volatility while emerging assemblers absorb spot-market exposure. KUBOTA and YANMAR Holdings command premium positioning through in-house hydraulics, whereas Indian and Korean competitors face margin compression from third-party sourcing dependencies.
Pricing Analysis
Input-cost pass-through from lithium-ion cells and precision sensors intensifies pricing pressure in electric and autonomous categories. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified Japanese systems from MIIT-compliant Chinese configurations and basic semi-automatic units. Price differentiation hinges on certification grade and after-sales service bundling. Cooperative buyers in Vietnam exhibit highest price sensitivity through shared depreciation models, while large agricultural firms in Japan prioritize throughput specifications over capital outlay.
Supply Chain Analysis
Certification gating through JIS safety interlock requirements and MIIT connectivity mandates filters supplier participation across developed Asian markets. Manufacturing concentration centers on Japan, China, and India, with hydraulic systems sourcing from Japanese captive facilities and electronic modules from Chinese domestic vendors. Raw material dependencies include high-grade steel for transplanting arms, lithium-ion cells for electric variants, and precision GPS receivers. Single-source vulnerability in hydraulic component supply creates bottleneck risk. Distribution runs through agricultural equipment dealers with field service capabilities, though direct sales channels expand for autonomous system deployments requiring specialized training protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart rice transplanter market represents a late-cycle quality story as cooperative consolidation across Southeast Asia shifts procurement toward premium autonomous specifications with 800+ hour annual utilization requirements.
For Market Incumbents: Acquire sensor algorithm development capabilities to defend against software-centric entrants from China's agricultural robotics sector. Deepen backward integration into hydraulic subsystems to maintain cost advantage as third-party sourcing costs escalate. Prioritize parallel JIS-MIIT certification tracks to capture subsidy eligibility across Japan and China procurement channels.
For New Entrants and Emerging Players: Cooperative fleet purchasing channels in Vietnam's Mekong Delta offer the most penetrable entry point for capital-constrained assemblers. Target Bangladesh's Brahmaputra delta mechanization gap with semi-automatic units before autonomous system penetration accelerates. Pursue demonstration partnerships with district-level agricultural collectives to establish field-proven performance records.
For Investors and Strategic Acquirers: Consolidation pressure builds where hydraulic-electronic hybrid diagnostic capabilities concentrate among Japanese integrated manufacturers. Long-term viability favors acquirers of algorithm-specialist firms with planting depth optimization IP. Watch cooperative utilization rate thresholds as the signal for autonomous system replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Parallel Certification Investment | Dual JIS-MIIT compliance unlocks subsidy access across Japan and China procurement channels. |
| Cooperative Channel Partnership | Fleet purchasing aggregation in Vietnam's Mekong Delta concentrates volume through shared ownership models. |
| Backward Integration into Hydraulics | Captive production insulates margin from spot-market volatility in precision hydraulic components. |
| Sensor Algorithm Acquisition | Planting depth optimization IP differentiates autonomous systems in compacted paddy conditions. |
| Electric Propulsion R&D | Battery energy density improvements expand addressable plot sizes beyond current sub-5 hectare limits. |
Research Methodology
Bottom-up cooperative purchasing modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with agricultural equipment dealers, cooperative procurement managers, OEM platform engineers, and aftermarket service heads combined with secondary validation from MIIT mechanization reports, METI smart agriculture roadmaps, customs trade data, and SEC filings of listed manufacturers. Triangulation across these sources ensures demand-side and supply-side figures converge.
Input-output matrices map hydraulic component flows, battery cell procurement, and GPS module sourcing against finished equipment production across the analysis window. Segmentation dimensions include automation depth, propulsion architecture, technology tier, end-user type, and distribution channel. CAGRs derive from fitted growth curves applied to cooperative fleet expansion rates and regulatory subsidy trajectories. Forecast inputs incorporate rural electrification benchmarks and seasonal planting window compression indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery energy density breakthroughs and cross-border certification harmonization. Forecasts reflect documented assumptions about cooperative consolidation velocity and subsidy program continuity. A model refresh is warranted upon material change in China's MIIT connectivity mandate enforcement or Japan's METI safety standard revision timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Fly Trap Market