
 Air Seeder Market | 2026-2036
Air Seeder Market Size, Share, and Industry Trends Forecast 2026-2036
Air Seeder Market Insights
The EU Green Deal is realigning air seeder procurement criteria across European agriculture cooperatives. John Deere leverages its integrated precision agriculture platform to sustain technology leadership in electronic control systems. CNH Industrial anchors its competitive position through manufacturing scale across North American and European production facilities. AGCO Corporation differentiates via specialized product lines targeting variable soil conditions.
An air seeder is a pneumatic planting implement that uses pressurized air to convey seed and fertilizer from a central tank to individual openers, typically operating at rates exceeding 12 meters of working width for broad-acre cereal and oilseed establishment. The machine meters product through fluted rollers or positive-displacement wheels, then suspends particles in an airstream for distribution across multiple rows with spacing precision measured in centimeters. Multi-row air seeders occupy the dominant share of unit volume due to their alignment with commercial grain farm scale requirements. Precision air seeders represent the fastest-expanding category as variable-rate technology and section control adoption intensify among yield-focused agriculture producers. Dealer networks remain the primary distribution channel for capital-intensive farm machinery, though direct sales from manufacturers to large cooperatives are gaining structural importance.
The EPA regulates off-road diesel emissions from agricultural equipment under Tier 4 Final standards, compelling manufacturers to integrate after-treatment systems that add cost and complexity to air seeder power units. ISO 7250 and related machinery safety standards govern operator protection and guarding requirements across jurisdictions including the European Union and Australia. Equipment purchasers must evaluate total cost of ownership against regulatory compliance timelines as emission standards tighten and precision agriculture interoperability protocols mature.
Market Dynamics
Precision agriculture adoption among broad-acre grain producers is compressing equipment replacement cycles and forcing manufacturers to integrate variable-rate control systems into base machine configurations.
Growth Catalysts
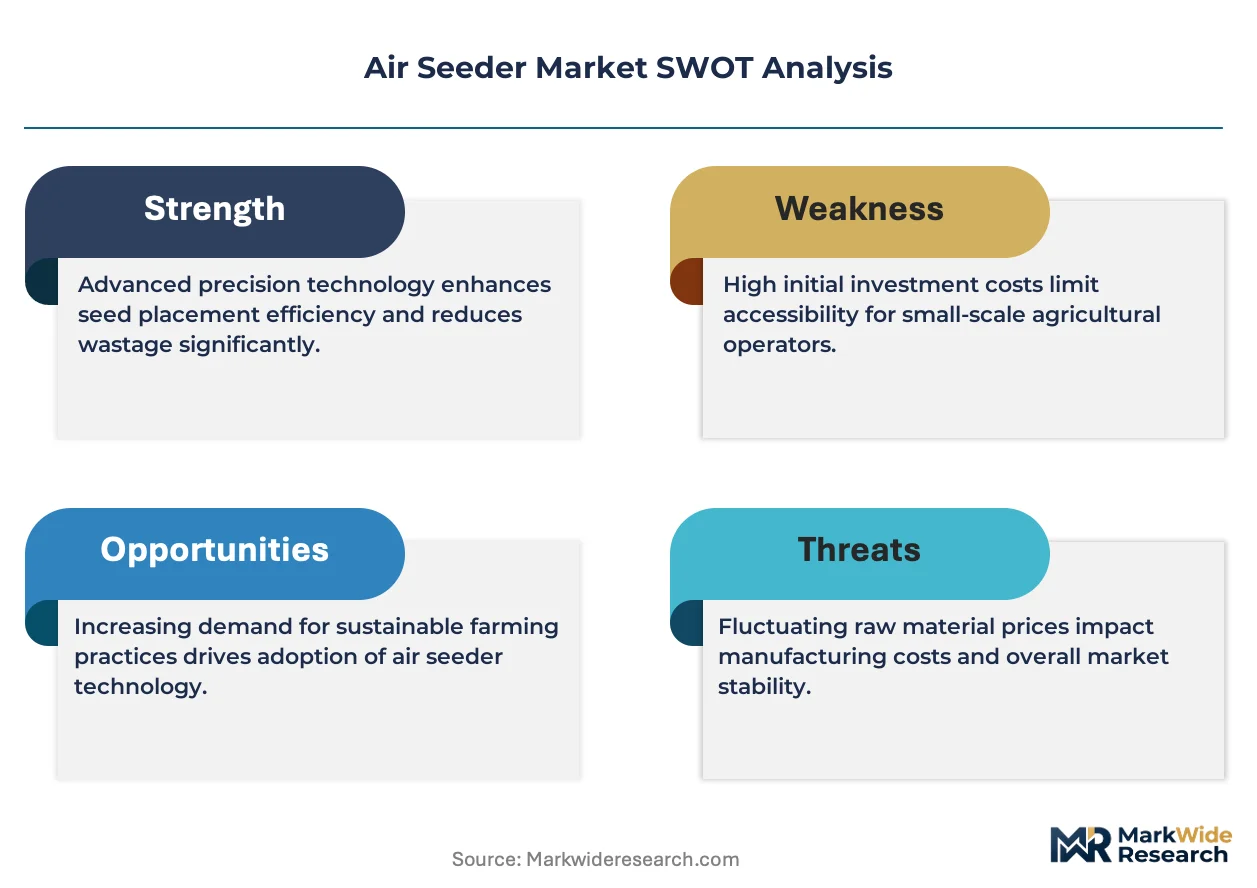
- EPA Tier 4 Final mandates:Emission compliance deadlines in the United States are accelerating fleet turnover as operators replace pre-compliant power units before regulatory deadlines tighten.
- Variable-rate technology:Section control and prescription mapping capabilities are becoming baseline requirements for yield-focused cereal operations across the Canadian prairie provinces.
- Broad-acre consolidation:Farm scale expansion in Australia and Argentina is concentrating demand for 12-meter-plus working widths that only multi-row air seeders deliver.
Market Restraints
- Diesel after-treatment costs:Selective catalytic reduction and diesel particulate filter systems add capital burden and maintenance complexity to power unit specifications.
- Steel and component volatility:Input cost swings for hydraulic cylinders and precision-ground seed meters compress manufacturer margins and destabilize pricing commitments.
- Precision agriculture skill scarcity:Technical proficiency gaps in prescription mapping and telemetry diagnostics limit adoption velocity among smaller commercial operators.
Strategic Opportunities
- EU Green Deal farm sustainability mandates:European agriculture cooperatives face procurement criteria realignment that favors equipment with documented carbon intensity reductions and nutrient placement precision.
- Direct manufacturer-to-cooperative sales:Large-scale grain operations in Brazil and Ukraine are bypassing traditional dealer networks for volume procurement agreements with integrated service packages.
- Telematics and prescription convergence:Machine-generated as-planted data streams are integrating with satellite imagery analytics to enable closed-loop agronomic decision systems.
Industry Challenges
- ISO 7250 safety compliance timelines:Operator protection and guarding requirements across European Union and Australian jurisdictions demand redesign cycles that compress product development schedules.
- Legacy fleet interoperability:Proprietary communication protocols between tractor guidance systems and seeder controllers create integration friction during mixed-manufacturer upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Seeder Market |
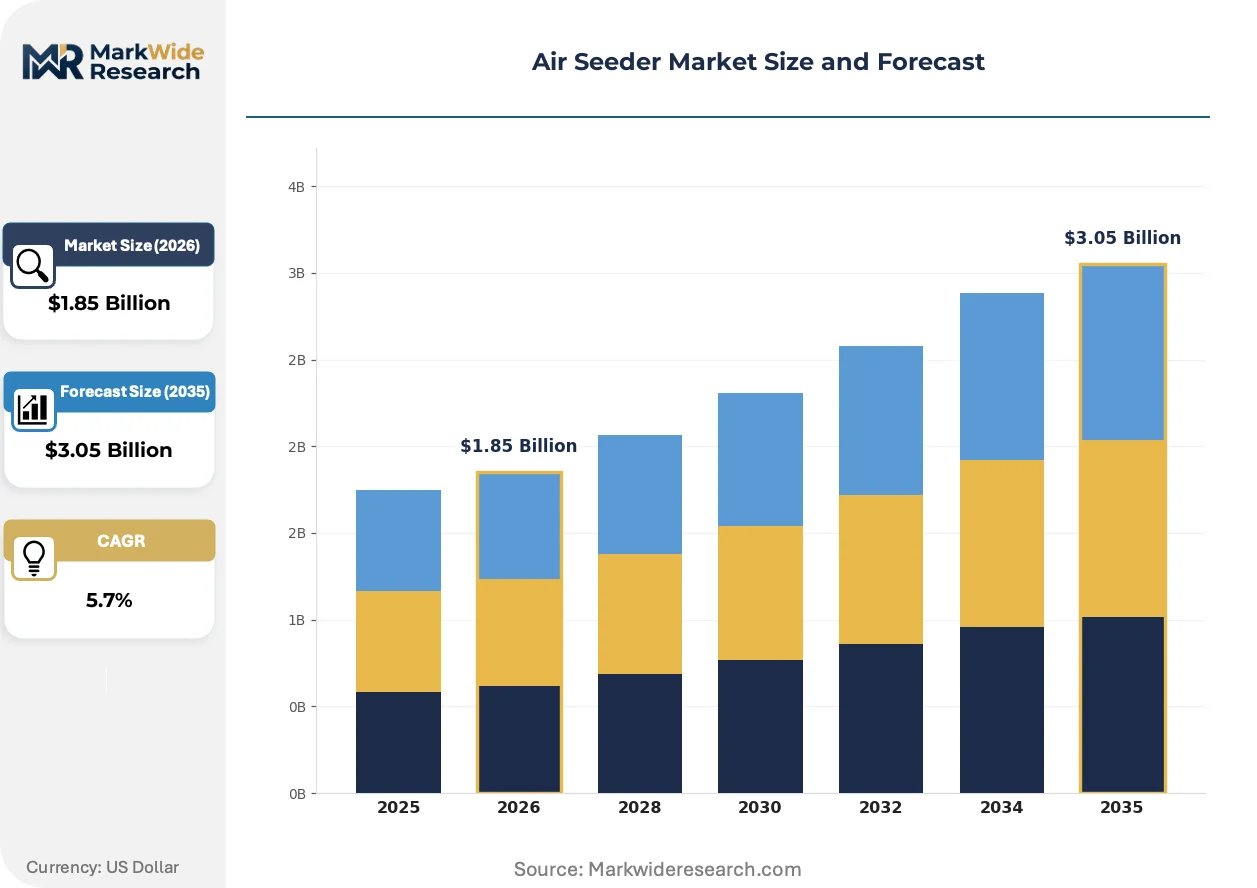
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Row Air Seeders, Multi-Row Air Seeders, Precision Air Seeders, Broadcast Seeders End User: Agriculture Producers, Agricultural Cooperatives, Government Agencies, Research Institutions Distribution Channel: Direct Sales, Retail Distribution, Online Sales, Dealer Networks Technology: Pneumatic Technology, Hydraulic Technology, Mechanical Technology, Electronic Control Systems |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Bourgault Industries, Great Plains, Morris Industries, Amity Technology, HORSCH, Vaderstad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Seeder Market Trends and Innovations
Air seeder architecture is fragmenting along precision capability lines as manufacturers race to embed prescription-ready electronics into mid-tier product families without sacrificing mechanical reliability.
Individual row control technology is modularizing the traditional air seeder value chain. Hydraulic or electric meter drives at each opener enable real-time population adjustments based on soil sensor feedback. Large-scale Saskatchewan and Alberta operations are specifying these systems on new purchases despite 15-20% capital premiums. The technology is modularizing how manufacturers configure product tiers, allowing precision components to slot across economy and premium frames rather than remaining exclusive to flagship lines.
The EU Green Deal's farm sustainability mandates are rewriting equipment specification sheets across European agriculture cooperatives. Carbon intensity disclosure requirements and nutrient use efficiency targets now appear in formal procurement criteria. German and French cereal producers face compliance timelines that favor machines with section control and variable-rate fertilizer placement. Equipment tenders increasingly weight telemetry integration and as-applied data logging alongside traditional mechanical performance metrics.
Service contract unbundling is disrupting capital-intensive machinery distribution patterns. Large cooperatives in the United States and Canada are negotiating direct parts and labor agreements separate from machine purchase transactions, compressing dealer margin structures. Equipment-as-a-service pilots are emerging among 10,000-plus hectare operations in Argentina and Ukraine that prefer operational expenditure treatment for seasonal planting windows. This restructuring is most visible in North American plains states where manufacturer captive finance arms compete with independent lessors on total cost-per-acre metrics.
Air Seeder Market Segmentation
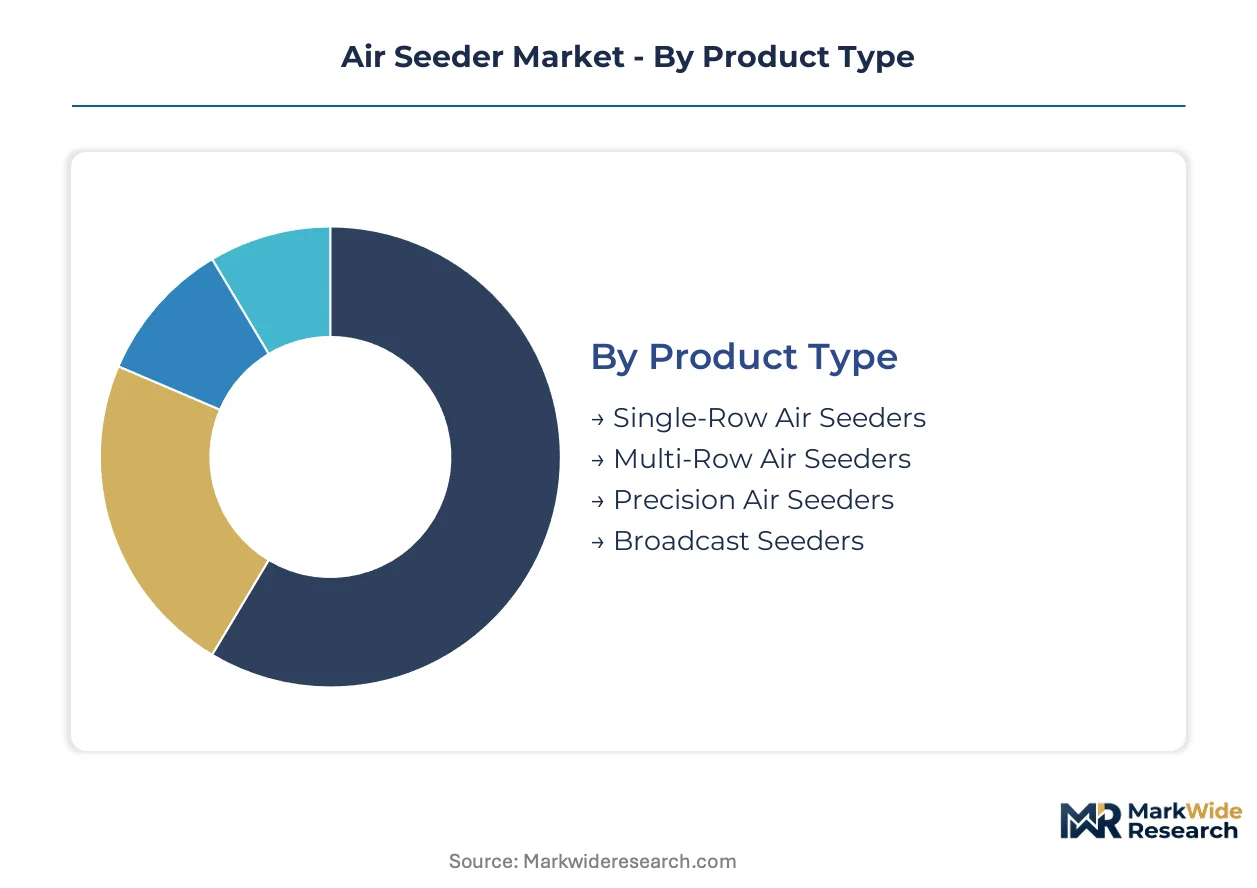
Air seeder procurement patterns diverge sharply between commodity grain operations seeking mechanical reliability and precision-focused producers demanding prescription-ready electronics. Segmentation reveals how manufacturers must configure product tiers across divergent capital investment appetites and technical proficiency levels.
Product Type:
Standardization dominates economy tiers while precision capabilities fragment premium configurations across this product spectrum.
- Multi-Row Air Seeders:These pneumatic implements distribute seed and fertilizer across 12-meter-plus working widths through centralized tanks and pressurized air delivery systems. Prairie grain operations in Saskatchewan and Alberta specify these units for wheat and canola establishment where scale economics override precision requirements. EPA Tier 4 Final compliance deadlines accelerate fleet turnover among operators running pre-compliant power units.
- Precision Air Seeders:Variable-rate technology and section control systems enable real-time population adjustments based on soil sensor feedback. Large-scale Saskatchewan operations absorb 15-20% capital premiums for individual row control capabilities. EU Green Deal nutrient placement mandates are rewriting procurement criteria for German and French cereal producers.
- Single-Row Air Seeders:Compact pneumatic units suit specialty crop producers and research plot applications with sub-meter working widths.
- Broadcast Seeders:Non-pneumatic spreaders serve pasture renovation and cover crop establishment where row precision is secondary to application speed.
Most installed capacity flows through Multi-Row Air Seeders. Expansion is steepest in Precision Air Seeders.
End User:
Customer scale determines whether procurement flows through dealer networks or direct manufacturer negotiation.
- Agriculture Producers:Broad-acre grain farmers in the Canadian prairie provinces and Australian wheat belt drive volume demand for 12-meter-plus working widths. These operators evaluate total cost of ownership against regulatory compliance timelines as emission standards tighten.
- Agricultural Cooperatives:Consolidated purchasing entities in Brazil and Ukraine negotiate volume procurement agreements with integrated service packages. Cooperatives bypass traditional dealer networks for direct manufacturer relationships that include separate parts and labor contracts.
- Government Agencies:Public research stations and extension services acquire specialized equipment for cultivar trials and agronomic studies.
- Research Institutions:University agricultural departments specify single-row and precision configurations for controlled-plot experimentation.
Volume concentrates with Agriculture Producers. Procurement sophistication climbs fastest among Agricultural Cooperatives.
Distribution Channel:
Capital intensity and service requirements shape channel selection across customer tiers.
- Dealer Networks:Traditional agricultural equipment dealerships provide financing, parts inventory, and field service for capital-intensive machinery purchases. These networks retain dominance in North American plains states where manufacturer captive finance arms compete with independent lessors.
- Direct Sales:Large cooperatives and 10,000-plus hectare operations in Argentina and Ukraine prefer operational expenditure treatment through equipment-as-a-service pilots. Direct agreements unbundle service contracts from machine purchase transactions.
- Retail Distribution:Compact broadcast seeders and attachment components move through farm supply retailers serving smaller-scale producers.
- Online Sales:Replacement parts and precision agriculture accessories increasingly flow through manufacturer e-commerce portals.
Transaction value concentrates through Dealer Networks. Structural disruption is most visible in Direct Sales.
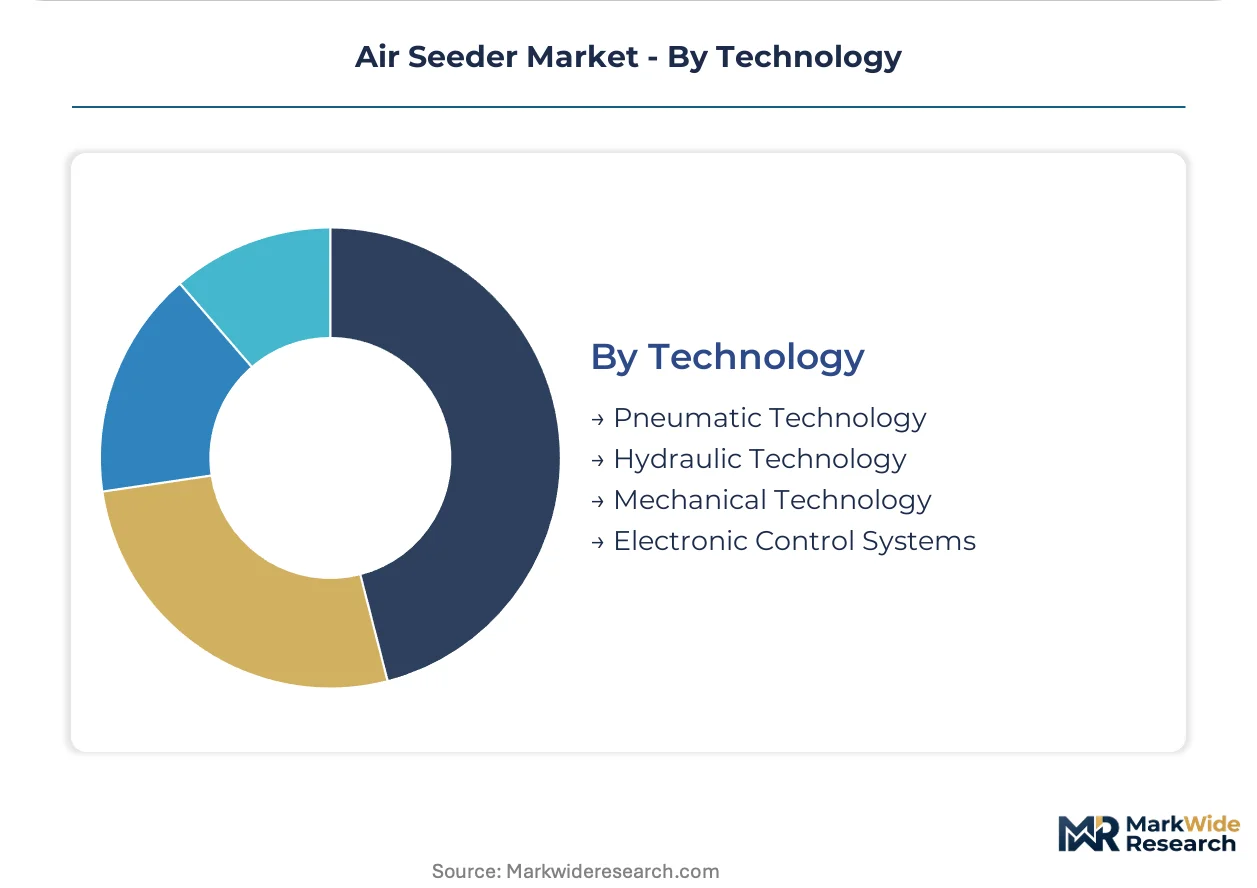
Technology:
Mechanical reliability competes with electronic sophistication for development resources and customer investment.
- Pneumatic Technology:Pressurized air systems suspend seed and fertilizer particles for distribution across multiple rows with centimeter-level spacing precision. This foundational architecture dominates broad-acre cereal and oilseed establishment.
- Electronic Control Systems:Integrated telemetry, prescription mapping, and section control capabilities enable closed-loop agronomic decision systems. ISO 7250 safety compliance timelines and proprietary communication protocols create integration friction during mixed-manufacturer upgrades.
- Hydraulic Technology:Fluid power systems drive meter mechanisms and opener positioning on mid-tier configurations.
- Mechanical Technology:Fluted rollers and positive-displacement wheels persist in economy tiers where electronic complexity introduces maintenance risk.
Installed base runs predominantly on Pneumatic Technology. Capability investment concentrates in Electronic Control Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized equipment operators and precision agriculture technicians concentrate in the Canadian prairie provinces, where broad-acre grain expertise anchors North American demand for multi-row pneumatic systems.
United States
EPA Tier 4 Final compliance deadlines accelerate fleet turnover across the Great Plains states. The USDA Conservation Reserve Program influences planting equipment specifications for participating operators. Kansas and Nebraska equipment clusters see rising specification of variable-rate control systems as base configurations.
Canada
Saskatchewan and Alberta grain operations drive specification of 12-meter-plus working widths for wheat and canola establishment. Environment and Climate Change Canada emission regulations align with federal clean fuel standards for agricultural diesel equipment. Prairie equipment dealerships in Regina and Saskatoon anchor distribution networks serving consolidated broad-acre farms.
Australia
Farm scale expansion across the Western Australian wheat belt concentrates demand for multi-row configurations. The Australian Pesticides and Veterinary Medicines Authority regulates agricultural chemical application equipment standards. Equipment clusters in Perth and Adelaide serve export-oriented grain operations with precision agriculture integration requirements.
Germany
EU Green Deal carbon intensity disclosure requirements reshape procurement criteria for cereal producers. The Federal Motor Transport Authority enforces emission compliance for agricultural machinery power units. Bavarian and Lower Saxony agricultural cooperatives specify section control and variable-rate fertilizer placement in equipment tenders.
Brazil
Large-scale soybean and corn operations in Mato Grosso and Goiás negotiate direct manufacturer agreements bypassing traditional dealer channels. ANVISA regulates agricultural chemical handling equipment standards. The Campo Grande equipment corridor serves 10,000-plus hectare operations seeking operational expenditure treatment for seasonal planting windows.
Air Seeder Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a consolidated vendor base where manufacturing scale determines pricing power. Three to five integrated agricultural equipment conglomerates anchor volume production through captive foundry and assembly operations. Strategic archetypes separate full-line manufacturers with integrated precision platforms from specialized seeder fabricators and regional assembly operations. Competitive moves concentrate on manufacturing footprint consolidation and precision agriculture technology licensing arrangements.
Among North American full-line manufacturers, John Deere, CNH Industrial, and AGCO Corporation represent the integrated equipment conglomerate archetype. John Deere exemplifies the precision platform integrator position through its captive electronics and telemetry systems. CNH Industrial anchors manufacturing scale across transatlantic production facilities. AGCO Corporation occupies a position emphasizing specialized product configurations for variable soil conditions. European specialists including HORSCH and Vaderstad sit within the premium precision tier, while Bourgault Industries and Morris Industries represent Canadian prairie-focused fabrication expertise.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Bourgault Industries |
| Great Plains |
| Morris Industries |
| Amity Technology |
| HORSCH |
| Vaderstad |
| Others |
Pricing and Supply Chain Analysis
Precision agriculture technicians concentrated across Saskatchewan and Manitoba anchor labor-cost differentials that widen pricing-tier spreads between economy pneumatic systems and prescription-ready electronic configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies air seeder procurement based on section control sophistication and telemetry integration depth. Price differentiation hinges on ISO 7250 safety certification tier and after-sales service bundling through dealer networks. Cost compression in economy tiers is intensifying because steel and hydraulic component volatility compresses manufacturer margins. Small-scale commercial operators in Argentina exhibit highest price sensitivity, while 10,000-plus hectare cooperatives in Brazil absorb capital premiums for individual row control capabilities.
Supply Chain Analysis
Dealer-to-farm networks anchored in Regina, Saskatoon, and Winnipeg handle volume demand from prairie grain operations, while direct manufacturer channels serve consolidated cooperatives. Manufacturing concentration spans the United States, Germany, and Canada for precision-ground seed meters and electronic control modules. Component sourcing draws from specialized foundries for hydraulic cylinders and pneumatic distribution heads. Single-source vulnerability in semiconductor supply for telemetry systems creates procurement risk during fleet upgrade cycles. Distribution runs through captive finance arms competing with independent lessors on total cost-per-acre metrics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air seeder market functions as a stable compounder anchored by irreversible farm scale consolidation across broad-acre grain belts.
For Market Incumbents: Anticipate margin compression from diesel after-treatment cost pass-through by deepening backward integration into precision electronics manufacturing. Defend against emerging equipment-as-a-service pilots by unbundling service contracts for large cooperative accounts. Prioritize certification investment in EU Green Deal compliance to capture European procurement realignment. For New Entrants and Emerging Players: Capture white space in retrofit precision kits for legacy multi-row pneumatic fleets across Australian wheat belt operations. Target mid-tier Saskatchewan farms seeking section control without flagship capital outlay. Pursue go-to-market partnerships with independent telemetry providers to bypass established dealer networks. For Investors and Strategic Acquirers: Valuations sit cheapest among Canadian prairie-focused fabrication specialists with proven mechanical reliability but limited precision platform integration. Long-term viability over the next decade favors asset-light designers with modular electronic control architectures. Monitor adoption velocity of prescription mapping capabilities among sub-5,000 hectare operators as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Platform Integration | Embedding variable-rate electronics into mid-tier frames captures yield-focused cereal producers. |
| Backward Integration into Electronics | In-house production of seed meter controllers reduces proprietary protocol friction during upgrades. |
| Equipment-as-a-Service Pilot | Operational expenditure treatment attracts 10,000-plus hectare operations in Argentina and Ukraine. |
| EU Green Deal Certification | Carbon intensity disclosure compliance unlocks German and French cooperative procurement channels. |
| Direct Cooperative Sales Channel | Bypassing dealer networks for volume agreements with Brazilian soybean operations compresses margin structures. |
Research Methodology
Bottom-up agriculture producer modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with equipment dealership principals, OEM procurement teams, aftermarket service heads, and precision agriculture technicians informed demand-side validation. Secondary sources include EPA Tier 4 Final compliance filings, EU Green Deal procurement documentation, Environment and Climate Change Canada emission regulations, and customs records for agricultural machinery trade flows. Triangulation between these sources ensures segmentation integrity across product type, end user, and technology dimensions.
Input-output matrices project unit shipments and average selling prices across the analysis window, with CAGRs derived from regression analysis against farm consolidation rates and regulatory compliance timelines. Segmentation dimensions encompass product tier precision capability, customer scale archetype, distribution channel structure, and regional regulatory cluster. Forecast inputs include EPA emission deadline schedules, EU nutrient placement mandate implementation pace, and telemetry adoption curves among prairie grain operations.
Underlying measurement precision varies by segment; precision air seeder forecasts carry tighter precision than broadcast seeder estimates due to concentrated buyer concentration. Projections reflect assumptions regarding farm scale expansion continuity and emission standard enforcement rigor. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Bean Harvester Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Industrial Potato Graders Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Farm Implements Market