
 Tree Trimmers Market | 2026-2036
Tree Trimmers Market Size, Share, and Industry Trends Forecast 2026-2036
Tree Trimmers Market Analysis
Aftermarket service revenue is fragmenting across dealer networks and direct-to-contractor channels in the tree trimmers market. The Davey Tree Expert Company leverages its national footprint to capture recurring blade-sharpening and engine-maintenance contracts. Bartlett Tree Experts anchors its equipment strategy through captive service depots in major metropolitan zones. Asplundh Tree Expert competes via volume-based fleet arrangements with original equipment distributors.
Tree trimmers comprise handheld, pole-mounted, and portable mechanized cutting devices designed to sever branches and foliage at heights ranging from ground level to approximately 15 feet, utilizing reciprocating blades, rotating cutting lines, or chainsaw chains driven by manual force, electric motors, or two-stroke gasoline engines. Their primary commercial purpose centers on vegetation management for safety clearance, aesthetic shaping, and fire-risk reduction in built environments. Gas-powered trimmers still dominate the product type landscape among municipal and large-scale landscaping operators where runtime and torque requirements exceed current battery capabilities. Battery-powered technology is expanding fastest among residential and commercial landscaping end users as lithium-ion energy density improves and urban noise restrictions tighten. Pole saws occupy a specialized niche with concentrated margins in utility right-of-way maintenance and orchard pruning applications.
OSHA governs worker exposure to vibration and noise in professional tree trimming operations, compelling equipment manufacturers to redesign handles and dampen engine mounts. EPA emissions standards for small spark-ignition engines push gasoline trimmer producers toward catalytic converters and precision fuel injection. Municipalities across California, New York, and Colorado enforce leaf-blower and trimmer noise ordinances that accelerate battery-powered procurement mandates. Stakeholders must monitor the pace of municipal electrification deadlines against the residual performance gap between battery and gasoline platforms in heavy-duty canopy work.
Market Dynamics
Municipal noise ordinances are compressing the gasoline-to-battery transition timeline for professional landscaping fleets, forcing equipment distributors to rebalance inventory mix ahead of lithium-ion runtime parity.
Growth Catalysts
- California Air Resources Board (CARB) small-engine standards:Municipalities across the state accelerate fleet electrification mandates, pulling forward contractor replacement cycles for handheld cutting equipment.
- Urban forestry budget expansion:Cities from Austin to Minneapolis increase canopy management allocations, sustaining demand for pole-mounted and mechanized trimming systems.
- Lithium-ion energy density improvements:Battery pack performance gains enable commercial operators to complete full workdays without range anxiety, narrowing the operational gap with gasoline alternatives.
Market Restraints
- Two-stroke engine component supply concentration:Carburetor and ignition system production clusters in Southeast Asian manufacturing zones, exposing gasoline trimmer assemblers to shipping volatility.
- Battery cell raw material cost exposure:Lithium and cobalt price swings compress margin stability for cordless equipment producers negotiating fixed-price municipal contracts.
- Runtime limitations in heavy canopy work:Battery platforms still underperform gasoline equivalents in sustained high-torque applications above 12-foot cutting heights, constraining utility right-of-way adoption.
Strategic Opportunities
- Orchard mechanization in Washington State:Tree fruit producers seek automated pruning systems to offset seasonal labor scarcity, creating specialized demand for precision pole saws.
- Equipment-as-a-service channel innovation:Rental platforms and dealer-managed fleet programs reduce upfront capital barriers for mid-sized landscaping contractors.
- OSHA vibration exposure standards:Stricter enforcement of hand-arm vibration limits drives replacement demand for ergonomically redesigned handles and dampened drive systems.
Industry Challenges
- Certified small-engine technician scarcity:EPA emission control complexity and precision fuel injection systems require specialized diagnostic skills that vocational programs have not scaled to match.
- Inventory stranding risk:Distributors face write-down exposure on gasoline trimmer stockpiles as municipal electrification deadlines compress effective selling windows.
- Cross-platform battery interoperability:Proprietary battery ecosystems fragment contractor fleet standardization, complicating procurement decisions for multi-brand operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tree Trimmers Market |
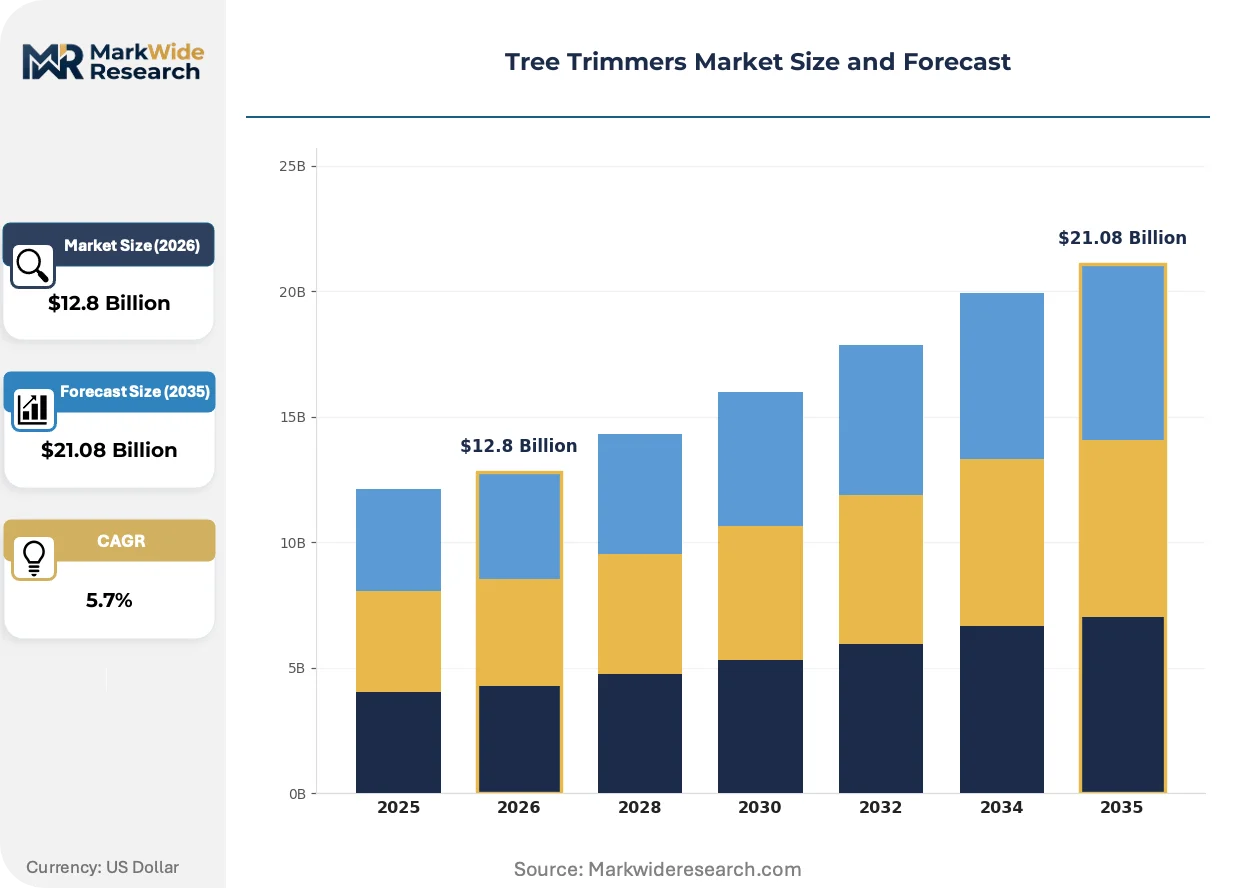
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pruners, Electric Shears, Gas-Powered Trimmers, Pole Saws End User: Homeowners, Landscaping Companies, Municipalities, Property Management Firms Technology: Battery-Powered, Corded, Gasoline, Manual Application: Residential Use, Commercial Landscaping, Urban Forestry, Orchard Maintenance |
| Companies Covered | Summit Tree Care, Bartlett Tree Experts, Asplundh Tree Expert, Yellowstone Landscape, SavATree, The Davey Tree Expert Company, Forest Tree Services, BrightView, Fine Tree Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tree Trimmers Market Emerging Trajectories
Digital connectivity and predictive maintenance capabilities are embedding themselves into professional-grade trimming equipment, shifting value capture from hardware sales toward lifecycle service relationships.
Brushless motor control systems are virtualizing traditional mechanical power transmission in high-end battery trimmers. Commercial landscaping fleets in Colorado and Oregon adopt these platforms fastest, driven by municipal noise restrictions and total cost-of-ownership calculations. The technology is virtualizing dealer service revenue streams as remote diagnostics enable proactive maintenance scheduling before field failures occur.
EPA Phase 3 small spark-ignition engine standards impose stricter emission limits on gasoline-powered handheld equipment. Manufacturers respond with catalytic converter integration and precision port fuel injection, adding cost and complexity to combustion platforms. Municipal procurement offices in Texas and Florida now weight emission compliance scores more heavily in bid evaluations, tilting specification requirements toward cleaner technologies.
Landscaping contractors increasingly unbundle equipment purchases from maintenance contracts, negotiating sharpening and seasonal tune-up services separately from initial acquisition. Independent mobile service technicians capture share from dealer networks in suburban Atlanta and Phoenix markets. This fragmentation pressures original equipment distributors to defend attachment rates through captive financing and extended warranty bundling.
Tree Trimmers Market Segmentation
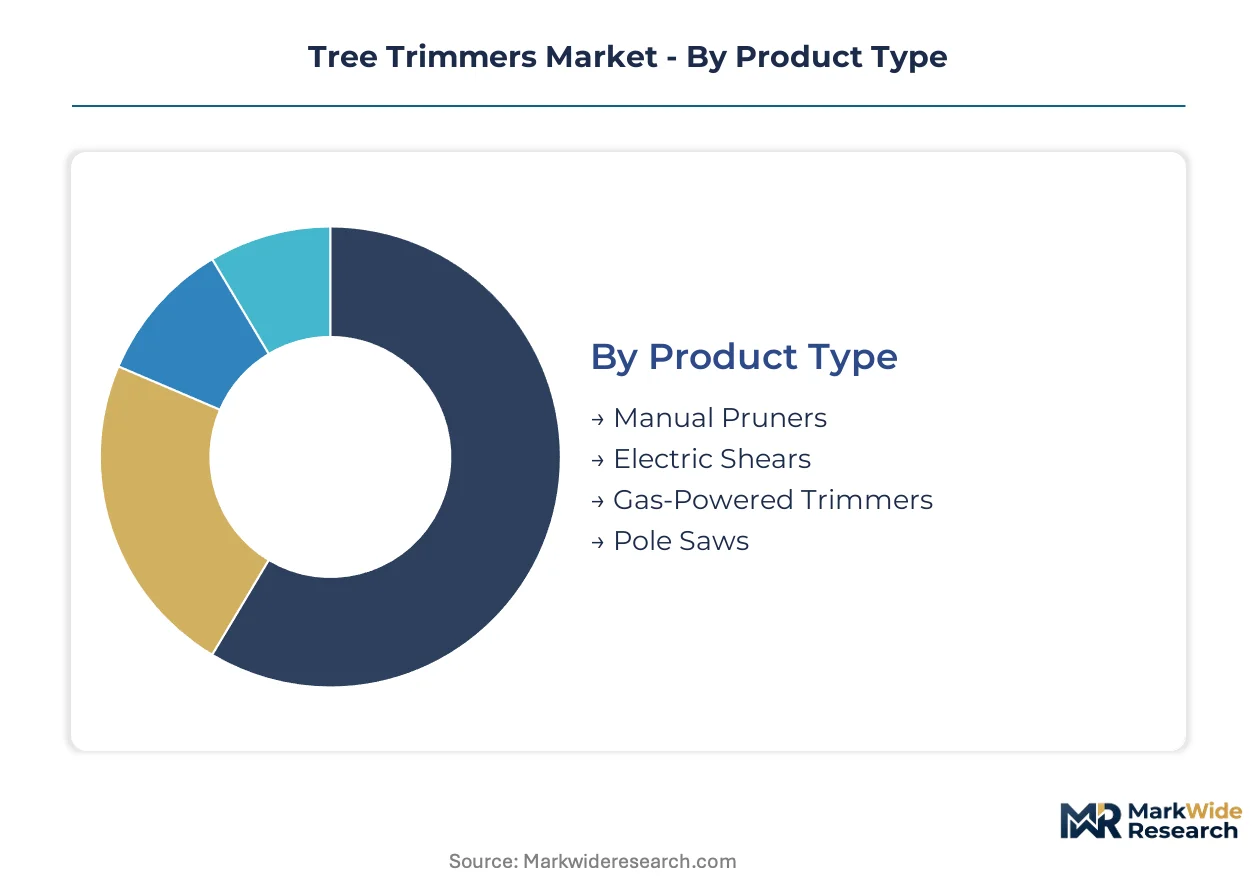
Segmentation in the tree trimmers market reveals divergent equipment lifecycles across power platforms and end-user categories. Municipal fleets and commercial landscaping operators compress replacement cycles under regulatory pressure, while residential segments extend usage periods through aftermarket part availability.
Product Type:
Replacement velocity varies dramatically across this category, with professional-grade equipment cycling every 3-5 years versus 8-12 year lifespans for residential manual tools.
- Gas-Powered Trimmers:Two-stroke and four-stroke engine platforms deliver sustained torque for heavy canopy work above 12 feet. Demand concentrates among Texas municipal fleets and Florida utility contractors where runtime requirements exceed current battery density.
- Pole Saws:Telescoping shaft designs with reciprocating chain drives address specialized vertical reach applications. Washington State orchard operators and California utility right-of-way crews drive procurement as labor scarcity accelerates mechanization.
- Manual Pruners:Bypass and anvil cutting mechanisms serve precision pruning in residential gardens and boutique vineyard operations.
- Electric Shears:Corded and cordless variants target light-duty hedge maintenance in suburban property management portfolios.
Gas-Powered Trimmers anchors the volume base while Pole Saws gains share at the steepest rate.
End User:
Procurement scale and specification authority separate this category, with institutional buyers wielding fleet-standardization power unavailable to fragmented residential purchasers.
- Landscaping Companies:Mid-sized contractors operating 15-50 unit fleets drive standardization decisions across metropolitan Denver and Phoenix markets. OSHA vibration exposure limits and municipal noise ordinances force ergonomic platform upgrades ahead of natural depreciation cycles.
- Municipalities:Urban forestry departments in Austin, Minneapolis, and Portland manage canopy inventories through dedicated trimming allocations. CARB small-engine standards and local electrification mandates compress gasoline equipment effective lifespans.
- Property Management Firms:Multi-site residential and commercial portfolios negotiate volume service contracts with regional landscaping vendors.
- Homeowners:Individual purchasers select battery-powered platforms for noise compliance in dense suburban neighborhoods.
Landscaping Companies anchors the volume base while Municipalities expands most quickly under regulatory compulsion.
Technology:
Power delivery architecture determines runtime, torque curves, and regulatory exposure across operating environments.
- Battery-Powered:Lithium-ion cell packs with brushless motor controllers achieve energy density thresholds enabling full workday operation. Colorado and Oregon commercial fleets adopt fastest where municipal noise restrictions intersect with total cost-of-ownership calculations.
- Gasoline:Small spark-ignition engines with catalytic converter integration respond to EPA Phase 3 emission standards. Carburetor and precision fuel injection complexity requires scarce certified technician skills.
- Corded:AC motor platforms serve fixed-location maintenance depots and greenhouse operations with reliable grid access.
- Manual:Human-powered cutting mechanisms persist in precision applications and backup redundancy configurations.
Gasoline anchors the volume base while Battery-Powered climbs the fastest as lithium-ion performance gaps narrow.
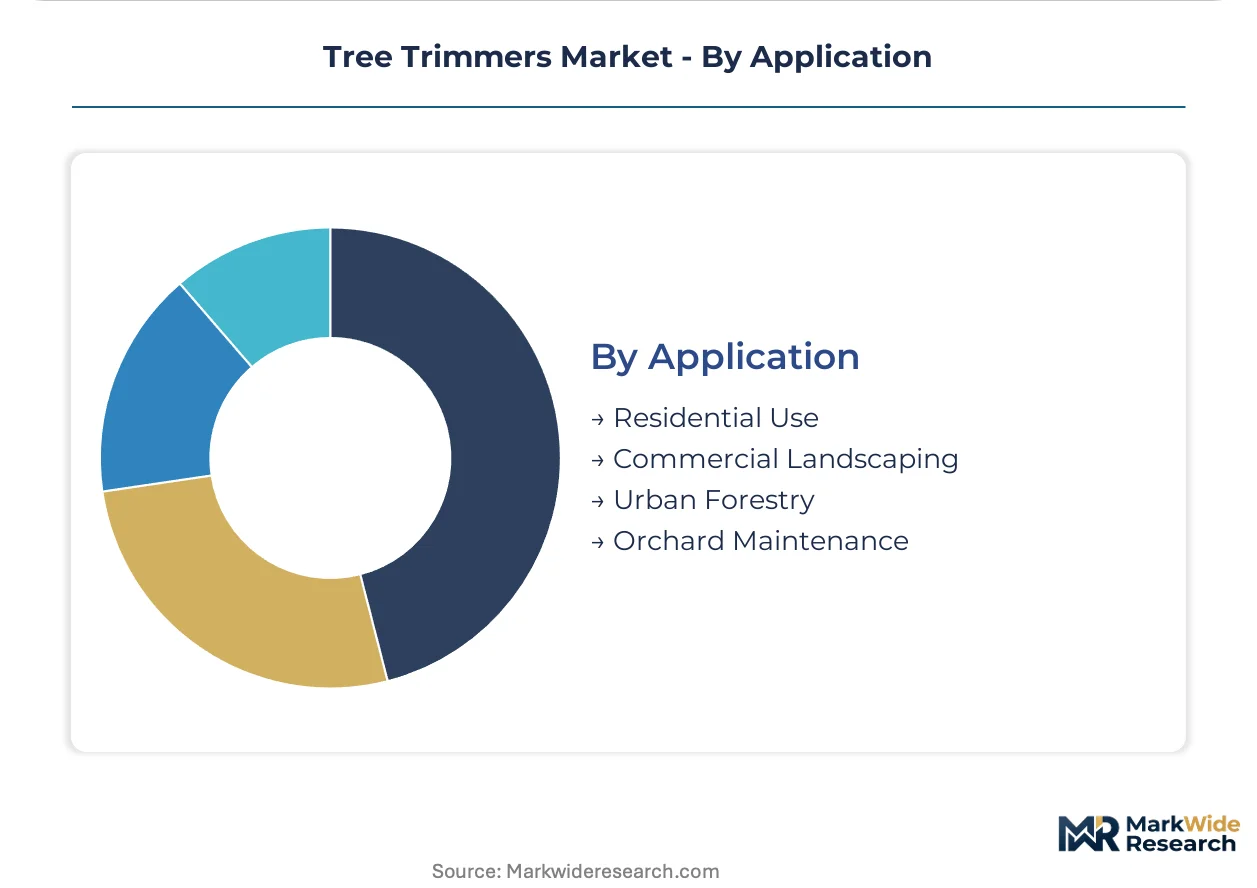
Application:
Worksite characteristics and vegetation density dictate equipment specification requirements across divergent operating contexts.
- Commercial Landscaping:Route-optimized crews require interchangeable battery platforms and rapid recharge protocols. Atlanta and Phoenix markets show fastest adoption of unbundled equipment and maintenance contract structures.
- Urban Forestry:Municipal canopy management programs in New York and California cities integrate GIS inventory systems with trimming cycle planning. Fire-risk reduction and storm damage prevention justify specialized pole-mounted and aerial lift configurations.
- Residential Use:Suburban property maintenance selects lightweight battery platforms for weekend operation within noise-restricted hours.
- Orchard Maintenance:Washington State tree fruit producers invest in precision pruning systems addressing seasonal labor availability constraints.
Commercial Landscaping anchors the volume base while Urban Forestry demonstrates the steepest expansion trajectory as city canopy budgets grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractors in the United States deploy heavy gas-powered fleets for sustained canopy work, while European operators favor lighter battery platforms under stricter municipal noise regimes. Japanese municipalities invest in precision pole systems for dense urban forestry. This consumption-mix differential shapes equipment specification requirements across national markets.
United States
Texas municipal fleets and Florida utility contractors sustain demand for high-torque gasoline platforms where runtime requirements exceed current battery density. EPA Phase 3 small spark-ignition engine standards push manufacturers toward catalytic converter integration and precision fuel injection. Atlanta and Phoenix commercial landscaping markets show fastest adoption of unbundled equipment and maintenance contract structures.
Germany
Professional arboriculture operators in Baden-Württemberg and Bavaria prioritize ergonomic designs meeting stringent hand-arm vibration exposure limits. The EU Green Deal and national climate targets accelerate municipal fleet electrification timelines. Stuttgart-based equipment distributors report compressed replacement cycles for gasoline trimmers ahead of local emission deadlines.
Japan
Tokyo and Osaka urban forestry departments invest in precision pole-mounted systems for dense canopy management in confined built environments. METI energy efficiency guidelines favor brushless motor adoption in commercial equipment procurement. Nagoya industrial clusters supply specialized cutting chain and reciprocating blade components to domestic manufacturers.
Canada
British Columbia and Ontario landscaping contractors balance battery platform adoption against extended seasonal runtime requirements in northern climates. Health Canada and PMRA coordinate emission and pesticide exposure standards affecting vegetation management protocols. Vancouver municipal procurement offices weight noise compliance scores heavily in bid evaluations for urban maintenance contracts.
Australia
New South Wales and Victoria fire-risk reduction programs drive specialized trimming allocations in wildland-urban interface zones. State-level environmental protection agencies enforce noise restrictions accelerating battery-powered procurement among Sydney and Melbourne commercial operators. Queensland mining corridor vegetation management sustains demand for heavy-duty gasoline pole saws in remote access applications.
Tree Trimmers Market Vendor Landscape
Capability concentration sits with specialized arboriculture service providers; scale advantage sits with diversified landscaping conglomerates. The market structures around three tiers: national tree care specialists with captive equipment depots, regional landscaping operators with standardized fleet programs, and utility-focused contractors with right-of-way maintenance expertise. Dominant competitive moves include geographic expansion through municipal contract aggregation and technology licensing for battery platform interoperability.
Within the national specialist tier, The Davey Tree Expert Company, Bartlett Tree Experts, and Asplundh Tree Expert occupy positions exemplifying divergent equipment strategies. The Davey Tree Expert Company represents the service-revenue model through recurring maintenance contract capture. Bartlett Tree Experts exemplifies captive infrastructure deployment with metropolitan depot networks. Asplundh Tree Expert anchors the volume-based fleet arrangement archetype through original equipment distributor partnerships. These three structures illustrate how scale, specialization, and vertical integration differentiate competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Summit Tree Care |
| Bartlett Tree Experts |
| Asplundh Tree Expert |
| Yellowstone Landscape |
| SavATree |
| The Davey Tree Expert Company |
| Forest Tree Services |
| BrightView |
| Fine Tree Care |
| Others |
Supply Flow & Price Mechanics
Southeast Asian carburetor manufacturing clusters in Thailand and Vietnam determine downstream pricing power for gasoline trimmer assemblers, with component scarcity translating directly into OEM margin compression and distributor inventory holding costs.
Pricing Analysis
Long-term fleet-of-take agreements between municipal procurement offices and original equipment distributors dominate commercial landscaping transactions, while spot purchasing persists in residential channels. Three-tier pricing structure across premium brushless-motor platforms, standard gasoline units, and economy corded alternatives separates specification tiers. Pricing pressure stems from lithium and cobalt raw material volatility compressing cordless equipment margins. Municipal buyers exhibit lowest price sensitivity due to regulatory compliance mandates, whereas mid-sized contractors face acute capital constraints.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing arrangements between Southeast Asian ignition system producers and North American distributor networks. Manufacturing concentrates in China, Japan, and Germany for brushless motor controllers, precision fuel injection components, and specialized cutting chains. Raw material dependencies span lithium carbonate, cobalt sulfate, and high-grade aluminum forgings. Single-source vulnerability concentrates in Japanese bearing suppliers for professional-grade drive systems. Distribution runs through dealer-managed fleet programs and direct-to-contractor e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-powered equipment substitution threatens incumbent gasoline platform dominance, requiring defensive repositioning around service revenue capture and regulatory compliance bundling.
For Market Incumbents: Build captive service-network moats through blade-sharpening subscription contracts and seasonal maintenance lock-ins. Defend against battery-platform substitution by integrating catalytic converter upgrades into municipal compliance packages. Add capacity in Texas and Florida where runtime requirements sustain gasoline demand. Invest in OSHA vibration-dampening certification to accelerate replacement cycle capture. For New Entrants and Emerging Players: Mid-market landscaping contractors in Colorado and Oregon represent the most penetrable entry point, with noise ordinance acceleration creating procurement urgency. Washington State orchard mechanization offers specialized pole-saw demand with concentrated margins. Equipment-as-a-service rental platforms reduce capital barriers for fleet standardization. Target unbundled maintenance contract fragmentation in Atlanta and Phoenix suburban markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among national tree care specialists with captive depot networks and municipal contract backlogs. Long-term viability favors operators with backward integration into service infrastructure over pure hardware distributors. Acquisition targets should demonstrate fleet-standardization power across 15-50 unit contractor bases. Monitor municipal electrification deadline acceleration as inflection signal for gasoline inventory stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Interoperability Licensing | Cross-brand battery ecosystems reduce contractor fleet fragmentation and capture switching costs. |
| Captive Service Depot Expansion | Metropolitan depot networks lock in recurring maintenance revenue from municipal forestry departments. |
| Brushless Motor Control Integration | Virtualized power transmission enables remote diagnostics and predictive maintenance scheduling. |
| Orchard Mechanization Partnership | Washington State precision pruning systems address seasonal labor scarcity in tree fruit operations. |
| OSHA Vibration Compliance Certification | Ergonomic handle redesigns accelerate replacement demand under stricter exposure enforcement. |
Methodological Framework
Desk research of EPA emission filings, OSHA enforcement databases, and municipal procurement records preceded structured interviews with equipment distributor principals, municipal urban forestry directors, commercial landscaping fleet managers, and aftermarket service technicians. Primary fieldwork captured inventory mix decisions, replacement cycle compression factors, and unbundled contract negotiation patterns. Secondary validation drew from trade association shipment data, customs import records, and lithium-ion cell pricing indices. Bottom-up unit economics triangulated against top-down market sizing across power platform and end-user segments.
Assumptions held fixed include municipal electrification deadline schedules and EPA Phase 3 emission standard implementation timelines, while battery energy density improvement curves and raw material price trajectories were stress-tested across scenarios. Segmentation modeling spanned product type, end-user category, power technology, and application context with regional regulatory cluster overlays. CAGRs were derived from replacement velocity differentials between regulatory-compressed and natural-depreciation cycles. Industry-specific inputs included urban forestry budget allocation trends and certified small-engine technician pipeline constraints.
Practitioners should monitor municipal noise ordinance acceleration and lithium supply contract renegotiations for early signals of platform substitution inflection. Forecasts reflect documented assumptions regarding runtime parity achievement and emission compliance cost pass-through. Macroeconomic contraction, regulatory delay, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Global Yield Monitoring Devices Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Indoor Farming Equipment Market