
 Aircraft Seat Frames Market | 2026-2036
Aircraft Seat Frames Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Seat Frames Market Analysis
Low-cost carrier retrofit programs is rotating demand away from legacy full-service airline specifications toward lighter, higher-density seat frames. Collins Aerospace sustains broad certification coverage across FAA and EASA jurisdictions. Jamco Corporation anchors its position through manufacturing scale in Japan. Safran leverages vertical integration from materials through final assembly to control cost structures.
Aircraft seat frames are structural load-bearing assemblies, typically fabricated from aluminum alloys or carbon fiber reinforced polymers, engineered to withstand crashworthiness loads while minimizing mass per passenger position. These components serve the primary commercial purpose of providing certified occupant restraint and comfort platforms across fixed-wing and rotary-wing aircraft. Carbon fiber segments command premium positioning due to weight reduction thresholds demanded by next-generation narrow-body programs. Commercial aviation application pools dominate current volume, though business jet retrofit cycles represent concentrated margin opportunities for specialized suppliers.
FAA certification requirements under 14 CFR Part 25, EASA CS 25.561 dynamic testing mandates, and NADCAP accreditation for special processes collectively govern market access and product qualification timelines. ISO 9001 quality management baseline expectations further filter supplier eligibility for tier-one OEM contracts. Stakeholders must monitor evolving flammability standards and sustainability disclosure pressures as these reshape material selection roadmaps and supplier qualification protocols.
Market Dynamics
Retrofit cycles at low-cost carriers are compressing specification timelines, forcing suppliers to accelerate qualification of lighter frame architectures while maintaining 14 CFR Part 25 crashworthiness compliance. This structural pressure is redistributing procurement power toward airframers with captive seat divisions.
Growth Catalysts
- FAA 16g dynamic seat testing mandates:Regulatory stringency under 14 CFR Part 25.562 is accelerating replacement of legacy frame designs in narrow-body fleets.
- Southeast Asia single-aisle expansion:Indonesia, Vietnam, and the Philippines are adding aircraft positions faster than global averages, concentrating demand for high-density seating.
- Carbon fiber reinforced polymer maturation:Automated fiber placement advances are reducing unit costs for thermoplastic composite frames, opening retrofit applications previously reserved for new-build programs.
Market Restraints
- Aluminum alloy price volatility:Aerospace-grade 7075-T6 and 2024-T3 input costs swing with LME pricing, compressing margin visibility for frame fabricators on fixed-price contracts.
- Specialized supplier concentration in Japan:Precision forging and NADCAP-accredited heat treatment capacity clusters around Nagoya and Tokyo, creating geographic chokepoints.
- Titanium fastener substitution limits:CFRP frames require galvanically compatible attachment hardware, locking suppliers into titanium supply chains with longer lead times than steel alternatives.
Strategic Opportunities
- India narrow-body induction wave:IndiGo and Air India Express fleet expansion creates unmet demand for domestically assembled seat structures under the country's PLI scheme for aerospace components.
- Urban air mobility seat adaptation:eVTOL air taxi programs require crashworthy frames at one-third the mass of commercial aviation equivalents, opening adjacent design engineering contracts.
- EASA CS 25.853 flammability standard harmonization:Pending alignment with FAA burn-test protocols would simplify dual-certification pathways for suppliers serving both jurisdictions.
Industry Challenges
- NADCAP special process auditor scarcity:Non-destructive testing and chemical processing accreditation backlogs extend supplier qualification timelines by 8-14 months.
- Legacy fleet documentation gaps:Aging aircraft seat traceability records complicate retrofit engineering, forcing expensive reverse-engineering of original frame specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Seat Frames Market |
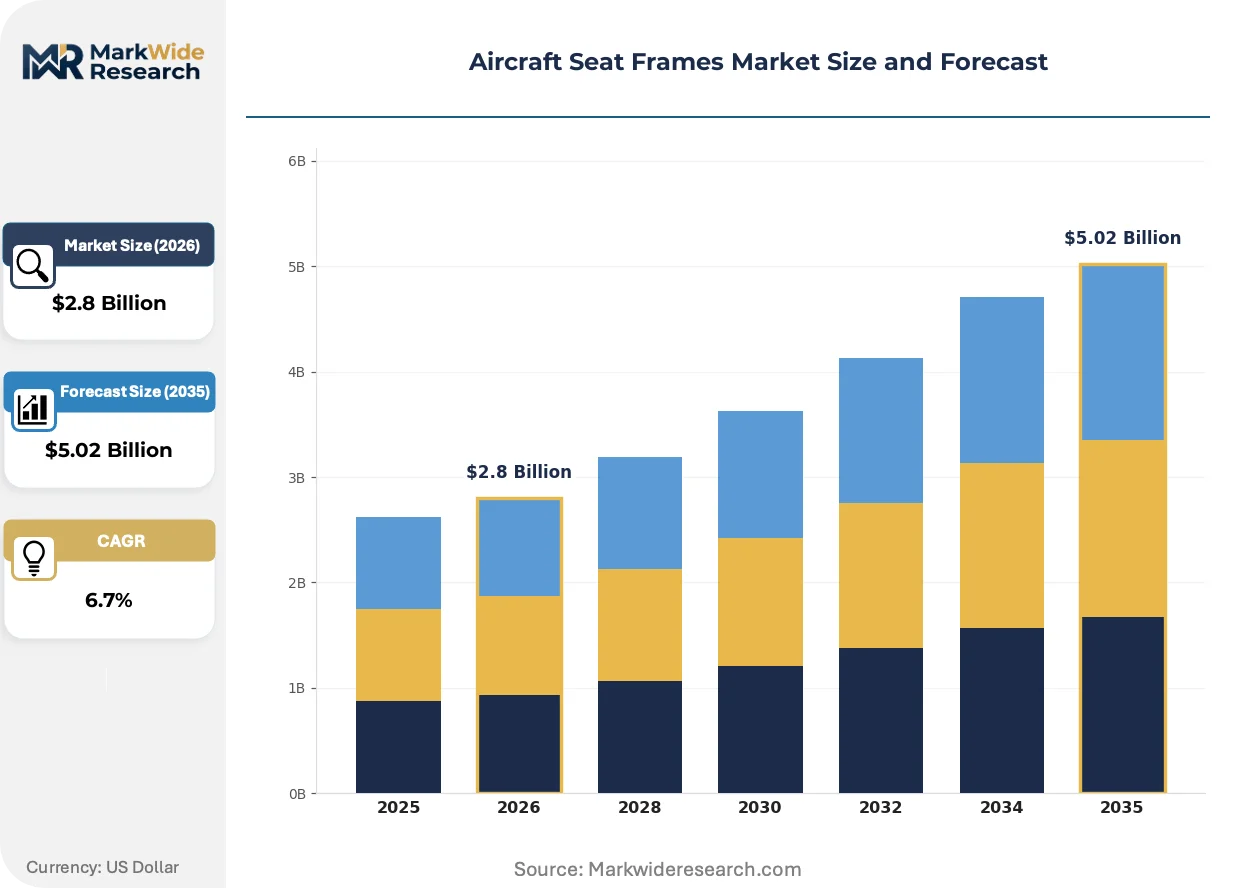
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Carbon Fiber, Steel, Composites Application: Commercial Aviation, Military Aircraft, Business Jets, Helicopters Design Type: Standard Seat, Premium Class, Economy Class, First Class Certification: FAA Certified, EASA Certified, ISO 9001, NADCAP |
| Companies Covered | Adient Aerospace, Jamco Corporation, Collins Aerospace, Geven S.p.A., Aviointeriors S.p.A., Safran, Thompson Aero Seating, Mirus Aircraft Seating, RECARO Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Seat Frames Market Emerging Trajectories
Material substitution and regulatory harmonization are compressing product lifecycles while fragmenting procurement authority across airframers, seat integrators, and airline technical departments.
Thermoplastic composite seat frames are displacing aluminum monocoque designs in premium cabin positions where 15-20% weight reduction justifies unit cost premiums. Business jet completion centers and flag carrier first-class retrofit programs are adopting these structures fastest. This displacement is compressing the addressable market for conventional machined aluminum frames to economy and high-density configurations.
EASA's upcoming CS 25.853(c) amendments tightening heat-release and smoke-density thresholds for cabin materials are forcing reformulation of resin systems in composite frames. European suppliers are accelerating phenolic and PEEK-based alternatives through qualification pipelines. Narrow-body programs with heavy European content, including A320neo family deliveries, are experiencing the most intensive material requalification activity.
Airline technical departments are consolidating seat procurement decisions previously dispersed across engineering, finance, and cabin experience functions. This centralization is displacing the influence of individual route planners and brand managers in specification choices. Low-cost carriers in Southeast Asia with standardized fleet policies are exhibiting this pattern most distinctly, compressing vendor negotiation cycles and demanding lifecycle cost guarantees.
Aircraft Seat Frames Market Segmentation
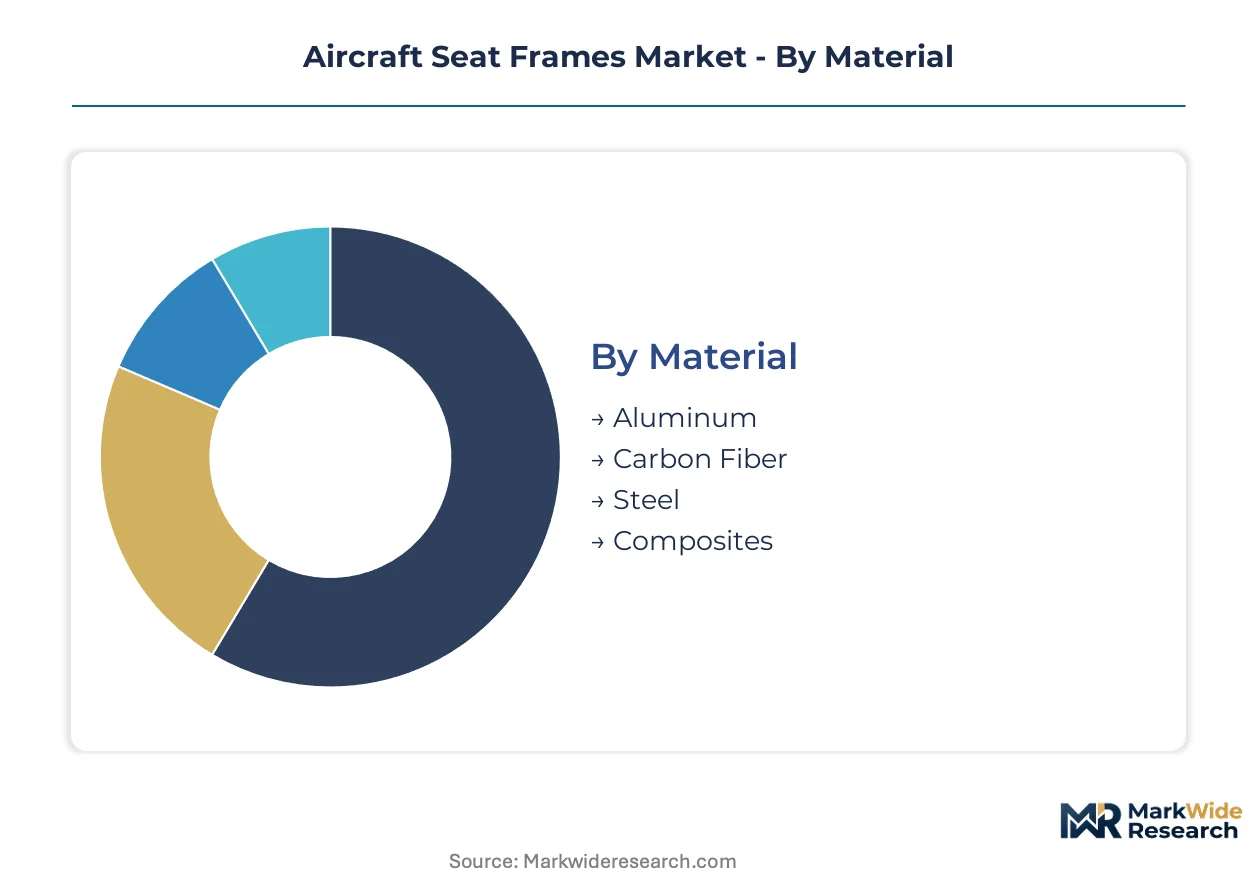
Material selection drives fundamental cost and performance differentiation in seat frame procurement. Certification requirements fragment supplier pools across regulatory jurisdictions, while design tiering concentrates margin capture in premium cabin positions.
Material:
Carbon fiber substitution pressure intensifies as thermoplastic processing costs decline, threatening aluminum's dominance in narrow-body retrofits.
- Aluminum:Aerospace-grade 7075-T6 and 2024-T3 alloys dominate economy-class configurations where unit cost sensitivity outweighs mass reduction targets. Southeast Asian low-cost carriers specify aluminum frames for high-density single-aisle retrofits due to established supply chains and NADCAP-accredited heat treatment capacity in Japan.
- Carbon Fiber:Automated fiber placement advances are reducing unit costs for thermoplastic composite frames. Business jet completion centers in the United States and flag carrier first-class programs adopt these structures fastest where 15-20% weight reduction justifies premium positioning.
- Steel:Legacy wide-body fleets retain steel-reinforced frames for crew rest positions and galley-adjacent seating where impact resistance exceeds weight priorities.
- Composites:Hybrid thermoset-thermoplastic formulations address EASA flammability standard tightening through phenolic and PEEK-based resin systems.
Aluminum anchors the volume base while carbon fiber gains share at the steepest rate.
Application:
Commercial aviation concentration shapes procurement scale, yet military and business aviation segments concentrate margin through specialized crashworthiness requirements.
- Commercial Aviation:Narrow-body retrofit cycles at low-cost carriers compress specification timelines and accelerate lighter frame qualification. Indonesia, Vietnam, and the Philippines drive demand concentration as single-aisle fleet expansion outpaces global averages.
- Military Aircraft:Crew seat assemblies require 14 CFR Part 25.562 dynamic testing compliance plus additional ballistic and blast-resistant specifications. Procurement flows through defense integrators with captive qualification capabilities.
- Business Jets:Completion centers specify thermoplastic composite frames for premium cabin positions where customization and weight reduction command price premiums.
- Helicopters:Rotary-wing crashworthiness mandates under CS 29.561 create specialized demand for energy-absorbing frame architectures with stroke-controlled deformation zones.
Commercial aviation commands procurement volume while business jets deliver the highest margin per passenger position.
Design Type:
Airline technical department centralization is compressing negotiation cycles and shifting specification authority toward lifecycle cost guarantees rather than upfront unit pricing.
- Economy Class:High-density configurations specify aluminum frames with minimal recline mechanisms. Low-cost carriers in Southeast Asia standardize across fleets to simplify maintenance provisioning and reduce spare part complexity.
- Premium Class:Wider seat pans and increased pitch requirements drive heavier frame specifications, offset partially by carbon fiber adoption in long-haul configurations.
- First Class:Suite-enclosed seating demands custom frame engineering for privacy partitions and lie-flat mechanisms. Business jet completion centers represent the most specialized demand pool.
- Standard Seat:Regional turboprop and narrow-body baseline configurations prioritize interchangeability and rapid turnaround maintenance over mass optimization.
Economy class generates unit volume while first class commands engineering premium and customization margin.
Certification:
Dual-jurisdiction qualification requirements fragment supplier eligibility and extend product development timelines for market access.
- FAA Certified:14 CFR Part 25.561 and 25.562 dynamic testing mandates govern occupant restraint and crashworthiness for United States-registered aircraft. FAA certification anchors supplier qualification for North American operator procurement.
- EASA Certified:CS 25.561 and pending CS 25.853(c) amendments tighten heat-release thresholds, forcing European suppliers through intensive material requalification for composite frame resin systems.
- ISO 9001:Quality management baseline filters tier-one OEM contract eligibility, with AS9100 aerospace-specific extensions required for major airframe manufacturer supply agreements.
- NADCAP:Special process accreditation for non-destructive testing and chemical processing creates auditor scarcity bottlenecks, extending supplier qualification timelines.
FAA certification covers the broadest operator base while EASA standards are tightening fastest on flammability performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Low-cost carriers in Southeast Asia anchor procurement volume, while North American and European suppliers compete on certification breadth and material innovation. Fleet expansion in emerging aviation markets is redistributing manufacturing investment toward regional assembly hubs.
United States
Business jet completion centers in Wichita and Vero Beach drive demand for thermoplastic composite frames where weight reduction commands premium pricing. FAA 14 CFR Part 25.562 dynamic testing mandates accelerate replacement cycles in narrow-body retrofits. Dallas-Fort Worth hosts concentrated seat integrator engineering operations serving domestic airline retrofit programs.
Japan
Precision forging capacity for aerospace-grade aluminum alloys clusters around Nagoya and Tokyo, supplying Southeast Asian low-cost carrier fleets. METI industrial policy supports NADCAP-accredited heat treatment infrastructure for tier-one OEM contracts. Osaka-based manufacturing scales dominate high-volume economy-class frame production for regional turboprop programs.
Germany
EASA CS 25.853 flammability standard tightening forces resin system reformulation in composite frame manufacturing. Hamburg and Munich anchor specialized seat engineering clusters serving Airbus narrow-body and wide-body programs. German suppliers concentrate on premium cabin configurations where customization requirements exceed mass-production economies.
India
IndiGo and Air India Express fleet induction creates unmet demand for domestically assembled seat structures. PLI scheme incentives for aerospace components attract foreign joint ventures to Bangalore and Hyderabad manufacturing zones. DGFT import substitution policies accelerate local content requirements for airline procurement.
Indonesia
Lion Air Group and Garuda Indonesia expansion concentrates single-aisle fleet growth faster than global averages. The country's national aviation regulator enforces EASA-aligned certification for imported seat assemblies. Jakarta and Surabaya maintenance hubs increasingly specify high-density aluminum frames for rapid-turnaround retrofit cycles.
Aircraft Seat Frames Market Vendor Landscape
Player mix skews toward diversified aerospace conglomerates with captive seat divisions, supplemented by specialized seating integrators and regional component fabricators. Consolidation pressure favors suppliers with dual FAA-EASA certification coverage and NADCAP-accredited special process capabilities. Two strategic archetypes dominate: vertically integrated airframer-affiliated divisions controlling cost structures through materials-to-assembly pipelines, and independent specialists capturing margin through premium cabin customization. Competitive moves center on qualification acceleration for lighter frame architectures and geographic expansion into Southeast Asian assembly partnerships.
Among diversified aerospace conglomerates, Collins Aerospace and Safran exemplify integrated players with broad regulatory jurisdiction coverage. Jamco Corporation anchors the specialized fabricator tier through Japanese manufacturing scale. RECARO Holding GmbH occupies a position in the premium seating specialist segment where business jet and flag carrier first-class programs concentrate margin opportunity. These three represent distinct competitive positioning vectors: regulatory breadth, manufacturing scale, and customization depth.
| Leading Market Players |
|---|
| Adient Aerospace |
| Jamco Corporation |
| Collins Aerospace |
| Geven S.p.A. |
| Aviointeriors S.p.A. |
| Safran |
| Thompson Aero Seating |
| Mirus Aircraft Seating |
| RECARO Holding GmbH |
| Others |
Supply Flow & Price Mechanics
FAA 14 CFR Part 25.562 dynamic testing mandates gate both supplier qualification timelines and price differentiation across frame architectures, compressing margin structures for uncertified fabricators while rewarding dual-jurisdiction coverage with premium positioning.
Pricing Analysis
Next-generation carbon fiber reinforced polymer frames command 40-60% unit premiums over legacy aluminum configurations, while prior-generation steel-reinforced structures face accelerated price erosion in retrofit cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and material performance tier. Pricing pressure stems from low-cost carrier procurement consolidation demanding lifecycle cost guarantees rather than upfront unit quotes. Economy-class aluminum frames exhibit highest buyer price sensitivity, while business jet completion centers show lowest sensitivity due to weight-reduction value capture.
Supply Chain Analysis
NADCAP-accredited heat treatment capacity clustering around Nagoya and Tokyo creates geographic chokepoints for aerospace-grade aluminum alloy processing. Japan, the United States, and Germany anchor precision forging and composite manufacturing, with India emerging as an assembly hub under PLI scheme incentives. Raw material dependencies draw from titanium fastener supply chains, thermoplastic resin systems, and aerospace-grade aluminum billet. Single-source vulnerability concentrates in Japanese special process accreditation. Distribution runs through tier-one seat integrators with captive airframer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where dual FAA-EASA certification coverage creates switching costs that lock airline technical departments into qualified supplier relationships.
For Market Incumbents: Consolidate NADCAP-accredited special process capabilities through targeted acquisition of Japanese heat treatment and non-destructive testing facilities. Expand carbon fiber reinforced polymer manufacturing footprint in Southeast Asian assembly partnerships to capture low-cost carrier retrofit volume. Threat of emerging Indian domestic fabricators under PLI incentives demands preemptive capacity positioning.
For New Entrants and Emerging Players: Differentiate on urban air mobility seat adaptation where eVTOL crashworthiness requirements at one-third commercial mass open adjacent engineering contracts. Target India's unmet narrow-body assembly demand through joint ventures in Bangalore and Hyderabad manufacturing zones. Go-to-market angle: position as domestic content providers under DGFT import substitution policies.
For Investors and Strategic Acquirers: EASA CS 25.853(c) flammability standard harmonization reshapes the acquisition landscape toward suppliers with phenolic and PEEK-based resin qualification pipelines. Long-term viability favors vertically integrated players with materials-to-assembly cost control. Signal to watch: NADCAP auditor queue lengths as indicator of qualification bottleneck intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Certification Investment | FAA-EASA coverage unlocks procurement eligibility across North American and European operator fleets. |
| Thermoplastic Composite Capacity Expansion | Automated fiber placement advances reduce unit costs for carbon fiber reinforced polymer frame production. |
| Southeast Asian Assembly Partnership | Indonesia, Vietnam, and Philippines fleet expansion concentrates demand for high-density aluminum configurations. |
| NADCAP Special Process Acquisition | Heat treatment and chemical processing accreditation removes 8-14 month supplier qualification bottlenecks. |
| Urban Air Mobility Seat Engineering | eVTOL programs require crashworthy frames at mass thresholds one-third of commercial aviation equivalents. |
Methodological Framework
Cross-validation between primary interviews with seat integrator procurement directors, airline technical department heads, and NADCAP-accredited facility managers anchors the qualitative findings against secondary validation from FAA certification databases, EASA CS amendment dockets, and customs trade records for aerospace-grade aluminum and carbon fiber imports. Bottom-up triangulation across material-tier volume estimates and top-down reconciliation against airframe manufacturer delivery schedules ensures consistency.
Sensitivity analysis across the projection horizon models material substitution rates, regulatory amendment timelines, and fleet expansion trajectories. Segmentation dimensions include material type, application category, design tier, and certification jurisdiction. CAGRs derive from regression analysis of historical procurement cycles and forward projection of narrow-body retrofit intensity. Industry-specific inputs incorporate LME aluminum price volatility assumptions and NADCAP auditor capacity constraints.
Material uncertainties — aluminum alloy price swings, EASA flammability standard finalization, and NADCAP accreditation backlogs — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as low-cost carrier procurement consolidation and urban air mobility program maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market