
 Global Commercial Aircraft Airframe Materials Market | 2026-2036
Global Commercial Aircraft Airframe Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Aircraft Airframe Materials Market Intelligence
The substitution of traditional aluminum alloys with advanced carbon fiber reinforced polymers in new aircraft designs is hardening the business case for composite-centric supply chains. Hexcel Corporation leverages its leadership in advanced composite technologies and pre-impregnated materials. Toray Industries, Inc. sustains its market position through extensive R&D in carbon fiber production and process innovation. Meanwhile, Alcoa Corporation competes by developing next-generation aluminum-lithium alloys for fuselage applications, offering an alternative to full composite structures.
Commercial aircraft airframe materials comprise a specialized portfolio of metals, alloys, and composites engineered for high strength-to-weight ratios and fatigue resistance. These materials must withstand extreme temperature variations, aerodynamic stresses, and corrosive environments throughout an aircraft's operational life. While aluminum alloys remain dominant for fuselage structures in legacy and narrow-body aircraft, carbon fiber reinforced polymers represent the fastest-growing material type, especially for new wide-body wings and empennage components. Titanium alloys find specialized use in high-stress areas like landing gear and engine nacelles due to superior heat resistance.
Material qualification and airworthiness certification are governed by stringent standards from regulators like the FAA in the United States, the European Union Aviation Safety Agency (EASA), and the Civil Aviation Administration of China (CAAC). These bodies mandate rigorous testing protocols for flammability, toxicity, and structural integrity, creating high barriers to entry for new material suppliers. Suppliers must now navigate complex sustainability requirements, including recyclability and lifecycle emissions, which will dictate future material selection by aircraft manufacturers.
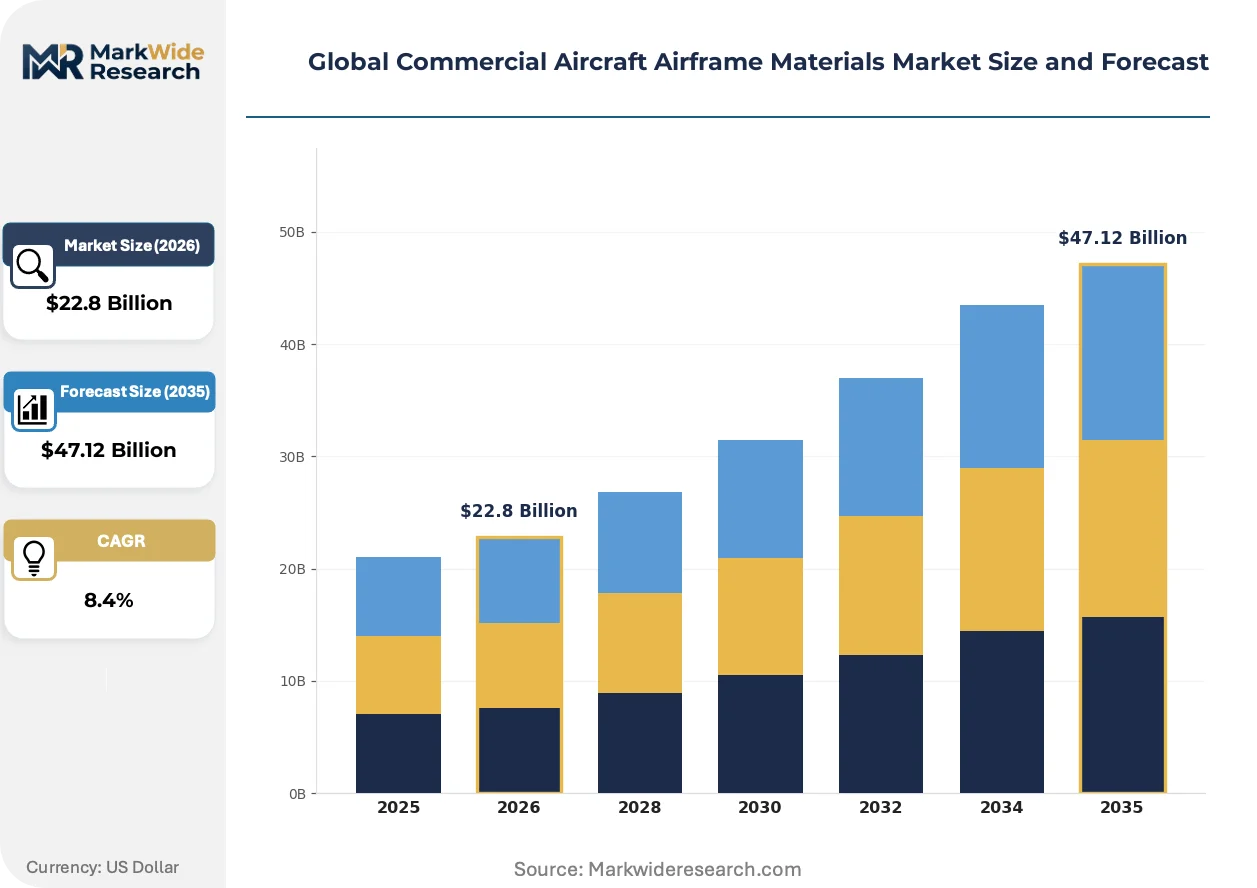
Market Dynamics
The imperative for improved fuel efficiency is the central force driving material innovation. This pressure links airframe weight reduction to operating economics, accelerating the substitution of traditional metals with advanced composites in new commercial aircraft programs.
Growth Catalysts
- Narrow-Body Fleet Renewal:High-volume production of new single-aisle jets by OEMs provides a stable demand foundation for both advanced aluminum alloys and composite prepregs.
- Advanced Thermoplastics:The pursuit of faster production cycles and recyclability, aligning with EU Green Deal objectives, drives investment into thermoplastic composite solutions.
- Chinese Industrial Policy:Government support for domestic aircraft programs in China creates a significant new geographic market for qualified airframe material suppliers.
Market Restraints
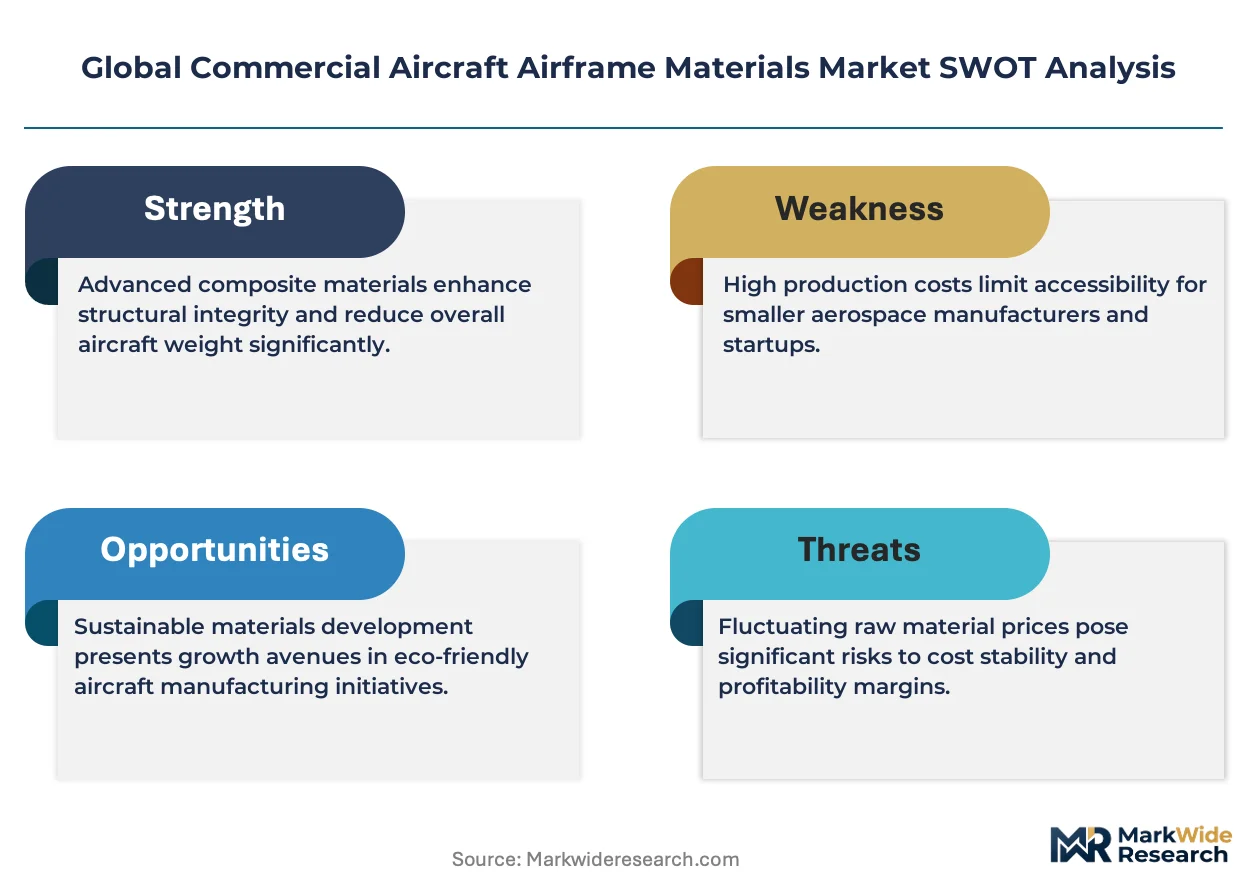
- Stringent Airworthiness Certification:The lengthy, costly material qualification process under FAA and EASA rules creates high barriers to entry and slows innovation adoption.
- Input Cost Volatility:Prices for key raw materials like aerospace-grade carbon fiber and titanium sponge are volatile, compressing margins for component fabricators.
- High Capital Expenditure:Production of advanced materials requires significant investment in specialized equipment like autoclaves, concentrating supply among a few large-scale firms.
Strategic Opportunities
- Composite Recycling Systems:Developing viable methods to recycle carbon fiber from end-of-life aircraft creates a circular economy and a source of lower-cost feedstock.
- Additive Manufacturing:Using 3D printing for complex titanium parts allows for weight reduction and part consolidation, especially for low-volume components like brackets.
- Urban Air Mobility (UAM):The emerging eVTOL aircraft market presents new demand for ultra-lightweight composites tailored for smaller, electrically powered airframes.
Industry Challenges
- Specialized Labor Shortages:A deficit of technicians skilled in composite fabrication and automated fiber placement creates production bottlenecks and increases labor costs for manufacturers.
- MRO Integration Complexity:Integrating new materials with legacy aircraft requires significant re-engineering of maintenance, repair, and overhaul (MRO) procedures and global supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Aircraft Airframe Materials Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum Alloys, Titanium Alloys, Carbon Fiber Reinforced Polymers, Glass Fiber Reinforced Polymers, Magnesium Alloys Component: Fuselage, Wings, Empennage, Landing Gear, Engine Nacelle Application: Structural Framework, Aerodynamic Surfaces, Thermal Insulation, Noise Reduction, Corrosion Protection End User: Aircraft Manufacturers, Maintenance Repair Organizations, Defense Contractors, Leasing Companies, Research Institutions |
| Companies Covered | Constellium SE, VSMPO-AVISMA Corporation, Toray Industries, Inc., Kobe Steel, Ltd., Teijin Limited, Hexcel Corporation, Alcoa Corporation, Southwest Aluminum (Kunshan) Co., Ltd., Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Aircraft Airframe Materials Market Strategic Shifts & Innovations
Material science advancements are driven by the dual objectives of enhancing structural performance while meeting aggressive sustainability targets. This dynamic is forcing a re-evaluation of traditional material selection, manufacturing processes, and supply chain circularity across the aerospace industry.
Advanced multi-material joining techniques are critical for creating hybrid airframe structures. Aircraft OEMs are adopting these methods to integrate large composite sections, like wings, with metallic fuselages on new aircraft platforms. This approach is unifying disparate material systems, enabling optimized performance and weight characteristics that monolithic designs cannot achieve.
The European Union Green Deal, reinforced by regulations like the Corporate Sustainability Reporting Directive (CSRD), imposes strict lifecycle accountability. This forces material suppliers to document and report the full environmental footprint of their products, from raw material extraction to end-of-life. The carbon fiber and aluminum alloy segments are most affected, as procurement decisions by major European OEMs now increasingly factor in these environmental metrics.
A shift towards circularity in supply agreements is gaining traction among major aircraft manufacturers. Traditional linear procurement models are being augmented with clauses that mandate material take-back programs for production scrap and end-of-life components. This change is most visible in Europe, where OEMs are partnering with suppliers to establish closed-loop recycling systems for composites and specialty alloys.
Global Commercial Aircraft Airframe Materials Market Segmentation
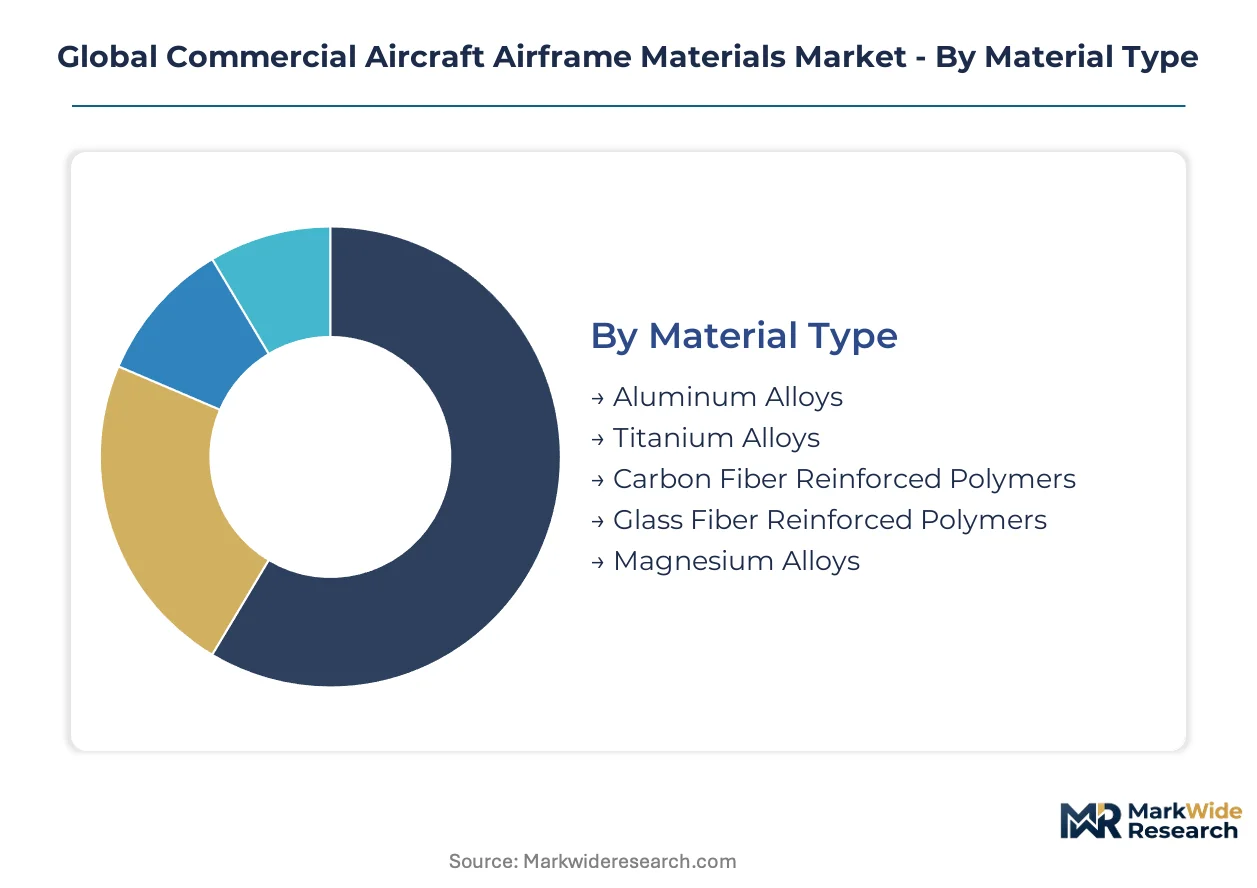
The segmentation of the commercial aircraft airframe materials market reveals the intricate interplay between material science advancements and specific aerospace requirements. This analysis dissects the market by material type, component, application, and end user, highlighting the specialized demands driving innovation and supply chain configurations.
Material Type:
The material type segmentation highlights the ongoing shift from traditional, high-volume metallic solutions to advanced, premium composite alternatives.
- Carbon Fiber Reinforced Polymers:These advanced composites offer superior strength-to-weight ratios and fatigue resistance, making them critical for new generation wide-body aircraft structures. Demand concentrates in Europe and North America for new aircraft programs emphasizing fuel efficiency mandates like the EU Green Deal.
- Aluminum Alloys:These traditional metallic materials remain dominant for fuselage structures in narrow-body aircraft, valued for their cost-effectiveness, established manufacturing processes, and reparability. North American and Chinese aircraft manufacturers maintain high demand for these alloys in high-volume production lines.
- Titanium Alloys:Valued for their high strength, corrosion resistance, and ability to withstand extreme temperatures, titanium alloys are used in high-stress areas such as landing gear and engine pylons.
- Glass Fiber Reinforced Polymers:These materials provide a cost-effective solution for secondary structural components and interior applications where extreme strength is not paramount.
- Magnesium Alloys:Offering excellent strength-to-weight characteristics, magnesium alloys find niche applications in specific aircraft parts where weight reduction is critical and environmental exposure is controlled.
Today's leader: Aluminum Alloys. Tomorrow's challenger: Carbon Fiber Reinforced Polymers.
Component:
Component segmentation reflects the diverse structural and functional demands placed on airframe materials across different parts of an aircraft.
- Fuselage:This primary structural component forms the aircraft's main body, requiring materials with high structural integrity, fatigue resistance, and reparability. Materials like advanced aluminum-lithium alloys and composite barrels are specified by OEMs in the United States and France.
- Wings:Critical for lift and aerodynamic control, wings demand materials with exceptional stiffness, strength, and fatigue life to withstand significant bending and torsional loads. Wide-body aircraft wings increasingly utilize carbon fiber reinforced polymers to achieve weight targets.
- Empennage:Comprising the tail section for stability and control, empennage components often leverage lightweight composites for aerodynamic efficiency.
- Landing Gear:Subjected to extreme impact and dynamic loads, landing gear components require robust materials like high-strength titanium alloys and specialized steels.
- Engine Nacelle:Housing the aircraft engines, nacelles demand materials capable of enduring high temperatures and noise dampening properties.
The segment expanding most quickly is Wings, while Fuselage maintains a stable base of material demand.
Application:
Application segmentation underscores the critical performance criteria materials must meet, from primary structural integrity to specialized environmental protection.
- Structural Framework:This application involves the primary load-bearing elements of the airframe, requiring materials with maximum strength-to-weight ratios and fracture toughness for flight safety. Material qualification by regulators like the FAA and EASA is most stringent here.
- Aerodynamic Surfaces:Materials for aerodynamic surfaces must ensure smooth airflow and minimize drag, often employing composites for complex shapes and lightweight construction. These surfaces include wing skins and control surfaces.
- Corrosion Protection:Materials and coatings designed for corrosion protection extend the operational life of metallic airframe components in harsh atmospheric conditions.
- Thermal Insulation:Used to manage temperature extremes, thermal insulation materials protect internal systems and maintain cabin comfort.
- Noise Reduction:Specialized materials and structures contribute to noise reduction, particularly around engine areas, enhancing passenger experience and complying with acoustic regulations.
The segment with the most stringent material requirements is Structural Framework, with Aerodynamic Surfaces seeing innovation for operational efficiency.
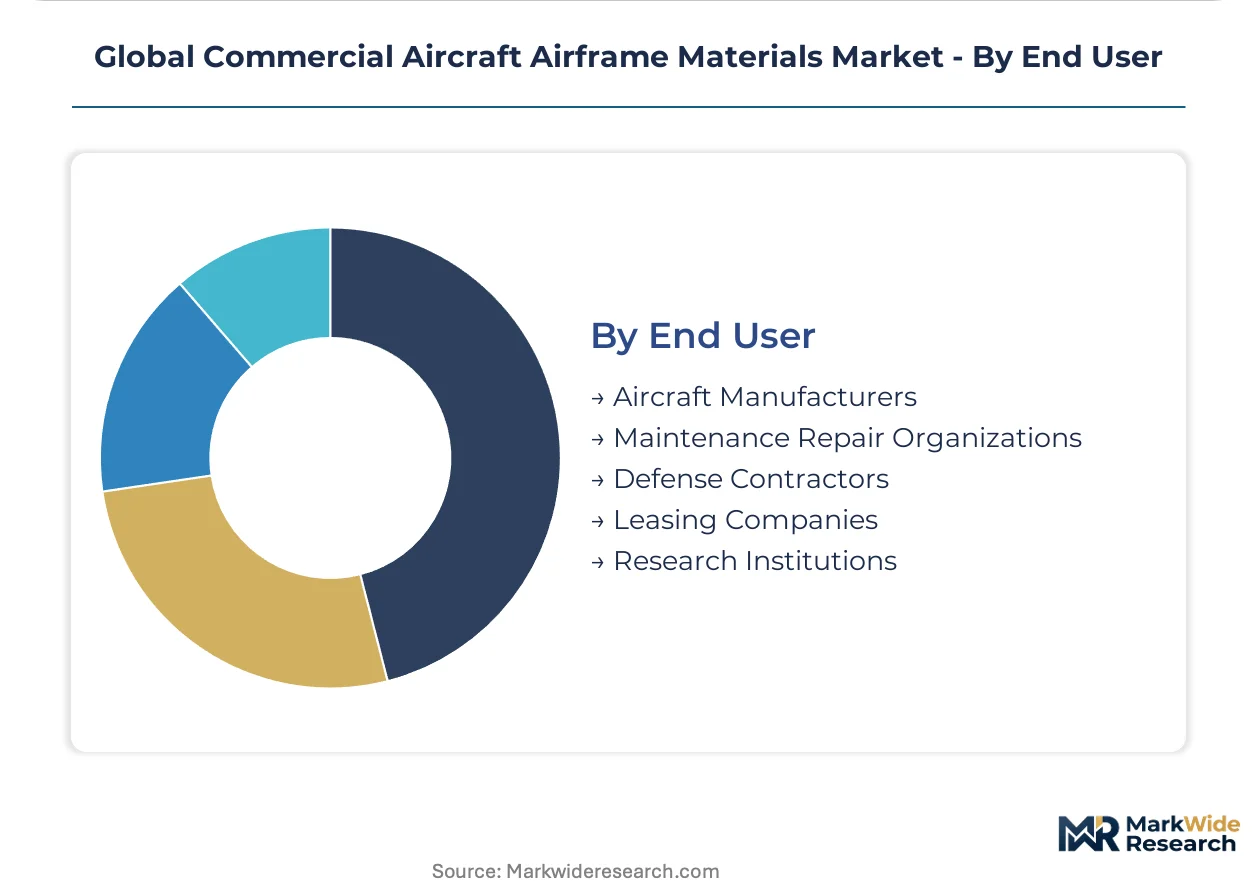
End User:
End user segmentation illustrates the varied procurement scales and material requirements across the aerospace value chain.
- Aircraft Manufacturers:These OEMs represent the largest end-user segment, procuring vast quantities of advanced materials for new aircraft production lines. Their demand is concentrated in established aerospace clusters across the United States, France, and increasingly China.
- Maintenance Repair Organizations:MROs require certified replacement materials for repairs and overhauls of in-service aircraft, often involving legacy material specifications and stringent airworthiness standards. This segment supports global fleets.
- Defense Contractors:These entities procure specialized, high-performance materials for military aircraft, prioritizing mission-specific capabilities and extreme durability over commercial cost considerations.
- Leasing Companies:While not direct material procurers, leasing companies influence material selection through their asset management strategies, focusing on material durability and maintenance costs over an aircraft's lifecycle.
- Research Institutions:These organizations drive material science innovation, testing new alloys and composites for future aerospace applications, often in collaboration with manufacturers and regulators.
Demand from Aircraft Manufacturers drives material innovation, while Maintenance Repair Organizations ensure operational continuity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aerospace clusters drive significant demand for commercial aircraft airframe materials. New narrow-body fleet production and ongoing MRO activities sustain material procurement volumes. Advanced composite adoption for next-generation aircraft platforms further shapes regional material requirements.
United States
United States aircraft manufacturers sustain robust demand for both advanced aluminum alloys and carbon fiber reinforced polymers. The FAA mandates rigorous material qualification, ensuring structural integrity and safety across all airframe components. Production hubs like Seattle and Wichita focus on high-volume manufacturing of fuselages and wings for major OEMs.
France
French aerospace firms drive substantial demand for advanced composites, particularly for wide-body aircraft programs like Airbus. EASA certification processes and EU Green Deal objectives influence material selection for recyclability and emissions. Toulouse remains a critical hub for Airbus final assembly, integrating large composite sections into new aircraft.
China
Chinese industrial policy supports domestic aircraft programs, creating a growing market for specialized airframe materials. The CAAC sets stringent airworthiness standards for new aircraft designs and material qualification. Manufacturing centers in Shanghai and Xi'an are expanding capacity for both metallic and composite airframe component production.
Germany
German aerospace suppliers contribute significantly to European aircraft production, focusing on high-performance materials for structural components. EASA regulations and the Corporate Sustainability Reporting Directive mandate detailed lifecycle assessments for all procured materials. Hamburg is a major site for Airbus manufacturing, while Stade specializes in advanced carbon fiber composite production.
Japan
Japanese material science leadership drives innovation in carbon fiber production and advanced composites for global aerospace partners. METI promotes R&D investment in high-performance materials, aligning with future aircraft requirements. The Nagoya region is a key aerospace manufacturing cluster, supporting both domestic and international airframe programs.
Global Commercial Aircraft Airframe Materials Market Key Industry Players
Capacity expansion dominates the current landscape for commercial aircraft airframe materials. This market exhibits tiered consolidation, with established material science firms holding significant shares in specialized segments like advanced composites and high-strength alloys. Strategic archetypes include integrated composite technology providers, legacy metallic alloy specialists, and emerging innovators in sustainable materials and recycling solutions. Companies increasingly pursue strategic partnerships for R&D, and diversify their product portfolios to address evolving airframe designs and regulatory mandates.
On the premium-tier vector, Hexcel Corporation exemplifies leadership in advanced composite technologies, particularly pre-impregnated materials crucial for high-performance aircraft structures. Toray Industries, Inc., a Japan-based entity, occupies a strong market position through its extensive R&D efforts in carbon fiber production and process innovation for various aerospace applications. Meanwhile, Alcoa Corporation, a US-based materials giant, anchors the market for next-generation aluminum-lithium alloys, offering a compelling alternative to full composite structures for fuselage applications and maintaining a competitive edge.
| Leading Market Players |
|---|
| Constellium SE |
| VSMPO-AVISMA Corporation |
| Toray Industries, Inc. |
| Kobe Steel, Ltd. |
| Teijin Limited |
| Hexcel Corporation |
| Alcoa Corporation |
| Southwest Aluminum (Kunshan) Co., Ltd. |
| Solvay S.A. |
Cost & Logistics Intelligence
Carbon fiber raw material costs, influenced by energy prices and geopolitical stability, directly impact composite material pricing for commercial aircraft airframe manufacturers. This volatility then affects airframe component fabricators and end-product pricing for aircraft OEMs downstream.
Pricing Analysis
Input cost pass-through from raw material suppliers to component fabricators directly influences airframe material pricing. The dominant pricing model involves contract-based long-term offtake agreements between major material suppliers and aircraft OEMs. Price differentiation drivers include certification level by regulators like the FAA and EASA, coupled with volume scale for large production runs. Pricing pressure stems from OEM mandates for fuel efficiency and continuous cost reduction across new aircraft programs. Aircraft manufacturers represent the most price-sensitive buyers due to high-volume procurement, while MROs exhibit less price sensitivity for certified replacement parts.
Supply Chain Analysis
Workforce availability for specialized composite fabrication and advanced metallurgy remains a critical factor in manufacturing geographies like the United States and France. Geographic supply concentration for advanced airframe materials centers in the United States, Japan, and France, with emerging capacity in China. Raw material dependencies include aerospace-grade carbon fiber, titanium sponge, and specialized aluminum billets. A primary supply chain risk involves single-source vulnerability for highly specialized materials and prepregs. Distribution runs through direct sales channels to aircraft manufacturers, with a specialized network of distributors serving Maintenance Repair Organizations for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial aircraft airframe materials market offers geographic arbitrage opportunities, driven by lower manufacturing labor costs in emerging aerospace clusters like China compared to established hubs in the United States and Europe. This cost differential influences material sourcing strategies.
For Market Incumbents:
Deploy targeted R&D investment in advanced thermoplastic composites to counter the threat of new material entrants and address sustainability mandates. Consolidate market share through strategic acquisitions of smaller, specialized material science firms with unique intellectual property in lightweight alloys. This strategy defends against margin pressure from OEM procurement teams and secures future material supply. Focus on achieving closed-loop recycling systems for existing composite waste streams.
For New Entrants and Emerging Players:
Launch via direct OEM partnerships in emerging aerospace markets like China, targeting their domestic aircraft programs for material qualification. Focus on developing cost-effective recycling solutions for carbon fiber, addressing a significant white-space opportunity in circularity. The empennage component segment offers a penetrable entry point for novel material systems with lower certification barriers. Prioritize material science breakthroughs that enable faster production cycles.
For Investors and Strategic Acquirers:
Consolidation pressure builds where specialized material science and advanced manufacturing capabilities are scarce, particularly in composite fabrication. Long-term viability over a ten-year window favors firms with robust intellectual property in sustainable materials and circular economy solutions. Target acquisition archetypes include vertically integrated composite prepreg manufacturers or titanium alloy specialists. A signal to watch is the accelerated adoption of closed-loop recycling systems by major OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Thermoplastics | Increases supply chain resilience and meets demand for faster production cycles for aircraft OEMs. |
| Advanced Composite Recycling Facility | Establishes circular economy solutions for end-of-life aircraft materials, addressing sustainability mandates. |
| Joint Venture for Aluminum-Lithium R&D | Accelerates development of next-generation metallic alloys for fuselage structures, offering weight reduction. |
| Certification of New Carbon Fiber Grades | Expands addressable market for high-performance materials in critical airframe components. |
| Digital Twin for Material Performance | Enhances material qualification processes and predicts operational fatigue life for new aerospace designs. |
Research Approach
Bottom-up aircraft OEM demand modeling reconciled against top-down material supplier production tracking forms the analytical core. This approach integrates primary interviews with material scientists, aerospace engineers, procurement leads, and regulatory specialists. Secondary validation draws from FAA and EASA certification documents, OEM annual reports, and trade association publications. Triangulation across these sources ensures data robustness.
Historical trendline analysis projects material adoption rates across the analysis window, considering technological inflection points. Segmentation dimensions modeled include material type, component, application, end user, and regional aircraft production. Compound annual growth rates derive from a proprietary blend of historical performance and anticipated program lifecycles. Industry-specific forecast inputs include new aircraft order backlogs and material qualification timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical instability or significant regulatory shifts. Forecasts reflect assumptions documented regarding technological advancements and OEM material selection. Material deviation in new aircraft program delays or unexpected raw material supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Aviation Connector Market