
 Rock-Socketed Drilling Rig Market | 2026-2036
Rock-Socketed Drilling Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Rock-Socketed Drilling Rig Market Insights
Drill string automation and real-time telemetry is fragmenting the traditional rig procurement model across the rock-socketed drilling rig value chain. SANY Group leverages its integrated hydraulic component manufacturing to control cost positions in the Asia-Pacific basin. Zoomlion Heavy Industry Science and Technology anchors its competitive stance through deep R&D investment in intelligent drilling control systems. Soilmec S.p.A specializes in compact rotary rigs for restricted-access urban geotechnical sites across Southern Europe.
A rock-socketed drilling rig is a foundation engineering machine designed to bore cylindrical shafts into bedrock and socket reinforcing elements into competent rock strata, typically achieving socket depths of 3 to 20 meters with torque outputs exceeding 200 kNm. The equipment serves primarily to transfer structural loads from buildings, bridges, and dams directly into stable rock formations, eliminating settlement risk in variable overburden conditions. Rotary rigs dominate the installed base for large-diameter socket work in mining and heavy civil construction, while sonic technology captures premium-margin environmental sampling contracts where undisturbed core recovery is mandatory. Hybrid powertrains are gaining fastest traction in European urban construction fleets as emission-controlled zones expand, though diesel-hydraulic configurations still sustain the majority of remote mining deployments.
China's MIIT enforces GB standards on construction machinery emissions and safety interlocks, directly conditioning product certification for domestic sales and export eligibility. The EU F-Gas Regulation and Stage V emission frameworks from the European Commission constrain hydraulic fluid and engine choices for rigs operating in member states, elevating compliance costs for non-European suppliers. Stakeholders must monitor how divergent certification pathways between China's GB system and Europe's CE-MDR convergence reshape sourcing strategies and aftermarket service architectures.
Market Dynamics
Drill string automation and real-time telemetry systems are fragmenting traditional rig procurement models, forcing manufacturers to restructure from equipment sales toward integrated performance contracts that bundle hardware, software, and remote diagnostics.
Growth Catalysts
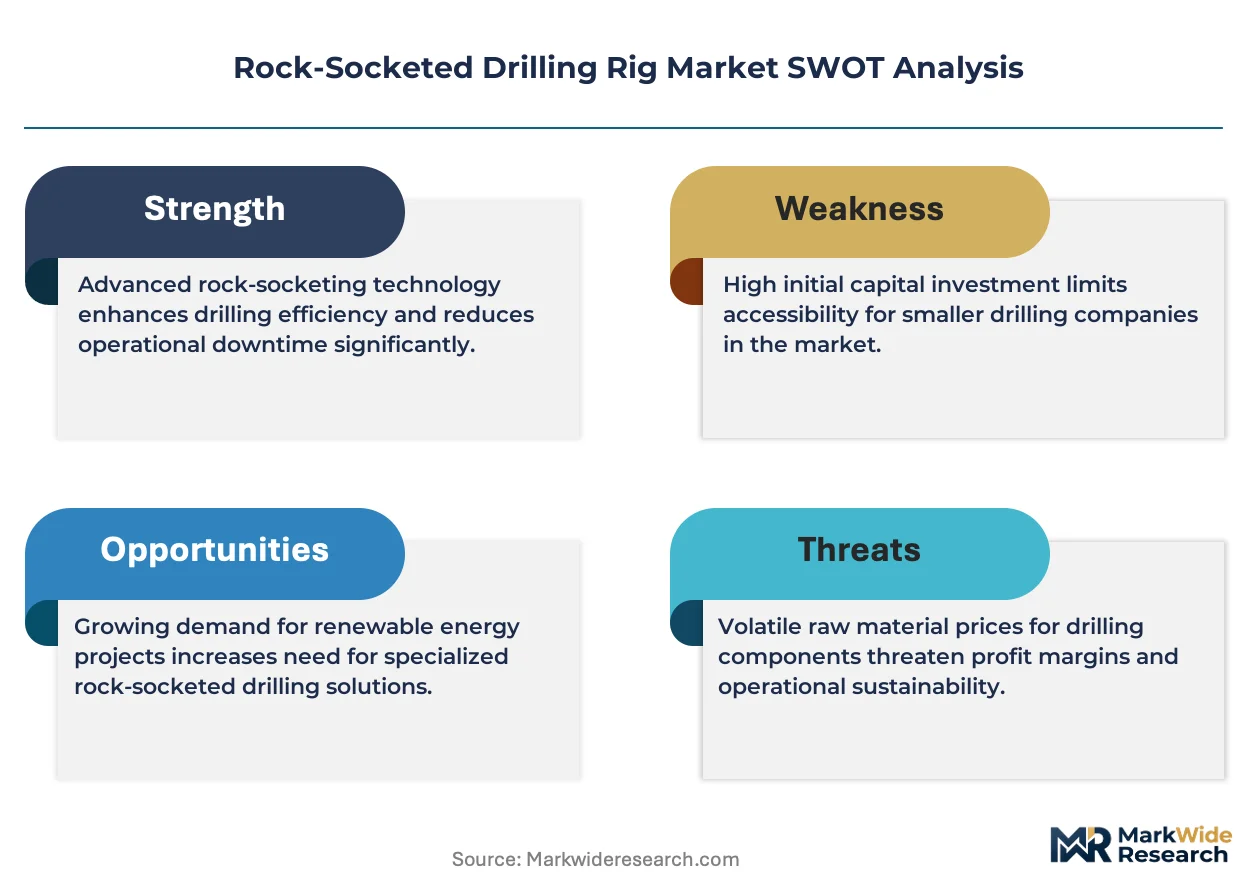
- EU Stage V emission frameworks:European urban construction fleets face mandatory emission-controlled zone compliance, accelerating hybrid-electric powertrain replacement cycles.
- Hydropower tunneling in Sichuan and Yunnan provinces:China's western infrastructure corridor generates concentrated demand for specialized rock-socketed penetration capabilities in deep foundation work.
- Deep-socketed mining foundations:Australian and Canadian extraction operations are expanding fleet orders for bedrock anchoring systems that eliminate settlement risk in variable overburden.
Market Restraints
- High-grade alloy steel input costs:Drill string and kelly bar manufacturing faces volatile nickel and chromium price swings that compress margin predictability.
- European hydraulic fluid compliance:EU F-Gas Regulation constraints on fluorinated greenhouse gases limit supplier choices and elevate certification costs for non-European OEMs.
- Sonic rig throughput limitations:Environmental sampling contracts requiring undisturbed core recovery face slower penetration rates that constrain project economics against rotary alternatives.
Strategic Opportunities
- Remote mining automation:Autonomous drill string control and telemetry integration create white space for performance-based contracting in Australian Pilbara and Canadian oil sands operations.
- Urban geotechnical compaction:Southern European restricted-access sites favor compact rotary rig formats that maneuver within dense historic city centers.
- China's dual carbon goals:MIIT emission standards and GB certification pathways for construction machinery create regulatory tailwinds for domestic hybrid powertrain development.
Industry Challenges
- Intelligent drilling control integration:Legacy diesel-hydraulic fleets require costly retrofitting to accommodate sensor arrays and automated torque management systems.
- CE-MDR and GB standard divergence:Manufacturers face parallel certification timelines and incompatible safety interlock requirements that fragment aftermarket service architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rock-Socketed Drilling Rig Market |
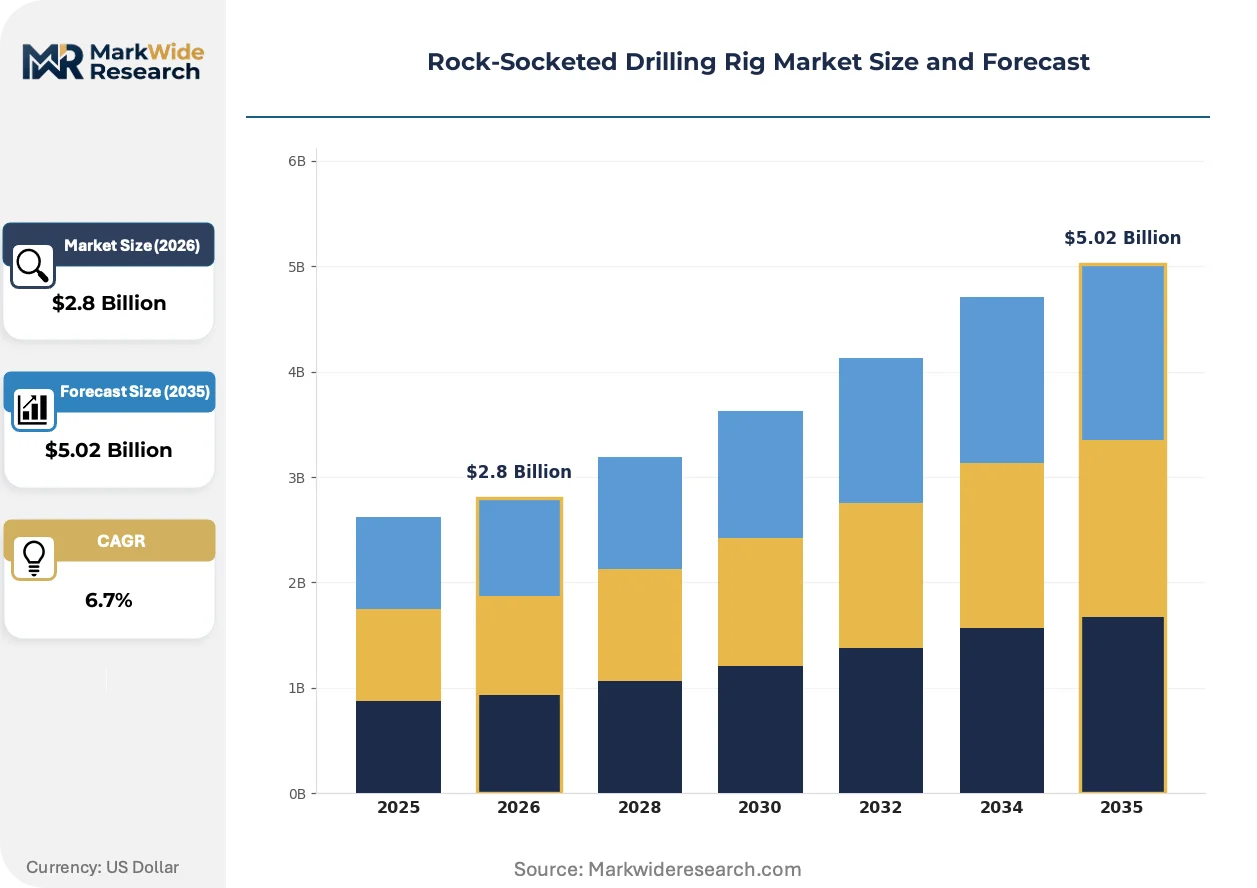
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rig Type: Rotary, Percussion, Top-Hammer, Down-The-Hole, Sonic Technology: Hydraulic, Pneumatic, Electric, Diesel, Hybrid Application: Mining, Geotechnical Investigation, Environmental Sampling, Water Well Drilling, Construction End User: Mining Companies, Construction Firms, Research Institutes, Water Resource Management Agencies |
| Companies Covered | Soilmec S.p.A, SANY Group, Zoomlion Heavy Industry Science and Technology, CITIC Heavy Industries, Tesmec S.p.A, Dando Drilling, Mastenbroek, Sunward Intelligent Equipment, Shandong Hengwang Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rock-Socketed Drilling Rig Market Trends and Innovations
Foundation engineering equipment is converging around autonomous drilling control, emission-compliant powertrains, and unbundled service models that separate hardware ownership from operational performance.
Intelligent drilling control systems is digitizing torque management and penetration rate optimization across deep-socketed foundation work. Mining contractors in Australia are adopting these platforms fastest, driven by labor scarcity and 24-hour shift requirements. The technology is digitizing competitive differentiation from mechanical reliability toward predictive maintenance and remote diagnostics capabilities.
China's GB standards on construction machinery emissions and safety interlocks are tightening product certification requirements for domestic sales and export eligibility. Manufacturers must redesign hydraulic systems and engine packages to satisfy MIIT mandates, elevating R&D allocation toward compliance engineering. Domestic OEMs with captive component manufacturing gain timeline advantages over import-dependent competitors.
Performance-based contracting is displacing traditional equipment purchase models in European urban construction. Contractors in Germany and France now procure drilled shaft capacity by linear meter rather than machine ownership, transferring utilization risk to OEM service organizations. This shift compresses capital deployment for mid-tier geotechnical specialists while concentrating fleet ownership among integrated manufacturers.
Rock-Socketed Drilling Rig Market Segmentation
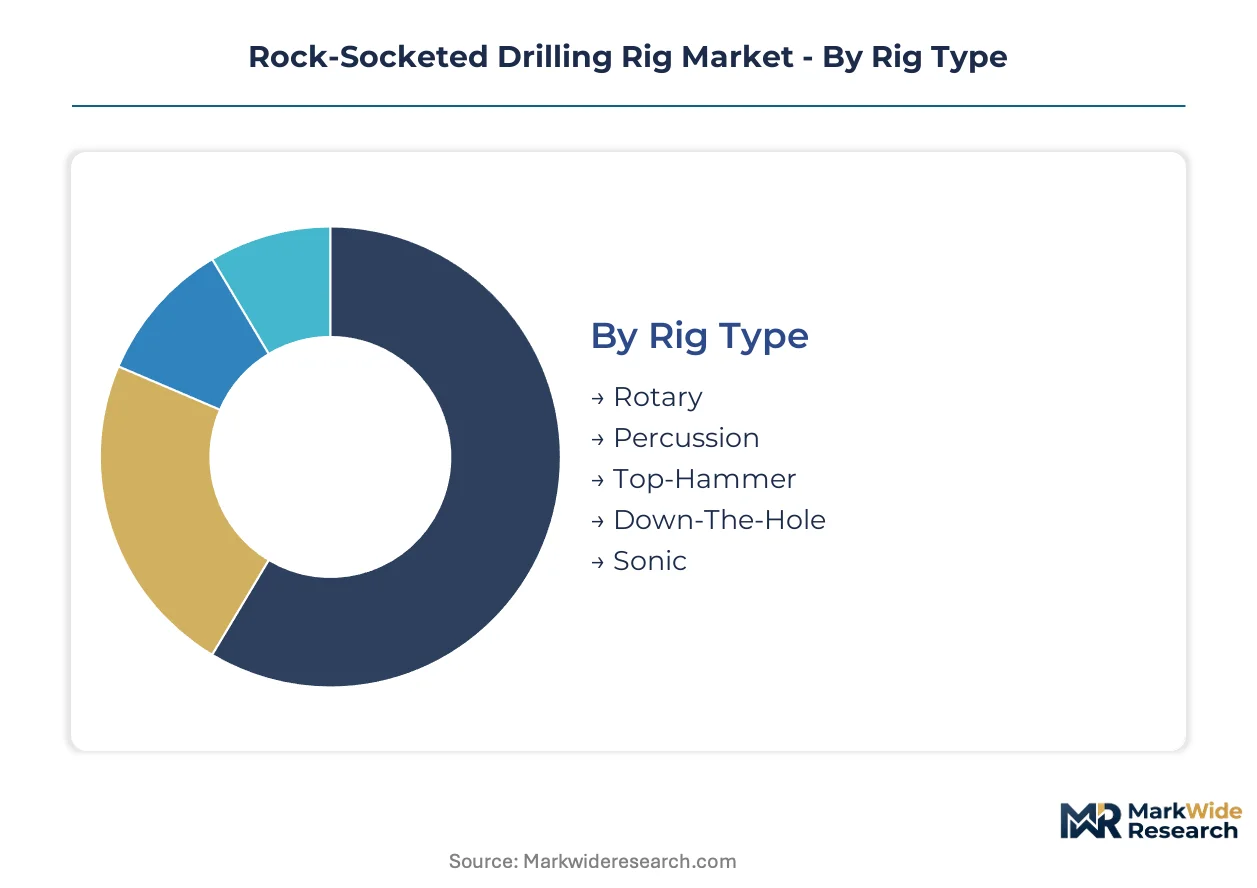
Segmentation in rock-socketed drilling rigs reveals how torque requirements, emission constraints, and project economics fragment procurement patterns across foundation engineering. Equipment specification diverges sharply between deep mining sockets demanding 200+ kNm torque and urban geotechnical work prioritizing compact maneuverability.
Rig Type:
Mature rotary technology anchors the installed base while emerging sonic formats capture premium environmental contracts.
- Rotary:These rigs deploy continuous flight augers and tricone bits to achieve socket depths of 3-20 meters in competent rock strata. Australian Pilbara mining operations specify rotary units for bedrock anchoring systems that eliminate settlement risk in variable overburden conditions.
- Sonic:High-frequency resonant drill heads generate 50-150 Hz vibrations that liquefy soil and preserve undisturbed core samples. Environmental sampling contracts in Germany's brownfield remediation sites mandate sonic recovery where regulatory compliance requires intact stratigraphic records.
- Percussion:Pneumatic or hydraulic hammer mechanisms deliver impact energy for hard rock penetration in shallow socket applications.
- Top-Hammer:Drill string transmits impact from surface-mounted hammers, optimizing energy efficiency in bench drilling and pre-splitting operations.
- Down-The-Hole:Hammer positioned directly above the bit reduces energy losses in deep boreholes exceeding 50 meters.
Rotary retains volume leadership; sonic holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium hybrid systems from standard diesel-hydraulic configurations dominating remote deployments.
- Diesel:Conventional powertrains sustain the majority of mining fleet orders in Canada and Australia where grid access remains limited. These configurations face replacement pressure from EU Stage V emission frameworks that restrict urban construction zone eligibility.
- Hybrid:Combined diesel-electric architectures enable zero-emission operation in European emission-controlled zones while preserving range for remote site transit. SANY Group and Zoomlion accelerate development to satisfy China's MIIT GB certification pathways for construction machinery.
- Hydraulic:Fluid power transmission delivers precise torque control for deep-socketed foundation work in heavy civil construction.
- Pneumatic:Compressed air systems dominate top-hammer and down-the-hole percussion rigs in hard rock mining applications.
- Electric:Grid-tethered or battery-electric units eliminate local emissions for tunneling projects in China's Sichuan and Yunnan hydropower corridors.
Diesel maintains installed base dominance; hybrid systems are climbing the fastest.
Application:
Application concentration follows infrastructure investment cycles, with mining and construction commanding capital deployment while environmental sampling operates at premium margins.
- Mining:Deep-socketed bedrock foundations anchor processing plants, tailings dams, and heavy equipment pads against differential settlement. Fleet orders from Australian and Canadian extraction operations concentrate demand for high-torque rotary configurations.
- Geotechnical Investigation:Site characterization for transport tunnels and dam foundations requires continuous core recovery and in-situ testing capabilities.
- Environmental Sampling:Undisturbed core recovery mandates sonic technology where regulatory frameworks require intact stratigraphic documentation.
- Water Well Drilling:Aquifer development programs in arid regions deploy percussion and rotary rigs for production boreholes.
- Construction:Building and bridge foundations in China's western provinces drive specialized rock-socketed penetration demand.
Mining commands the largest equipment volume; environmental sampling delivers the highest margin per meter drilled.
End User:
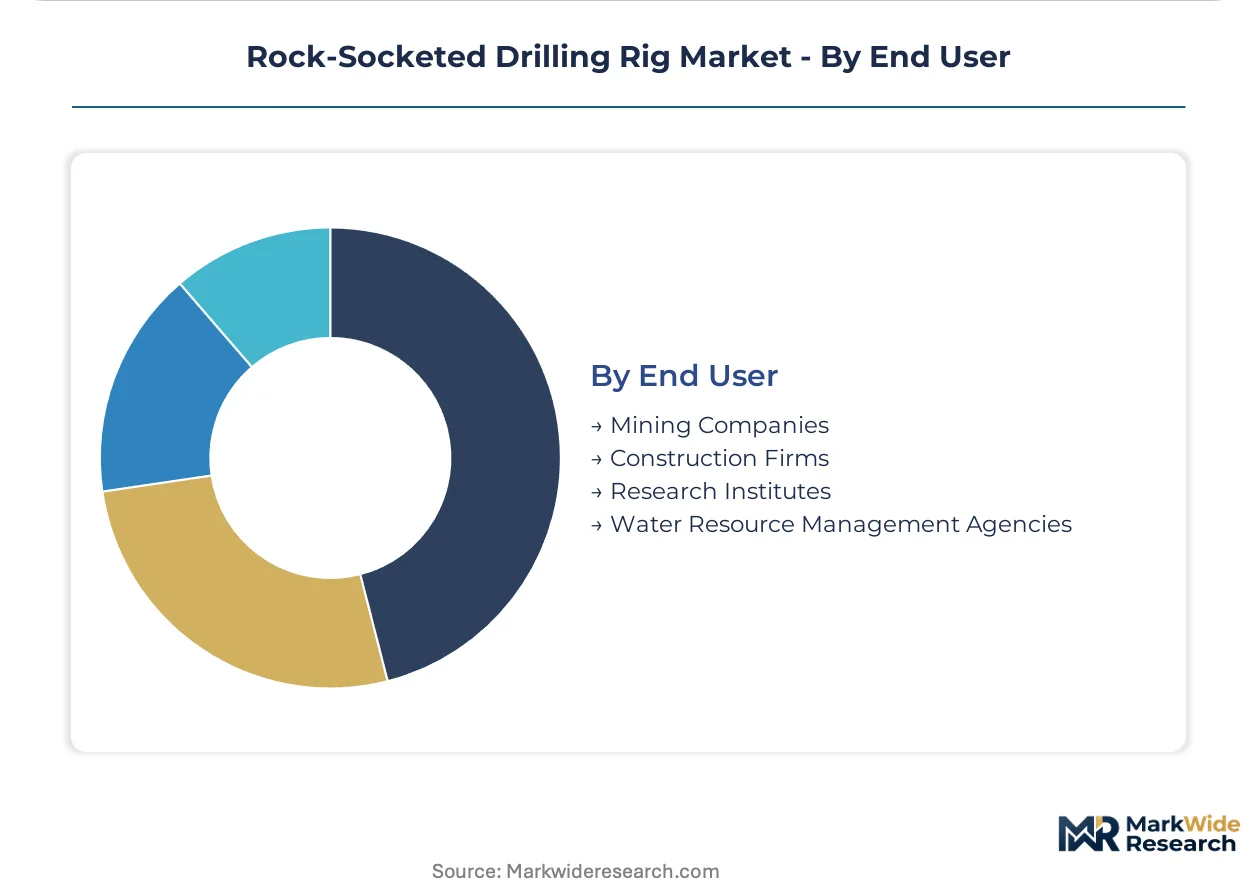
Customer type determines procurement model sophistication, with mining companies adopting performance contracts while research institutes specify precision instrumentation.
- Mining Companies:Large-scale extraction operators in Australia and Canada procure drilled shaft capacity through integrated performance contracts rather than equipment ownership. These arrangements bundle hardware, telemetry, and remote diagnostics to optimize 24-hour shift utilization.
- Construction Firms:German and French urban contractors now source linear-meter capacity from OEM service organizations, compressing capital deployment for mid-tier geotechnical specialists.
- Research Institutes:Scientific drilling programs require instrumented rigs with real-time data acquisition for crustal studies and climate archive recovery.
- Water Resource Management Agencies:Public sector procurement emphasizes lifecycle cost and local content requirements for groundwater development projects.
Mining companies drive fleet renewal cycles; construction firms are gaining share fastest through unbundled service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining contractors in Australia and Canada dominate fleet procurement through performance-based contracts, while European urban construction drives hybrid powertrain adoption under emission-controlled zones.
China
Hydropower tunneling in Sichuan and Yunnan provinces generates concentrated demand for specialized rock-socketed penetration capabilities in deep foundation work. MIIT enforces GB standards on construction machinery emissions and safety interlocks, conditioning product certification for domestic sales and export eligibility. SANY Group and Zoomlion Heavy Industry Science and Technology leverage integrated manufacturing clusters in Changsha to accelerate hybrid powertrain development aligned with dual carbon goals.
Australia
Pilbara mining operations specify high-torque rotary rigs for bedrock anchoring systems that eliminate settlement risk in variable overburden conditions. The TGA regulates workplace safety equipment standards, influencing rig specification for remote site deployment. Perth-based contractors adopt autonomous drill string control and telemetry integration to optimize 24-hour shift utilization amid persistent labor scarcity.
Canada
Oil sands extraction operations in Alberta expand fleet orders for deep-socketed foundation work in tailings dam construction. Health Canada oversees environmental assessment protocols that mandate undisturbed core recovery in sensitive watershed zones. Edmonton and Calgary serve as procurement hubs where mining companies bundle hardware, software, and remote diagnostics through integrated performance contracts.
Germany
Brownfield remediation sites in the Ruhr region mandate sonic technology for environmental sampling where regulatory compliance requires intact stratigraphic records. The KBA enforces Stage V emission frameworks that restrict diesel-hydraulic rig eligibility in urban construction zones. Munich and Stuttgart contractors now procure drilled shaft capacity by linear meter rather than machine ownership, compressing capital deployment for mid-tier geotechnical specialists.
Italy
Restricted-access urban geotechnical sites across Rome, Milan, and Naples favor compact rotary rig formats that maneuver within dense historic city centers. ANSM certification requirements intersect with CE-MDR safety interlock standards, elevating compliance complexity for domestic and import equipment alike. Soilmec S.p.A anchors the Southern European market through specialized compact rotary configurations designed for foundation work in confined metropolitan conditions.
Rock-Socketed Drilling Rig Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates ownership among integrated manufacturers while fragmenting procurement among mid-tier service contractors. Equipment vendors face pressure to restructure from hardware sales toward bundled performance contracts that transfer utilization risk to OEM service organizations. Three strategic archetypes dominate: integrated conglomerates with captive component manufacturing, regional specialists in compact urban formats, and technology-focused developers of intelligent drilling control systems. Competitive moves center on M&A to secure telemetry capabilities and strategic partnerships to access emission-compliant powertrain technologies.
Among Asia-Pacific-based integrated manufacturers, SANY Group and Zoomlion Heavy Industry Science and Technology occupy positions that exemplify the conglomerate archetype, leveraging in-house hydraulic component production to control cost positions across the regional basin. Soilmec S.p.A represents the specialist tier, anchoring competitive stance through compact rotary formats purpose-built for restricted-access European urban sites. These three companies illustrate how geographic origin and structural configuration shape strategic positioning without requiring uniform capability profiles.
| Leading Market Players |
|---|
| Soilmec S.p.A |
| SANY Group |
| Zoomlion Heavy Industry Science and Technology |
| CITIC Heavy Industries |
| Tesmec S.p.A |
| Dando Drilling |
| Mastenbroek |
| Sunward Intelligent Equipment |
| Shandong Hengwang Group |
| Others |
Pricing and Supply Chain Analysis
Commodity volatility in nickel and chromium alloy feedstocks compresses margin predictability across drill string manufacturing tiers while simultaneously fragmenting procurement strategies between long-term contract buyers and spot-market purchasers. This input cost instability widens pricing spreads between premium certified rigs and standard configurations while reshaping supplier geography toward integrated steel-producing regions.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate large mining fleet procurement in Australia and Canada, transferring alloy steel price risk to end-users through quarterly adjustment clauses. Three-tier pricing structure across premium hybrid-electric, standard diesel-hydraulic, and economy refurbished tiers reflects certification grade differentiation under EU Stage V and China's GB emission standards. Cost compression in the standard tier is intensifying because mining contractors consolidate orders through performance-based contracting that bundles hardware, telemetry, and remote diagnostics. Mining companies exhibit lowest price sensitivity due to 24-hour utilization economics, while mid-tier European geotechnical specialists face acute capital constraints driving linear-meter service adoption.
Supply Chain Analysis
High-grade alloy steel production concentrates in China, Germany, and Japan, with Changsha and Essen serving as primary feedstock hubs for hydraulic component and drill string manufacturing. SANY Group and Zoomlion draw from captive in-house forging capabilities, while Western OEMs rely on third-party kelly bar and tricone bit suppliers from these geographies. Single-source vulnerability in specialized torque transmission components creates procurement risk for non-integrated manufacturers dependent on Changsha hydraulic cluster output. Distribution runs through OEM-direct channels for large mining contracts and specialized equipment distributors for urban geotechnical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mining company consolidation toward integrated performance contracting concentrates buyer power among a shrinking cohort of large extraction operators, forcing equipment vendors to absorb utilization risk through service-based revenue models rather than transactional sales.
For Market Incumbents: Insulate margin positions through backward integration into hydraulic component manufacturing and captive alloy steel sourcing from Changsha or Ruhr Valley production clusters. SANY Group's control over in-house forging and Zoomlion's R&D investment in intelligent drilling control systems demonstrate how upstream capability ownership defends against price erosion from emerging Chinese competitors. Prioritize certification engineering resources toward simultaneous GB and CE-MDR compliance to prevent aftermarket service fragmentation from divergent safety interlock requirements. For New Entrants and Emerging Players: Compact rotary rigs for restricted-access urban geotechnical sites in Southern Europe represent the most penetrable entry point, with Rome, Milan, and Naples generating sustained demand where Soilmec S.p.A currently dominates. Australia's autonomous drilling telemetry integration presents a second white-space opportunity where labor scarcity drives rapid technology adoption. Partner with established hydraulic component suppliers in Changsha to compress development timelines and access GB certification pathways for Chinese market eligibility. For Investors and Strategic Acquirers: EU Stage V emission framework enforcement reshapes the acquisition landscape by elevating hybrid powertrain development capabilities above pure mechanical engineering competence. Long-term viability over the next decade hinges on software-integrated drilling control systems rather than traditional rig manufacturing scale. Target acquisition archetypes include telemetry platform developers and emission-compliant powertrain engineering teams. Watch for MIIT GB standard tightening as the signal indicating accelerated domestic Chinese OEM consolidation and export eligibility barriers for non-compliant foreign competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Development | EU Stage V and China's GB standards mandate emission-compliant architectures for urban zone eligibility. |
| Intelligent Drilling Control Integration | Autonomous torque management addresses Australian Pilbara labor scarcity and 24-hour shift optimization. |
| Performance-Based Contracting Model | German and French contractors now procure linear-meter capacity, transferring utilization risk to OEMs. |
| Backward Integration into Hydraulic Components | SANY Group's captive manufacturing controls cost positions across Asia-Pacific basin procurement. |
| Dual Certification Engineering Investment | Parallel GB and CE-MDR compliance prevents aftermarket service architecture fragmentation. |
Research Methodology
Desk research of customs trade databases, mining fleet procurement records, and construction machinery certification filings preceded structured interviews with foundation engineering contractors, mining maintenance directors, OEM procurement teams, and aftermarket service heads. Primary fieldwork across Australian Pilbara operations, Sichuan hydropower corridors, and German brownfield remediation sites validated secondary estimates of hybrid powertrain adoption rates and performance contract penetration. Bottom-up rig shipment analysis triangulated against top-down infrastructure investment forecasts from national planning agencies.
Assumptions held fixed include current EU Stage V and China GB emission enforcement trajectories, while alloy steel price volatility and autonomous drilling technology diffusion rates were modeled as scenario variables across the projection horizon. Segmentation modeling incorporated rig type, powertrain technology, application concentration, and end-user procurement sophistication dimensions. CAGRs derived from regression analysis of historical fleet replacement cycles against announced mining and hydropower capital programs, with torque output requirements and emission zone expansion schedules serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in mining commodity prices, Chinese infrastructure stimulus intensity, or European construction activity would shift the trajectory of fleet renewal demand. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology adoption S-curves. Cross-checking against national mining association equipment surveys and MIIT construction machinery production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Global Dozers Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Mining Shovel Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Global Autonomous Mining Equipment Market