
 Asia-Pacific Robotics and Automation Actuators Market | 2026-2036
Asia-Pacific Robotics and Automation Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Robotics and Automation Actuators Market Analytics
South Korea's advanced manufacturing corridor is rewriting actuator procurement patterns across the region. Fanuc Corporation leverages its captive servo motor foundries to sustain margin control in high-precision segments. Yaskawa Electric Corporation anchors regional supply through its Kitakyushu production complex and extensive distributor network.
Robotics and automation actuators are electromechanical devices that convert energy into controlled mechanical motion, typically achieving positioning accuracy within micrometer tolerances through servo feedback loops or stepper indexing sequences. They serve as the terminal motion element in automated systems across assembly, material handling, and process control applications. Electric actuators incorporating servo technology command premium positioning in semiconductor and electronics manufacturing due to repeatability requirements, while pneumatic variants retain cost advantages in food and beverage packaging where washdown compliance and explosion safety matter. The OEM end-user channel concentrates volume, though system integrators capture higher value-add through application engineering and commissioning services.
Japan's METI enforces JIS standards on industrial robot safety and electromagnetic compatibility, while China's MIIT administers GB standards for servo system energy efficiency and network security in connected actuators. South Korea's MFDS and KOSHA frameworks impose functional safety certifications on healthcare and collaborative robot deployments. Stakeholders must monitor divergence between national certification regimes as compliance costs fragment cross-border product strategies.
Market Dynamics
China's MIIT mandates on industrial robot density are compressing deployment timelines across the Yangtze River Delta manufacturing corridor, forcing actuator suppliers to accelerate certification cycles and localize servo motor production.
Growth Catalysts
- Electric Vehicle Assembly Expansion:Automotive OEMs across China and Japan are scaling actuator procurement for battery module handling and electric powertrain assembly lines.
- MIIT Robot Density Mandates:China's Ministry of Industry and Information Technology compliance requirements are tightening procurement specifications for connected servo systems in connected factories.
- Semiconductor Equipment Investment:Wafer handling robotics in South Korea's Pyeongtaek cluster is driving demand for sub-micron positioning actuators with integrated force feedback.
Market Restraints
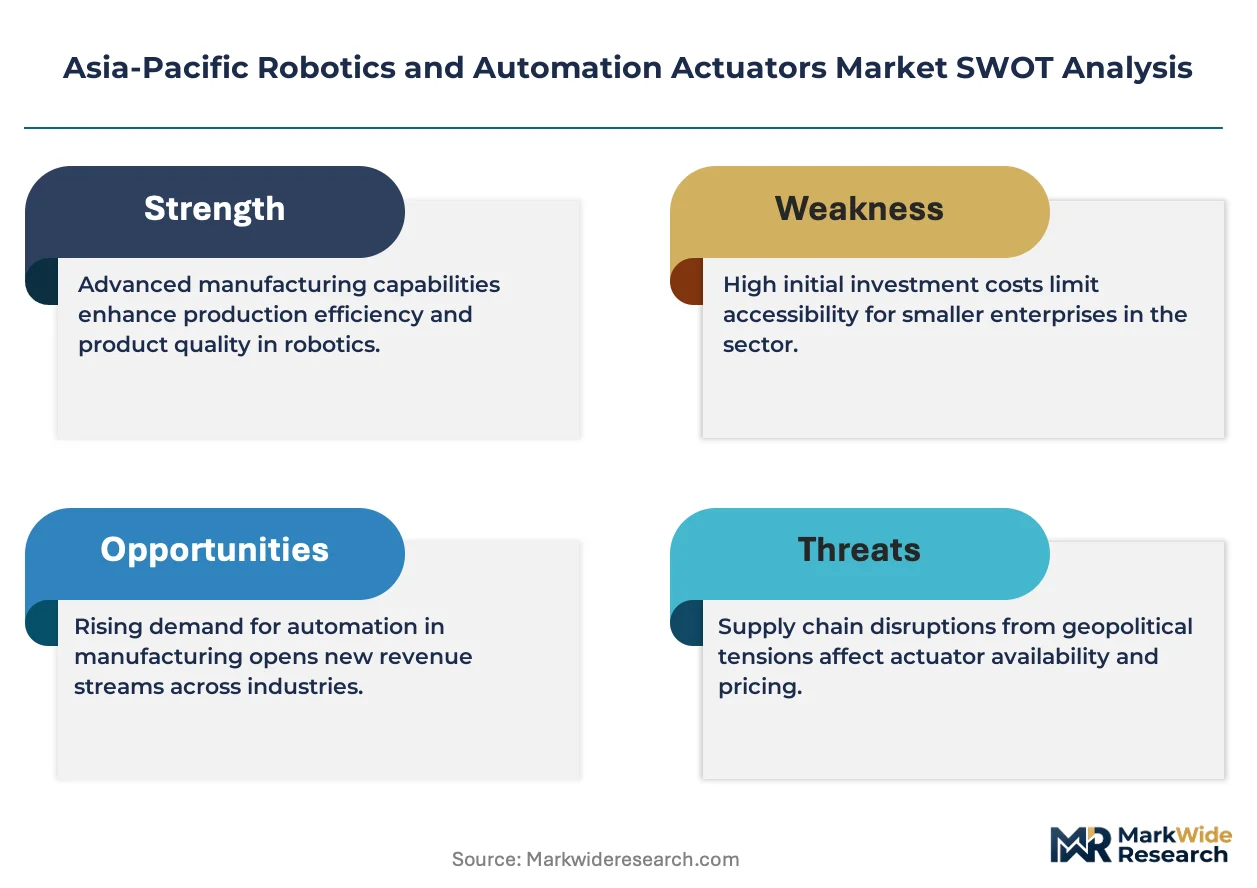
- Rare Earth Magnet Dependency:Neodymium supply concentration in China's Inner Mongolia processing facilities creates input cost volatility for high-torque servo motors.
- Cross-Border Certification Friction:Divergence between Japan's JIS standards and China's GB standards fragments product strategies and extends compliance timelines.
- Pneumatic Substitution in Food Packaging:Washdown-compliant pneumatic actuators retain cost advantages over electric alternatives in beverage bottling applications.
Strategic Opportunities
- Vietnam Manufacturing Migration:Electronics contract manufacturers relocating from China are creating greenfield demand for collaborative robot actuators in Bac Ninh and Hai Phong industrial zones.
- 5G-Enabled Predictive Maintenance:Convergence of industrial IoT sensors and edge computing is enabling condition-based actuator servicing contracts.
- India PLI Scheme for Robotics:The Production Linked Incentive scheme for industrial automation is opening tariff-advantaged procurement channels for servo system integrators.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time control algorithm development for multi-axis synchronization requires specialized firmware engineers concentrated in Tokyo and Shenzhen.
- Legacy System Integration Complexity:Retrofitting analog-drive actuators with EtherCAT and PROFINET protocols demands custom gateway engineering for brownfield automotive plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Robotics and Automation Actuators Market |
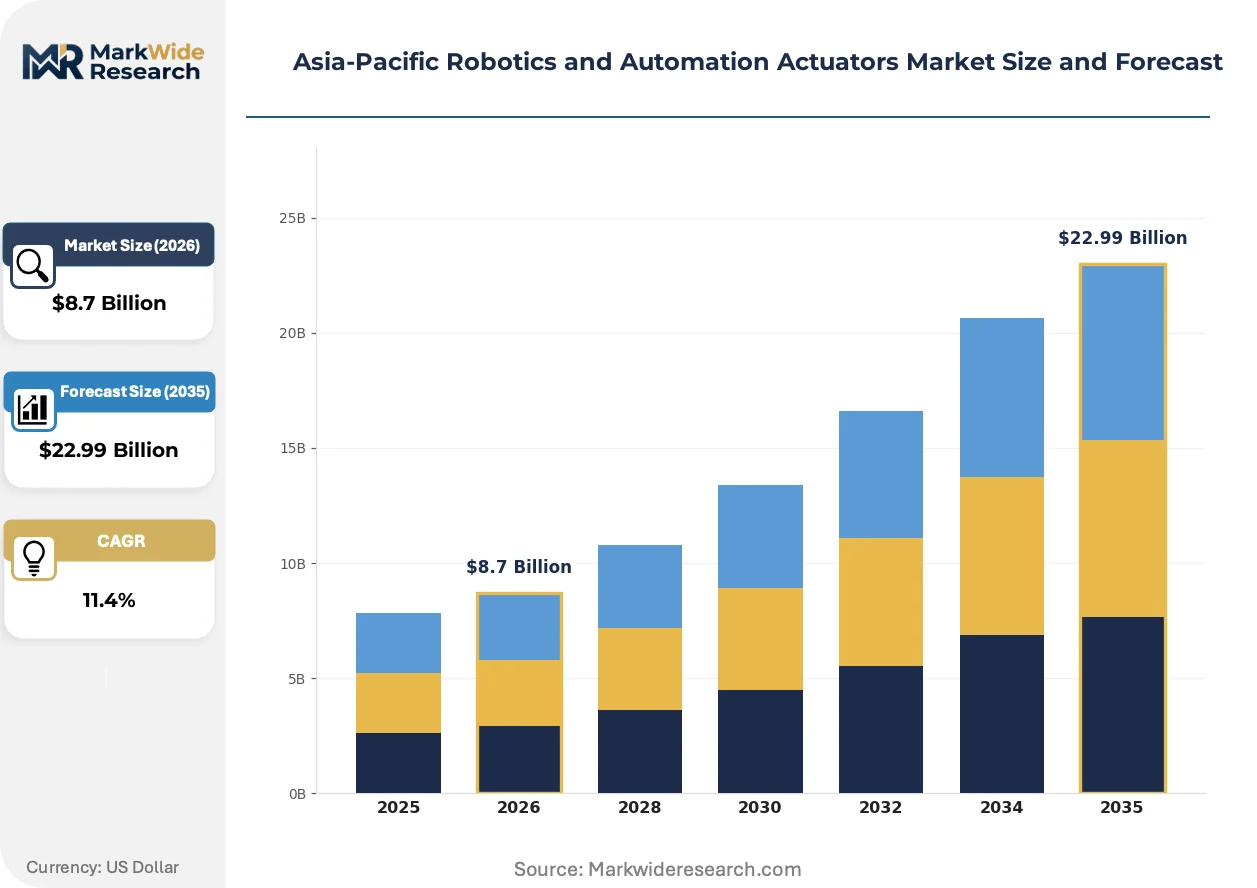
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Actuators, Pneumatic Actuators, Electric Actuators, Mechanical Actuators Industry Vertical: Manufacturing, Healthcare, Automotive, Food & Beverage Technology: Servo Technology, Stepper Technology, Linear Technology, Rotary Technology End User: OEMs, System Integrators, Maintenance Providers, Research Institutions |
| Companies Covered | Fanuc Corporation, Yaskawa Electric Corporation, SMC Corporation, ABB Limited, MISUMI Corporation, UBTECH Robotics, Xiaomi Corporation, Toshiba Corporation, Omron Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Robotics and Automation Actuators Market Evolving Landscape
Digital servo architectures are displacing analog drive systems across precision manufacturing, while regulatory pressure on energy efficiency and network security is reshaping product certification requirements throughout the region.
Integrated servo-drive modules with embedded motion controllers are digitizing commissioning workflows by collapsing cabinet space requirements and enabling remote parameter tuning. Semiconductor fabs in South Korea are adopting these compact units for cleanroom-constrained installations. This consolidation is digitizing traditional distributor value chains by shifting application engineering toward software-based configuration tools.
Japan's METI enforcement of updated JIS B 8433 electromagnetic compatibility standards is mandating shielded cabling and filtered power entry modules for all new collaborative robot deployments. Industrial robot OEMs in Nagoya are redesigning actuator enclosures to meet conducted emission limits. Medical device manufacturers exporting to Japan are accelerating pre-certification testing to avoid customs delays.
System integrators are unbundling after-sales service contracts from hardware procurement, selling predictive maintenance subscriptions separately through cloud-connected actuator health monitoring. Electronics manufacturers in China's Pearl River Delta are piloting usage-based pricing for high-precision linear actuators. This service model is most visible in flat-panel display assembly where unplanned downtime costs exceed hardware depreciation.
Asia-Pacific Robotics and Automation Actuators Market Segmentation
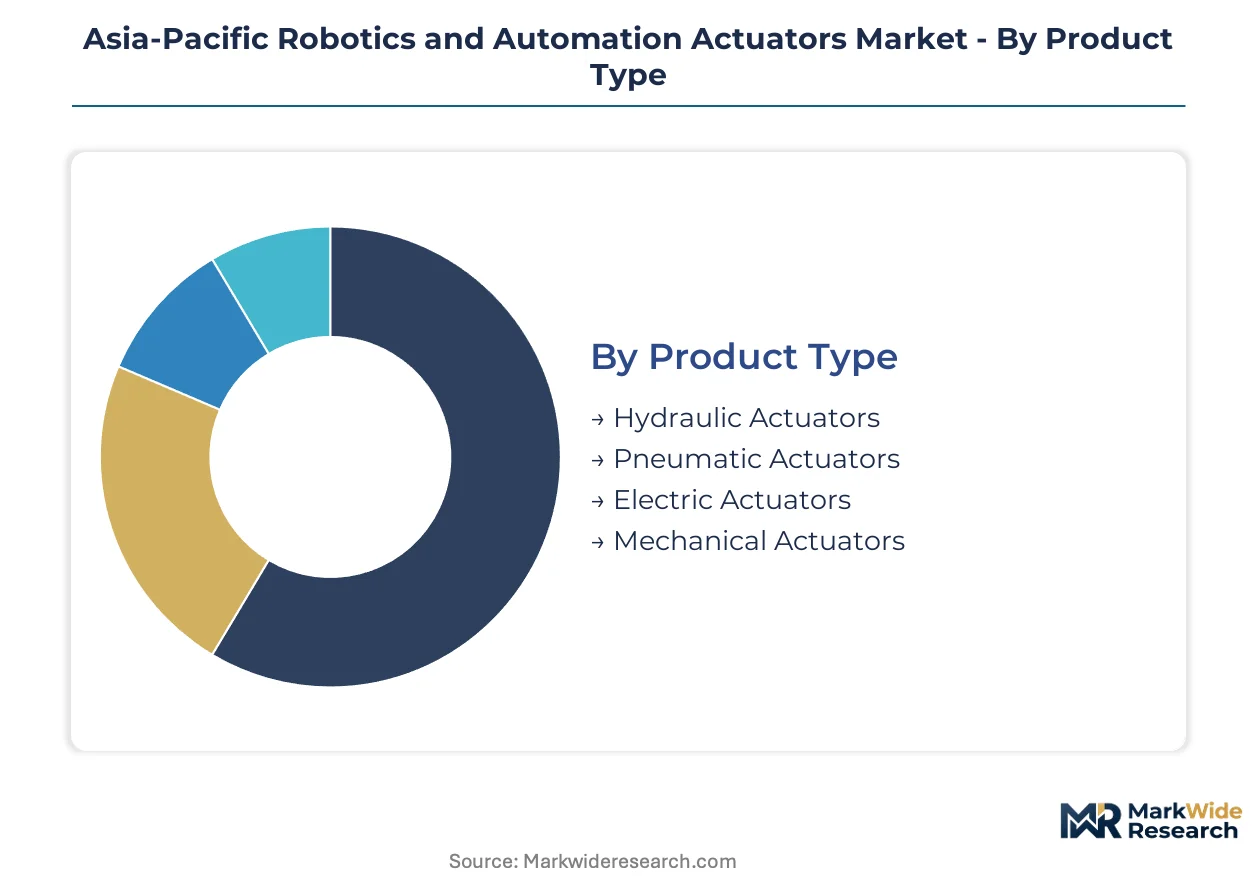
Actuator procurement patterns diverge sharply across product architectures and end-use channels, with after-sales service intensity varying from minimal for pneumatic replacements to substantial for servo system lifecycle management. Understanding these segment boundaries clarifies margin architecture and channel investment priorities for suppliers competing across China's Yangtze River Delta and Japan's Nagoya manufacturing belt.
Product Type:
After-sales service intensity escalates from pneumatic spares to electric servo system overhauls, with hydraulic actuator maintenance demanding specialized fluid power expertise concentrated in legacy automotive plants.
- Electric Actuators:Servo motor and drive combinations achieve micrometer positioning accuracy through closed-loop feedback control. Demand concentrates in South Korea's Pyeongtaek semiconductor cluster where wafer handling robotics require sub-micron repeatability; MIIT energy efficiency mandates on connected factories are accelerating displacement of pneumatic alternatives in China's precision assembly lines.
- Pneumatic Actuators:Compressed air cylinders and rotary actuators deliver cost-effective motion in washdown environments through simple mechanical design. Food and beverage packaging lines across Japan's Kansai region retain these units for explosion safety compliance; lower maintenance complexity reduces service contract attach rates versus electric alternatives.
- Hydraulic Actuators:High-force fluid power systems dominate heavy pressing and metal forming applications in legacy automotive stamping plants.
- Mechanical Actuators:Screw and cam mechanisms persist in low-speed positioning tasks where electrical infrastructure is limited.
Electric actuators hold the largest share; momentum sits with servo-integrated architectures as factory digitization accelerates.
Industry Vertical:
Application requirements shape actuator specification hierarchies, with semiconductor and electric vehicle manufacturing commanding premium positioning precision while food packaging prioritizes washdown durability.
- Automotive:Battery module handling and electric powertrain assembly lines in China and Japan are scaling multi-axis servo systems for flexible manufacturing. Yangtze River Delta OEMs are retrofitting analog-drive actuators with EtherCAT protocols to meet MIIT connected factory mandates.
- Manufacturing:General automation spans material handling, assembly, and process control across electronics contract manufacturers relocating to Vietnam's Bac Ninh province.
- Healthcare:South Korea's MFDS functional safety certifications govern collaborative robot deployments in surgical and rehabilitation applications.
- Food & Beverage:Pneumatic actuators retain cost advantages in beverage bottling where explosion safety and washdown compliance dominate specification criteria.
Automotive applications command the highest unit values; healthcare installations are expanding most quickly on collaborative robot penetration.
Technology:
Control architecture selection determines commissioning complexity and long-term service revenue potential, with digital servo systems enabling remote parameter tuning and predictive maintenance subscriptions.
- Servo Technology:Closed-loop motor control with encoder feedback enables dynamic positioning and torque limiting for collaborative robotics. Japan's METI JIS B 8433 electromagnetic compatibility standards are mandating shielded cabling and filtered power entry modules for all new deployments.
- Stepper Technology:Open-loop indexing suits low-cost positioning in pick-and-place applications across China's Pearl River Delta electronics assembly.
- Linear Technology:Direct-drive mechanisms eliminate mechanical transmission losses in flat-panel display assembly where unplanned downtime costs exceed hardware depreciation.
- Rotary Technology:Gearmotor combinations persist in conveyor and material handling systems throughout Southeast Asian manufacturing migration corridors.
Servo technology dominates precision segments; linear direct-drive architectures are gaining share fastest in cleanroom-constrained semiconductor installations.
End User:
Channel structure fragments between high-volume OEM procurement and value-add system integration, with maintenance providers capturing recurring revenue through condition-based servicing contracts.
- OEMs:Original equipment manufacturers concentrate volume procurement for robot and machine tool production, leveraging captive servo motor foundries where available. Fanuc Corporation and Yaskawa Electric Corporation anchor regional supply through integrated manufacturing complexes.
- System Integrators:Application engineering and commissioning services capture margin premiums through multi-axis synchronization and custom control algorithm development.
- Maintenance Providers:Cloud-connected actuator health monitoring enables unbundled predictive maintenance subscriptions separate from hardware procurement.
- Research Institutions:Universities and national laboratories prototype next-generation control architectures with specialized firmware requirements.
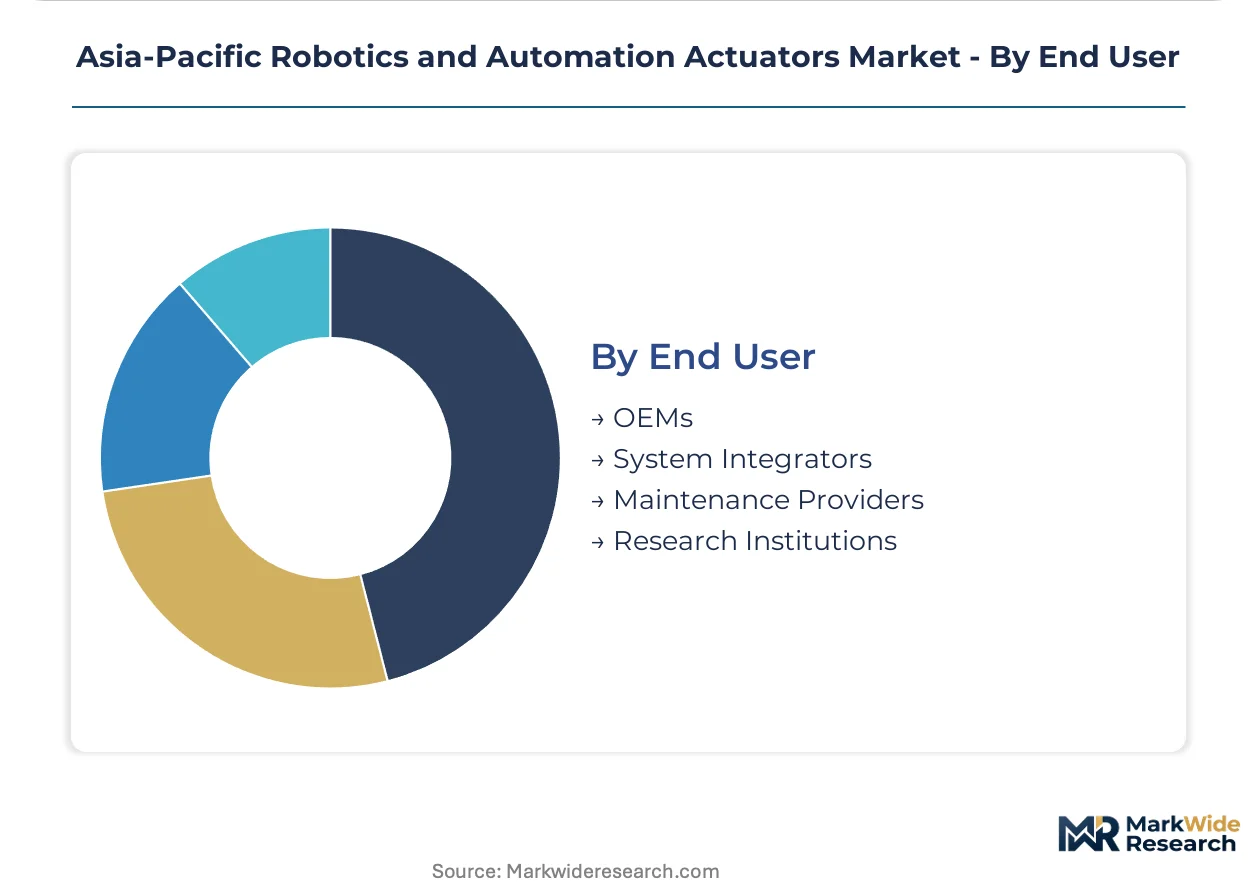
OEMs represent the dominant procurement channel; system integrators are capturing expanding value-add as factory digitization demands application-specific engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in China's Yangtze River Delta and Japan's Nagoya belt, with South Korea's Pyeongtaek cluster anchoring semiconductor-grade demand. Regional divergence in certification regimes fragments product strategies and extends compliance timelines for cross-border suppliers.
China
MIIT mandates on industrial robot density are compressing deployment timelines across manufacturing corridors. The ministry's GB standards for servo system energy efficiency and network security tighten procurement specifications for connected factories. Yangtze River Delta OEMs are retrofitting analog-drive actuators with EtherCAT protocols to meet connected factory mandates.
Japan
METI enforcement of updated JIS B 8433 electromagnetic compatibility standards is mandating shielded cabling and filtered power entry modules. Medical device manufacturers exporting to Japan are accelerating pre-certification testing to avoid customs delays. Nagoya industrial robot OEMs are redesigning actuator enclosures to meet conducted emission limits.
South Korea
MFDS and KOSHA frameworks impose functional safety certifications on healthcare and collaborative robot deployments. Wafer handling robotics in Pyeongtaek's semiconductor cluster drives demand for sub-micron positioning actuators with integrated force feedback. The Busan-Ulsan manufacturing belt is scaling battery module handling systems for electric vehicle supply chains.
Vietnam
Electronics contract manufacturers relocating from China are creating greenfield demand for collaborative robot actuators. The Bac Ninh and Hai Phong industrial zones are absorbing assembly line automation investments from Pearl River Delta migrants. Local industrial zones are prioritizing washdown-compliant pneumatic systems for food and beverage packaging.
India
The Production Linked Incentive scheme for industrial automation is opening tariff-advantaged procurement channels for servo system integrators. Karnataka and Tamil Nadu manufacturing corridors are piloting predictive maintenance subscriptions through cloud-connected actuator health monitoring. Electronics manufacturers in the Delhi-NCR belt are retrofitting legacy systems with digital servo architectures.
Asia-Pacific Robotics and Automation Actuators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base organizes around three tiers: diversified industrial conglomerates with captive servo motor foundries, focused motion control specialists with regional distributor networks, and emerging robotics platforms with integrated actuator-design capabilities. Consolidation pressure runs through M&A activity targeting servo drive technology assets, while capacity expansion concentrates in China's Yangtze River Delta and Japan's Kyushu region.
Within the diversified industrial tier, Fanuc Corporation and Yaskawa Electric Corporation exemplify integrated manufacturing complexes with captive production of precision motion components. SMC Corporation occupies a position among pneumatic system specialists with established washdown-compliant product lines for food and beverage applications. These three anchors represent distinct competitive archetypes: the vertically integrated robot OEM, the motion control platform with regional supply chain density, and the fluid power specialist defending cost-positioned segments.
| Leading Market Players |
|---|
| Fanuc Corporation |
| Yaskawa Electric Corporation |
| SMC Corporation |
| ABB Limited |
| MISUMI Corporation |
| UBTECH Robotics |
| Xiaomi Corporation |
| Toshiba Corporation |
| Omron Corporation |
| Others |
Value Network & Pricing Analysis
Shanghai-Nagoya container freight corridors transmit cost volatility from rare earth processing clusters in China's Inner Mongolia directly into servo motor landed costs, compressing margins for distributors serving Japan's Nagoya industrial belt while amplifying price spreads between certified and uncertified actuator tiers.
Pricing Analysis
China's MIIT GB standards for servo system energy efficiency and network security dictate the pricing tier structure across the Asia-Pacific robotics actuator market. Three-tier pricing structure across premium, standard, and economy levels separates METI JIS B 8433-certified units with shielded cabling from uncertified alternatives and basic pneumatic spares. Price differentiation rests on certification grade and after-sales service bundling, with predictive maintenance subscriptions commanding recurring revenue premiums. Cost compression in economy-tier pneumatic replacements is intensifying because Vietnamese electronics contract manufacturers prioritize capital expenditure minimization during greenfield facility ramp-ups. System integrators demonstrate the lowest price sensitivity due to value-add engineering margins, while maintenance providers in India's PLI scheme corridors exhibit highest sensitivity to hardware procurement costs.
Supply Chain Analysis
Foxconn and Luxshare Precision anchor contract manufacturing concentration for servo-drive module assembly, with secondary capacity held by Delta Electronics and TDK-Lambda facilities. Geographic supply concentrates in China's Yangtze River Delta, Japan's Kyushu region, and South Korea's Gyeonggi-do province. Raw material dependencies draw from neodymium magnet processing in Inner Mongolia, silicon steel laminations from Nippon Steel's Nagoya works, and rare earth permanent magnets from Lynas Rare Earths' Malaysian separation facility. Single-source vulnerability in neodymium supply creates structural risk for high-torque servo motor production. Distribution runs through Fanuc and Yaskawa's captive distributor networks alongside independent motion control specialists serving Vietnam's Bac Ninh corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific robotics actuator market functions as a defensive-moat arena where regulatory certification entrenchment creates switching costs that lock OEMs into approved supplier relationships across multi-year deployment cycles.
For Market Incumbents: Harden certification moats by accelerating pre-clearance testing for Japan's updated JIS B 8433 electromagnetic compatibility standards before METI enforcement tightens. Deepen backward integration into rare earth magnet sourcing through offtake agreements with Lynas Rare Earths or MP Materials to neutralize neodymium price volatility threatening margin stability in high-torque servo segments. For New Entrants and Emerging Players: Pursue greenfield collaborative robot actuator deployments in Vietnam's Bac Ninh and Hai Phong industrial zones where incumbent distributor networks remain underdeveloped. Electronics contract manufacturers relocating from China's Pearl River Delta represent the most penetrable buyer segment due to urgent automation timelines and limited legacy system baggage. Lead with cloud-connected predictive maintenance subscriptions to differentiate from hardware-centric incumbents. For Investors and Strategic Acquirers: Servo drive firmware specialists with embedded motion controller IP command scarcity premiums as factory digitization accelerates. Long-term viability over the coming decade hinges on software-defined actuator architectures displacing analog legacy systems. Monitor MIIT enforcement intensity on industrial robot density mandates as the inflection signal indicating deployment velocity acceleration or deceleration across China's manufacturing corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Clearance Investment | Accelerated JIS B 8433 testing prevents METI enforcement delays for Nagoya OEMs. |
| Rare Earth Supply Agreement | Lynas offtake contracts hedge neodymium volatility for high-torque servo production. |
| Predictive Maintenance Platform Launch | Cloud-connected health monitoring captures recurring revenue from Pearl River Delta electronics manufacturers. |
| Vietnam Distribution Network Buildout | Bac Ninh corridor penetration captures greenfield demand from China manufacturing migrants. |
| Servo-Drive Module Integration | Embedded motion controllers collapse cabinet space for Pyeongtaek semiconductor cleanroom constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automation engineering directors at automotive OEMs, servo system procurement managers at electronics contract manufacturers, motion control application specialists at system integrators, and aftermarket service heads at distributor networks. Secondary validation drew from MIIT GB standard filings, METI JIS certification registries, MFDS medical device approvals, customs trade data on servo motor imports, and SEC 10-K disclosures from listed motion control suppliers. Bottom-up actuator shipment estimates triangulated against top-down manufacturing automation capex forecasts.
Calibration against historical deployment patterns anchored forward projections across the analysis window. Segmentation dimensions modeled include product architecture, industry vertical, control technology, and end-user channel structure. CAGRs derived from regression analysis of robot density mandates, electric vehicle assembly line investments, and semiconductor capital expenditure cycles. Forecast inputs incorporated MIIT compliance timeline assumptions and rare earth magnet price trajectory scenarios.
Macroeconomic conditions sit as an overlay; deviation in Chinese manufacturing PMI, Japanese yen exchange rates, or Korean semiconductor equipment capex would shift the trajectory. Quarterly review of MIIT robot density enforcement statistics, METI certification backlog data, and Vietnam FDI inflow figures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Handheld Robotics Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Waste Sorting Robots Market