
 Pallet Stretch Wrapping Machines Market | 2026-2036
Pallet Stretch Wrapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Stretch Wrapping Machines Market Outlook
China is fragmenting as domestic manufacturers add semi-automatic and rotary arm capacity to serve e-commerce fulfillment networks. Lantech leverages its North American installed base to sustain aftermarket film and parts revenue. Robopac anchors European demand with integrated weighing and wrapping systems for food exporters. Signode Industrial Group differentiates through steel strapping and stretch hybrid lines for heavy-load chemical shipments.
Pallet stretch wrapping machines apply thermoplastic film—typically linear low-density polyethylene ranging from 12 to 30 microns—around palletized loads using rotating turntables or orbiting arms to secure goods for transport and storage. The equipment integrates pre-stretch film carriages that elongate material by 200-300 percent before application, reducing per-load film consumption and stabilizing irregular pallet configurations. Automatic machines capture the largest installed base among machine types due to labor-cost pressures in high-volume distribution centers, while biodegradable film variants represent the fastest-growing segment as brand owners face Scope 3 emissions targets and retailer sustainability scorecards. Rotary arm systems occupy premium price tiers where floor space constraints prevent turntable installations.
OSHA guidelines in the United States govern machine guarding and operator safety around rotating stretch wrappers, while the EU Machinery Directive mandates CE marking and risk assessments for automated wrapping systems sold across member states. The EU Packaging and Packaging Waste Regulation further shapes film specification by setting minimum recycled content thresholds that stretch film producers must meet, pushing end users toward machines compatible with thinner or reformulated materials. Stakeholders should monitor how film chemistry evolves under these frameworks, since machine pre-stretch ratios and tension controls must adapt to handle post-consumer resins without tearing or load failure.
Market Dynamics
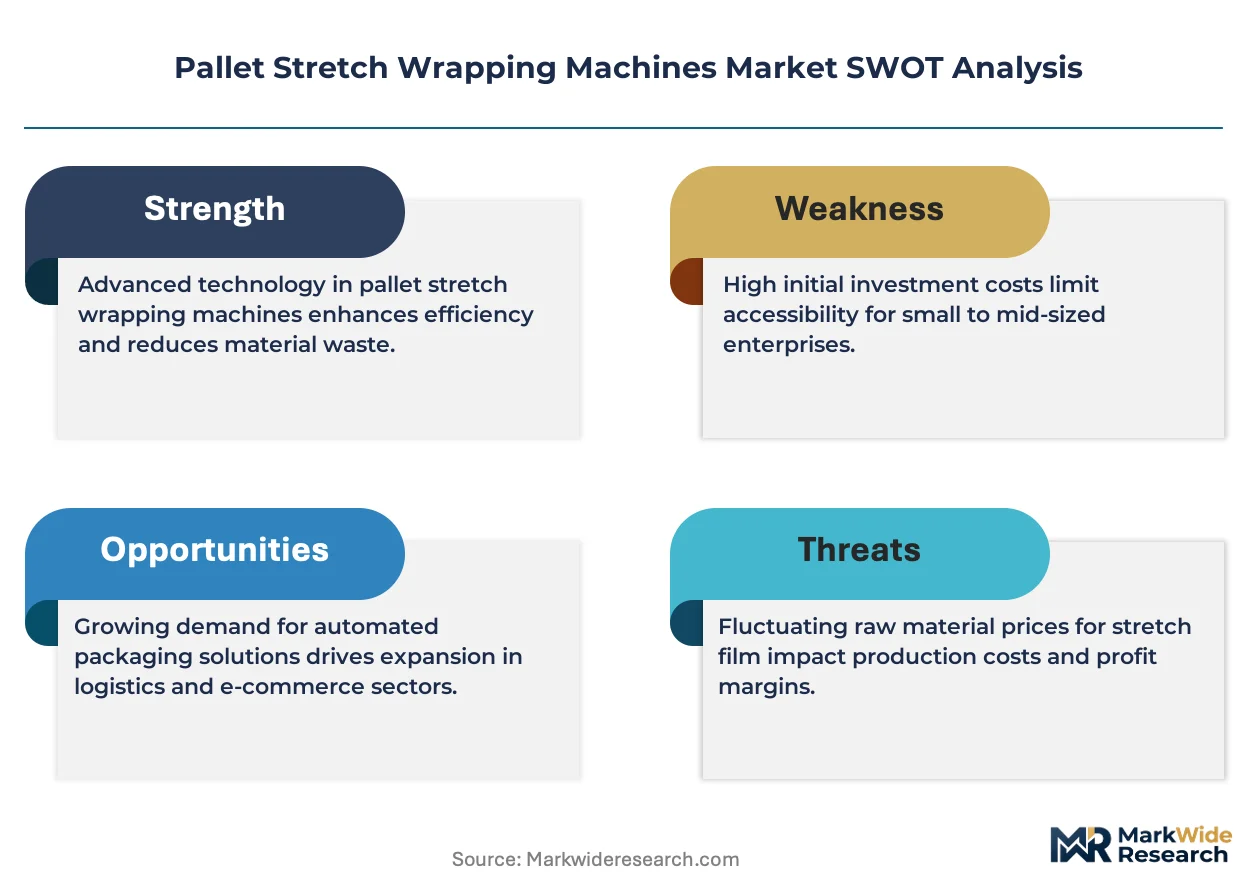
Pre-stretch film carriage technology is compressing per-load material consumption while EU recycled-content mandates force machine recalibration for thinner, post-consumer resin films. This dual pressure—operational efficiency meets regulatory compliance—determines capital allocation across distribution networks.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Minimum recycled-content thresholds for stretch films push end users toward machines with adjustable pre-stretch ratios and tension controls. Food exporters in Germany and the Netherlands are retrofitting lines to handle reformulated materials.
- E-commerce fulfillment density:Automated palletizing lines in China and Southeast Asia are integrating semi-automatic rotary arm wrappers to match order velocity. Domestic manufacturers are scaling capacity to serve these networks.
- Biodegradable film chemistry:Brand owners facing Scope 3 emissions targets and retailer sustainability scorecards are specifying compostable linear low-density polyethylene variants. Machine builders are engineering carriages compatible with these lower-tensile materials.
Market Restraints
- Linear low-density polyethylene price volatility:Petrochemical feedstock fluctuations compress margin predictability for film-dependent operations. High-volume distribution centers face working capital strain from inventory cost swings.
- Rotary arm system floor space requirements:Orbital arm configurations demand ceiling clearance and structural load capacity that aging warehouse stock cannot accommodate. Turntable alternatives dominate retrofits in space-constrained facilities.
- CE marking compliance complexity:The EU Machinery Directive mandates risk assessments and conformity procedures that extend sales cycles for non-European equipment vendors. Documentation burdens favor established regional suppliers.
Strategic Opportunities
- India warehouse automation:The PLI scheme for manufacturing and logistics infrastructure is incentivizing automated material handling investments. Pallet stretch wrapping represents an attach point for system integrators.
- Weighing-wrapping integration:Converging load dimensioning, weight capture, and film application into single-pass operations reduces labor touchpoints. Food and beverage exporters are specifying these hybrid systems.
- Aftermarket film and parts revenue:North American installed bases generate recurring consumables demand. Service contracts covering carriage maintenance and film supply lock in multi-year customer relationships.
Industry Challenges
- Pre-stretch ratio recalibration for post-consumer resins:Film chemistry variability demands operator expertise in tension programming. Training gaps slow adoption of recycled-content materials.
- OSHA machine guarding compliance:Rotating turntable and arm systems require perimeter fencing and emergency stop integration. Installation timelines extend when retrofitting legacy warehouse layouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Stretch Wrapping Machines Market |
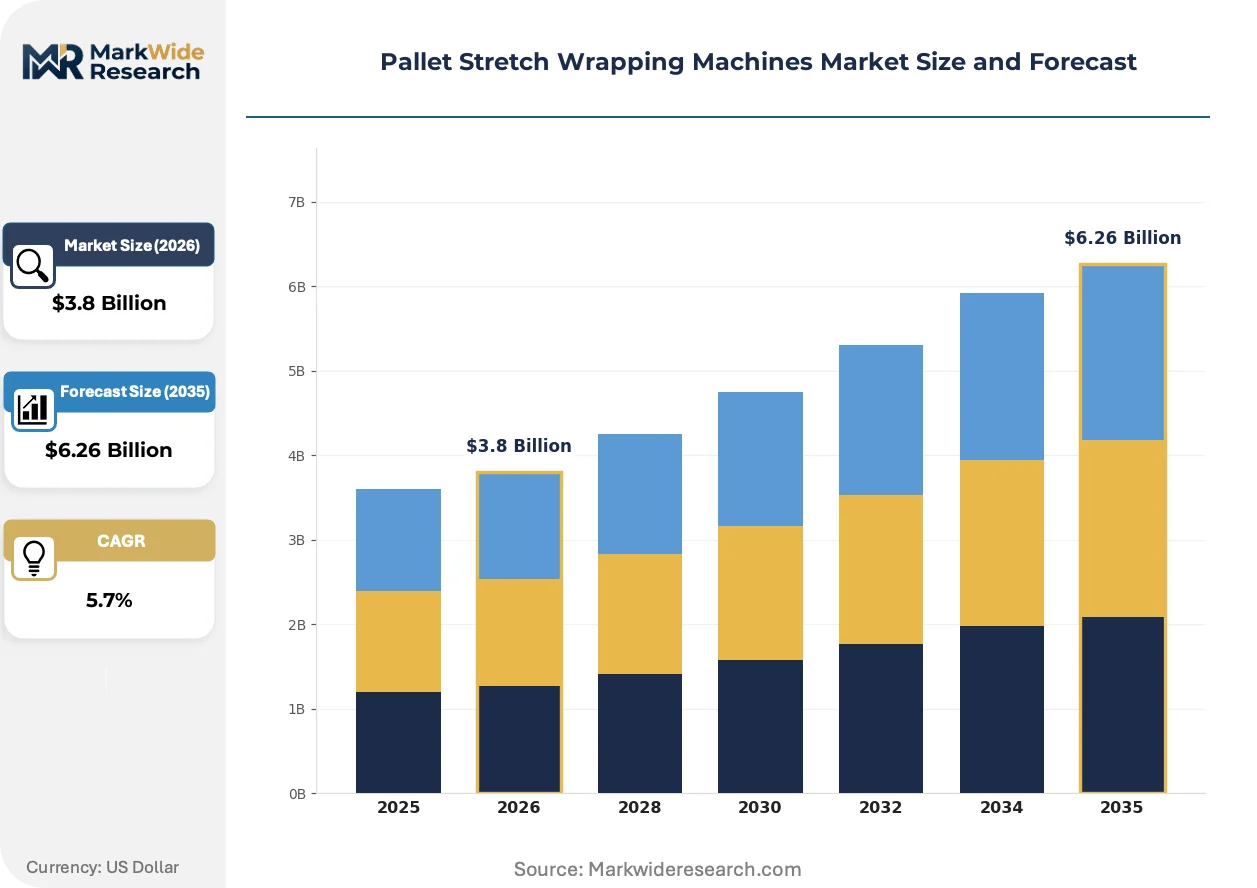
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Automatic, Semi-Automatic, Manual, Rotary Arm Film Type: Polyethylene, PVC, Biodegradable, Cast End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Packaging Style: Horizontal, Vertical, Bundled, Individual |
| Companies Covered | Lantech, Robopac, Signode Industrial Group, Fromm Packaging Systems, Wulftec International, Arpac LLC, Atlanta Stretch, Orion Packaging Systems, Muller LCS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Stretch Wrapping Machines Market Strategic Shifts
Digital twin architectures are virtualizing machine performance optimization, while regulatory chemistry mandates and buyer consolidation reshape specification priorities across distribution networks.
Remote monitoring platforms are virtualizing predictive maintenance for stretch wrapping equipment. Cloud-connected sensors track carriage wear, film tension variance, and cycle counts in real time. Third-party logistics operators are deploying these systems across multi-site fleets to compress unplanned downtime and consolidate service scheduling.
REACH restrictions on persistent organic pollutants are tightening additive specifications for stretch film formulations. Chemical exporters must verify compliance documentation through their supply chains. Machine builders in Germany are certifying equipment compatibility with reformulated films to maintain access to automotive and pharmaceutical distribution contracts.
Consolidated buying by national grocery and home improvement retailers is compressing vendor diversity. Specification authority has shifted to corporate procurement functions from individual warehouse managers. North American big-box distribution centers now mandate standardized wrapping protocols across their networks, favoring suppliers with national service coverage and consumables logistics.
Pallet Stretch Wrapping Machines Market Segmentation
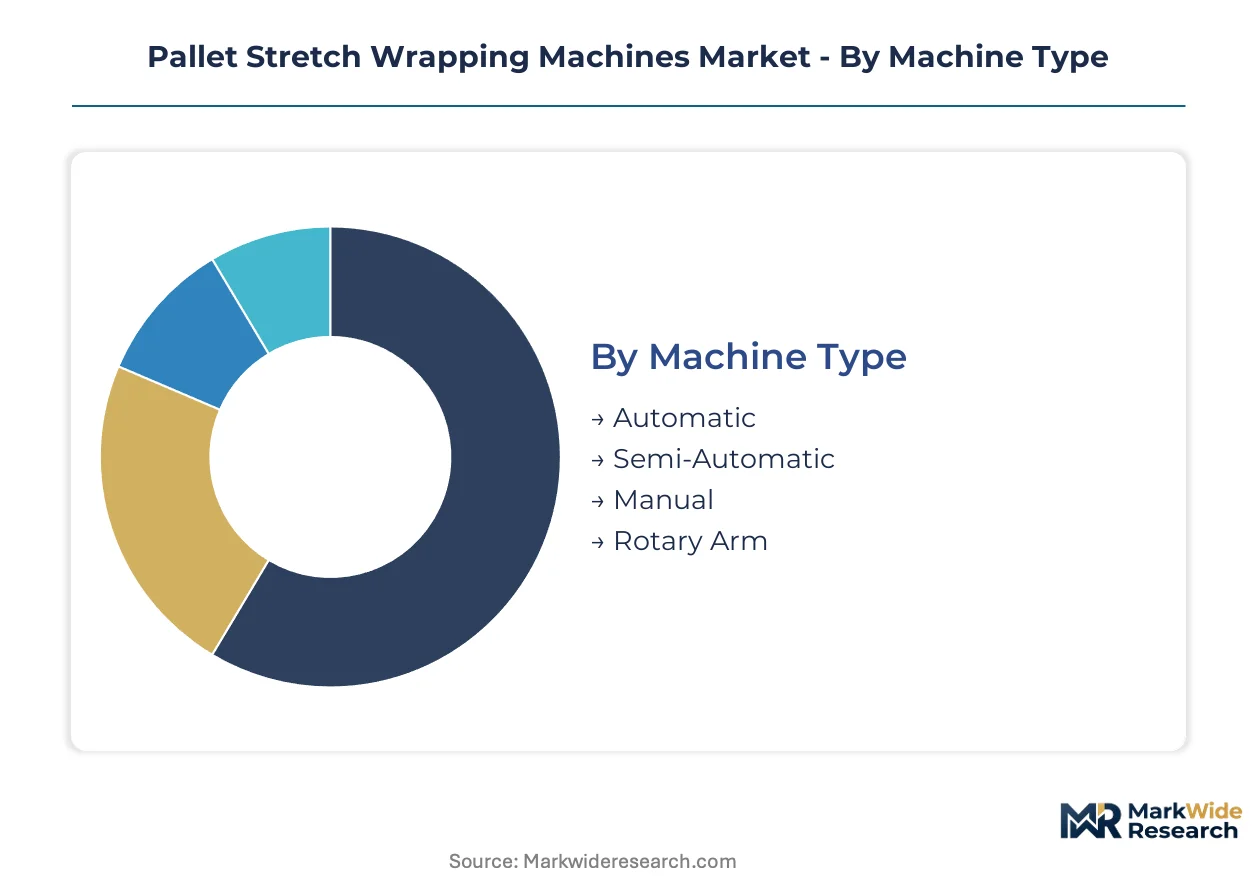
Segmentation in pallet stretch wrapping machines reveals how capital cycles, film chemistry, and end-use compliance requirements fragment procurement decisions across distribution networks. Equipment buyers prioritize cycle time, film compatibility, and regulatory alignment differently based on operational scale and load characteristics.
Machine Type:
Automatic machines turn over fastest in high-volume distribution centers where labor costs dominate ROI calculations, while manual systems persist longest in small-batch operations with irregular throughput.
- Automatic:Rotary turntable and conveyor-fed systems integrate with warehouse management software for unattended operation. German automotive and chemical exporters specify these for throughput rates exceeding 100 pallets per hour, driven by CE marking requirements under the EU Machinery Directive and pressure to reduce per-load labor touchpoints.
- Semi-Automatic:Operator-attended machines bridge the gap between manual and fully automated lines. E-commerce fulfillment networks in China deploy these for order velocity matching, with domestic manufacturers scaling rotary arm capacity to serve fragmented demand without full capital commitment.
- Manual:Hand-held dispensers and mobile wrapping carts serve low-volume operations. Regional distributors in India leverage these for PLI scheme warehouse retrofits where automation budgets remain constrained.
- Rotary Arm:Orbital arm configurations wrap stationary loads from above. Food exporters in the Netherlands specify these where floor space constraints prevent turntable installations, despite premium pricing and structural load requirements.
Automatic machines anchor the volume base while rotary arm systems gain share at the steepest rate among premium configurations.
Film Type:
Cost tiers separate commodity thermoplastics from engineered formulations, with sustainability premiums reshaping specification authority in corporate procurement functions.
- Polyethylene:Linear low-density polyethylene dominates installed film consumption. REACH restrictions on persistent organic pollutants are tightening additive specifications, forcing German machine builders to certify carriage compatibility with reformulated materials for automotive distribution contracts.
- Biodegradable:Compostable linear low-density polyethylene variants address Scope 3 emissions targets. Brand owners facing retailer sustainability scorecards specify these lower-tensile materials, requiring recalibrated pre-stretch ratios and tension controls.
- PVC:Polyvinyl chloride films retain niche applications for heavy-load chemical containment. Chemical exporters verify compliance documentation through supply chains under tightening additive regulations.
- Cast:Cast extrusion films offer clarity and cling for retail-ready pallet presentation. North American big-box distribution centers mandate standardized wrapping protocols favoring these materials for barcode scanning reliability.
Polyethylene films anchor the volume base while biodegradable formulations climb the fastest as regulatory chemistry mandates harden.
End User:
Application-specific compliance burdens and throughput requirements create divergent equipment specification patterns across verticals.
- Food & Beverage:Automated palletizing lines integrate weighing-wrapping hybrid systems to cut film waste and labor costs. EU Packaging and Packaging Waste Regulation recycled-content thresholds push German and Dutch exporters toward machines with adjustable pre-stretch ratios.
- Pharmaceuticals:Cold chain validation and load integrity documentation drive specification. CE marking and risk assessment requirements under the EU Machinery Directive extend sales cycles, favoring established regional suppliers with compliance documentation capabilities.
- Cosmetics:Retail-ready presentation requirements prioritize film clarity and consistent wrap tension. Corporate procurement consolidation compresses vendor diversity toward suppliers with national service coverage.
- Chemicals:Heavy-load containment and hazardous material handling dictate steel strapping and stretch hybrid configurations. OSHA machine guarding guidelines govern rotating system installations in US facilities, extending retrofit timelines.
Food and beverage anchors the volume base while pharmaceuticals expands most quickly on cold chain infrastructure investment.
Packaging Style:
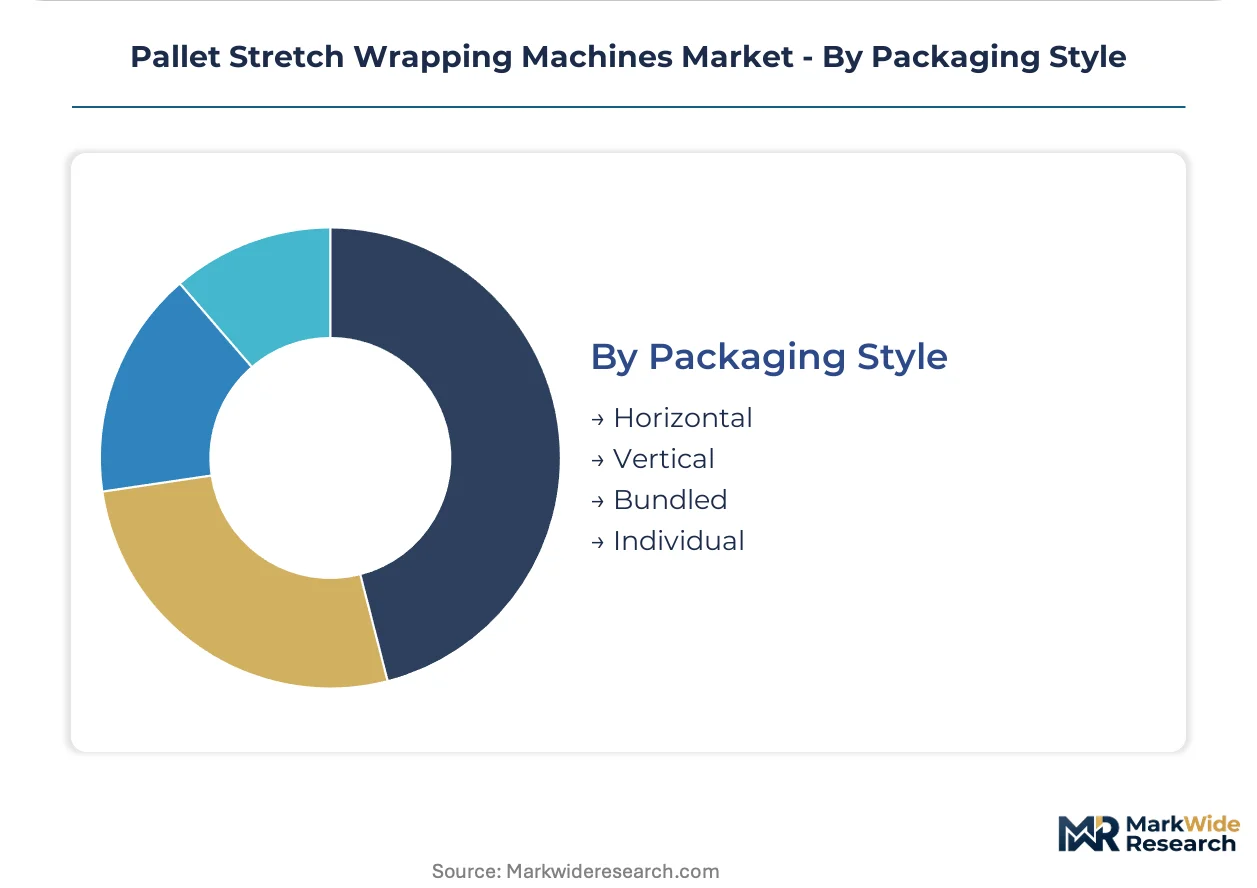
Volume concentration and margin structure vary by orientation and bundling approach, with horizontal systems dominating throughput-intensive applications.
- Horizontal:Side-sealing configurations wrap palletized loads along the long axis. High-throughput distribution centers in Germany specify these for automotive and chemical export lines where cycle time compression dominates capital allocation.
- Vertical:Top-down wrapping approaches suit irregular load geometries. Rotary arm systems enable vertical packaging where floor space constraints prevent turntable installations.
- Bundled:Multi-pallet consolidation reduces per-unit film consumption. Third-party logistics operators deploy these configurations across multi-site fleets with remote monitoring platforms for predictive maintenance.
- Individual:Single-load wrapping preserves product differentiation. E-commerce fulfillment networks in Southeast Asia specify these for order velocity matching with semi-automatic rotary arm integration.
Horizontal wrapping anchors the volume base while bundled configurations gain share fastest on logistics consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and chemical exporters command the largest installed base of high-throughput rotary turntable systems. Machinery builders cluster around industrial distribution corridors to serve CE marking compliance requirements under the EU Machinery Directive.
Germany
Bavarian automotive distribution centers specify automatic wrapping lines exceeding 100 pallets per hour. The EU Packaging and Packaging Waste Regulation mandates minimum recycled-content thresholds for stretch films. Stuttgart and Munich host machinery certification labs where builders validate carriage compatibility with reformulated materials.
United States
OSHA machine guarding guidelines govern rotating turntable installations across high-volume distribution networks. Third-party logistics operators deploy remote monitoring platforms across multi-site fleets to compress unplanned downtime. Chicago and Dallas-Fort Worth anchor the North American installed base for aftermarket film and parts revenue.
China
Domestic manufacturers scale semi-automatic and rotary arm capacity to serve e-commerce fulfillment velocity. SAMR and GB standards regulate machinery safety and film specifications. Yangtze River Delta warehouse clusters in Shanghai and Suzhou integrate wrapping lines with automated palletizing systems.
Netherlands
Rotary arm configurations dominate food exporter specifications where floor space constraints prevent turntable installations. REACH restrictions on persistent organic pollutants tighten additive specifications for stretch film formulations. Rotterdam port logistics corridors drive demand for integrated weighing-wrapping hybrid systems.
India
The PLI scheme for manufacturing and logistics infrastructure incentivizes automated material handling investments. BIS standards govern machinery safety certifications for imported equipment. Maharashtra warehouse automation projects in Mumbai-Pune belt represent emerging attach points for system integrators.
Pallet Stretch Wrapping Machines Market Competitive Environment
Integrated solution providers and specialized machinery fabricators split the market along the automation sophistication axis. The vendor base concentrates around three strategic archetypes: North American aftermarket service networks, European integrated weighing-wrapping specialists, and Asian cost-optimized rotary arm suppliers. Competitive moves center on geographic expansion into PLI-incentivized Indian warehouses and technology licensing for biodegradable film carriage compatibility.
Within the European integrated systems tier, Robopac anchors positioning around food exporter demand for weighing-wrapping convergence. Lantech exemplifies the North American aftermarket archetype through consumables and service contract relationships. Signode Industrial Group occupies the heavy-load hybrid segment where steel strapping and stretch combinations serve chemical distribution requirements.
| Leading Market Players |
|---|
| Lantech |
| Robopac |
| Signode Industrial Group |
| Fromm Packaging Systems |
| Wulftec International |
| Arpac LLC |
| Atlanta Stretch |
| Orion Packaging Systems |
| Muller LCS |
| Others |
Value Chain & Pricing Dynamics
Linear low-density polyethylene feedstock concentration in Gulf Coast petrochemical corridors dictates margin allocation between film producers and machinery fabricators. Pre-stretch carriage technology premiums capture value downstream as resin price volatility compresses film supplier margins.
Pricing Analysis
EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across automatic, semi-automatic, and manual machine categories. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking compliance burden, pre-stretch ratio sophistication, and aftermarket service bundling. Cost compression in economy-tier manual systems is intensifying because Chinese domestic manufacturers scale rotary arm capacity. Small-batch regional distributors exhibit highest price sensitivity, while German automotive exporters accept premium positioning for integrated weighing-wrapping systems.
Supply Chain Analysis
Export-control regimes limiting advanced automation technology flows constrain high-throughput system availability outside established manufacturing zones. Machinery production draws from Germany, Italy, and China, with linear low-density polyethylene film supply anchored in Saudi Arabia, South Korea, and the United States. Single-source vulnerability concentrates in precision servo motor components sourced from Japanese suppliers. Distribution runs through authorized dealer networks with captive aftermarket film and parts logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet stretch wrapping machinery demand follows capital expenditure cycles in warehouse automation, with e-commerce fulfillment density driving the current upswing phase.
For Market Incumbents: Entrench aftermarket revenue streams through multi-year film supply contracts and remote monitoring platform subscriptions. Defend against Chinese rotary arm cost competition by certifying carriage compatibility with EU recycled-content films under Machinery Directive requirements. Prioritize backward integration into biodegradable film formulation partnerships to lock in specification authority with sustainability-focused brand owners. For New Entrants and Emerging Players: Mid-market semi-automatic rotary arm systems for Indian PLI scheme warehouse projects represent the most penetrable entry point. Domestic e-commerce fulfillment networks in Southeast Asia offer secondary white-space for velocity-matching equipment without full automation capital commitment. Lead with pay-per-wrap financing models to bypass incumbent service contract relationships. For Investors and Strategic Acquirers: Capital is best deployed toward integrated weighing-wrapping specialists with established food exporter relationships and CE marking documentation capabilities. Long-term viability hinges on regulatory chemistry adaptation rather than pure throughput specification. Watch for biodegradable film chemistry standardization as the inflection signal for carriage technology consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Carriage Certification | REACH additive restrictions force equipment recalibration for compostable linear low-density polyethylene variants. |
| Remote Monitoring Platform Deployment | Cloud-connected predictive maintenance compresses unplanned downtime for third-party logistics multi-site fleets. |
| Weighing-Wrapping System Integration | Single-pass load dimensioning and film application reduces labor touchpoints for Dutch food exporters. |
| Aftermarket Service Contract Expansion | Multi-year film and parts agreements lock in recurring revenue from North American installed bases. |
| Indian PLI Scheme Market Entry | Maharashtra warehouse automation projects offer system integrator attach points for pallet wrapping lines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with warehouse automation directors, OEM procurement teams, aftermarket service heads, and film formulation chemists. Secondary validation drew from SEC machinery manufacturer filings, EU Machinery Directive conformity databases, customs trade data for linear low-density polyethylene flows, and OSHA incident reporting systems. Bottom-up equipment shipment tallies and top-down distribution network spend estimates were triangulated to anchor volume figures.
Calibration against historical capital expenditure cycles in warehouse automation and e-commerce fulfillment buildouts shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include machine type sophistication, film chemistry grade, end-use vertical compliance burden, and regional regulatory cluster. CAGRs were derived from elasticity analysis of equipment replacement cycles and film consumption intensity per pallet. Industry-specific forecast inputs encompass EU recycled-content mandate phase-in schedules and biodegradable film tensile property evolution.
Practitioners should monitor REACH additive restriction enforcement and biodegradable film chemistry standardization for early signals of carriage technology obsolescence risk. Forecasts reflect assumptions about linear low-density polyethylene feedstock price band stability and warehouse labor cost trajectories. Material shifts in EU Packaging and Packaging Waste Regulation recycled-content thresholds or OSHA machine guarding interpretation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Folder Gluer Machines Market