
 Nano Robots Market | 2026-2036
Nano Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Robots Market Intelligence
Aftermarket service revenue for nano-robotic instrumentation is fragmenting across third-party calibration providers and original equipment manufacturers. Thermo Fisher Scientific leverages its global service network to capture recurring maintenance contracts for electron microscopy systems. Bruker Corporation anchors its position through captive supply of specialized probes and consumables. Oxford Instruments competes by extending warranty-to-service bundles that lock in multi-year customer relationships.
Nano robots are engineered devices operating at the nanometer scale, typically fabricated through electron-beam lithography or self-assembly techniques, designed to manipulate matter or deliver payloads with molecular precision for industrial, medical, or research objectives. Biological nano robots dominate current medical treatment applications due to proven biocompatibility pathways, while mechanical variants lead industrial automation where positional accuracy exceeds biological tolerance thresholds. Hybrid systems integrating magnetic manipulation with chemical reaction interfaces represent the fastest-expanding technology segment as researchers combine locomotion control with targeted payload release.
The FDA oversees pre-market approval pathways for nano-robotic therapeutic devices in the United States, while the EMA governs clinical trial frameworks across European member states, and ISO 10993 biocompatibility standards shape material selection for implantable systems. Regulatory convergence between these bodies on characterization methodologies is reducing redundant testing burdens for multi-jurisdiction developers. Stakeholders must monitor how emerging guidance on autonomous navigation in biological environments reshapes product liability frameworks and reimbursement eligibility.
Market Dynamics
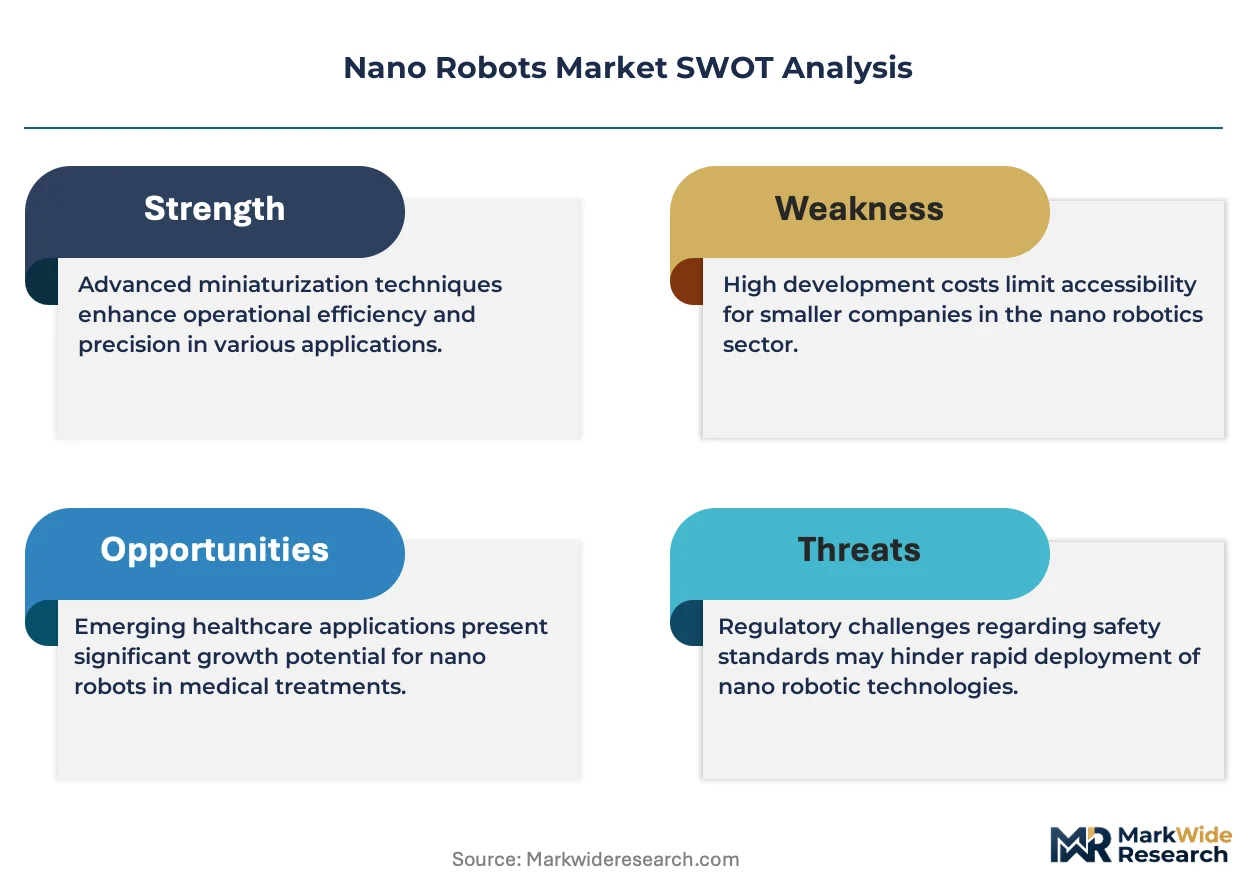
The convergence of magnetic manipulation systems with chemical reaction interfaces is compressing development timelines for targeted therapeutic platforms, forcing traditional pharmaceutical pipelines to integrate nanoscale engineering capabilities or risk obsolescence.
Growth Catalysts
- Oncology drug delivery protocols:Healthcare systems in the United States are channeling capital toward precision payload release systems that minimize systemic toxicity during chemotherapy administration.
- EMA accelerated assessment pathways:European developers gain faster market access for implantable nanorobotic devices meeting MDR biocompatibility benchmarks.
- Electron-beam lithography maturation:Fabrication cost curves for mechanical nano robots are flattening as semiconductor foundries repurpose existing equipment.
Market Restraints
- Specialized probe supply concentration:Captive sourcing arrangements for atomic force microscopy tips create single-source vulnerability for characterization laboratories.
- ISO 10993 testing redundancy:Divergent biocompatibility interpretation between FDA and EMA inflates preclinical validation budgets for multi-jurisdiction developers.
- Biological tolerance thresholds:Mechanical nano robots face hard limits in physiological environments where immune clearance rates exceed locomotion endurance.
Strategic Opportunities
- Neurological intervention applications:Blood-brain barrier penetration capabilities position hybrid magnetic-chemical systems for Parkinson's and Alzheimer's therapeutic delivery.
- NIH Small Business Innovation Research grants:Boston and San Francisco research clusters access non-dilutive capital for clinical translation milestones.
- Self-assembly manufacturing methods:Bottom-up fabrication reduces cleanroom dependency and enables distributed production networks outside traditional semiconductor hubs.
Industry Challenges
- Cross-disciplinary talent scarcity:Positional accuracy engineering demands simultaneous expertise in molecular biology and MEMS design, shrinking the qualified labor pool.
- Autonomous navigation liability frameworks:Product insurance markets lack actuarial models for self-directed therapeutic devices operating in biological environments.
- Legacy electron microscopy integration:Retrofitting existing imaging infrastructure for real-time nano robot tracking requires proprietary software adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Robots Market |
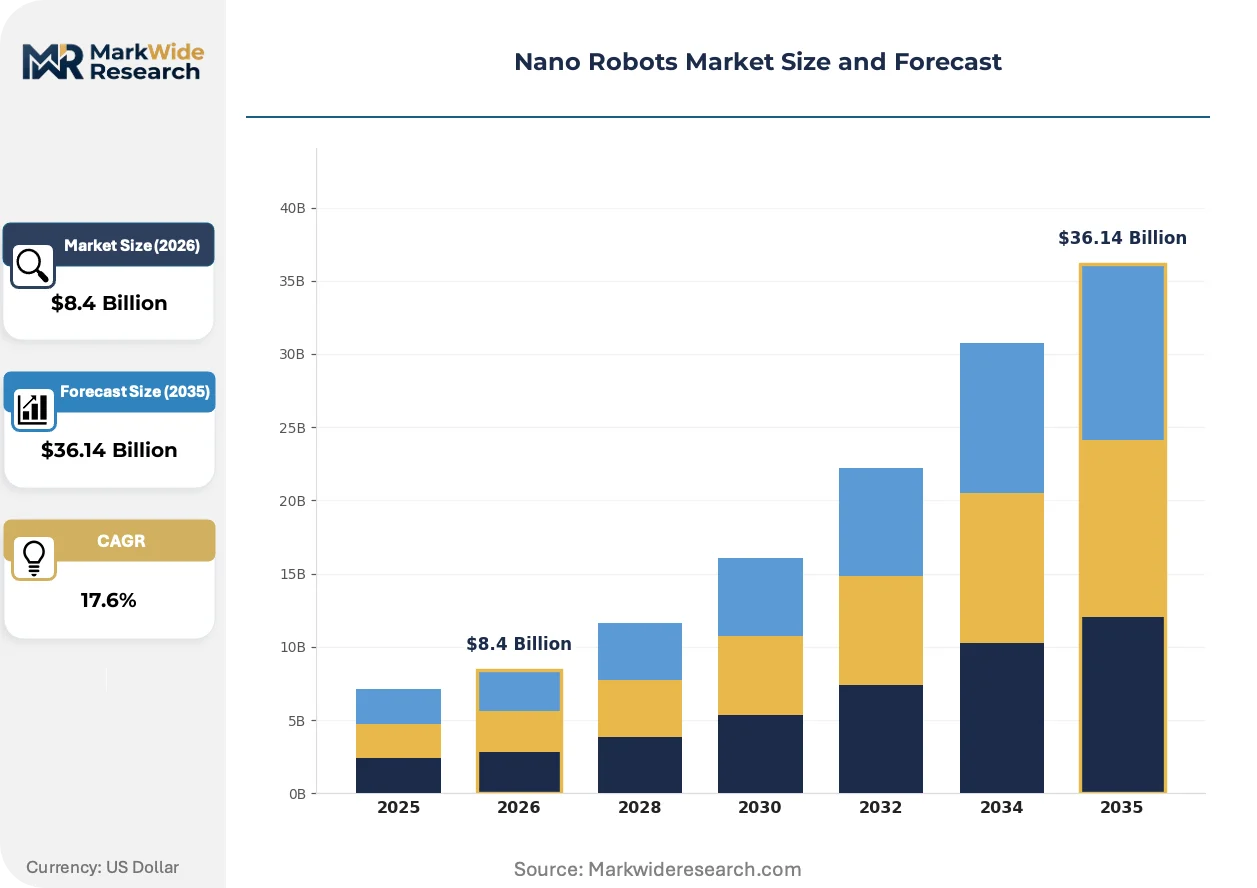
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Biological, Mechanical, Hybrid, Autonomous Application: Medical Treatment, Drug Delivery, Environmental Monitoring, Industrial Automation Technology: Magnetic Manipulation, Acoustic Waves, Optical Tweezers, Chemical Reactions End User: Healthcare, Aerospace, Electronics, Research Institutions |
| Companies Covered | Thermo Fisher Scientific, Oxford Instruments, Bruker Corporation, JEOL Ltd, Ginkgo Bioworks, EV Group, Agilent Technologies, Park Systems, Imina Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Robots Market Strategic Shifts & Innovations
Computational modeling is displacing physical prototyping cycles across the development pipeline, compressing iteration timelines while expanding the searchable design space for locomotion and payload mechanisms.
DNA origami frameworks are virtualizing structural design for biological nano robots, enabling programmable shape-morphing for vascular navigation. Academic medical centers in Germany and Switzerland are piloting these structures for localized thrombolysis. The approach is collapsing the traditional separation between fabrication and functional testing.
REACH substance restrictions are forcing material substitutions in European-manufactured nano robot shells, with developers abandoning certain heavy-metal coatings for polymer-ceramic composites. The transition is most acute in implantable oncology devices where long-term biostability requirements conflict with environmental compliance mandates.
Hospital procurement committees are consolidating vendor relationships around integrated service bundles that combine hardware, calibration, and consumable supply. Third-party maintenance providers in the United States are losing share to original equipment manufacturer captive service networks. The shift is pronounced in academic research institutions facing compressed capital equipment renewal cycles.
Nano Robots Market Segmentation
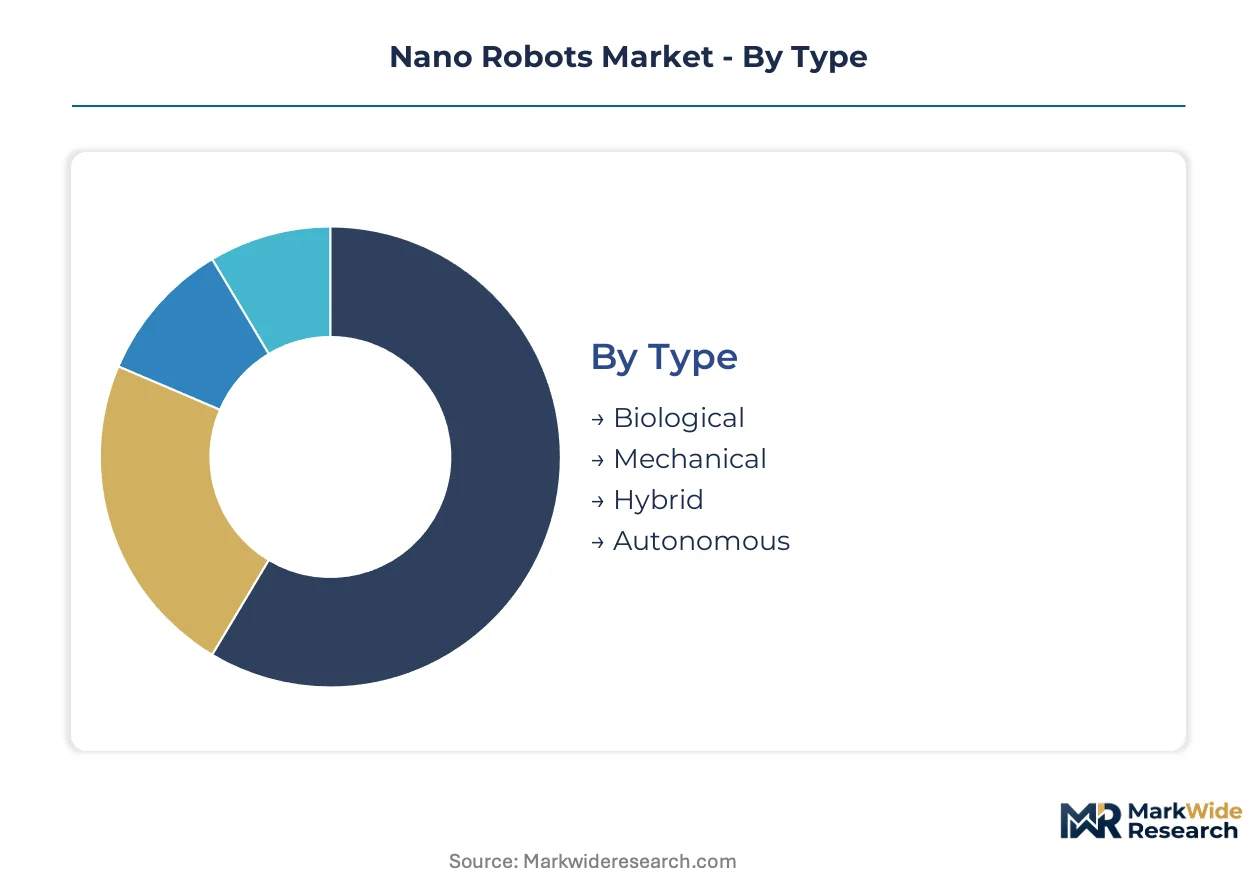
Segmentation in nano robotics determines procurement patterns, service bundling strategies, and regulatory pathway selection. Different configurations demand distinct calibration protocols and consumable replenishment cycles that reshape vendor economics.
Type:
After-sales service intensity varies sharply across type categories, with mechanical variants requiring probe replacement programs and biological systems demanding sterile handling certifications.
- Biological:Engineered from DNA, proteins, or cellular components with inherent biocompatibility. Demand concentrates in oncology drug delivery within United States healthcare systems, where FDA pre-market approval timelines favor proven biological pathways over novel mechanical architectures.
- Mechanical:Fabricated through electron-beam lithography with rigid structural elements. Research institutions in Germany and Switzerland anchor procurement volumes for atomic force microscopy integration, though immune clearance limitations restrict physiological deployment.
- Hybrid:Combines magnetic locomotion with chemical payload interfaces, attracting NIH-funded Boston clusters for neurological applications.
- Autonomous:Self-directed navigation systems with onboard sensing; liability insurance gaps currently constrain commercial rollout.
By volume, Biological leads. By growth pace, Hybrid is ahead.
Application:
Application segmentation tracks directly to end-user capital allocation cycles and reimbursement eligibility frameworks.
- Medical Treatment:Surgical intervention and tissue repair platforms. United States academic medical centers drive procurement, with EMA accelerated assessment pathways enabling parallel European market entry for implantable systems.
- Drug Delivery:Precision payload release for chemotherapy and biologics. Oncology protocols in Boston and San Francisco research clusters attract the largest share of NIH translational funding.
- Environmental Monitoring:Pollutant detection and remediation in industrial settings; REACH compliance mandates in Europe reshape material specifications.
- Industrial Automation:Positional accuracy exceeding biological tolerance thresholds; semiconductor foundries in Japan and South Korea dominate deployment.
Drug Delivery commands premium pricing. Medical Treatment shows the steepest expansion trajectory.
Technology:
Technology choice determines fabrication infrastructure requirements and third-party service dependency.
- Magnetic Manipulation:External field control for locomotion and positioning. Hybrid system developers in Germany combine this with chemical interfaces for blood-brain barrier penetration in Parkinson's therapeutics.
- Acoustic Waves:Ultrasound-driven propulsion for deep tissue navigation; research institutions in Switzerland pilot thrombolysis applications.
- Optical Tweezers:Laser-based trapping for precise manipulation; electronics manufacturing in Japan leverages this for sub-micron assembly.
- Chemical Reactions:Catalytic or enzymatic propulsion; environmental monitoring applications in Europe face ECHA substance restriction compliance costs.
Magnetic Manipulation holds the largest installed base. Chemical Reactions is climbing the fastest.
End User:
End user segmentation reveals divergent procurement authority structures and maintenance contract preferences.
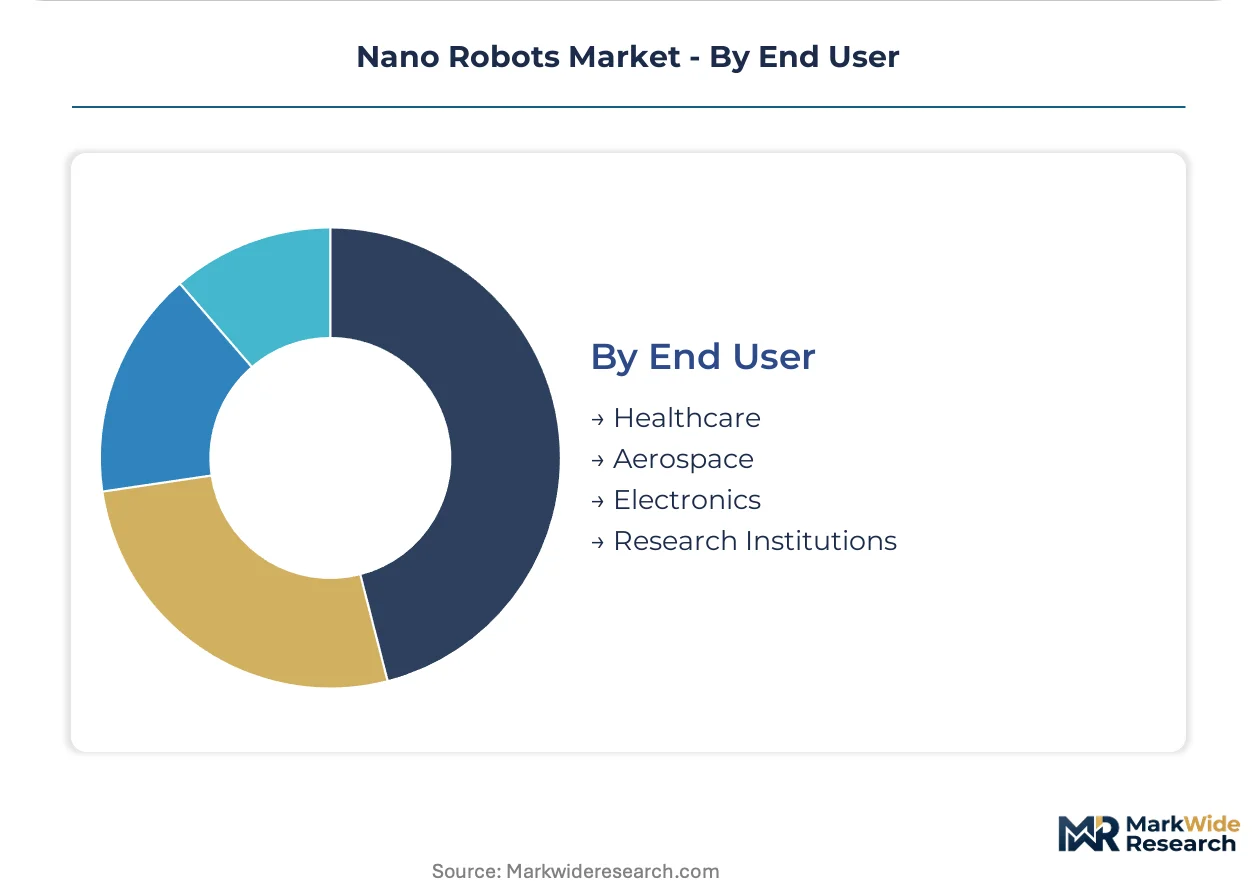
- Healthcare:Hospital systems and academic medical centers with consolidated vendor relationships. United States procurement committees increasingly favor OEM-integrated service bundles over third-party calibration providers.
- Aerospace:Satellite component inspection and microgravity manufacturing; specialized probe supply concentration creates sourcing vulnerability.
- Electronics:Semiconductor metrology and defect analysis; Japanese and South Korean foundries repurpose existing electron-beam lithography infrastructure.
- Research Institutions:Universities and national laboratories with compressed capital renewal cycles; Boston and San Francisco clusters access NIH SBIR non-dilutive funding.
Healthcare generates the highest service revenue per unit. Research Institutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States channels capital toward biological nano robots for oncology drug delivery, while Germany and Japan prioritize mechanical variants for semiconductor metrology and industrial automation. Switzerland and South Korea concentrate on hybrid magnetic-chemical systems for neurological and electronics applications respectively.
United States
NIH-funded research clusters in Boston and San Francisco drive commercialization pipelines for drug delivery platforms. FDA pre-market approval pathways favor biological nano robots with established biocompatibility profiles. Academic medical centers consolidate procurement around OEM-integrated service bundles, squeezing third-party calibration providers.
Germany
Academic medical centers in Heidelberg and Munich pilot DNA origami frameworks for localized thrombolysis. REACH substance restrictions force material substitutions in implantable oncology devices, accelerating polymer-ceramic composite adoption. The country's national pharmaceutical regulator aligns with EMA accelerated assessment pathways for nanorobotic therapeutics.
Japan
Semiconductor foundries repurpose electron-beam lithography infrastructure for mechanical nano robot fabrication. METI standards guide industrial automation deployment where positional accuracy exceeds biological tolerance thresholds. Tokyo and Osaka research institutions anchor procurement volumes for atomic force microscopy integration.
Switzerland
Swissmedic governs clinical trial frameworks for blood-brain barrier penetration applications in Parkinson's therapeutics. Academic medical centers in Zurich and Geneva combine magnetic manipulation with chemical interfaces for hybrid system development. The country captures premium pricing for neurological intervention platforms.
South Korea
Electronics manufacturers leverage optical tweezer systems for sub-micron assembly in semiconductor metrology. The country's national pharmaceutical regulator, MFDS, shapes biocompatibility standards for emerging medical applications. Seoul and Busan foundries dominate industrial automation deployment with repurposed fabrication equipment.
Nano Robots Market Key Industry Players
Capability concentration sits with specialized fabrication and instrumentation providers; scale advantage sits with diversified life sciences conglomerates. The market structure shows tiered competition between precision equipment manufacturers, biological engineering platforms, and semiconductor metrology specialists. Three archetypes dominate: electron microscopy system integrators, DNA origami biological fabricators, and atomic force microscopy probe suppliers. Competitive moves center on captive supply arrangements for specialized consumables and warranty-to-service bundling for multi-year customer lock-in.
Within the electron microscopy tier, Thermo Fisher Scientific and JEOL Ltd exemplify scale-driven instrumentation providers. Oxford Instruments and Bruker Corporation occupy positions in the specialized probe and characterization equipment segment. Among biological engineering platforms, Ginkgo Bioworks represents the DNA origami fabrication archetype. These anchors illustrate how vendor economics fragment across aftermarket service revenue, consumable replenishment cycles, and fabrication infrastructure requirements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Oxford Instruments |
| Bruker Corporation |
| JEOL Ltd |
| Ginkgo Bioworks |
| EV Group |
| Agilent Technologies |
| Park Systems |
| Imina Technologies |
| Others |
Cost & Logistics Intelligence
Single-source dependency for specialized atomic force microscopy probes determines both pricing tier spreads and supply chain shape, with captive sourcing arrangements from Bruker Corporation and Oxford Instruments compressing margins for third-party characterization laboratories while locking academic institutions into multi-year service bundles.
Pricing Analysis
Long-term offtake contracts dominate procurement for electron-beam lithography systems, with semiconductor foundries in Japan and South Korea securing volume commitments that flatten per-unit pricing curves. Price differentiation rests on after-sales service bundling intensity and ISO 10993 certification tier for biological variants. Cost compression in mechanical nano robots intensifies as fabrication infrastructure repurposing spreads across Asian foundries. Hospital procurement committees in the United States exhibit highest price sensitivity, while neurological intervention platforms in Switzerland command premium tolerance.
Supply Chain Analysis
Extended payment terms from research institutions are reshaping supplier financing structures, with OEMs absorbing working capital strain to secure multi-year maintenance lock-in. Raw material sourcing draws from Germany for precision optics, Japan for electron-beam components, and the United States for biological substrate materials. Single-source vulnerability concentrates in specialized probe manufacturing. Distribution runs through consolidated vendor relationships at academic medical centers, squeezing independent calibration providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA pre-market approval timelines and EMA accelerated assessment pathways create sticky incumbent positions that resist displacement.
For Market Incumbents: Build switching-cost moats through warranty-to-service bundling that captures multi-year calibration contracts at NIH-funded Boston and San Francisco research clusters. Deepen captive supply arrangements for atomic force microscopy probes to neutralize third-party maintenance encroachment. Invest in ISO 10993 biocompatibility certification infrastructure ahead of converging FDA-EMA guidance to preempt emerging DNA origami competitors. For New Entrants and Emerging Players: Pursue white-space opportunity in autonomous navigation systems for biological environments, where liability insurance gaps have stalled commercial rollout by established players. Target neurological intervention applications in Switzerland and Germany, where blood-brain barrier penetration capabilities attract premium pricing. Lead with self-assembly manufacturing methods that reduce cleanroom dependency and enable distributed production outside traditional semiconductor hubs. For Investors and Strategic Acquirers: FDA guidance finalization on autonomous therapeutic devices reshapes the acquisition landscape by clarifying product liability frameworks and reimbursement eligibility. Prioritize platform-stage biological engineering specialists with established NIH SBIR funding relationships over mechanical fabrication plays facing immune clearance limitations. Watch for EMA regulatory convergence signals as the inflection indicator for multi-jurisdiction scalability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| NIH SBIR Grant Capture | Non-dilutive capital from Boston and San Francisco clusters accelerates clinical translation milestones without equity dilution. |
| EMA Accelerated Assessment Pathway | Faster market access for implantable devices meeting MDR biocompatibility benchmarks compresses European commercialization timelines. |
| Captive Probe Supply Arrangement | Oxford Instruments and Bruker Corporation lock characterization laboratories into proprietary consumable replenishment cycles. |
| DNA Origami Platform Licensing | Ginkgo Bioworks enables programmable shape-morphing for vascular navigation without fabrication infrastructure investment. |
| Self-Assembly Manufacturing Scale-Up | Bottom-up fabrication reduces cleanroom dependency and enables distributed production networks outside semiconductor hubs. |
Research Approach
Desk research of FDA 510(k) filings, EMA assessment reports, NIH RePORTER databases, and ISO technical committee documentation preceded structured interviews with biomedical engineering directors, hospital procurement committee chairs, electron microscopy facility managers, and regulatory affairs leads at nanotechnology developers. Secondary validation drew from patent landscape analysis, clinical trial registry entries, and semiconductor foundry capex disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Assumption sets held regulatory approval timelines and NIH funding allocations fixed while varying EMA convergence scenarios and self-assembly manufacturing maturation curves across the analysis window. Segmentation dimensions modeled included nano robot type, application area, propulsion technology, and end-user procurement authority structure. CAGRs derived from installed base growth rates and replacement cycle compression in electron microscopy systems. Forecast inputs incorporated electron-beam lithography cost curve trajectories and REACH substance restriction compliance burdens.
Macroeconomic conditions sit as an overlay; deviation in NIH appropriations levels or semiconductor capital equipment spending would shift the trajectory. Forecasts reflect documented assumptions about regulatory convergence timing and fabrication infrastructure repurposing rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Commercial Robots Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
North America Collaborative Robots Market