
 South America AUV Market | 2026-2036
South America AUV Market Size, Share, and Industry Trends Forecast 2026-2036
South America AUV Market Analytics
Aftermarket service revenue is narrowing toward OEM-captive maintenance and software update contracts as AUV operational hours accumulate in Brazil's deepwater fields. Kongsberg Maritime anchors its regional presence through Kongsberg Maritime do Brasil, sustaining local technician networks for subsea vehicle support. Oceaneering International, Inc. competes via its integrated survey and intervention portfolio, while Fugro N.V. dominates offshore inspection contracts through its permanently stationed Rio de Janeiro operations center.
An autonomous underwater vehicle is a self-propelled, untethered submersible operating at depths exceeding 3,000 meters, powered by lithium-ion or silver-zinc battery packs and guided by inertial navigation systems with Doppler velocity logs for dead-reckoning positioning; its primary purpose is executing pre-programmed seabed missions without surface vessel tethering, reducing day-rate costs for bathymetric survey and subsea asset inspection. Autonomous underwater vehicles within the product-type dimension command the highest margin pools where long-endurance lithium-polymer configurations displace legacy lead-acid systems, while environmental monitoring applications outpace search and rescue in absolute deployment growth as Brazil's IBAMA intensifies pre-drilling baseline studies. Sonar technology leads the technology stack with multibeam echosounder payloads generating the densest point-cloud data for pre-salt geohazard assessment.
Brazil's ANP mandates subsea infrastructure inspection intervals under its safety management regulations, while INMETRO certification requirements for underwater equipment establish product standards that filter non-compliant imports. Argentina's ENARGAS oversees offshore pipeline surveillance protocols in the Austral Basin, creating parallel compliance demand. Stakeholders must monitor how Petrobras fleet standardization decisions and emerging local-content rules reshape vendor qualification pathways across the continent's offshore basins.
Market Dynamics
Platform-to-AUV fleet conversion accelerates across Brazil's deepwater basins as ANP-mandated inspection intervals compress operational windows and force capital redeployment from crewed vessels to autonomous systems.
Growth Catalysts
- ANP Safety Management Regulations:Brazil's offshore regulator mandates periodic subsea infrastructure integrity assessments, converting platform-based inspection schedules into dedicated AUV fleet procurement.
- Pre-salt Geohazard Surveying:Operators in Santos Basin deploy long-endurance lithium-polymer configurations for bathymetric mapping of salt dome formations prior to well placement.
- IBAMA Baseline Studies:Brazil's environmental agency intensifies pre-drilling ecological assessments, expanding AUV deployment for benthic habitat characterization.
Market Restraints
- Silver-zinc Battery Supply Concentration:Deepwater AUV configurations depend on specialty battery chemistry with limited regional sourcing, exposing operators to import lead times and currency fluctuation.
- INMETRO Certification Friction:Brazil's national metrology institute maintains stringent underwater equipment standards that filter non-compliant imports and extend vendor qualification timelines.
- Crewed Vessel Substitution Economics:Hybrid ROV-AUV architectures in shallow Argentine waters retain cost advantages for intermittent inspection cycles, constraining pure AUV penetration.
Strategic Opportunities
- Argentine Austral Basin Expansion:ENARGAS pipeline surveillance protocols create parallel compliance demand as offshore exploration blocks mature toward production.
- Chilean Marine Research Programs:Academic and governmental oceanographic institutions build AUV capabilities for sub-Antarctic ecosystem monitoring, opening non-oil and gas revenue channels.
- Multibeam-Synthetic Aperture Sonar Convergence:Payload integration of complementary acoustic technologies enables simultaneous geohazard detection and pipeline freespan measurement in single deployments.
Industry Challenges
- Subsea Navigation Technician Scarcity:Inertial navigation system calibration and Doppler velocity log maintenance require specialized skill sets with limited training infrastructure in regional port cities.
- Legacy Platform Integration Complexity:AUV docking and data retrieval systems must interface with existing FPSO architectures originally designed for ROV tether management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America AUV Market |
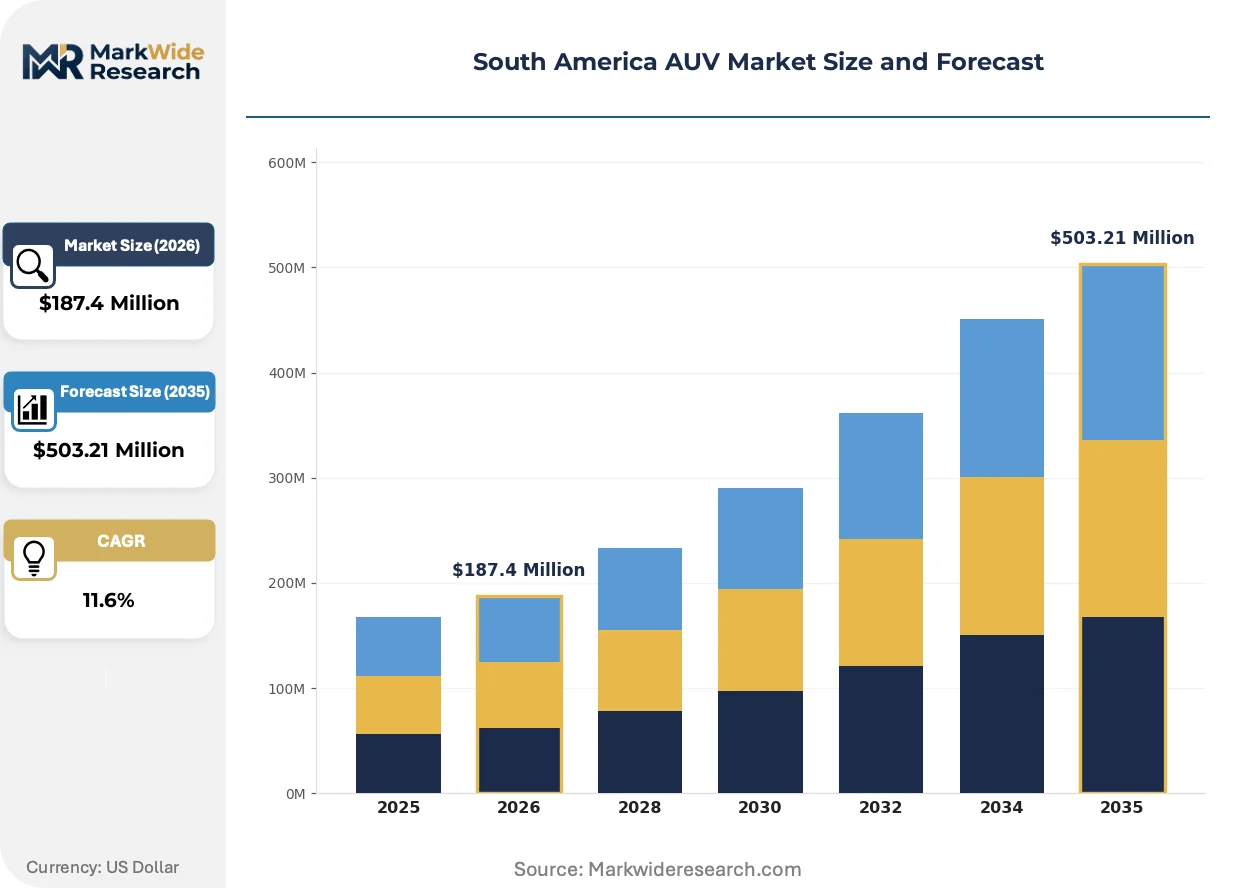
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remotely Operated Vehicles, Autonomous Underwater Vehicles, Hybrid Vehicles, Micro AUVs End User: Oil & Gas Industry, Marine Research Institutions, Military, Environmental Agencies Technology: Sonar, GPS, Inertial Navigation, Real-Time Data Processing Application: Surveying, Environmental Monitoring, Search & Rescue, Infrastructure Inspection |
| Companies Covered | Subsea Tech, Oceaneering International, Inc., General Dynamics Corporation, L3Harris Technologies, Lockheed Martin Corporation, Fugro N.V., Kongsberg Maritime, Teledyne Technologies, Boeing, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America AUV Market Evolving Landscape
Acoustic payload virtualization and regulatory inspection digitization are compressing survey timelines while reshaping how operators contract for subsea asset intelligence.
Multibeam echosounder systems are virtualizing traditional bathymetric survey workflows by generating dense point-cloud data without surface vessel positioning redundancy. Petrobras and international operators in Brazil's pre-salt cluster adopt these configurations for real-time geohazard assessment during drilling program execution. The technology is virtualizing legacy survey economics by eliminating day-rate dependencies on dynamically positioned support vessels.
ANP's digital submission requirements for subsea integrity reports are forcing inspection data standardization across vendor fleets. Operators must now deliver machine-readable defect classifications and change-detection analytics rather than raw sonar files. Brazil's Santos Basin contractors respond by embedding automated feature-extraction algorithms directly into AUV payload processors.
Service unbundling now separates vehicle operation from data interpretation, with specialized analytics firms capturing margin previously retained by integrated survey contractors. Argentine operators increasingly procure AUV hours on day-rate terms while outsourcing seabed interpretation to third-party geoscience boutiques. This pattern concentrates most visibly in Brazil's Rio de Janeiro vendor ecosystem, where permanent operations centers compete for discrete work packages rather than full campaign contracts.
South America AUV Market Segmentation
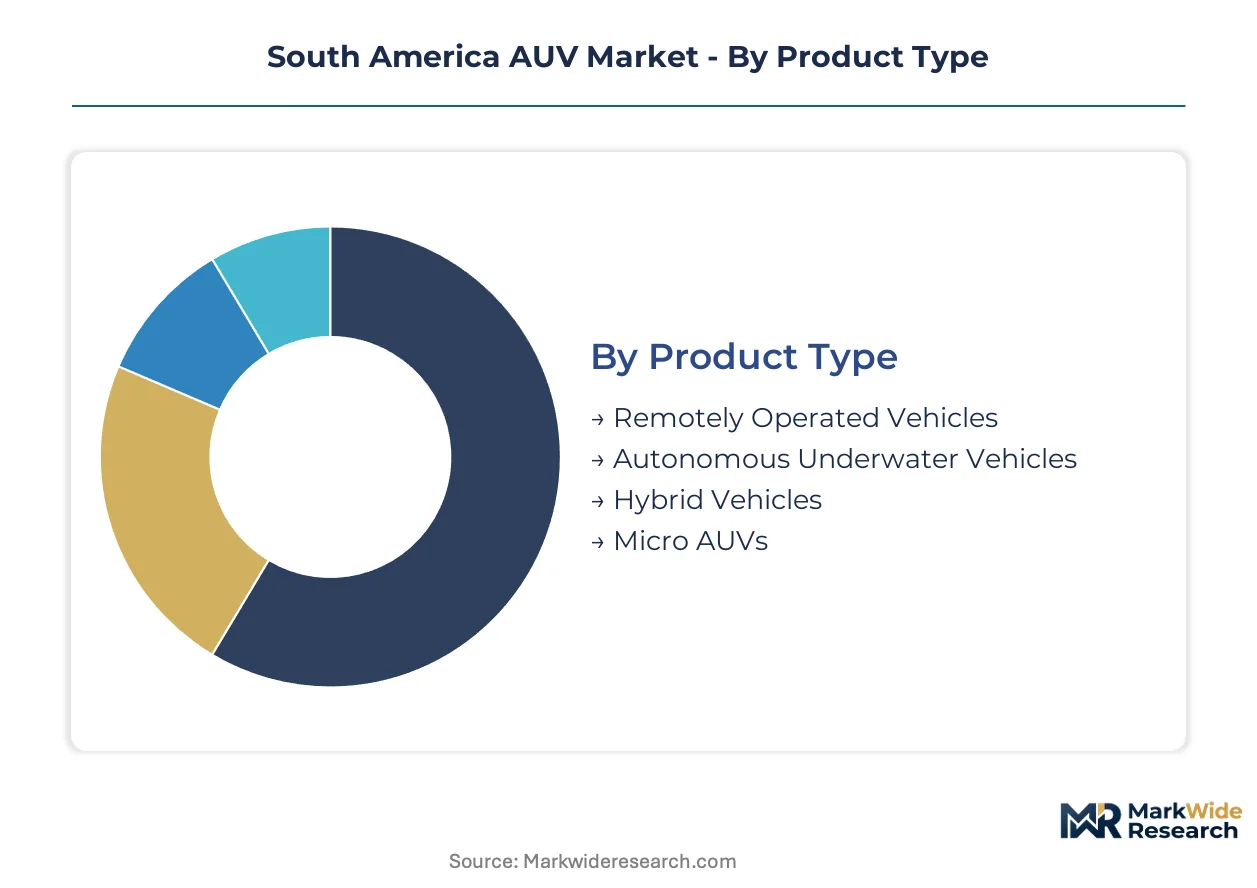
Segmentation in South America's AUV market reveals how vessel configuration, client procurement patterns, and payload sophistication stratify across Brazil's pre-salt basins, Argentine offshore blocks, and Chilean research corridors. Each dimension exposes distinct margin pools and vendor qualification pathways shaped by national regulatory frameworks.
Product Type:
Use-case spectrum spans crewed-tethered dependence through full autonomy, with battery chemistry and endurance specifications determining fit across water depth and mission complexity.
- Autonomous Underwater Vehicles:Self-propelled, untethered platforms operating below 3,000 meters on lithium-ion or silver-zinc battery packs, guided by inertial navigation with Doppler velocity logs. Demand concentrates in Brazil's Santos Basin pre-salt cluster where ANP-mandated inspection intervals compress operational windows and Petrobras fleet standardization favors long-endurance lithium-polymer configurations over legacy lead-acid systems.
- Remotely Operated Vehicles:Tethered platforms maintaining real-time surface control through umbilical connections, dominant in shallow-water Argentine Austral Basin operations where ENARGAS pipeline surveillance protocols tolerate intermittent inspection cycles and hybrid ROV-AUV architectures retain cost advantages for infrequent deployment.
- Hybrid Vehicles:Dual-mode architectures switching between autonomous transit and tethered intervention, gaining traction where legacy FPSO infrastructure requires ROV-compatible docking stations but operators seek AUV economics for transit legs.
- Micro AUVs:Compact, short-endurance platforms under 100 kilograms displacement, deployed by Chilean marine research programs for sub-Antarctic ecosystem monitoring in constrained-budget academic settings.
The dominant share belongs to Autonomous Underwater Vehicles, while Hybrid Vehicles are closing the gap fastest as operators retrofit existing FPSO architectures.
End User:
Procurement concentration tracks hydrocarbon production maturity and regulatory enforcement intensity across national offshore basins.
- Oil & Gas Industry:Petrobras and international operators in Brazil's Santos Basin drive fleet-scale procurement, with ANP safety management regulations mandating periodic subsea infrastructure integrity assessments that convert platform-based inspection schedules into dedicated AUV fleet procurement and accelerate platform-to-AUV conversion.
- Marine Research Institutions:Academic and governmental oceanographic bodies in Chile build capabilities for sub-Antarctic ecosystem monitoring, opening non-oil and gas revenue channels with discrete equipment procurement cycles distinct from hydrocarbon capital deployment.
- Environmental Agencies:Brazil's IBAMA intensifies pre-drilling baseline studies, expanding AUV deployment for benthic habitat characterization and creating compliance-driven demand separate from operator-led procurement.
- Military:Naval mine countermeasure and harbor security programs represent sporadic, specification-intensive procurement with extended vendor qualification timelines distinct from commercial offshore patterns.
Oil & Gas Industry retains the dominant procurement volume, though Environmental Agencies are expanding most quickly as IBAMA enforcement tightens pre-drilling assessment requirements.
Technology:
Payload integration determines data density and survey timeline compression, with acoustic technologies leading hardware margins.
- Sonar:Multibeam echosounder systems generating dense point-cloud data for pre-salt geohazard assessment dominate technology stack revenue, with payload virtualization eliminating day-rate dependencies on dynamically positioned support vessels.
- Inertial Navigation:INS calibration combined with Doppler velocity logs enables dead-reckoning positioning in GPS-denied deepwater environments, though subsea navigation technician scarcity constrains regional maintenance capacity.
- GPS:Surface-restricted positioning for shallow-water operations and mission initialization, less relevant as operating depth increases in Brazil's pre-salt fields.
- Real-Time Data Processing:Onboard automated feature-extraction algorithms responding to ANP digital submission requirements for machine-readable defect classifications, embedding interpretation directly into AUV payload processors.
Sonar commands the dominant technology share, while Real-Time Data Processing is gaining share fastest as regulatory digitization forces inspection data standardization.
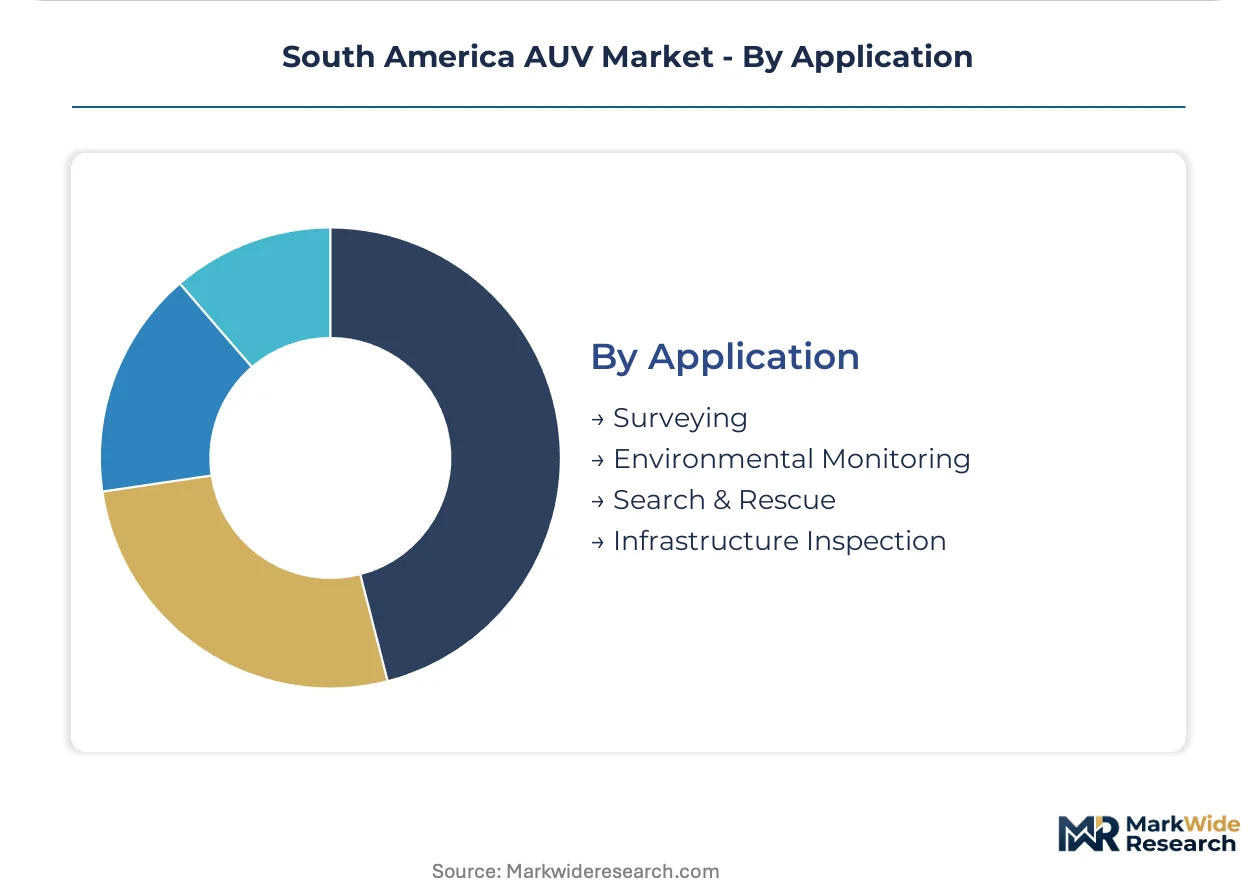
Application:
Mission type determines payload configuration and contract structure, with service unbundling separating vehicle operation from data interpretation.
- Surveying:Bathymetric mapping and geohazard assessment for pre-salt well placement, where multibeam-synthetic aperture sonar convergence enables simultaneous salt dome detection and seabed characterization in single deployments.
- Infrastructure Inspection:Pipeline freespan measurement and platform integrity assessment driven by ANP-mandated intervals, with permanently stationed Rio de Janeiro operations centers competing for discrete work packages rather than full campaign contracts.
- Environmental Monitoring:Pre-drilling baseline studies and benthic habitat characterization, expanding deployment growth as IBAMA intensifies ecological assessment requirements ahead of exploration licensing.
- Search & Rescue:Emergency response and wreck location missions, constrained by intermittent demand patterns and competition from surface-based recovery systems.
Surveying holds the dominant application share, though Infrastructure Inspection is climbing the fastest as ANP inspection intervals compress and service unbundling concentrates vendor competition in Rio de Janeiro.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes AUV capacity for deepwater hydrocarbon inspection while Argentina and Chile deploy the same platforms for shallower pipeline surveillance and academic research respectively, creating a three-speed demand structure across the continent.
Brazil
Petrobras fleet standardization drives procurement concentration in the Santos Basin pre-salt cluster, where lithium-polymer endurance configurations displace legacy systems. ANP safety management regulations mandate periodic subsea infrastructure integrity assessments, compressing operational windows and accelerating platform-to-AUV conversion. Rio de Janeiro anchors vendor operations with permanently stationed service centers competing for discrete inspection contracts.
Argentina
ENARGAS pipeline surveillance protocols in the Austral Basin create compliance-driven demand as offshore exploration blocks mature toward production. Hybrid ROV-AUV architectures retain cost advantages for intermittent inspection cycles in shallower waters, constraining pure AUV penetration. Buenos Aires-based contractors increasingly procure AUV hours on day-rate terms while outsourcing seabed interpretation to specialized geoscience boutiques.
Chile
Academic and governmental oceanographic institutions build AUV capabilities for sub-Antarctic ecosystem monitoring, opening non-oil and gas revenue channels with constrained-budget procurement cycles. Micro AUV platforms under 100 kilograms displacement dominate this segment. Concepción and Punta Arenas research corridors concentrate equipment deployment for benthic habitat characterization studies.
Colombia
Caribbean offshore exploration licensing generates emerging demand for pre-drilling baseline environmental assessments. The country's national hydrocarbon regulator imposes ecological survey requirements ahead of block awards, creating compliance pull for bathymetric survey platforms. Barranquilla and Cartagena port infrastructure supports limited AUV logistics capacity as international contractors establish regional staging points.
Peru
Marine research institutions along the Pacific coast deploy compact AUV systems for Humboldt Current ecosystem monitoring and underwater archaeological surveys. Government oceanographic programs prioritize discrete equipment procurement distinct from hydrocarbon capital deployment cycles. Callao serves as the primary logistics hub for subsea vehicle maintenance and technician training development.
South America AUV Market Competitive Landscape
Capability concentration sits with integrated survey contractors possessing permanently stationed regional operations centers; scale advantage sits with diversified defense conglomerates leveraging cross-program technology transfer. The market structures around three archetypes: full-service inspection contractors, defense-heritage platform OEMs, and specialized marine technology subsidiaries. Consolidation pressure manifests through strategic partnerships linking vehicle manufacturers with local service networks, while portfolio diversification drives hybrid vehicle development bridging autonomous and tethered architectures.
Among defense-heritage platform developers, General Dynamics Corporation and Lockheed Martin Corporation exemplify the technology-transfer archetype, applying underwater autonomy expertise developed for naval programs toward commercial hydrocarbon inspection markets. Kongsberg Maritime anchors the integrated marine technology tier through its Brazilian subsidiary operations, sustaining local technician networks for subsea vehicle support. Fugro N.V. occupies a position within the full-service survey contractor segment, competing via permanently stationed Rio de Janeiro infrastructure for offshore inspection contracts.
| Leading Market Players |
|---|
| Subsea Tech |
| Oceaneering International, Inc. |
| General Dynamics Corporation |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Fugro N.V. |
| Kongsberg Maritime |
| Teledyne Technologies |
| Boeing |
| Others |
Value Network & Pricing Analysis
Silver-zinc battery chemistry concentration in Japanese and South Korean specialty cell manufacturers concentrates margin capture upstream, while Brazilian operators absorb currency-adjusted procurement premiums for deepwater endurance configurations. This upstream bottleneck shapes downstream pricing power toward OEM-captive service contracts that bundle hardware with technician networks.
Pricing Analysis
Long-term offtake agreements between Petrobras and integrated survey contractors dominate contract structures, compressing spot-market exposure for pure-play AUV operators. Price differentiation rests on INMETRO certification tier and lithium-polymer endurance specifications, with premium configurations commanding service-bundled premiums. Cost compression in mid-tier survey services is intensifying because Argentine operators increasingly unbundle vehicle procurement from seabed interpretation. Environmental agencies exhibit highest price sensitivity due to constrained-budget academic procurement cycles, while pre-salt operators demonstrate lowest sensitivity given ANP-mandated compliance deadlines.
Supply Chain Analysis
Export-control regimes limiting multibeam echosounder and inertial navigation system flows from US and Norwegian defense-heritage suppliers constrain regional availability of precision payload hardware. Manufacturing concentration centers on Germany, Norway, and the United States for sonar processors, while lithium-ion cell assembly draws from South Korean and Chinese facilities. Single-source vulnerability in Doppler velocity log calibration equipment exposes Brazilian operators to extended lead times. Distribution runs through permanently stationed Rio de Janeiro operations centers that maintain captive spare inventories for ANP-mandated inspection windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with service unbundling and regulatory digitization, as IBAMA baseline study requirements and ANP digital submission mandates create specialized niches for analytics boutiques and certification specialists alongside integrated contractors.
For Market Incumbents: Harden technician network density in Santos Basin port clusters to defend against emerging local-content rules that favor Brazilian-registered service entities. Deepen backward integration into lithium-polymer battery pack assembly to reduce exposure to yen and won currency fluctuation. Prioritize automated feature-extraction algorithm development to capture margin migrating from raw data delivery toward machine-readable defect classification. For New Entrants and Emerging Players: Pursue Chilean marine research corridors where sub-Antarctic ecosystem monitoring programs operate outside hydrocarbon capital deployment cycles and specification intensity remains lower than pre-salt inspection mandates. Target micro AUV configurations under 100 kilograms displacement for academic procurement patterns. Lead with discrete analytics service contracts rather than integrated survey campaigns to bypass incumbent operations center infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed survey contractors holding Rio de Janeiro permanent infrastructure but facing margin compression from service unbundling. Long-term viability favors platforms with defense-technology transfer pathways and dual-use naval-commercial applications. Watch Petrobras fleet standardization decisions as inflection indicator for vendor qualification pathway consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Local-Content Certification Investment | INMETRO compliance accelerates vendor qualification for ANP-mandated inspection contracts. |
| Payload Virtualization Development | Onboard feature-extraction algorithms respond to digital submission requirements for subsea integrity reports. |
| Technician Network Expansion | Local calibration capacity addresses scarcity of Doppler velocity log maintenance skills in regional ports. |
| Hybrid Vehicle Architecture Launch | Dual-mode platforms bridge legacy FPSO ROV infrastructure with AUV economics for transit legs. |
| Environmental Analytics Partnership | IBAMA baseline study specialization captures compliance-driven demand separate from operator procurement. |
Research Methodology
A spread of perspectives from AUV fleet managers at Petrobras and international operators, subsea survey procurement leads, INMETRO certification engineers, and marine research program directors converged on the working assumptions. Secondary validation drew from ANP regulatory filings, IBAMA environmental licensing databases, Brazilian customs import records for underwater equipment, and SEC disclosures from listed survey contractors. Bottom-up equipment deployment tallies triangulated against top-down hydrocarbon capital expenditure allocations across the analysis window.
Demand-supply-balance framing modeled fleet utilization rates against ANP-mandated inspection interval compression and pre-salt drilling program timelines. Segmentation dimensions spanned product type, end user, technology payload, application mission, and water depth tier. CAGRs derived from logistic diffusion curves fitted to platform-to-AUV conversion patterns and battery chemistry displacement rates. Forecast inputs included Petrobras fleet standardization announcements and ENARGAS pipeline surveillance protocol enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by defense-heritage platform OEMs into commercial service contracts would shift outcomes. Material shifts in ANP local-content enforcement or Brazilian real exchange rate volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Educational Robot Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Collaborative Robots Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
Global Programmable Robots Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
United States Articulated Robot Market
Robotics and Automation
Palletizing Robots Market