
 Healthcare Companion Robots Market | 2026-2036
Healthcare Companion Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Companion Robots Market Intelligence
A shift from single-source sensor procurement to multi-source component sourcing is repositioning supply chain risk for healthcare robot manufacturers. Intuition Robotics leverages Israeli R&D partnerships for AI-driven eldercare interfaces. PARO Robots anchors its therapeutic seal platform through captive Japanese manufacturing of tactile sensors. SoftBank Robotics competes via channel control across European hospital distribution networks.
Healthcare companion robots are electromechanical systems integrating AI processors, capacitive touch arrays, and voice-recognition modules to deliver non-clinical patient support, monitoring, and social engagement in care settings. Social robots lead product category revenue through established dementia therapy protocols, while assistive robots represent the fastest-growing segment as mobility aid algorithms mature. End-user concentration tilts toward nursing homes where reimbursement frameworks stabilize procurement budgets, though home care channels capture expanding margin pools through direct-to-consumer subscription models.
FDA classifies therapeutic companion robots as Class II medical devices when claiming clinical outcomes, while EU MDR requires notified body intervention for CE marking of robots with diagnostic functions. Japan's PMDA maintains streamlined review pathways for emotionally supportive devices without therapeutic claims, shaping divergent product registration strategies across jurisdictions. Stakeholders must monitor evolving software-as-medical-device determinations that could reclassify AI-updated companion platforms without hardware changes.
Market Dynamics
Reimbursement pathway fragmentation across Japan, Germany, and the United States is forcing manufacturers to engineer divergent product certification strategies for the same hardware platform. Payers in each jurisdiction apply incompatible evidentiary standards for therapeutic claims, compressing margin structures and lengthening commercialization timelines.
Growth Catalysts
- Japan PMDA streamlined pathways:Emotionally supportive devices without explicit therapeutic claims access accelerated review, reducing time-to-market for dementia care applications in nursing facilities.
- EU MDR diagnostic function mandates:Notified body intervention requirements for robots with patient monitoring capabilities are creating certified product scarcity that commands premium positioning in German rehabilitation networks.
- Capacitive touch array maturation:Tactile sensor reliability improvements enable consistent therapeutic interaction protocols, expanding reimbursable use cases beyond pilot programs.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing dependence on East Asian cell manufacturers exposes production schedules to export control volatility and shipping lane disruptions.
- FDA Class II clinical evidentiary burdens:Therapeutic outcome claims trigger 510(k) or De Novo pathways requiring controlled studies, imposing capital requirements that exclude mid-tier entrants.
- Human caregiver substitution thresholds:Institutional liability frameworks limit unsupervised deployment, capping addressable hours per unit below theoretical operational capacity.
Strategic Opportunities
- Home care direct-to-consumer channels:Subscription-based service models bypass institutional procurement cycles, capturing recurring revenue streams from aging-in-place demographics in the United States.
- ISO 13485 quality system convergence:Harmonized medical device quality standards across notified bodies enable single-audit, multi-market access strategies for software-updatable platforms.
- Mobility aid algorithm licensing:Assistive navigation IP bundled into third-party hardware creates royalty revenue without manufacturing exposure, targeting Japanese eldercare facility networks.
Industry Challenges
- Software-as-medical-device determinations:AI model updates risk triggering reclassification reviews, requiring regulatory affairs teams to pre-validate algorithm change protocols with FDA and PMDA.
- Voice recognition module integration:Acoustic processing hardware from disparate suppliers creates firmware compatibility failures, demanding expanded quality assurance headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Companion Robots Market |
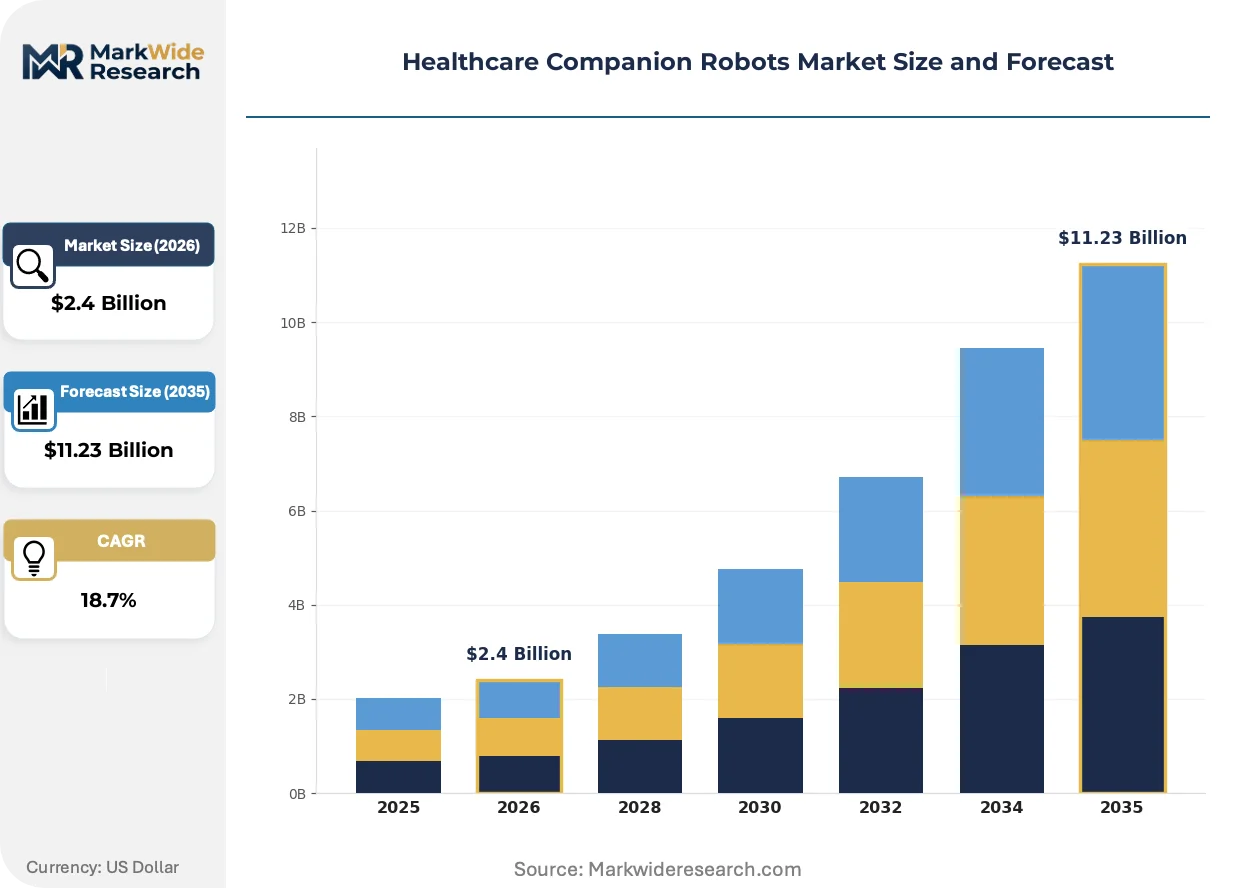
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Social Robots, Therapy Robots, Assistive Robots, Surgical Robots End User: Hospitals, Nursing Homes, Home Care, Rehabilitation Centers Functionality: Monitoring, Communication, Mobility Assistance, Emotional Support Technology: AI, Machine Learning, Sensor Technology, Speech Recognition |
| Companies Covered | Intuition Robotics, Blue Frog Robotics, SoftBank Robotics, Honda Robotics, Ubtech Robotics, PARO Robots, Hanson Robotics, No Isolation, ASUS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Companion Robots Market Strategic Shifts & Innovations
Edge AI inference engines are migrating onto companion robot mainboards, eliminating cloud latency for real-time emotional state detection. This architectural shift compresses hardware BOMs while expanding deployable environments beyond reliable connectivity coverage.
Multimodal sensor fusion is automating contextual awareness in dementia care settings. Japanese nursing facilities deploy these systems for agitation episode prediction, reducing pharmacological intervention incidence. The technology is automating documentation workflows previously requiring licensed nursing observation hours.
EU AI Act high-risk system classifications are reshaping conformity assessment obligations for therapeutic companion platforms. Notified bodies must evaluate algorithmic transparency and bias mitigation measures prior to CE marking. German rehabilitation centers now require supplier documentation of training data provenance as a procurement gate.
Institutional leasing arrangements are displacing capital purchase models in North American long-term care chains. Operators prefer per-bed-month fees that transfer obsolescence risk to manufacturers, compressing upfront revenue recognition while extending customer lifetime value horizons. This pattern is most visible in United States multi-site nursing home operators consolidating vendor relationships.
Healthcare Companion Robots Market Segmentation
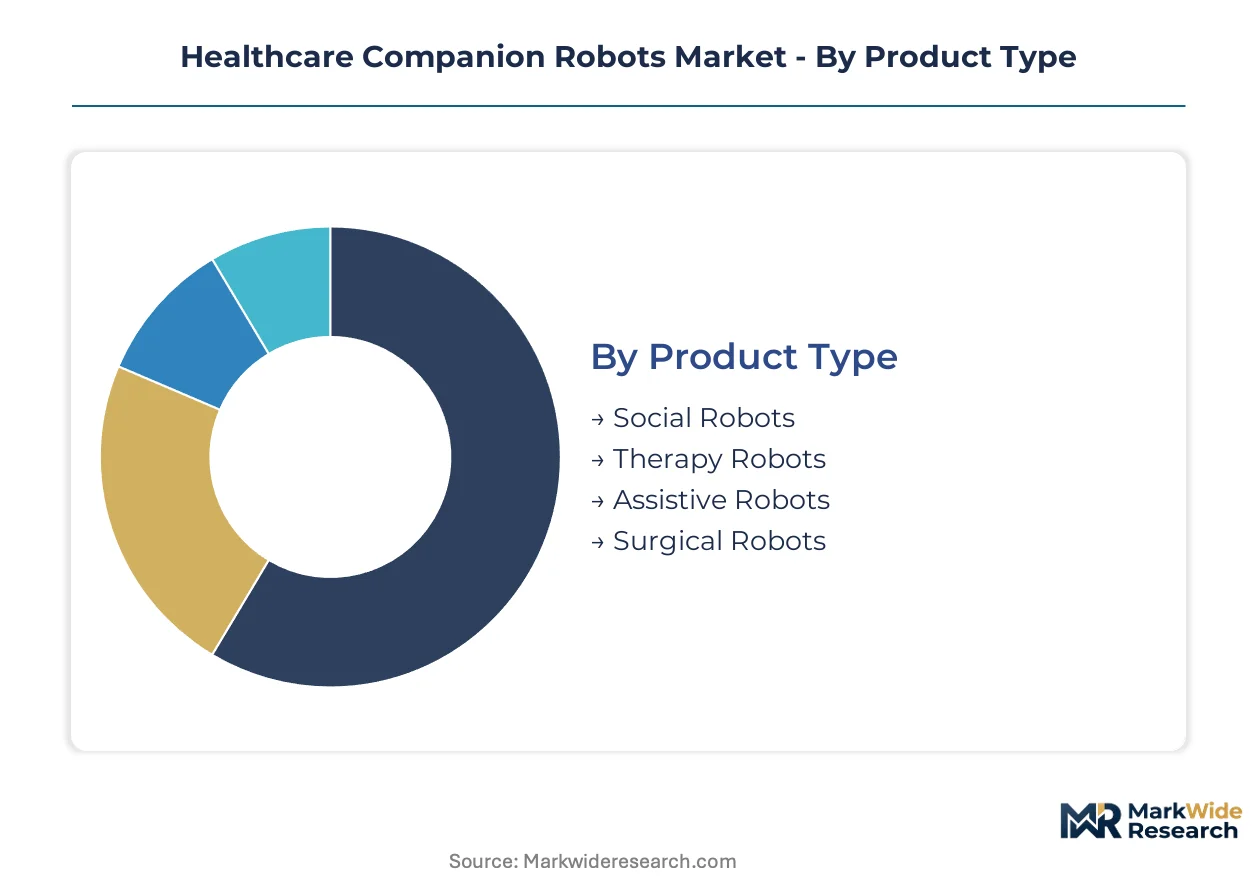
Healthcare companion robot manufacturers face divergent capital requirements across product architectures. Segment selection determines regulatory pathway complexity, sensor integration costs, and reimbursement eligibility.
Product Type:
Social robots demand the heaviest upfront investment in tactile sensor arrays and emotional AI training datasets.
- Social Robots:These platforms integrate capacitive touch surfaces, voice synthesis modules, and facial recognition cameras for dementia therapy applications. Japanese nursing facilities under PMDA guidance drive procurement volume for PARO seal units and similar anthropomorphic designs. The hardware BOM concentrates spending on haptic feedback systems and edge AI processors.
- Therapy Robots:Engineered for clinical outcome claims, these systems carry FDA Class II certification burdens requiring controlled study documentation. German rehabilitation centers operating under EU MDR notified body requirements absorb premium pricing for certified therapeutic platforms. Capital intensity peaks here due to dual regulatory compliance costs.
- Assistive Robots:Mobility aid platforms with navigation algorithms and physical support mechanisms.
- Surgical Robots:Precision manipulation systems for minimally invasive procedures with sterilization-grade component requirements.
Most installed capacity flows through Social Robots. Expansion is steepest in Assistive Robots.
End User:
Nursing homes concentrate procurement volume through institutional reimbursement frameworks, while home care channels demand leaner hardware cost structures.
- Hospitals:Acute care settings prioritize infection-resistant enclosures and EMR integration capabilities. Procurement runs through centralized supply chains with multi-year service contracts.
- Nursing Homes:Long-term care operators in Japan and Germany deploy social robots for agitation reduction protocols. Reimbursement stability under national insurance schemes supports capital budgeting.
- Home Care:Direct-to-consumer subscription models bypass institutional sales cycles. Aging-in-place demographics in the United States absorb monthly service fees for remote monitoring and companionship functions.
- Rehabilitation Centers:Physical therapy applications require force-feedback actuators and progress-tracking software. EU MDR conformity documentation gates supplier selection in German-speaking markets.
Revenue concentration sits with Nursing Homes. Home Care channels are gaining share fastest.
Functionality:
Emotional support functions require multimodal sensor fusion, while monitoring applications leverage simpler camera and microphone arrays.
- Monitoring:Fall detection and vital sign tracking through passive infrared and radar sensors. Deployment concentrates in United States skilled nursing facilities with liability-driven risk management priorities.
- Communication:Voice-enabled family connectivity and medication reminder systems. Hardware costs scale with speech recognition accuracy requirements and multilingual support breadth.
- Mobility Assistance:Powered exoskeleton and walker guidance platforms with LiDAR navigation. Japanese METI-funded eldercare facility retrofits drive adoption for gait rehabilitation applications.
- Emotional Support:AI-driven affective computing with real-time emotional state classification. PMDA streamlined review pathways in Japan accelerate deployment for dementia care without therapeutic claims.
Deployment volume clusters around Monitoring. Emotional Support features are climbing the fastest.
Technology:
AI inference engines concentrate R&D spending, while sensor technology sourcing exposes supply chain vulnerabilities.
- AI:Edge-deployed neural networks for real-time decision-making without cloud dependency. Israeli R&D partnerships supply algorithmic capabilities for eldercare interface developers.
- Machine Learning:Continuous model refinement from aggregated interaction datasets. EU AI Act high-risk system classifications impose training data provenance documentation burdens on German market entrants.
- Sensor Technology:Tactile, visual, and acoustic input arrays from multi-source procurement. Japanese captive manufacturing of pressure-sensitive components reduces supply risk for domestic producers.
- Speech Recognition:Natural language processing modules from third-party API integration or in-house development. Firmware compatibility failures across disparate hardware suppliers expand quality assurance overhead.
Patent activity clusters in AI. Machine Learning capabilities are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka-Kobe manufacturing corridor anchors production capacity for tactile sensor arrays serving dementia therapy platforms. Japanese nursing facilities under PMDA guidance absorb the highest per-facility deployment density globally. Cross-border regulatory divergence between FDA, EU MDR, and PMDA pathways fragments certification timelines for identical hardware architectures.
Japan
Metropolitan Tokyo nursing chains deploy PARO seal units under streamlined PMDA emotionally supportive device pathways. METI subsidizes eldercare facility retrofits through regional technology adoption grants. Osaka-Kobe corridor concentrates captive manufacturing of pressure-sensitive tactile components for domestic robot producers.
Germany
Bavarian rehabilitation centers command premium pricing for EU MDR-certified therapeutic platforms with diagnostic functions. Notified body intervention requirements create certified product scarcity in Munich-Stuttgart medical technology cluster. German payers apply stringent evidentiary standards for therapeutic outcome reimbursement claims.
United States
California-based AI developers supply edge inference engines for eldercare interface platforms. FDA Class II medical device classification for therapeutic claims triggers 510(k) evidentiary burdens that exclude mid-tier market entrants. Texas and Florida long-term care chains pilot institutional leasing models transferring obsolescence risk to manufacturers.
Israel
Tel Aviv R&D partnerships concentrate algorithmic capabilities for affective computing and emotional state detection. Israeli developers supply AI-driven eldercare interfaces to third-party hardware manufacturers under licensing arrangements. Jerusalem-Beer Sheva corridor hosts machine learning training operations for multimodal sensor fusion systems.
South Korea
Seoul Capital Area electronics manufacturers produce capacitive touch arrays and voice recognition modules for regional robot assemblers. MFDS medical device regulations govern therapeutic platform certification timelines. Busan-Ulsan industrial zone supplies lithium-ion battery packs exposing production schedules to East Asian cell sourcing concentration.
Healthcare Companion Robots Market Key Industry Players
Global majors compete with regional champions across regulatory certification capabilities and distribution network depth. Market structure tilts toward specialized therapeutic platform developers with captive manufacturing assets alongside AI software licensors without hardware exposure. Three archetypes dominate: Japanese tactile sensor integrators with PMDA pathway expertise, European notified body certification specialists, and Israeli algorithm developers licensing IP to third-party hardware manufacturers. Competitive moves concentrate on strategic partnerships for multi-market regulatory access and mobility aid algorithm licensing to eldercare facility networks.
Within the tactile sensor integration tier, PARO Robots exemplifies Japanese captive manufacturing strategies for dementia therapy platforms. SoftBank Robotics occupies a position representing European hospital distribution network control. Intuition Robotics anchors the AI licensing archetype, supplying algorithmic capabilities without direct hardware manufacturing exposure. These three company structures illustrate divergent capital allocation strategies across certification-heavy therapeutic hardware versus software-centric service models.
| Leading Market Players |
|---|
| Intuition Robotics |
| Blue Frog Robotics |
| SoftBank Robotics |
| Honda Robotics |
| Ubtech Robotics |
| PARO Robots |
| Hanson Robotics |
| No Isolation |
| ASUS |
| Others |
Cost & Logistics Intelligence
Lithium carbonate benchmark volatility cascades through battery pack procurement into tiered hardware pricing for healthcare companion robots. Component concentration in East Asian cell manufacturing compresses margin structures for mid-tier assemblers while premium therapeutic platforms absorb input spikes through notified body certification premiums.
Pricing Analysis
Input-cost pass-through dominates pricing architecture for healthcare companion robots, with capacitive touch array and edge AI processor expenses flowing directly into hardware tiers. Three-tier pricing structure across premium therapeutic, standard social, and economy monitoring levels differentiates by FDA Class II certification status and tactile sensor density. Pricing pressure stems from lithium-ion cell supply concentration and shipping lane disruption exposure. Home care direct-to-consumer subscribers exhibit highest price sensitivity, while German rehabilitation centers under EU MDR mandates absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and sensor recalibration create secondary revenue streams for Japanese nursing facility operators deploying PARO seal units. Component sourcing concentrates in South Korea for capacitive touch arrays, Japan for pressure-sensitive tactile sensors, and China for voice recognition modules. Raw material dependencies include lithium carbonate, rare earth magnets, and semiconductor-grade silicon wafers. Single-source vulnerability in East Asian battery cell manufacturing exposes production schedules to export control volatility. Distribution runs through European hospital procurement consortia and Japanese eldercare facility networks with METI subsidy gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare Companion Robots Market functions as a stable compounder anchored by irreversible demographic aging across developed economies. Institutional reimbursement frameworks in Japan and Germany provide recurring revenue visibility that supports long-dated manufacturing investments.
For Market Incumbents: Acquire tactile sensor fabrication assets to reduce exposure to Osaka-Kobe supply concentration. Secure PMDA pathway expertise through regional partnerships before FDA Class II evidentiary burdens harden competitive moats. Channel control investments in German rehabilitation networks defend against Israeli algorithm licensors entering hardware manufacturing. For New Entrants and Emerging Players: Begin with home care direct-to-consumer subscription models in the United States, where aging-in-place demographics bypass institutional procurement cycles. Target mobility assistance functionality as the fastest-expanding segment with lower regulatory entry costs than therapeutic platforms. License navigation algorithms to Japanese eldercare facility networks rather than building captive manufacturing. For Investors and Strategic Acquirers: Asymmetric upside sits with Israeli affective computing developers holding algorithmic IP without hardware exposure. Five-to-ten year viability hinges on software-as-medical-device determination precedents that could reclassify AI-updated platforms. Monitor FDA software change control guidance drafts as the critical inflection signal for platform valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Streamlined Pathway Registration | Accelerates time-to-market for emotionally supportive devices in Japanese nursing facilities. |
| EU MDR Notified Body Certification | Creates certified product scarcity commanding premium positioning in German rehabilitation networks. |
| Hospital System Partnership | Locks in multi-year service contracts with acute care procurement committees for EMR-integrated platforms. |
| Software Companion Development | Enables recurring subscription revenue from algorithm updates without hardware refresh cycles. |
| Reimbursement Strategy | Secures national insurance scheme coverage for dementia therapy applications in Japanese eldercare chains. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with nursing home operations directors, biomedical engineers, PMDA regulatory consultants, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body databases, Japanese METI technology adoption grant records, and hospital procurement contract repositories. Bottom-up unit deployment estimates triangulated against top-down reimbursement flow analysis.
Segment-weighting approaches distributed value across product type, end user, functionality, and technology dimensions throughout the forecast period. CAGRs derived from installed base expansion rates and per-unit pricing trajectories modeled separately for institutional and direct-to-consumer channels. Edge AI processor cost curves and tactile sensor reliability improvements informed hardware BOM compression assumptions.
Several conditions sit outside the modeled scope, including unannounced regulatory reclassifications, lithium supply disruption scenarios, and breakthrough therapeutic efficacy claims that could accelerate substitution. Practitioners should monitor FDA software-as-medical-device guidance drafts and EU AI Act high-risk system enforcement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Data Center Robotics Market