
 Waste Sorting Robots Market | 2026-2036
Waste Sorting Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Sorting Robots Market Analysis
Skilled technician shortages in waste handling operations is redrawing competitive dynamics across the waste sorting robots sector. AMP Robotics leverages proprietary AI algorithms to anchor its position in North American recycling infrastructure. ZenRobotics sustains technology leadership through heavy-duty robotic arms purpose-built for construction and demolition waste streams. TOMRA dominates optical sorting integration, extending its influence from beverage container redemption into mixed municipal waste processing.
Waste sorting robots are autonomous material recovery systems combining articulated robotic arms with spectral imaging, near-infrared sensors, and deep learning classification networks to identify, localize, and physically separate recyclables from mixed waste streams at throughput rates exceeding human manual sorting by factors of three to five. Municipal waste facilities represent the most mature deployment channel, with recycling centers emerging as the fastest-growing end user segment driven by contamination-rate penalties and resale value recovery targets. Plastic sorting applications command the largest current volume, while electronic waste processing concentrates the highest margin pools due to precious metal recovery economics and specialized disassembly requirements.
The EPA enforces landfill diversion targets under the Resource Conservation and Recovery Act that directly shape municipal procurement timelines for automated sorting infrastructure. The EU Green Deal and REACH compliance frameworks mandate recycled content quotas that force European operators to invest in purity-grade sorting technology. OSHA standards governing worker exposure to hazardous waste environments further accelerate robotic substitution in industrial operations. Stakeholders must monitor regulatory tightening on contamination thresholds as the decisive variable determining retrofit versus greenfield deployment economics.
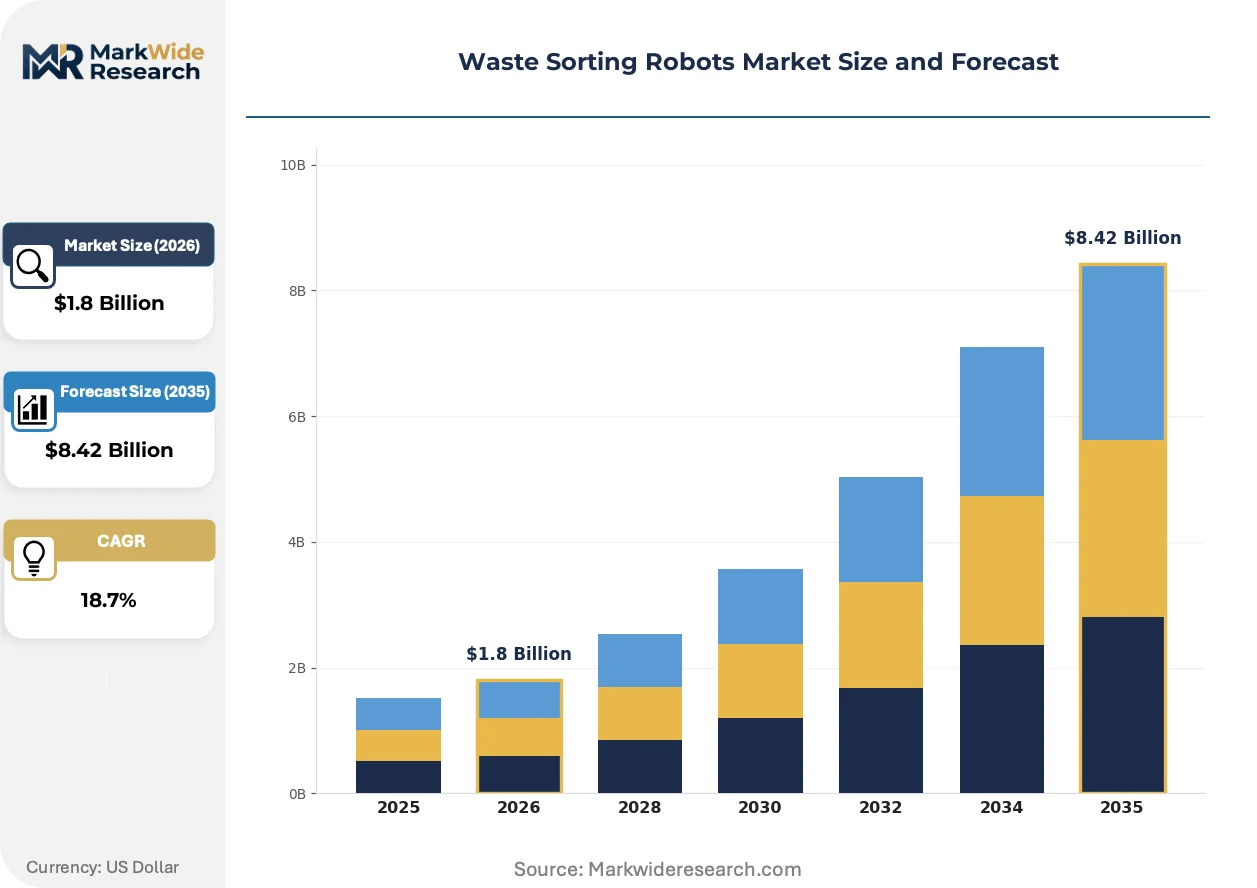
Market Dynamics
Labor scarcity in European and North American recycling operations is compressing payback-period thresholds for robotic sorting investments, while EU Green Deal mandates on contamination rates are forcing facility retrofits at unprecedented velocity.
Growth Catalysts
- EU Green Deal recycling purity mandates:The framework's escalating contamination thresholds compel municipal operators in Germany, France, and the Netherlands to deploy AI-driven optical sorting systems capable of achieving 95%+ material recovery rates.
- Construction and demolition waste streams:Heavy-duty robotic arms with payload capacities exceeding 30 kilograms are penetrating C&D recycling facilities where manual sorting poses acute ergonomic hazards and throughput bottlenecks.
- Near-infrared sensor fusion:Multi-spectral imaging arrays combining NIR, RGB, and laser-induced breakdown spectroscopy are expanding sortable resin categories from seven to over twenty polymer types.
Market Restraints
- Capital intensity of retrofit installations:Integration of robotic cells into existing MRF conveyor architectures demands mechanical reconfiguration budgets that often exceed the robot hardware cost by 40-60 percent.
- Sensor component supply concentration:High-resolution hyperspectral cameras and precision pneumatic ejectors rely on specialized German and Japanese component suppliers with 12-16 week lead times.
- Technical limitation in flexible packaging:Multi-layer film laminates and metallized pouches defeat current near-infrared polymer identification, creating residual waste streams that undermine facility economics.
Strategic Opportunities
- Electronic waste processing verticals:Precious metal recovery economics from printed circuit boards and battery cells justify premium robotic disassembly systems with specialized end-effectors for hazardous material handling.
- Performance-based service contracting:Robot-as-a-service models with throughput-guarantee pricing are penetrating mid-sized recycling centers that lack balance-sheet capacity for capital acquisition.
- REACH compliance-driven purity premiums:Recycled content quotas in automotive and packaging sectors create price spreads between standard and food-grade polymer fractions that reward high-fidelity sorting investments.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of articulated robotic arms with pneumatic sorting actuators requires cross-trained personnel fluent in both PLCs and machine vision calibration, a skill intersection with limited vocational pipeline output.
- Legacy MRF control system integration:Proprietary SCADA architectures from incumbent conveyor OEMs resist open-protocol connectivity with third-party robotic cells, forcing expensive middleware development or partial line rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Sorting Robots Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Computer Vision, AI Algorithms, Sensor-Based Systems End User: Municipal Waste Facilities, Recycling Centers, Industrial Operations, Commercial Establishments Application: Plastic Sorting, Metal Sorting, Organic Waste Management, Electronic Waste Processing Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Integrated Systems |
| Companies Covered | Sadako Technologies, TOMRA, AMP Robotics, Greyparrot, Machinex Industries, ZenRobotics, Bulk Handling Systems, Bollegraaf Recycling Machinery, Waste Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Sorting Robots Market Emerging Trajectories
Spectral imaging hardware and deep learning architectures are converging to expand sortable material categories while compressing the latency between identification and physical separation. These advances are redrawing competitive boundaries between optical sorters and robotic pickers.
Hyperspectral imaging arrays spanning 400-2500 nanometers are decomposing the technical barrier between polymer identification and contamination detection. Recycling centers in the Netherlands and Belgium are deploying these systems at throughputs exceeding five tons per hour. The technology is decomposing the historical trade-off between sorting speed and material purity, enabling single-pass processing that previously required dual-stage configuration.
REACH substance restrictions on persistent organic pollutants in recycled plastics are tightening testing and certification protocols for output streams. The European Chemicals Agency's evolving candidate list is forcing sorting facilities to invest in X-ray fluorescence detection modules for heavy metal screening. Electronics recyclers in Germany face the most acute compliance burden, with some operators retrofitting robotic lines to achieve batch-level traceability documentation.
Equipment purchasing committees at municipal waste authorities are consolidating vendor relationships around full-system integrators rather than component suppliers. Single-source accountability for throughput guarantees and uptime warranties is displacing the traditional practice of specifying best-of-breed subsystems separately. This pattern is most pronounced in France, where regional waste syndicates wield sufficient volume to demand turnkey performance contracts with penalty clauses for contamination-rate failures.
Waste Sorting Robots Market Segmentation
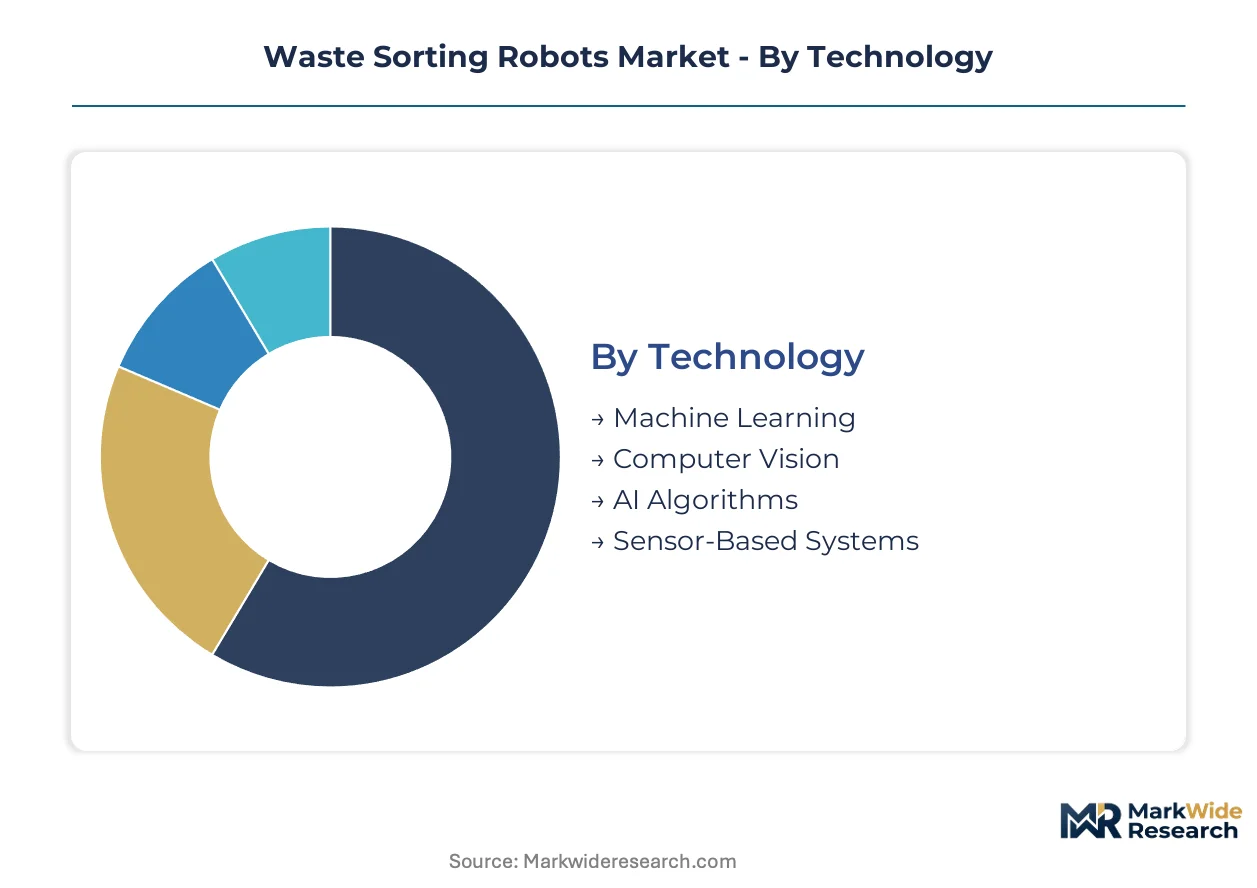
Waste sorting robots segment along technology maturity curves and facility integration depth. Procurement committees evaluate segments against contamination penalties, labor substitution economics, and retrofit complexity.
Technology:
Computer vision platforms face substitution pressure from sensor fusion architectures that bypass RGB limitations entirely.
- Machine Learning:Neural network architectures trained on heterogeneous waste stream datasets enable continuous model refinement without hardware replacement. German MRF operators prioritize these systems for their adaptability to seasonal packaging variations.
- Computer Vision:RGB and hyperspectral imaging arrays process visual signatures at conveyor speeds exceeding three meters per second. Dutch recycling centers deploy these for high-volume plastic identification where polymer purity premiums justify capital intensity.
- AI Algorithms:Proprietary classification engines differentiate sortable fractions through spectral fingerprint matching.
- Sensor-Based Systems:Near-infrared and X-ray fluorescence modules detect material composition independent of surface appearance.
Computer vision anchors the volume base while machine learning gains share at the steepest rate.
End User:
Cost tier stratification separates capital-rich municipal authorities from mid-sized recyclers seeking service contracts.
- Municipal Waste Facilities:Publicly funded MRFs with established conveyor infrastructure require extensive mechanical reconfiguration for robotic integration. French regional waste syndicates specify turnkey performance contracts with uptime guarantees.
- Recycling Centers:Privately operated facilities face acute contamination-rate penalties from offtake agreements. Belgium and Netherlands centers are expanding fastest as REACH compliance tightens material purity requirements.
- Industrial Operations:Manufacturing waste streams with consistent composition reduce algorithm training burdens.
- Commercial Establishments:Retail and hospitality generators deploy compact systems for on-site source separation.
Municipal waste facilities anchor the volume base while recycling centers climb the fastest.
Application:
Margin concentration varies sharply across material categories, with precious metal recovery economics diverging from bulk commodity processing.
- Plastic Sorting:Multi-polymer separation demands hyperspectral resolution across 900-1700 nanometer bands. German automotive packaging recyclers invest heavily to capture food-grade rPET premiums under EU recycled content mandates.
- Electronic Waste Processing:Robotic disassembly of printed circuit boards and battery cells targets copper, gold, and rare earth recovery. German electronics recyclers retrofit lines for batch-level traceability under ECHA substance restrictions.
- Metal Sorting:Eddy current and induction sensor arrays separate ferrous from non-ferrous fractions.
- Organic Waste Management:Contamination removal from compost streams employs lower-complexity vision systems.
Plastic sorting anchors the volume base while electronic waste processing expands most quickly.
Deployment:
Customer technical sophistication determines architecture preference, with cloud dependency creating cybersecurity evaluation hurdles.
- On-Premise:Localized processing eliminates latency between identification and pneumatic ejection. French nuclear-adjacent waste handlers mandate air-gapped systems for operational security compliance.
- Hybrid Solutions:Edge computing for real-time sorting decisions combined with cloud-based model training and fleet analytics. Netherlands operators favor these for balancing throughput responsiveness with algorithm improvement velocity.
- Cloud-Based:Centralized model updates reduce per-facility IT overhead.
- Integrated Systems:Single-vendor accountability spanning mechanical, control, and software layers.
On-premise deployments anchor the volume base while hybrid solutions gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys waste sorting robots primarily for construction and demolition waste streams, while the United States concentrates investment in municipal material recovery facilities and the Netherlands leads in food-grade plastic purification systems.
Germany
Construction and demolition waste processing drives robotic procurement in German recycling infrastructure. The EU Green Deal mandates escalating recycling purity thresholds that force facility operators to automate sorting lines. Bavarian waste syndicates around Munich are retrofitting heavy-duty robotic cells for 30-kilogram payload operations in C&D facilities.
United States
Municipal material recovery facilities dominate American deployment as labor shortages constrain manual sorting capacity. EPA enforcement of landfill diversion targets under the Resource Conservation and Recovery Act shapes procurement timelines for automated infrastructure. California's Sacramento Valley waste authorities are consolidating vendor relationships around full-system integrators with throughput guarantees.
Netherlands
Food-grade polymer purification commands premium investment as REACH compliance tightens material certification requirements. The Dutch national waste strategy mandates higher recycling rates that accelerate AI-driven optical sorting adoption. Randstad recycling clusters around Amsterdam and Rotterdam deploy hyperspectral imaging arrays exceeding five tons per hour throughput.
France
Regional waste syndicates wield sufficient procurement volume to demand turnkey performance contracts with penalty clauses. EU Green Deal contamination thresholds compel investment in purity-grade sorting technology for plastic fractions. Île-de-France waste authorities around Paris specify single-source accountability for uptime warranties and retrofit integration.
Belgium
Privately operated recycling centers face acute contamination-rate penalties from offtake agreements with packaging producers. ECHA substance restrictions on persistent organic pollutants force investment in X-ray fluorescence detection modules. Flemish processing facilities around Antwerp are expanding robotic lines fastest in Europe as REACH compliance tightens.
Waste Sorting Robots Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in waste sorting robotics. The upper tier combines proprietary AI classification engines with full mechanical system integration capabilities. Specialist competitors concentrate in pure-play computer vision, heavy-duty robotic manipulation, or optical sensor hardware. Dominant competitive moves include strategic partnerships between AI software developers and conveyor OEMs, plus geographic expansion through regional system integrator alliances.
Within the integrated tier, TOMRA anchors optical sorting integration from beverage redemption into mixed municipal waste, while AMP Robotics represents North American AI-native positioning and ZenRobotics exemplifies heavy-duty manipulation for construction waste streams. Specialists include Greyparrot with waste analytics software, Sadako Technologies with pneumatic sorting actuation, and Machinex Industries with turnkey material recovery facility integration. Bulk Handling Systems and Bollegraaf Recycling Machinery occupy positions as full-line mechanical system providers with robotic cell compatibility.
| Leading Market Players |
|---|
| Sadako Technologies |
| TOMRA |
| AMP Robotics |
| Greyparrot |
| Machinex Industries |
| ZenRobotics |
| Bulk Handling Systems |
| Bollegraaf Recycling Machinery |
| Waste Robotics |
| Others |
Supply Flow & Price Mechanics
EU Green Deal contamination thresholds gate both supplier qualification and price differentiation simultaneously, forcing robotic sorting vendors to tier offerings by purity-grade certification while buyers face penalty-driven procurement urgency that compresses negotiation leverage.
Pricing Analysis
Long-term performance contracts with throughput guarantees dominate municipal procurement, while mid-sized recyclers favor robot-as-a-service subscriptions that shift capital burden to operational expenditure. Price differentiation separates food-grade polymer certification tiers from standard output fractions, with REACH compliance premiums widening spreads between qualified and unqualified system integrators. Pricing pressure stems from retrofit integration costs that often exceed hardware expenditure, squeezing margin capture in brownfield deployments. Municipal waste authorities exhibit lowest price sensitivity due to diversion-mandate compliance deadlines, whereas privately held recycling centers face acute working capital constraints that amplify subscription-model preference.
Supply Chain Analysis
German and Japanese component suppliers anchor the chokepoint for high-resolution hyperspectral cameras and precision pneumatic ejectors, with 12-16 week lead times constraining deployment velocity for system integrators. Robotic arm assemblies draw from Chinese and South Korean manufacturing bases, while AI classification engines rest on cloud compute infrastructure concentrated in US and European hyperscale regions. Single-source vulnerability in specialized optical sensor supply creates exposure to trade restriction escalation or logistics disruption. Distribution runs through regional system integrator networks that consolidate mechanical, control, and software layers into turnkey accountability structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waste sorting robotics is approaching a platform-economics inflection where interoperability between AI classification engines and conveyor OEM control architectures determines competitive survival, with open-protocol integration emerging as the decisive ecosystem battleground.
For Market Incumbents: Consolidate around full-system integration capabilities that bundle proprietary AI with mechanical retrofit expertise, neutralizing the threat from pure-play computer vision specialists by controlling SCADA middleware development. Prioritize backward integration into pneumatic ejector manufacturing to reduce exposure to Japanese component lead times. Anchor capacity expansion in France and the Netherlands where regional waste syndicate procurement volume supports performance-contract pricing power. For New Entrants and Emerging Players: Differentiate on electronic waste disassembly specialization where precious metal recovery economics justify premium robotic end-effector development and regulatory traceability requirements create incumbent blind spots. Target mid-sized Belgian recycling centers facing acute REACH compliance pressure but lacking balance-sheet capacity for turnkey capital deployment. Pursue robot-as-a-service go-to-market structures that convert contamination-rate penalties into recurring revenue streams. For Investors and Strategic Acquirers: EU Green Deal recycling purity mandates reshape the acquisition landscape by elevating vendors with demonstrated 95%+ material recovery rates above component suppliers lacking integration depth. Frame long-term viability around five-to-ten year municipal contract renewal cycles and automotive sector recycled content quota expansion. Monitor ECHA candidate list evolution as the signal to watch for X-ray fluorescence detection module retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Protocol Integration Development | AMP Robotics and TOMRA are racing to establish middleware standards that lock out proprietary SCADA incumbents. |
| Heavy-Duty Payload Capacity Expansion | ZenRobotics anchors German C&D market position through 30-kilogram robotic arm specialization. |
| Hyperspectral Imaging Array Partnership | Dutch recycling clusters deploy five-ton-per-hour throughput systems that compress dual-stage processing economics. |
| Robot-as-a-Service Model Launch | Mid-sized Belgian operators convert REACH compliance penalties into operational expenditure structures. |
| X-Ray Fluorescence Module Retrofit | German electronics recyclers achieve batch-level traceability under ECHA substance restriction enforcement. |
Methodological Framework
Operator-level perspectives from MRF plant managers, recycling center operations directors, municipal procurement committee chairs, and robotic system maintenance technicians anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary sources including EPA enforcement records, ECHA candidate list updates, EU Green Deal implementation progress reports, and municipal waste authority RFP documentation. Bottom-up facility deployment tracking combined with top-down regulatory mandate analysis to establish market sizing boundaries.
Sensitivity analysis around retrofit integration cost variance and component lead time fluctuation shaped the forecast framework across the projection horizon. Segmentation dimensions modeled include technology architecture, end-user facility type, material application category, and deployment model configuration. CAGRs derived from facility-level procurement pipeline analysis weighted by regulatory compliance deadline clustering. Industry-specific inputs incorporated EU recycled content mandate trajectory and OSHA hazardous waste exposure standard evolution.
Material uncertainties — regulatory timeline acceleration, hyperspectral sensor supply disruption, and municipal budget cycle compression — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding labor substitution economics and contamination penalty enforcement intensity. Practitioners should keep alternative scenarios live as REACH substance restriction scope and automotive sector rPET offtake agreement terms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Autonomous Mobile Robots for Logistics and Warehousing Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market