
 Industrial Control Robotics Market | 2026-2036
Industrial Control Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Control Robotics Market Foresight
Germany is tilting toward expanded servo-motor and controller production to supply European automotive retrofit programs. ABB leverages its Zurich-based automation campus to sustain leadership in heavy-payload articulated systems for Mercedes-Benz and BMW welding lines. FANUC Corporation anchors its global installed base through captive CNC and servo supply chains in Yamanashi Prefecture. KUKA competes from Augsburg with deep integration into Volkswagen Group's electric vehicle body shops.
Industrial control robotics encompasses programmable multi-axis manipulators governed by servo drives, PLCs, and real-time kinematic algorithms executing tasks with repeatability below 0.1 millimeter. These systems synchronize motor torque, position feedback, and end-effector tooling to automate material transformation and assembly workflows in continuous-operation factories. Articulated robots lead installed value due to six-degree-of-freedom flexibility in automotive welding and painting cells where reach envelopes exceed two meters. Collaborative robots represent the fastest-expanding product class as force-limiting joints and vision-guided safety enable fenceless deployment beside human operators in electronics assembly. Sensor integration technology captures disproportionate R&D investment because LiDAR, torque sensors, and machine vision modules determine path accuracy and collision avoidance performance.
Factory inspectorates in Germany enforce ISO 10218 and ISO/TS 15066 compliance for collaborative robot safety zones and force thresholds. The EU Machinery Directive and CE marking requirements shape product design cycles for any control robotics vendor accessing European automotive or food packaging buyers. OSHA lockout/tagout standards and ANSI/RIA R15.06 specifications govern US deployment architecture and operator training protocols. Stakeholders must monitor how NIST cybersecurity frameworks for operational technology reshape remote access and over-the-air update architectures in connected robot fleets.
Market Dynamics
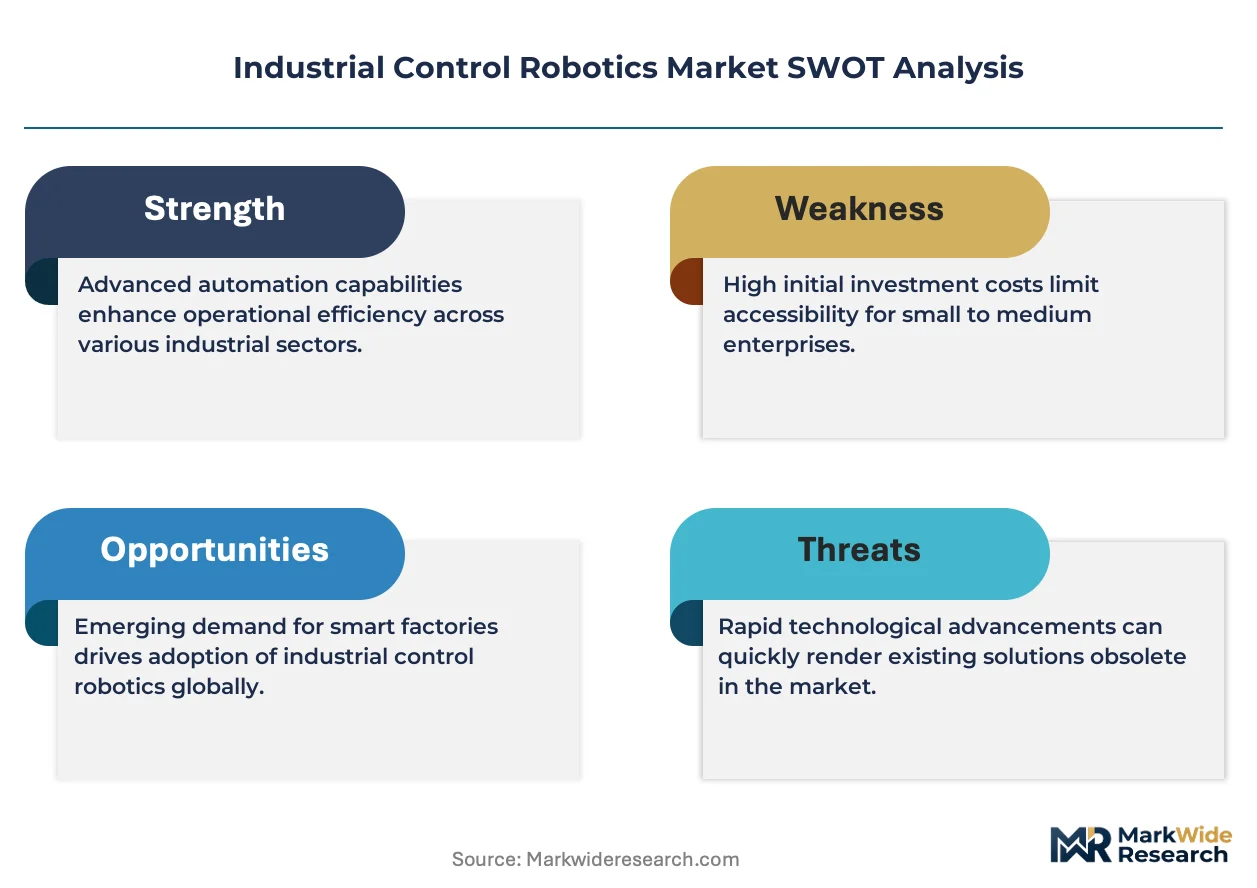
Automotive electrification programs are forcing wholesale reconfiguration of welding and assembly line architectures, driving demand for reprogrammable multi-axis systems capable of rapid retooling between internal combustion and battery-electric vehicle platforms.
Growth Catalysts
- ISO/TS 15066 force-limiting mandates:European factory inspectorates now require collaborative robot deployments in fenceless configurations, accelerating hardware refresh cycles across German and Italian automotive suppliers.
- Electronics contract manufacturing clusters:East Asian surface-mount assembly lines scale collaborative robot fleets to absorb smartphone and wearable device production volatility without fixed automation footprints.
- Servo-motor torque density improvements:Permanent magnet motor advances enable lighter robot arms with identical payload capacity, reducing cell footprint requirements in space-constrained Japanese and South Korean plants.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing capacity concentrates in Chinese refining operations, exposing servo-motor and high-torque joint actuator supply chains to export restriction risk.
- Cybersecurity compliance burden:NIST cybersecurity frameworks for operational technology impose architectural redesign costs on connected robot fleets with remote access capabilities.
- Legacy PLC protocol fragmentation:Proprietary fieldbus standards from incumbent automation vendors create integration friction when deploying third-party collaborative robots alongside existing fixed automation cells.
Strategic Opportunities
- Indian automotive component manufacturing:PLI scheme incentives for advanced cell and electric vehicle production create first-mover advantage for robot vendors establishing local integration partnerships.
- Machine vision-LiDAR convergence:Sensor fusion architectures combining 3D point cloud generation with real-time object recognition enable bin-picking applications in unstructured logistics environments previously resistant to automation.
- EU Green Deal embodied carbon tracking:Manufacturing facility decarbonization mandates drive retrofit demand for energy-efficient servo drives and regenerative power modules in existing European automotive body shops.
Industry Challenges
- Kinematic calibration expertise scarcity:Robot integrators face compressed project timelines as automotive OEMs accelerate electric vehicle platform launches, exceeding available pools of technicians proficient in multi-axis path optimization.
- Functional safety certification latency:TÜV and DEKRA validation cycles for collaborative robot force-limiting algorithms extend 14-18 months, delaying product launches and freezing R&D roadmaps.
- Legacy weld gun integration complexity:Retrofitting articulated robots into existing resistance welding cells requires custom end-effector adapters and current feedback loop re-engineering, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Control Robotics Market |
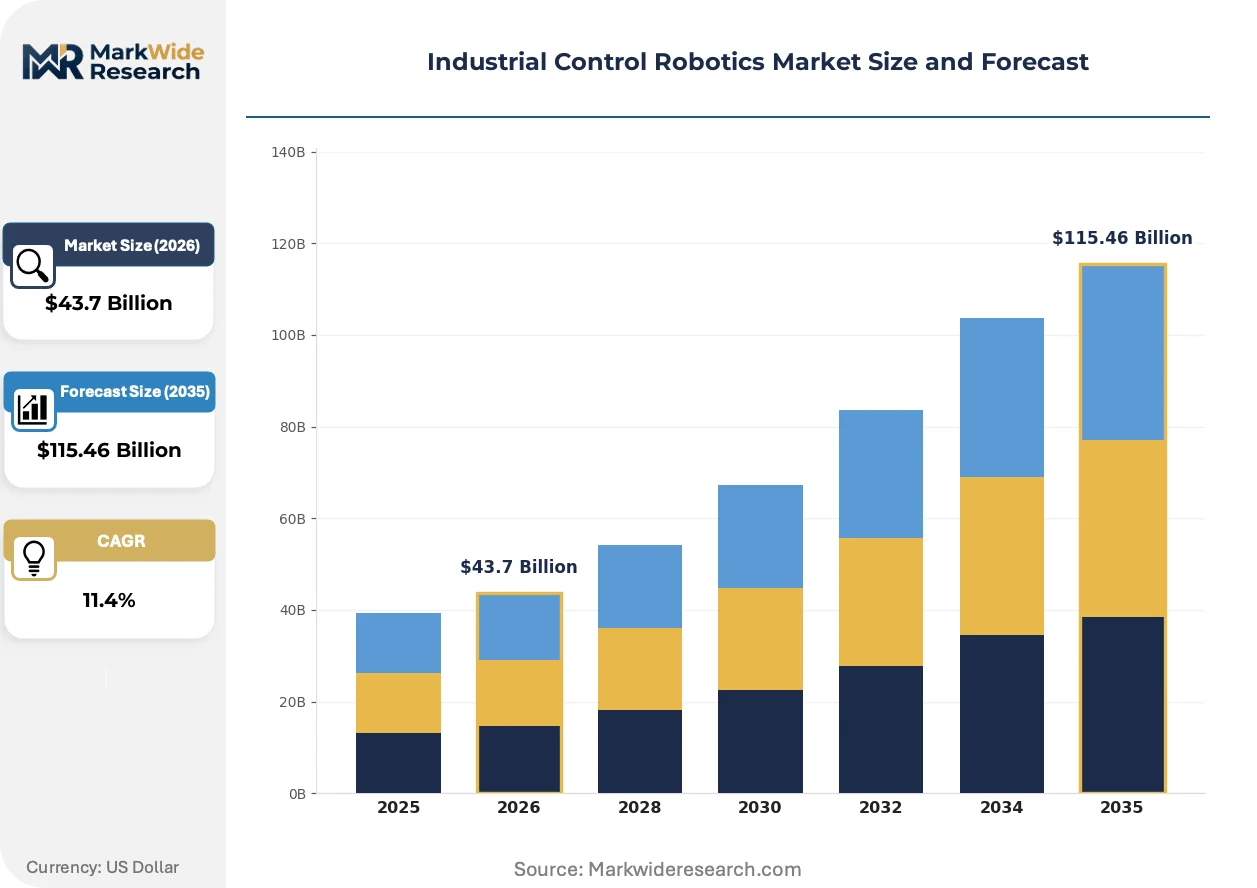
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $115.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Collaborative Robots, Cartesian Robots End User: Manufacturing, Assembly, Packaging, Material Handling Technology: AI-Powered Robotics, Machine Learning, Sensor Integration, Automation Software Application: Welding, Painting, Pick and Place, Quality Control |
| Companies Covered | ABB, FANUC Corporation, Yaskawa Electric Corporation, KUKA, Epson, Kawasaki Heavy Industries, Denso Corporation, Mitsubishi Electric, Universal Robots, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Control Robotics Market Shifts & Advancements
Control architectures are decoupling from proprietary hardware stacks, enabling software-defined motion control that permits algorithm updates without physical controller replacement. This shift compresses innovation cycles and fragments vendor lock-in structures.
Edge-computing motion controllers are migrating from centralized PLC cabinets to distributed nodes mounted directly on robot joints. Automotive OEMs in Stuttgart and Wolfsburg pilot these architectures to eliminate cabinet cooling loads and reduce cable harness complexity. The technology is compressing installation timelines from weeks to days while enabling over-the-air kinematic algorithm updates without production line stoppage.
EU AI Act risk classification rules now categorize adaptive welding path algorithms as high-risk artificial intelligence systems. Industrial robot vendors serving Mercedes-Benz and BMW welding programs must implement conformity assessment procedures and post-market monitoring systems. German automotive suppliers are responding by segregating adaptive control features into modular software blocks that can be deactivated to maintain CE marking compliance during regulatory interpretation periods.
Buyer contracting preferences are compressing from capital equipment purchase toward throughput-guarantee service agreements. Electronics contract manufacturers in Taiwan and South Korea now specify units-per-hour output commitments rather than robot hardware specifications, transferring operational risk to system integrators. This shift is most visible in semiconductor packaging facilities where die-bonding cycle time variability directly impacts foundry economics.
Industrial Control Robotics Market Segmentation
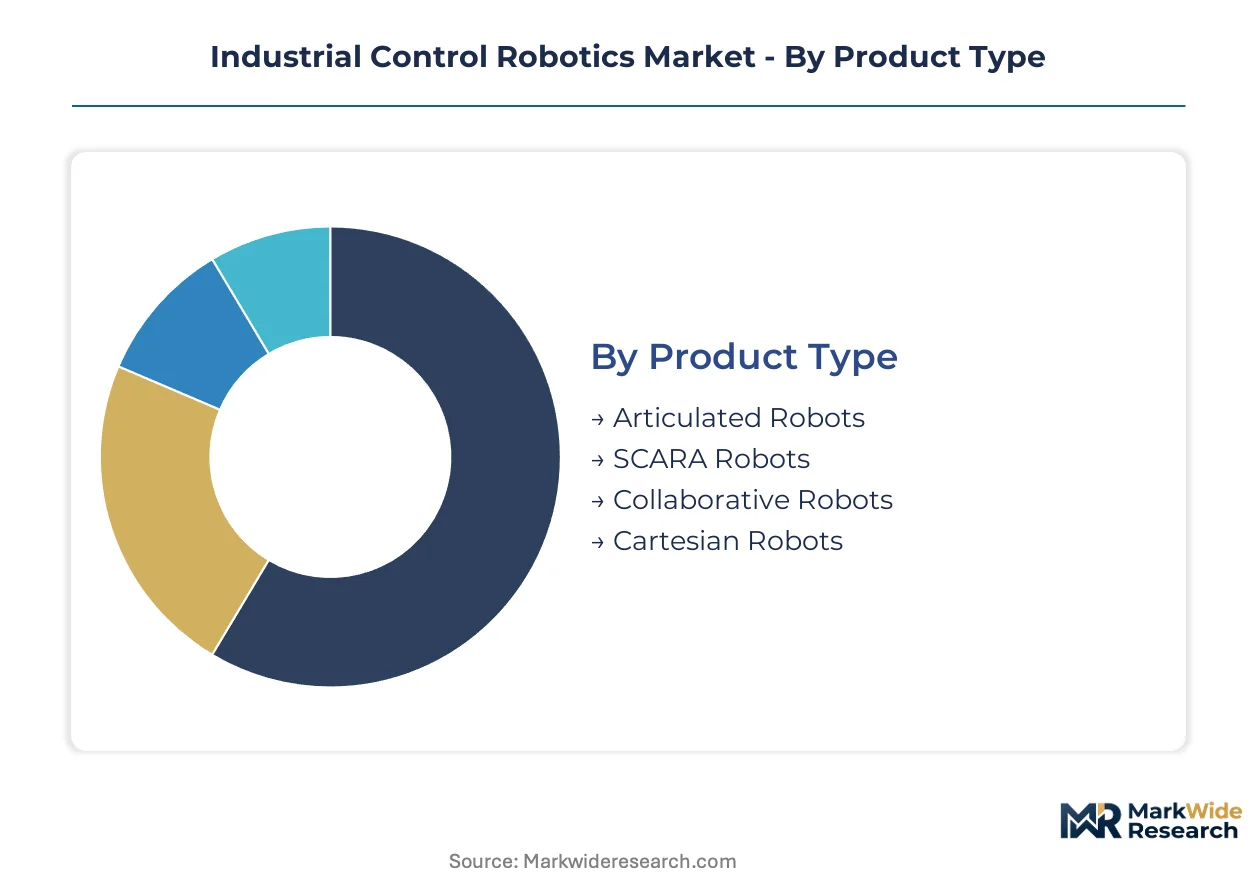
Segmentation in industrial control robotics reveals how technical specifications, end-use requirements, and integration complexity fragment procurement decisions across automotive, electronics, and logistics verticals. Understanding these divides exposes where vendors can command premium positioning versus where price competition dominates.
Product Type:
Mature six-axis architectures coexist with emerging force-limited platforms as factory footprints shrink and safety mandates evolve.
- Articulated Robots:Six-degree-of-freedom manipulators with rotary joints enabling complex path interpolation across welding and painting envelopes exceeding two meters. Mercedes-Benz and BMW body shops in Stuttgart and Munich drive sustained demand for heavy-payload variants capable of manipulating weld guns exceeding 100 kilograms.
- Collaborative Robots:Force-limiting joint actuators and torque sensors enable fenceless deployment beside human operators, with ISO/TS 15066 compliance now mandatory for European electronics contract manufacturers scaling flexible surface-mount assembly lines.
- SCARA Robots:Selective Compliance Assembly Robot Arms deliver high-speed planar motion with vertical rigidity for precision pick-and-place in semiconductor packaging facilities across Taiwan and South Korea.
- Cartesian Robots:Linear actuator configurations provide cost-effective positioning for gantry-mounted material handling in warehouse automation deployments.
Articulated robots retain volume leadership; collaborative robots hold the steepest expansion curve.
End User:
Cost tier differentiation separates capital-intensive continuous operations from batch-configurable contract manufacturing environments.
- Manufacturing:Continuous-operation automotive and heavy machinery production lines demand hardened controllers with mean-time-between-failures exceeding 60,000 hours, where unplanned downtime costs exceed €50,000 per hour at German OEM facilities.
- Assembly:Electronics contract manufacturers in East Asian clusters prioritize rapid reprogrammability to absorb smartphone and wearable device production volatility without fixed automation footprints.
- Packaging:Food and pharmaceutical facilities require IP69K-rated washdown capabilities and stainless steel construction to satisfy EU hygiene directives.
- Material Handling:Logistics operators deploy vision-guided systems for unstructured bin-picking in e-commerce fulfillment centers where SKU variety exceeds 100,000 units.
Manufacturing commands the highest absolute spend; assembly demonstrates the most rapid deployment velocity.
Technology:
Supply concentration in sensor hardware and AI inference chips is reshaping vendor integration strategies.
- AI-Powered Robotics:Adaptive path planning algorithms now trigger EU AI Act high-risk system classification, forcing German automotive suppliers to segregate learning features into modular software blocks for deactivation during regulatory interpretation periods.
- Machine Learning:Predictive maintenance models trained on motor current signatures and vibration spectra reduce unplanned downtime in FANUC's Yamanashi Prefecture servo motor production facilities.
- Sensor Integration:LiDAR, torque sensors, and machine vision modules capture disproportionate R&D investment as path accuracy and collision avoidance performance become primary competitive differentiators.
- Automation Software:Software-defined motion control architectures decouple algorithms from proprietary hardware stacks, compressing innovation cycles and fragmenting vendor lock-in structures.
Sensor integration absorbs the largest development budget; AI-powered robotics faces the steepest regulatory compliance burden.
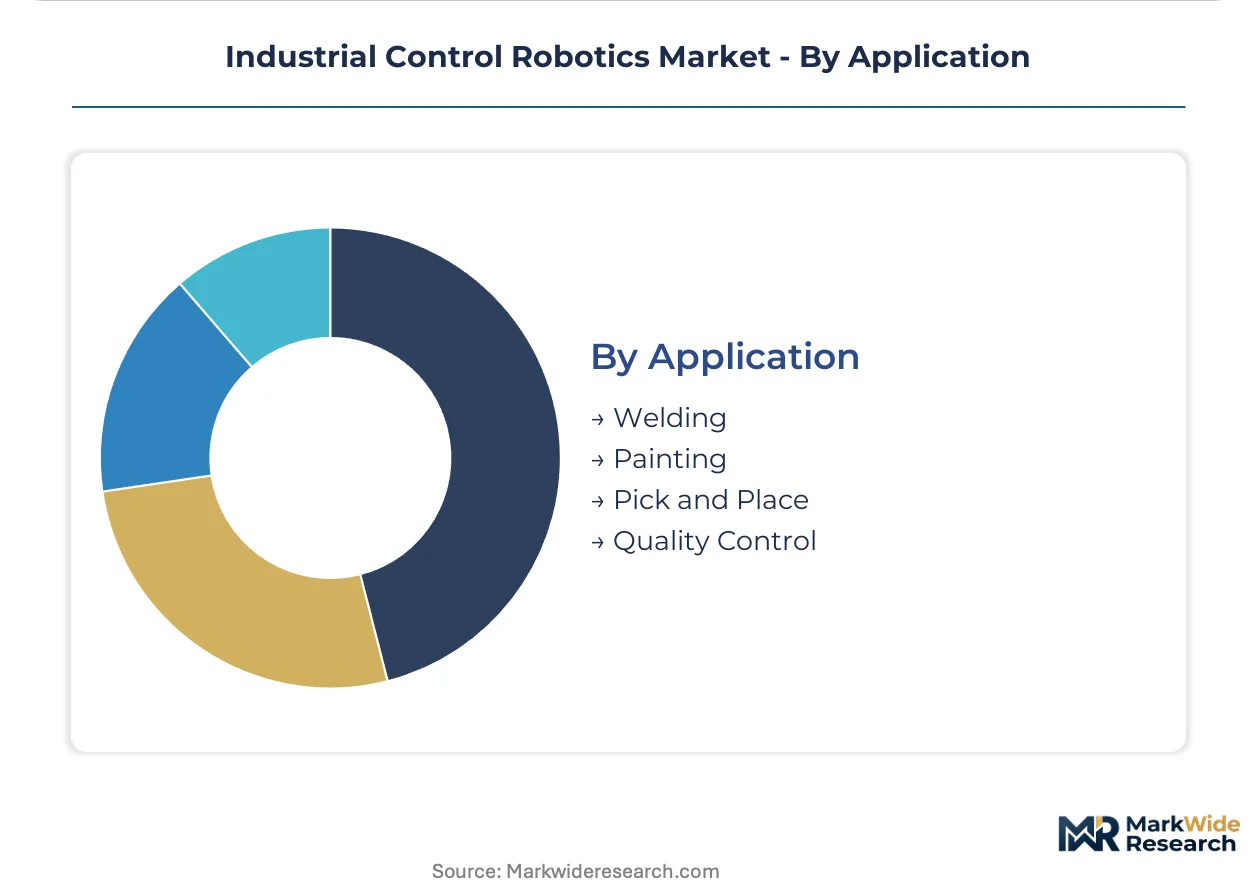
Application:
Margin structure varies sharply between precision-path processes and repetitive handling tasks.
- Welding:Resistance spot and arc welding cells require custom end-effector adapters and current feedback loop re-engineering, inflating deployment costs when retrofitting articulated robots into existing automotive body shops.
- Painting:Explosive atmosphere certification and electrostatic atomizer integration limit vendor qualification to specialists with ATEX compliance track records.
- Pick and Place:High-speed delta and SCARA configurations dominate electronics surface-mount lines where cycle times below 0.3 seconds directly impact foundry economics.
- Quality Control:Machine vision-guided inspection systems verify dimensional tolerances below 0.05 millimeter in aerospace component manufacturing.
Welding generates the highest system integration revenue; pick and place achieves the fastest hardware amortization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure anchors European demand for heavy-payload material handling systems. German automotive welding lines and Japanese precision manufacturing clusters drive regional specialization patterns across three continents.
Germany
Automotive electrification programs at Volkswagen and BMW facilities demand rapid retooling capabilities between combustion and battery platforms. Factory inspectorates enforce ISO 10218 and ISO/TS 15066 compliance for collaborative robot safety zones. Stuttgart and Munich body shops deploy heavy-payload articulated systems for resistance welding cells.
Japan
FANUC's Yamanashi Prefecture servo production and Yaskawa's Kitakyushu motor facilities concentrate precision component manufacturing. METI industrial automation incentives support SME robot adoption in Nagoya manufacturing clusters. Osaka-area electronics contract manufacturers scale collaborative robot fleets for flexible surface-mount assembly.
China
MIIT smart manufacturing initiatives accelerate robot density targets in Yangtze River Delta electronics clusters. GB standards for industrial robot safety reshape product certification requirements for domestic and export markets. Shenzhen and Suzhou surface-mount facilities absorb smartphone production volatility through rapid reprogrammable automation.
United States
OSHA lockout/tagout standards and ANSI/RIA R15.06 specifications govern deployment architecture in Detroit automotive welding programs. NIST cybersecurity frameworks for operational technology reshape remote access architectures in connected robot fleets. Michigan and Ohio body shops retrofit articulated systems for electric vehicle platform transitions.
South Korea
MFDS-equivalent industrial safety regulators align collaborative robot force thresholds with ISO/TS 15066 benchmarks. Government smart factory initiatives target semiconductor packaging and display panel manufacturing. Busan-Ulsan and Daejeon-Sejong clusters deploy SCARA configurations for die-bonding cycle time optimization.
Industrial Control Robotics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in servo motor and sensor hardware. The vendor base concentrates around heavy-payload articulated systems for automotive welding and force-limited collaborative platforms for electronics assembly. Three archetypes dominate: diversified industrial conglomerates with captive component supply, pure-play robot specialists with deep automotive integration partnerships, and emerging collaborative robot vendors with software-defined architectures. Competitive moves center on sensor fusion technology licensing and backward integration into permanent magnet motor production.
Within the diversified industrial tier, ABB leverages its Zurich-based automation campus to anchor European automotive demand. FANUC Corporation exemplifies captive supply chain control through integrated CNC and servo production. KUKA occupies a position within German automotive integration, serving Volkswagen Group electric vehicle body shops from its Augsburg base.
| Leading Market Players |
|---|
| ABB |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| KUKA |
| Epson |
| Kawasaki Heavy Industries |
| Denso Corporation |
| Mitsubishi Electric |
| Universal Robots |
| Others |
Supply & Pricing Matrix
Rare-earth magnet processing in Chinese refining operations concentrates upstream margin capture for servo-motor and joint actuator suppliers, forcing downstream robot vendors to absorb cost volatility or pass through to automotive and electronics buyers with limited substitution options.
Pricing Analysis
EU Machinery Directive and CE marking requirements dictate the pricing tier structure across European automotive procurement, with ISO/TS 15066-compliant collaborative systems commanding premium positioning over non-certified alternatives. Three-tier pricing structure across premium certified, standard industrial, and economy retrofit levels separates vendors by functional safety validation depth and after-sales service bundling. Pricing pressure stems from Chinese domestic robot manufacturers expanding export capacity with cost-competitive articulated systems. Electronics contract manufacturers in Taiwan and South Korea demonstrate highest price sensitivity due to throughput-guarantee contracting models, while German automotive OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese rare-earth refining operations, with Japanese permanent magnet producers and German servo-motor manufacturers forming secondary processing tiers. Permanent magnet alloys, high-purity copper windings, and precision-machined gearboxes constitute critical component dependencies. Single-source vulnerability in rare-earth oxide separation exposes supply chains to export restriction risk under evolving trade policy. Distribution runs through authorized system integrator networks in automotive clusters and direct OEM relationships in electronics manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial control robotics sits in early-cycle expansion as collaborative robot penetration in fenceless electronics assembly accelerates beyond historical fixed-automation replacement rates.
For Market Incumbents: Entrench captive servo-motor supply through backward integration into permanent magnet production or long-term offtake agreements with Japanese and German component specialists. Deepen software-defined motion control architectures to fragment competitor lock-in and absorb emerging collaborative robot vendors with modular algorithm platforms. ISO/TS 15066 certification investment represents the priority defensive lever against Chinese cost-competitive entrants.
For New Entrants and Emerging Players: Indian automotive component manufacturing clusters offer underpenetrated demand as PLI scheme incentives accelerate electric vehicle platform investments without incumbent robot vendor relationships. Target semiconductor packaging facilities in South Korea with die-bonding cycle time optimization as the most penetrable precision application. Machine vision-LiDAR convergence for unstructured bin-picking provides differentiated go-to-market positioning against established articulated robot vendors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed collaborative robot specialists possessing software-defined architectures but lacking automotive welding integration track records. Five-to-ten year viability hinges on successful migration from electronics assembly into heavier-payload manufacturing applications. TÜV and DEKRA certification cycle compression serves as the critical inflection signal for product launch velocity and R&D roadmap unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Production | Captive neodymium supply secures servo-motor cost stability against Chinese export policy shifts. |
| Software-Defined Motion Control Platform | Algorithm decoupling from proprietary hardware compresses innovation cycles for ABB and FANUC. |
| ISO/TS 15066 Certification Acceleration | Force-limiting validation depth determines European automotive supplier qualification access. |
| Machine Vision-LiDAR Sensor Fusion Development | 3D point cloud integration enables bin-picking penetration in logistics environments resistant to automation. |
| Indian Manufacturing Integration Partnership | PLI scheme incentives create first-mover positioning in emerging electric vehicle component supply chains. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at German and Japanese automotive facilities, procurement leads at electronics contract manufacturers, system integrator technical directors, and aftermarket service heads, then refined through secondary validation against SEC filings, customs trade data, MIIT smart manufacturing disclosures, and IHS Markit vehicle production databases. Bottom-up unit deployment estimates across welding, painting, and assembly applications were triangulated against top-down market value reconstruction.
Demand-supply balance modeling across the projection horizon incorporated segmentation by robot kinematic architecture, end-use industry vertical, force-limiting safety certification tier, and regional manufacturing cluster density. CAGRs were derived from installed base growth rates, replacement cycle compression, and average selling price trajectory assumptions. Forecast inputs included automotive electrification program timelines, EU AI Act compliance cost burdens, and rare-earth magnet supply concentration risk premiums.
Practitioners should monitor rare-earth export policy shifts, TÜV certification cycle durations, and EU AI Act enforcement interpretation for early signals of forecast revision. Cross-checking against IEA industrial automation deployment benchmarks and MIIT robot density targets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Quadruped Robot Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Robot End-Effector Market