
 PCB Layout Software Market | 2026-2036
PCB Layout Software Market Size, Share, and Industry Trends Forecast 2026-2036
PCB Layout Software Market Insights
Multi-source licensing for PCB layout tools is realigning how OEMs balance proprietary ecosystems against open-source alternatives. Cadence Design Systems sustains deep integration between its schematic capture and simulation suites, while Siemens anchors enterprise deployments through its Teamcenter PLM connectivity. KiCad competes on zero-license-cost entry points that attract university programs and startup design houses.
PCB layout software comprises electronic design automation tools that translate circuit schematics into manufacturable board geometries, typically managing trace widths down to sub-50-micron tolerances and layer counts exceeding 64 in high-density interconnect applications. Its primary purpose is to ensure signal integrity, thermal management, and electromagnetic compatibility before fabrication. Cloud-based deployment is capturing mid-market design houses that lack server infrastructure, while 3D CAD capabilities are pulling premium spending from aerospace contractors who must validate mechanical clearances before prototyping. Open-source alternatives remain concentrated among freelancers and educational institutions where budget constraints override enterprise feature requirements.
FDA oversight of medical device electronics and FCC Part 15 electromagnetic compatibility rules directly shape validation workflows embedded in commercial PCB software suites. The EPA's conflict minerals disclosure requirements and REACH substance restrictions in Europe compel traceability features that document material origins across supply chains. Stakeholders must weigh whether regulatory complexity favors integrated platform consolidation or specialized best-of-breed toolchains.
Market Dynamics
Automotive electrification is compressing PCB design cycles while mandating thermal and electromagnetic validation at earlier stages, forcing tool vendors to embed simulation engines directly into layout environments.
Growth Catalysts
- EU F-Gas Regulation:REACH substance restrictions in Europe compel traceability features that document material origins across supply chains, expanding software module demand for compliance documentation.
- High-density interconnect (HDI) proliferation:Layer counts exceeding 64 in aerospace and medical devices require advanced autorouting algorithms that handle sub-50-micron tolerances.
- Germany's automotive electronics cluster:Munich and Stuttgart design houses are expanding tool investments as electrification intensifies board complexity for battery management systems.
Market Restraints
- Specialized engineering talent scarcity:Signal integrity expertise commands premium compensation, constraining mid-market design house expansion.
- Cloud infrastructure dependency:SaaS deployment reliability hinges on regional data center concentration, creating latency vulnerabilities for distributed teams.
- Legacy file format lock-in:Proprietary ECAD formats from dominant vendors create switching friction that protects incumbents.
Strategic Opportunities
- India's electronics manufacturing incentives:PLI scheme beneficiaries require affordable PCB tools, opening segments for zero-license-cost entry points in university and startup ecosystems.
- Digital twin convergence:Integration between PCB layout and mechanical CAD enables pre-prototyping clearance validation that reduces aerospace iteration cycles.
- Medical device software validation:FDA 21 CFR Part 820 quality system requirements create demand for automated documentation workflows in diagnostic equipment design.
Industry Challenges
- Multi-physics simulation integration:Thermal-electromagnetic co-simulation demands specialized compute infrastructure that strains mid-tier engineering budgets.
- Cross-functional collaboration workflows:Mechanical and electrical design teams operate on mismatched revision control systems, introducing version conflict risks.
- Open-source toolchain fragmentation:KiCad and community extensions lack unified support structures, complicating enterprise adoption decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCB Layout Software Market |
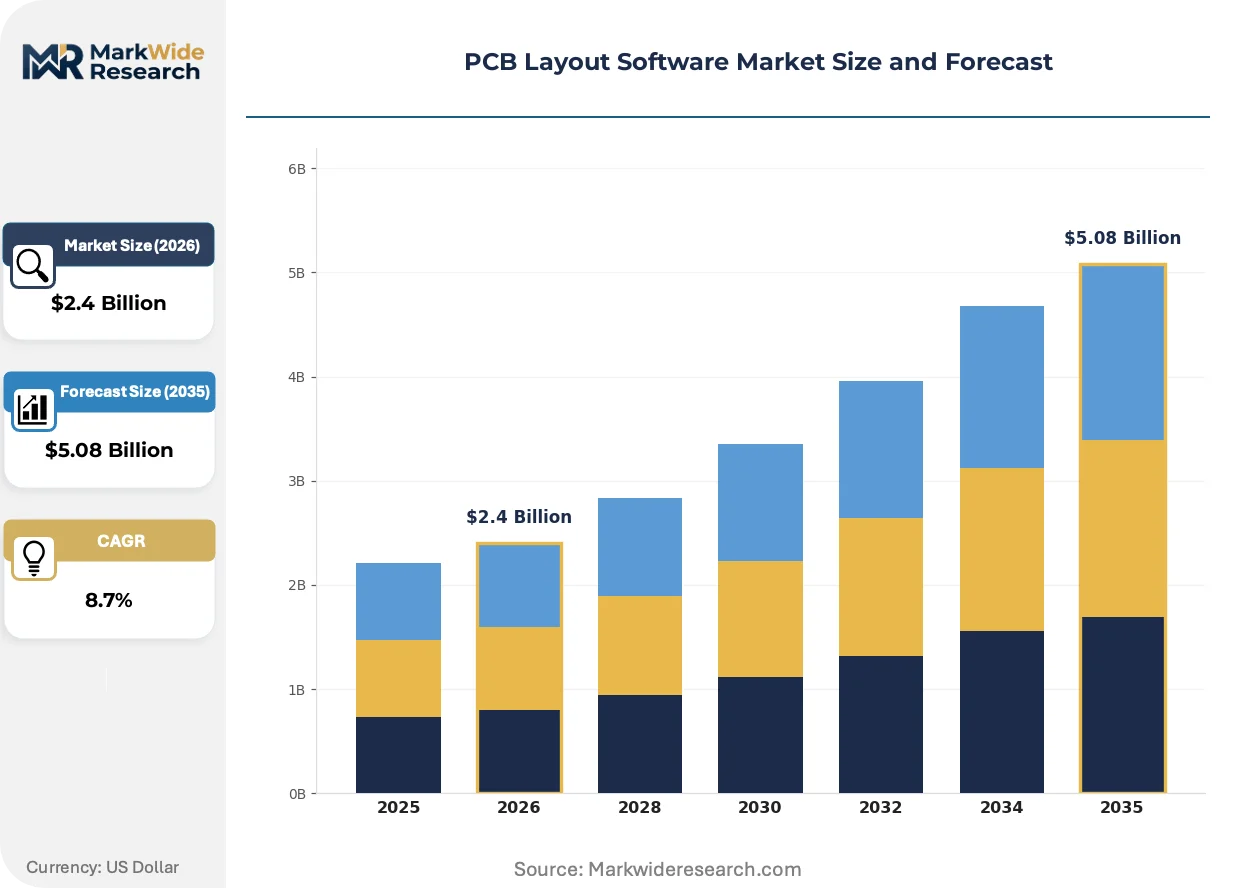
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D CAD, 3D CAD, Schematic Capture, Design Automation Application: Consumer Electronics, Automotive, Telecommunication, Aerospace Deployment: On-Premises, Cloud-Based, Hybrid, Open Source End User: OEMs, Design Houses, Educational Institutions, Freelancers |
| Companies Covered | Altium, Cadence Design Systems, Siemens, Zuken, Autodesk, ANSYS, OrCAD, PADS, KiCad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCB Layout Software Market Trends and Innovations
Cloud-native architectures are overtaking on-premise deployment models, while regulatory traceability mandates and shifting procurement patterns reshape how design tools are evaluated and purchased.
AI-assisted autorouting is overtaking rule-based algorithms in high-complexity designs. Machine learning models trained on fabrication yield data optimize trace geometries for manufacturability. Automotive tier-1 suppliers in Germany and Japan are adopting these engines for battery management system layouts. The technology is overtaking manual tuning cycles that previously consumed 40% of design schedules.
REACH substance restrictions and EU F-Gas Regulation compliance modules are becoming standard features in commercial suites. These tools automate material origin documentation and restricted substance screening across supply chains. Medical device and automotive electronics segments in Europe are driving adoption, with design houses embedding these workflows into release gates.
Subscription pricing is displacing perpetual licenses among mid-market design houses. Cloud-based deployment eliminates server capital expenditure while enabling elastic compute for simulation workloads. This shift concentrates most visibly among North American and European contract manufacturers serving aerospace prototyping contracts.
PCB Layout Software Market Segmentation
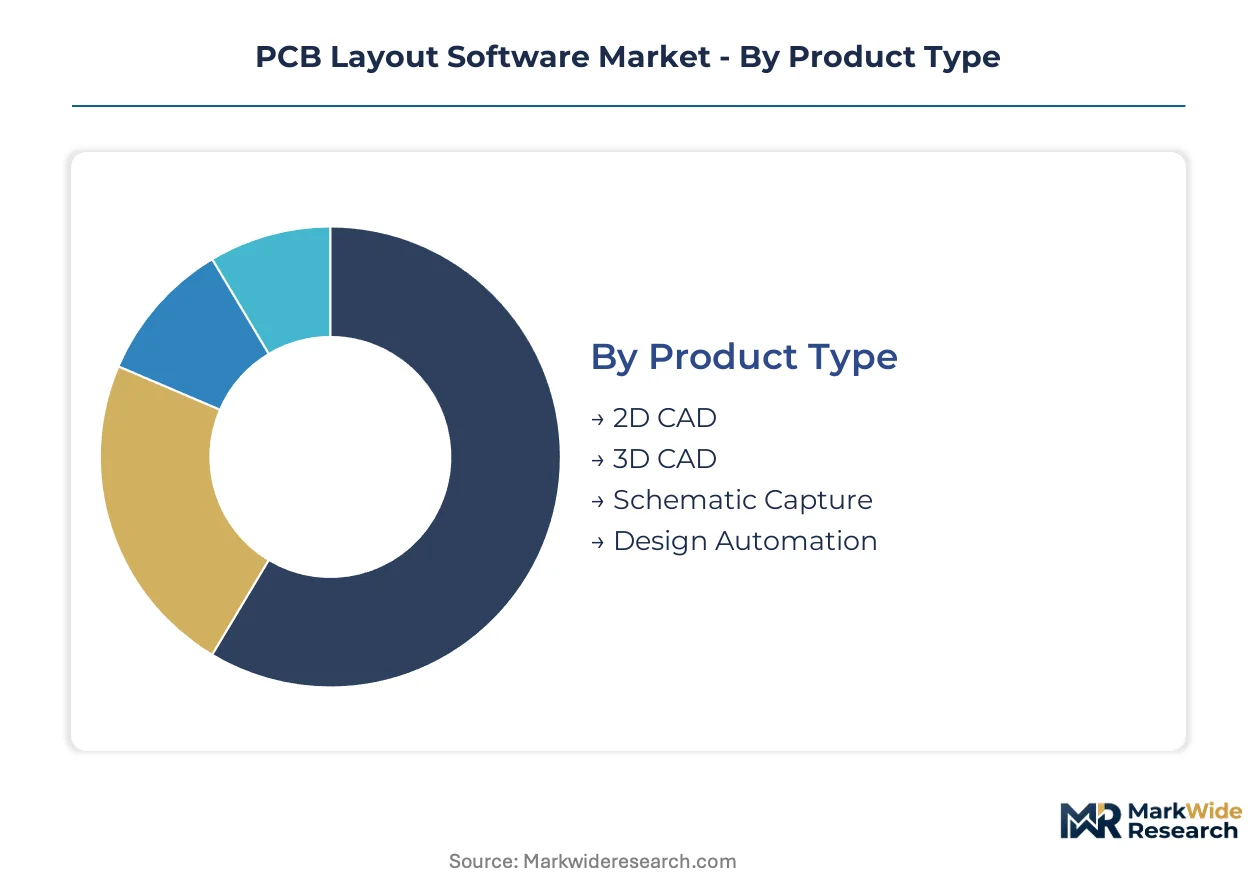
PCB layout software segments diverge sharply by technical capability versus cost accessibility. Procurement patterns cluster around deployment model and end-user sophistication rather than feature breadth alone.
Product Type:
Volume deployments favor 2D CAD and schematic capture tools, while premium spending concentrates in 3D CAD and design automation suites that integrate simulation engines.
- 2D CAD:Core planar routing and layer management tools handle standard multilayer boards without mechanical clearance validation. Demand concentrates among contract manufacturers in China's Pearl River Delta serving consumer electronics assembly, where cost-per-seat sensitivity overrides advanced feature requirements.
- 3D CAD:Mechanical-electrical co-design environments validate component clearances, thermal envelopes, and enclosure fit before prototyping. Aerospace contractors in Toulouse and Seattle drive premium adoption as pre-fabrication validation cuts iteration cycles for avionics systems.
- Schematic Capture:Circuit diagramming tools with symbol libraries and netlist generation for downstream layout.
- Design Automation:Constraint-driven autorouting and design rule checking engines for high-complexity boards.
Today's leader: 3D CAD. Tomorrow's challenger: Design Automation.
Application:
End-use differentiation separates high-reliability verticals with validation mandates from high-volume segments prioritizing throughput.
- Automotive:Battery management systems and ADAS modules require thermal-electromagnetic co-simulation embedded in layout workflows. Germany's Munich-Stuttgart corridor anchors investment as electrification compresses design cycles and mandates ISO 26262 functional safety documentation.
- Consumer Electronics:Smartphone and wearable OEMs prioritize autorouting speed and foundry DFM rule integration over simulation depth. Shenzhen and Dongguan design houses dominate procurement, leveraging high engineer counts to offset simpler toolsets.
- Telecommunication:Baseband and RF front-end designs for 5G infrastructure.
- Aerospace:Avionics and satellite systems with DO-254 hardware assurance and extended temperature qualification.
Automotive applications are climbing the fastest as electrification mandates reshape tool requirements.
Deployment:
Capital availability and data sovereignty concerns partition the market between cloud-adopting mid-tier houses and on-premise holdouts in regulated sectors.
- Cloud-Based:SaaS delivery eliminates server infrastructure while enabling elastic compute for simulation workloads. North American contract manufacturers serving aerospace prototyping contracts concentrate adoption where capital constraints meet intermittent high-performance computing needs.
- On-Premises:Perpetual licenses with local data retention satisfy ITAR export control and defense security requirements. US and European defense contractors maintain this model to air-gap design files from external infrastructure.
- Hybrid:Mixed deployment with sensitive IP on-premise and collaboration layers cloud-hosted.
- Open Source:Zero-license-cost entry points attracting university programs and startup ecosystems.
Cloud-Based deployment is gaining share fastest among mid-market houses, though On-Premises retains defense and medical device strongholds.
End User:
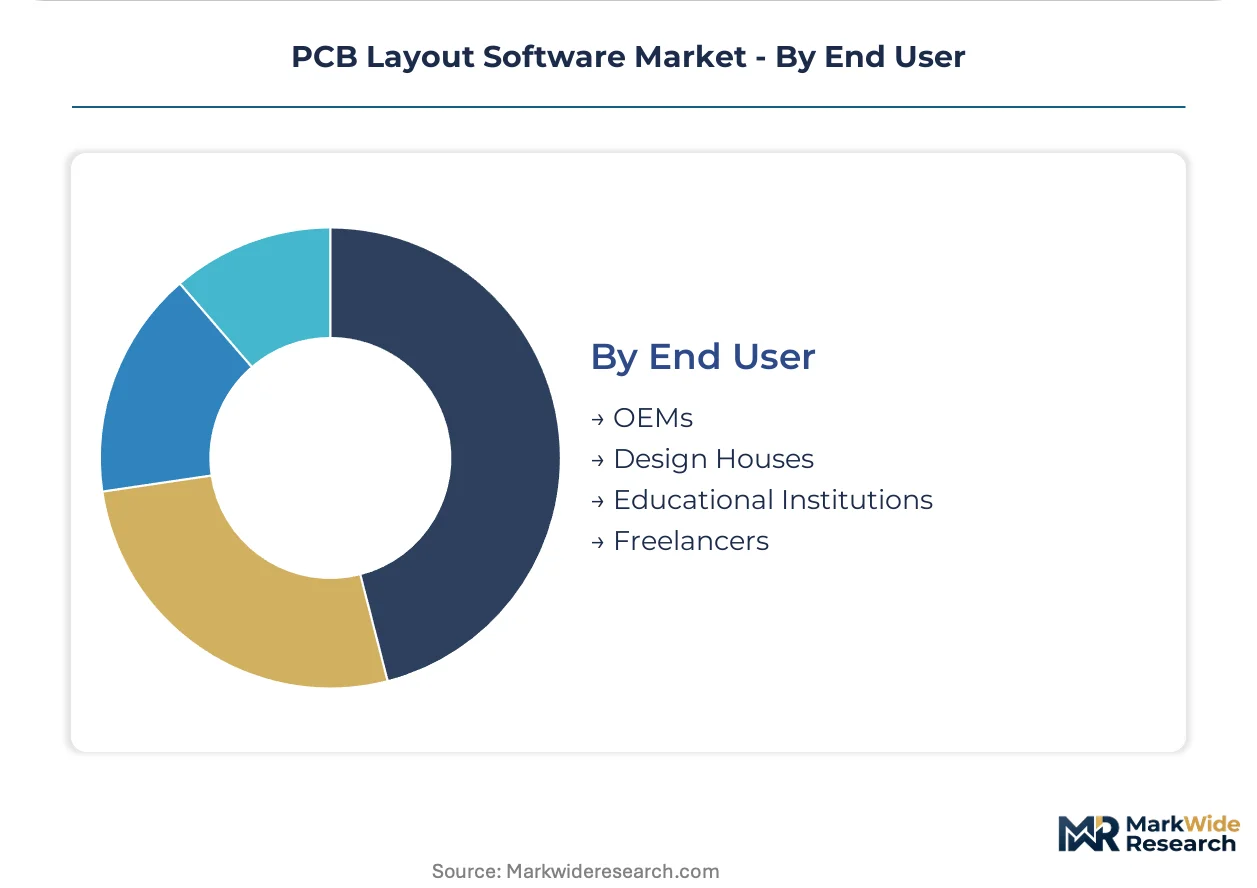
Organizational scale and technical staffing depth determine whether procurement favors integrated platforms or specialized toolchains.
- OEMs:Vertical integration demands enterprise-wide PLM integration and multi-site collaboration. Automotive OEMs in Japan and Germany standardize on suites with Teamcenter or equivalent backbone connectivity to synchronize electrical and mechanical release cycles.
- Design Houses:Independent engineering services firms serving multiple clients require flexible licensing and rapid tool onboarding. India's PLI scheme beneficiaries in Bengaluru and Hyderabad drive affordable tool demand as electronics manufacturing incentives expand local design capacity.
- Educational Institutions:University programs training next-generation engineers on accessible platforms.
- Freelancers:Independent contractors prioritizing low entry costs and community support over enterprise features.
Design Houses are expanding most quickly as outsourced electronics development accelerates, while OEMs retain the largest absolute spend per seat.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing PCB design tool procurement as compliance cost differentials widen between jurisdictions. Manufacturers migrate toward regions offering streamlined environmental certification pathways while maintaining proximity to end-market demand.
Germany
Automotive electrification and battery management system complexity are accelerating tool investments across Bavaria and Baden-Württemberg. The EU F-Gas Regulation and REACH substance restrictions mandate traceability modules that document material origins through supply chains. Munich-Stuttgart design houses now embed compliance workflows directly into release gates for ISO 26262 functional safety documentation.
United States
Aerospace contractors and defense electronics manufacturers sustain premium spending on 3D CAD validation suites. FDA 21 CFR Part 820 quality system requirements and ITAR export controls preserve on-premise deployment models with air-gapped infrastructure. Seattle and Greater Boston clusters concentrate procurement for avionics systems requiring DO-254 hardware assurance.
China
Consumer electronics OEMs in the Pearl River Delta prioritize autorouting speed and foundry DFM rule integration over simulation depth. MIIT standards and dual carbon goals are gradually tightening environmental disclosure requirements for export-bound manufacturers. Shenzhen and Dongguan design houses leverage high engineer counts to offset simpler toolsets in smartphone and wearable development.
Japan
Automotive tier-1 suppliers and precision electronics manufacturers anchor enterprise-wide PLM integration investments. METI industrial policy and JIS standards frameworks shape procurement specifications for multi-site collaboration platforms. Nagoya and Osaka industrial corridors concentrate demand as electrification compresses design cycles for hybrid and battery electric vehicle programs.
India
Electronics manufacturing incentives under the PLI scheme are expanding local design capacity in Bengaluru and Hyderabad. BIS standards alignment and DGFT import substitution policies favor affordable tool procurement for contract manufacturers. University programs and startup ecosystems increasingly adopt zero-license-cost entry points to train next-generation engineering talent.
PCB Layout Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native delivery and AI-assisted routing capabilities. The vendor base stratifies across three maturity tiers: integrated platform providers with PLM backbone connectivity, specialized EDA houses with deep simulation integration, and open-source alternatives competing on accessibility. Dominant competitive moves include strategic partnerships between layout tool vendors and mechanical CAD providers, plus technology licensing agreements that embed fabrication yield data into autorouting engines.
Within the integrated platform tier, Cadence Design Systems and Siemens exemplify enterprise-grade positioning through schematic-to-simulation workflow consolidation. Altium anchors the mid-market vector with unified design environments that attract independent design houses. KiCad occupies the accessibility tier, representing zero-license-cost alternatives that penetrate university programs and startup ecosystems where budget constraints override enterprise feature requirements.
| Leading Market Players |
|---|
| Altium |
| Cadence Design Systems |
| Siemens |
| Zuken |
| Autodesk |
| ANSYS |
| OrCAD |
| PADS |
| KiCad |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM mandates for ISO 26262 functional safety documentation are forcing PCB layout software vendors to embed compliance modules directly into standard offerings, compressing the premium that specialized toolchains once commanded and flattening pricing hierarchies across the mid-market.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and AI compute licensing is intensifying margin pressure on SaaS-tiered subscription models. Pricing stratifies across enterprise PLM-integrated suites, standalone professional licenses, and zero-license-cost open-source alternatives. Certification-grade validation tools for FDA 21 CFR Part 820 or DO-254 compliance sustain premium tiers. Price erosion runs through mid-market design automation seats as India's PLI scheme beneficiaries expand procurement volume. Freelancers and educational institutions exhibit highest price sensitivity; aerospace contractors with ITAR requirements demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from defense contractors and medical device OEMs mandate multi-vendor qualification for critical design tools, preventing single-platform lock-in despite proprietary format advantages. Software development concentrates in the United States, Germany, and Japan. Cloud delivery infrastructure draws from hyperscaler networks in North America and Europe. Single-source vulnerability centers on AI training data licensing from fabrication yield databases. Distribution runs through direct enterprise sales for OEMs, value-added resellers for design houses, and community repositories for open-source adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into sustained demand, with the EU F-Gas Regulation and REACH substance restrictions mandating traceability modules that embed compliance costs into standard procurement.
For Market Incumbents: Acquire specialized simulation engine assets to close thermal-electromagnetic co-simulation gaps before cloud-native entrants capture mid-market share. Defensive consolidation should prioritize PLM backbone connectivity investments that synchronize electrical and mechanical release cycles, neutralizing the threat from open-source alternatives gaining enterprise feature parity. For New Entrants and Emerging Players: Cloud-native deployment routes offer the fastest penetration vector into North American contract manufacturers serving aerospace prototyping contracts. White-space targets include India's PLI scheme beneficiaries in Bengaluru and Hyderabad requiring affordable tool procurement, and European design houses seeking REACH compliance automation without enterprise suite overhead. Freemium-to-subscription conversion models align with startup ecosystem budget constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native specialists possessing AI-assisted routing capabilities and elastic compute architectures. Long-term viability over the projection horizon favors vendors with embedded fabrication yield data partnerships and regulatory workflow automation. Signal to watch: automotive tier-1 supplier consolidation of battery management system design in-house versus outsourced to independent design houses.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Routing Engine Development | Machine learning models trained on fabrication yield data optimize trace geometries for manufacturability in automotive battery management systems. |
| PLM Backbone Integration Partnership | Deep Teamcenter or equivalent connectivity synchronizes electrical and mechanical release cycles for Japanese and German automotive OEMs. |
| Cloud-Native Platform Migration | SaaS delivery eliminates server capital expenditure while enabling elastic compute for simulation workloads among mid-market design houses. |
| Regulatory Compliance Module Expansion | Automated REACH substance screening and F-Gas documentation embed into release gates for European medical device and automotive segments. |
| Open-Source Community Ecosystem Investment | Unified support structures for KiCad and community extensions reduce enterprise adoption friction against proprietary alternatives. |
Research Methodology
Bottom-up automotive and aerospace electronics modeling reconciled against top-down EDA vendor shipment tracking forms the analytical core of this study. Primary interviews with PCB design managers, EDA procurement officers, semiconductor packaging engineers, and contract manufacturing executives were validated against secondary sources including SEC 10-K filings, MIIT industrial policy disclosures, and EU regulatory implementation guidance. Triangulation across these inputs ensures segmentation integrity.
Input-output matrices map deployment model adoption, end-user organizational scale, and regional regulatory cluster intensity across the projection horizon. Segmentation dimensions modeled include product type, application vertical, deployment architecture, and end-user sophistication tier. CAGRs derive from elasticity-calibrated penetration curves and technology substitution dynamics. Industry-specific forecast inputs incorporate automotive electrification content trajectories and cloud infrastructure capex cycles.
Automotive platform standardization delays, REACH enforcement variance across EU member states, and hyperscaler pricing volatility are the dominant revision risks to the outlook. Deviation in automotive electrification investment pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Test Data Management Market
Software & Services
IT Service Management Tools Market
Software & Services
Structured Data Management Software Market
Software & Services
Plant Design Software Market
Software & Services
Content Services Platforms Market
Software & Services
Non-Profit Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Sales Training Software Market
Software & Services
Sourcing Software Market
Software & Services
Multiexperience Development Platforms Market
Software & Services
CAD Modeling Software Market
Software & Services
Sales Gamification Software Market
Software & Services
Global Survey Software Market
Software & Services
Pharmacy Billing Software Market
Software & Services
Load Balancing Software Market
Software & Services
Software License Management (SLM) Market