
 North America Digital Marketing Software Market | 2026-2036
North America Digital Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Marketing Software Market Analytics
First-party data infrastructure is recalibrating budget allocation across the North America Digital Marketing Software Market as third-party cookie deprecation erodes legacy targeting economics. Adobe Inc leverages its Creative Cloud-to-Experience Cloud integration to sustain workflow lock-in among enterprise creative teams. Salesforce Inc anchors its competitive stance through deep CRM-data connectivity that bridges sales and marketing operations. HubSpot Inc specializes in mid-market inbound automation, occupying a distinct price-performance tier below enterprise suites.
North America Digital Marketing Software encompasses platforms that automate, measure, and optimize customer engagement across digital channels through algorithmic audience segmentation, real-time bidding protocols, and cross-channel attribution modeling. These systems process behavioral signals, transactional records, and predictive scores to orchestrate personalized messaging at scale. Cloud-based deployment leads structural investment due to elastic scaling and reduced IT overhead, while SaaS delivery concentrates recurring revenue pools among vendors with embedded workflow stickiness. Analytics functionality is maturing rapidly as AI-driven predictive models displace descriptive dashboards, shifting margin capture toward platforms with proprietary data science layers.
The Federal Trade Commission enforces truth-in-advertising standards that shape how platforms validate performance claims, while state attorneys general in California and New York apply GDPR-influenced privacy frameworks that restrict data retention and consent mechanisms. HIPAA boundaries limit health-sector marketing automation, creating compliance-driven product specialization among vendors serving pharmaceutical and insurance clients. Stakeholders must monitor the fragmentation of state privacy laws versus federal preemption efforts, as this regulatory trajectory will determine whether modular compliance tools or unified governance platforms capture the next wave of enterprise procurement.
Market Dynamics
First-party data infrastructure is recalibrating budget allocation across the North America Digital Marketing Software Market as third-party cookie deprecation erodes legacy targeting economics. Adobe Inc leverages its Creative Cloud-to-Experience Cloud integration to sustain workflow lock-in among enterprise creative teams. Salesforce Inc anchors its competitive stance through deep CRM-data connectivity that bridges sales and marketing operations. HubSpot Inc specializes in mid-market inbound automation, occupying a distinct price-performance tier below enterprise suites.
Growth Catalysts
- State Privacy Frameworks:The California Consumer Privacy Act and evolving state-level mandates in Virginia and Colorado compel enterprises to invest in compliant data governance architectures, expanding vendor addressable market for consent management and audit-ready infrastructure.
- Retail Media Networks:Walmart and Target's retail media platforms are pulling brand advertising spend into closed-loop measurement environments, creating demand for software that bridges off-site programmatic with on-site retail analytics.
- AI-Powered Creative Optimization:Generative AI tools for dynamic creative assembly are compressing production timelines from weeks to hours, enabling real-time personalization at scale for Fortune 500 marketing operations.
Market Restraints
- Data Localization Requirements:Canadian provincial privacy statutes and emerging US state laws are fragmenting cloud deployment architectures, forcing vendors to maintain region-segregated infrastructure that elevates operational complexity.
- Technical Talent Scarcity:The shortage of data engineers capable of implementing customer data platforms is extending implementation timelines and elevating professional services dependency for complex enterprise deployments.
- Identity Resolution Limitations:Cross-device graph accuracy degrades as deterministic signals diminish, compressing attribution confidence and forcing reliance on probabilistic modeling that increases media waste.
Strategic Opportunities
- Healthcare Marketing Automation:HIPAA-compliant campaign orchestration for pharmaceutical and insurance verticals remains underserved, with specialized vendors capturing premium pricing for consent and audit trail capabilities.
- Connected TV Integration:The convergence of programmatic digital video with linear television buying systems is creating white space for platforms that unify frequency capping and reach optimization across streaming and broadcast inventory.
- Mexico Market Expansion:Underpenetrated mid-market demand in Mexico's e-commerce sector presents first-mover advantage for SaaS providers with Spanish-language support and local payment integration.
Industry Challenges
- Legacy System Integration:Enterprise marketing operations require costly API development to connect modern orchestration platforms with decades-old on-premise data warehouses and proprietary CRM instances.
- Attribution Model Standardization:The absence of industry-wide multi-touch attribution protocols forces vendors to maintain multiple measurement frameworks, elevating product complexity and customer confusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Marketing Software Market |
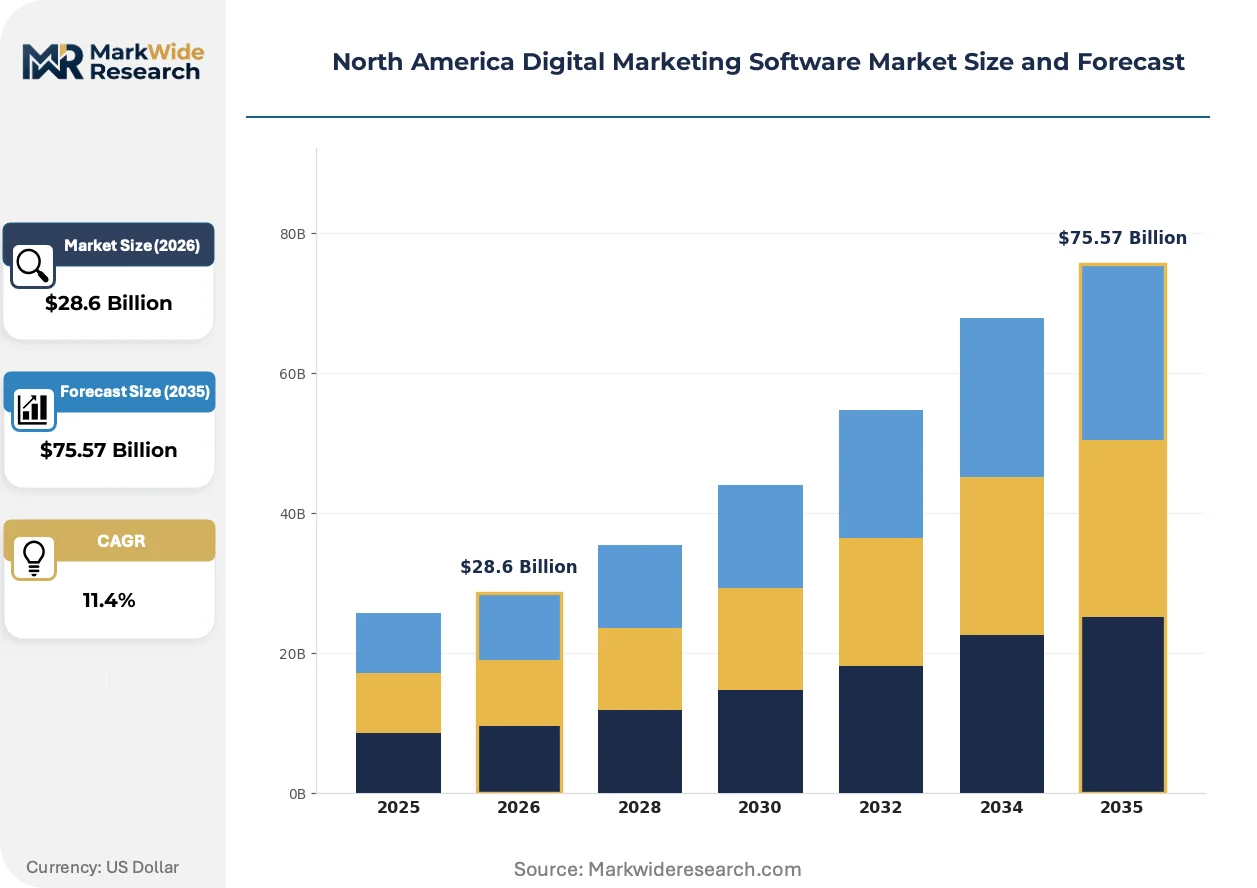
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Email Marketing, Social Media Management, Content Marketing, Search Engine Optimization Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Small Businesses, Enterprises, Agencies, E-commerce Functionality: Analytics, Automation, CRM Integration, Campaign Management |
| Companies Covered | Adobe Inc, Salesforce Inc, HubSpot Inc, Oracle Corp, Microsoft Corp, International Business Machines Corp, SAP SE, Hewlett Packard Enterprise Co, SAS Institute Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Marketing Software Market Evolving Landscape
Algorithmic decision-making is displacing rules-based campaign management across North American marketing operations, compressing the gap between data signal and creative execution. This shift is redistributing competitive advantage toward platforms with proprietary machine learning layers and first-party data scale.
Customer data platforms are consolidating point-solution functionality across tag management, identity resolution, and audience segmentation into unified data layers. Mid-market brands are adopting these consolidated architectures to reduce vendor fragmentation and simplify compliance auditing. The structural consequence is margin compression for standalone point solutions as platform bundling accelerates.
The Federal Trade Commission's truth-in-advertising enforcement is intensifying scrutiny of AI-generated performance claims and influencer disclosure protocols. This regulatory pressure is forcing platforms to embed automated compliance checking into campaign workflows, particularly affecting social media management and affiliate marketing software categories. Vendors are responding by acquiring legal-tech capabilities or partnering with specialized disclosure monitoring services.
Brand procurement teams are consolidating martech spending under centralized IT governance, displacing decentralized shadow-IT purchasing that dominated the 2015-2020 expansion. This behavioral shift elevates security certification and procurement integration requirements, favoring established vendors with SOC 2 Type II and FedRAMP credentials. The transition is most visible among financial services and healthcare enterprises in the Northeast and California markets.
North America Digital Marketing Software Market Segmentation
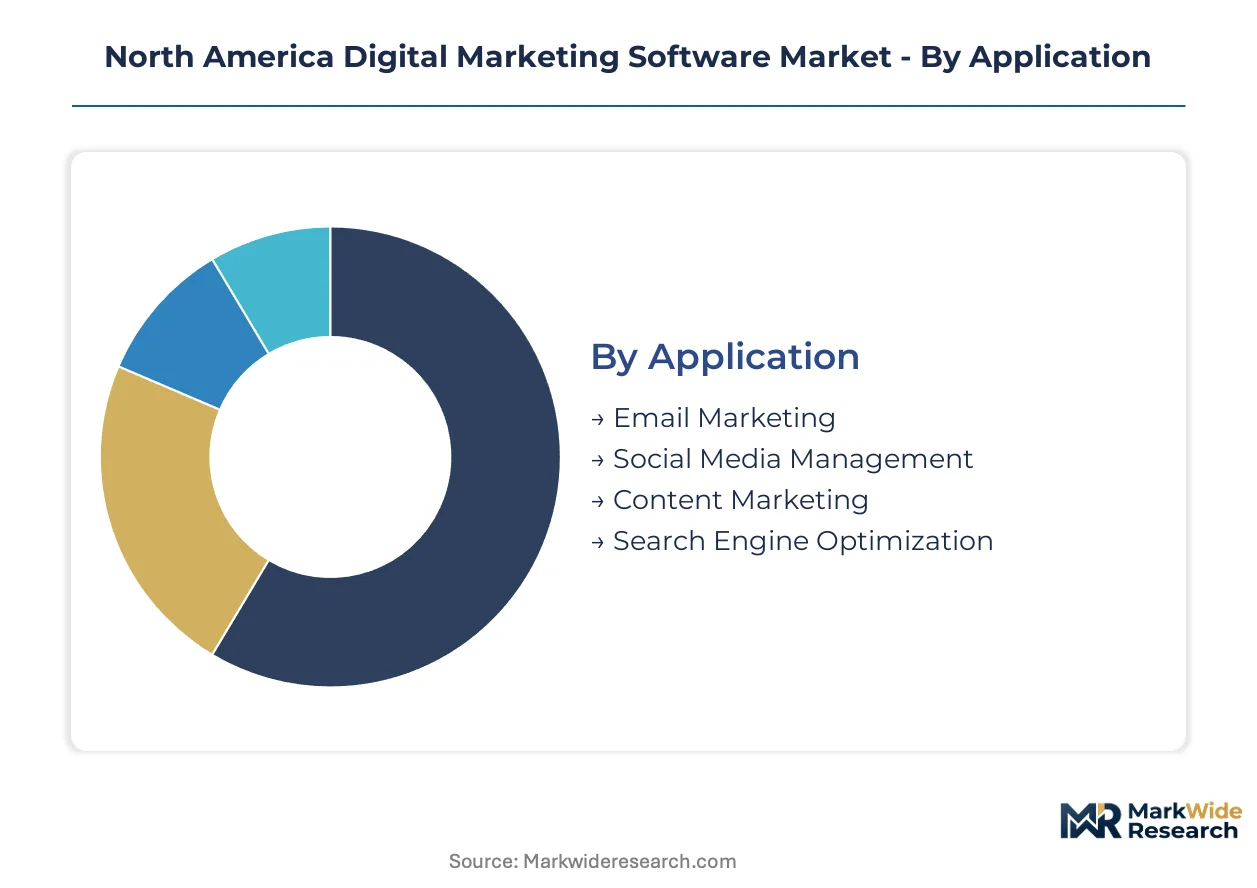
Segmentation in the North America Digital Marketing Software Market reveals how vendor R&D investment, compliance architecture, and customer procurement authority distribute across functional and deployment dimensions. Distinct operational requirements between California-headquartered enterprises and Texas-based mid-market agencies create divergent product specifications within each category.
Application:
Supply concentration in email marketing platforms has consolidated around vendors with deliverability infrastructure spanning AWS East and West regions.
- Email Marketing:Transactional and promotional campaign orchestration with real-time engagement scoring. Fortune 500 retailers in the US Northeast prioritize platforms with automated list hygiene and CAN-SPAM compliance workflows.
- Social Media Management:Cross-platform publishing, listening, and paid amplification coordination. California-based consumer brands drive demand for TikTok and Instagram Reels native scheduling with FTC disclosure automation.
- Content Marketing:Editorial calendar management and asset versioning for multi-channel distribution.
- Search Engine Optimization:Technical audit, rank tracking, and content optimization recommendation engines.
Email Marketing absorbs the bulk of installed capacity; Social Media Management is expanding most quickly.
Deployment:
Cost tier stratification separates enterprise multi-tenant cloud contracts from mid-market SaaS subscriptions with per-seat pricing.
- Cloud-Based:Elastic compute environments with region-specific data residency controls. Canadian provincial privacy statutes compel vendors to maintain Toronto and Montreal availability zones.
- SaaS:Recurring subscription delivery with embedded workflow automation and API marketplaces. US healthcare marketing teams require Business Associate Agreements for HIPAA-aligned SaaS procurement.
- On-Premises:Licensed software deployed within customer-controlled data centers.
- Hybrid:Split architectures with sensitive data on-premise and compute workloads in cloud environments.
Cloud-Based deployments command the majority of new contract value; SaaS is climbing the fastest among mid-market adopters.
End User:
Customer type determines feature depth, with enterprise procurement mandating SOC 2 Type II certification that filters vendor eligibility.
- Enterprises:Multi-divisional marketing operations with centralized governance and custom integration requirements. New York financial services firms prioritize platforms with FedRAMP authorization and granular role-based access controls.
- E-commerce:Direct-to-consumer brands with real-time inventory-linked campaign triggers. Shopify-integrated merchants in Ontario and California drive demand for automated abandoned-cart recovery sequences.
- Agencies:Multi-client campaign management with white-label reporting and consolidated billing.
- Small Businesses:Self-service platforms with template-driven campaign creation and limited technical configuration.
Enterprises absorb the bulk of installed capacity; E-commerce is gaining share fastest.
Functionality:
Margin capture concentrates in analytics layers where proprietary machine learning models differentiate platform value.
- Analytics:Attribution modeling, predictive scoring, and cross-channel performance dashboards. US retail media networks require platforms that reconcile off-site programmatic with on-site Walmart and Target closed-loop measurement.
- Automation:Trigger-based workflow orchestration and dynamic content assembly. Virginia and Colorado privacy frameworks compel vendors to embed consent-state-aware automation logic.
- CRM Integration:Bidirectional data synchronization with Salesforce, HubSpot, and Microsoft Dynamics instances.
- Campaign Management:Unified planning, execution, and optimization across digital channels.
Analytics absorbs the bulk of installed capacity; Automation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park in North Carolina and Austin's tech corridor concentrate SaaS development talent, drawing venture deployment toward these incentive-rich zones. State-level digital services tax regimes and data residency mandates reshape where vendors locate primary infrastructure.
United States
Fortune 500 marketing operations in New York and California drive enterprise software procurement at scale. The FTC enforces truth-in-advertising standards that compel platforms to validate AI-generated performance claims before deployment. Seattle and San Francisco Bay Area clusters host the densest concentration of marketing automation engineering talent.
California
The California Consumer Privacy Act mandates granular consent management and audit-ready data governance architectures. State attorneys general apply GDPR-influenced frameworks that restrict cross-border data flows and retention periods. Los Angeles and San Francisco marketing technology vendors embed automated compliance checking into campaign workflows.
Texas
Mid-market agencies in Austin and Dallas-Fort Worth expand adoption of template-driven campaign creation tools. State franchise tax incentives for software development reduce operational costs for SaaS providers establishing secondary headquarters. Houston's energy sector marketing teams prioritize HIPAA-aligned procurement for pharmaceutical client services.
New York
Financial services marketing operations in Manhattan require FedRAMP authorization and granular role-based access controls. State cybersecurity regulations mandate encryption standards for customer data platforms handling banking client information. Brooklyn and Queens emerging tech clusters attract CDP implementation specialists serving Northeast enterprises.
Canada
Provincial privacy statutes in Ontario and Quebec fragment cloud deployment architectures with data localization requirements. Health Canada guidelines limit health-sector marketing automation, creating compliance-driven specialization among vendors serving pharmaceutical clients. Toronto and Montreal availability zones concentrate vendor infrastructure investment to satisfy residency mandates.
North America Digital Marketing Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise suites consolidating procurement under centralized IT governance while mid-market SaaS fragments across point solutions. The vendor landscape organizes into three tiers: integrated platform providers with workflow lock-in, standalone automation specialists with price-performance advantages, and legacy infrastructure vendors with installed-base maintenance revenue. Dominant competitive moves include M&A to acquire consent management capabilities and strategic partnerships to embed generative AI creative tools.
Within the integrated platform tier, Adobe Inc and Salesforce Inc exemplify contrasting approaches to enterprise retention. Adobe leverages Creative Cloud-to-Experience Cloud integration to sustain workflow lock-in among creative teams. Salesforce anchors positioning through CRM-data connectivity bridging sales and marketing operations. HubSpot Inc occupies the mid-market inbound automation tier with distinct price-performance positioning below enterprise suites.
| Leading Market Players |
|---|
| Adobe Inc |
| Salesforce Inc |
| HubSpot Inc |
| Oracle Corp |
| Microsoft Corp |
| International Business Machines Corp |
| SAP SE |
| Hewlett Packard Enterprise Co |
| SAS Institute Inc |
| Others |
Value Network & Pricing Analysis
Cloud compute capacity from AWS East and West regions feeds into tiered SaaS subscription pricing, with latency-optimized instances commanding premium positioning for Fortune 500 buyers while standard multi-tenant deployments serve mid-market segments.
Pricing Analysis
Short lead-time provisioning for dedicated cloud instances carries 30-40% pricing premiums over standard SaaS tiers with shared infrastructure. Enterprise procurement teams negotiate three-year contracts with volume-scaled discounts, while mid-market adopters face per-seat pricing with limited customization. Price differentiation hinges on SOC 2 Type II certification status and FedRAMP authorization tier. Pricing pressure stems from hyperscaler commoditization of base compute, compressing margins for vendors without proprietary data science layers. Small business segments exhibit highest price sensitivity, prioritizing template-driven self-service over feature depth.
Supply Chain Analysis
Dual-sourcing requirements from enterprise procurement mandate qualified secondary infrastructure providers alongside primary hyperscaler relationships. Cloud infrastructure concentrates in United States, Canada, and Mexico data center zones. Raw material dependencies span silicon for server hardware, lithium for backup power systems, and rare earth elements for networking equipment. Supply chain risk centers on single-source vulnerability for specialized AI accelerator chips. Distribution runs through direct enterprise sales teams, channel partners, and self-service digital marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where CCPA and emerging state privacy frameworks erect barrier-to-entry moats favoring vendors with pre-built consent management and audit-ready governance architectures.
For Market Incumbents: To counter margin compression from hyperscaler infrastructure commoditization, deepen proprietary machine learning differentiation through first-party data scale advantages. Prioritize M&A targeting consent management specialists to consolidate compliance tooling under unified platforms. Fortify workflow lock-in by expanding Creative Cloud-to-Experience Cloud integration depth for enterprise creative teams.
For New Entrants and Emerging Players: Enter via HIPAA-compliant healthcare marketing automation verticals where specialized audit trail capabilities command premium positioning. Target Mexico's underpenetrated mid-market e-commerce sector with Spanish-language localization and local payment integration. Pursue channel partnerships with Shopify ecosystem developers to accelerate merchant acquisition velocity.
For Investors and Strategic Acquirers: FTC enforcement actions against AI-generated performance claims are the leading indicator that automated compliance checking capabilities will capture outsized valuation premiums. Five-to-ten year viability favors platforms with embedded legal-tech layers bridging marketing operations and regulatory monitoring. Acquisition targets should demonstrate FedRAMP authorization progress and established healthcare vertical penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Consent Management Platform Acquisition | CCPA and Virginia CDPA compliance mandates expand addressable market for audit-ready data governance tooling. |
| Healthcare Vertical Specialization | HIPAA-aligned campaign orchestration captures pharmaceutical and insurance procurement with premium pricing power. |
| Retail Media Network Integration | Walmart and Target closed-loop measurement bridges off-site programmatic with on-site analytics for brand advertisers. |
| Generative AI Creative Partnership | Dynamic creative assembly compresses production timelines from weeks to hours for Fortune 500 marketing operations. |
| Mexico Market Localization | Spanish-language support and local payment integration unlock underpenetrated mid-market e-commerce demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with chief marketing officers, IT procurement officers, platform engineers, and integration specialists validated demand-side assumptions. Secondary sources encompassed FTC enforcement actions, state attorney general privacy filings, SEC 10-K disclosures from publicly traded vendors, and hyperscaler capex reports. Bottom-up segment sizing triangulated against top-down market aggregation.
Granularity-level modeling deployed deployment mode, organization size, vertical industry, and integration complexity as core segmentation dimensions. CAGRs derived from logistic adoption curves fitted to historical penetration data and projected technology substitution rates across the analysis window. Forecast inputs incorporated cloud infrastructure expansion timelines, state privacy law enactment schedules, and retail media network spend migration patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated federal privacy preemption or prolonged third-party cookie deprecation delays. Deviation in FTC enforcement intensity against AI-generated claims would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Relational Database Management System Market
Software & Services
Workshop Management Software Market
Software & Services
Collaboration Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Global Club Management Software Market
Software & Services
Global UIUX Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Lifecycle Management Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Online Lottery Software Market
Software & Services
Android Emulator Market
Software & Services
Production Optimization Software Market
Software & Services
Torque Software Market