
 Poland IT Software and Service Market | 2026-2036
Poland IT Software and Service Market Size, Share, and Industry Trends Forecast 2026-2036
Poland IT Software and Service Market Analytics
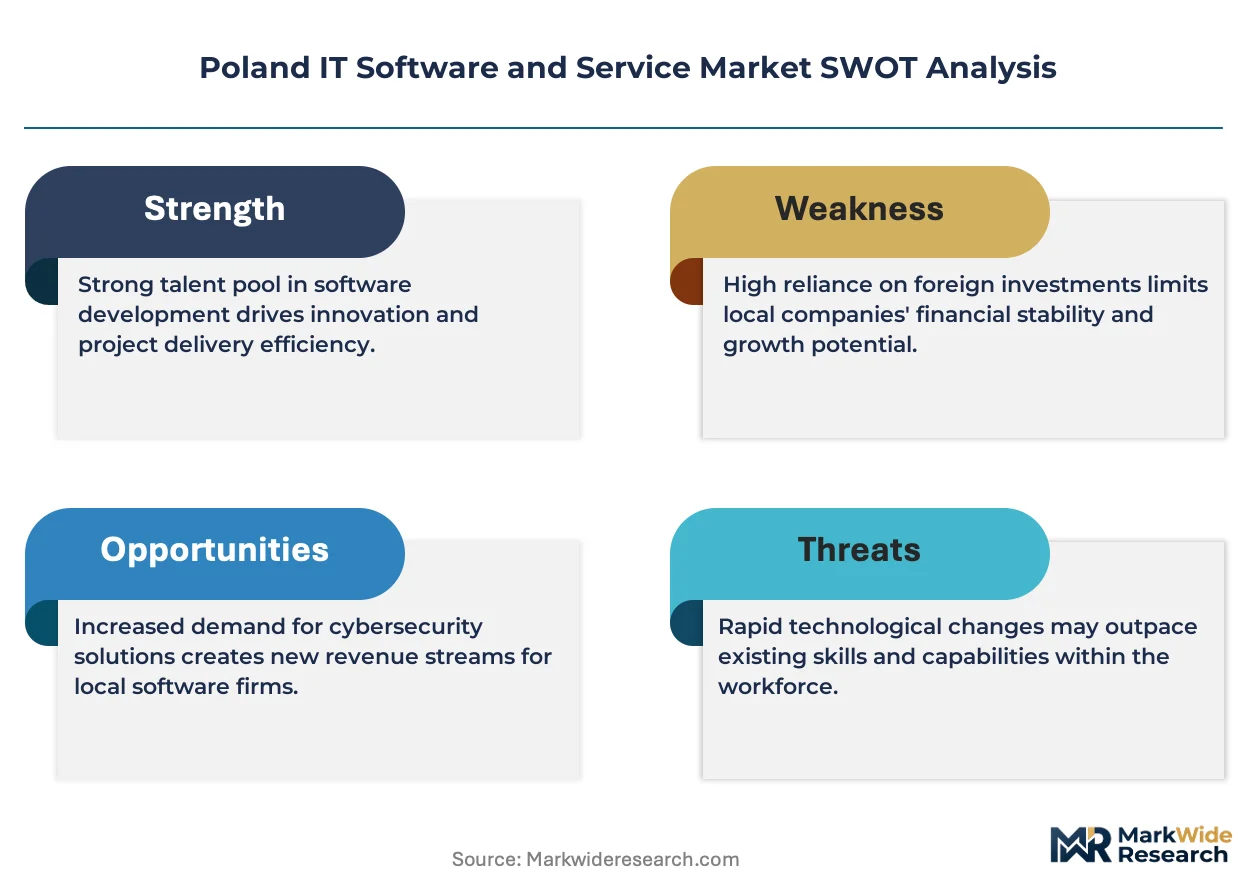
EU Green Deal reporting obligations under CSRD is pivoting enterprise procurement toward carbon-accounting software stacks. Future Processing anchors its competitive position through deep specialization in regulated industries including banking and healthcare. STX Next dominates the Python-centric development niche, while Spyrosoft extends its footprint across embedded systems and automotive software engineering.
Poland IT Software and Service encompasses the design, development, integration, and maintenance of software applications alongside advisory and managed infrastructure services, typically delivered through agile methodologies with two-week sprint cycles and cloud-native architectures. Enterprise Software and Cloud Solutions constitute the core revenue base, though Cybersecurity Services captures expanding margin pools as NIS2 transposition tightens liability frameworks. Hybrid Cloud deployment models attract mid-market manufacturing firms seeking to retain sensitive operational data on-premises while bursting analytics workloads to public infrastructure.
Poland's Office of Competition and Consumer Protection enforces digital platform fairness rules, while BIS certification requirements shape software quality benchmarks for government contracts. The EU AI Act risk-classification system forces healthcare providers and financial institutions to revalidate algorithmic tools before deployment. Stakeholders must monitor how EU cybersecurity certification schemes fragment procurement eligibility across Polish public-sector tenders.
Market Dynamics
EU AI Act risk-classification mandates are forcing Polish financial institutions and healthcare providers to revalidate algorithmic decision systems before deployment, compressing procurement timelines and elevating compliance spend.
Growth Catalysts
- NIS2 transposition:Poland's cybersecurity liability framework tightens, compelling mid-market manufacturers to outsource security operations to specialized service providers.
- Warsaw-Kraków corridor concentration:Developer talent pools and enterprise headquarters cluster along this axis, reducing recruitment friction for agile delivery teams.
- CSRD carbon-accounting mandates:Enterprise procurement pivots toward software stacks that automate Scope 3 emissions tracking and EU Green Deal reporting.
Market Restraints
- Specialized talent scarcity:Cloud-native architecture skills command premium wages, inflating project delivery costs for boutique development houses.
- EU cybersecurity certification fragmentation:Divergent national implementation timelines for ENISA schemes create eligibility uncertainty in Polish public-sector tenders.
- Hybrid cloud complexity:Mid-market manufacturing firms struggle to integrate on-premises operational data with public infrastructure bursting requirements.
Strategic Opportunities
- Łódź and Wrocław sub-markets:Secondary cities offer lower cost bases for delivery centers while maintaining proximity to Warsaw enterprise clients.
- Embedded systems convergence:Automotive software engineering expertise in Silesia intersects with industrial IoT demand from German OEM supply chains.
- Algorithmic audit services:EU AI Act enforcement creates white space for independent validation of high-risk AI systems in Polish banking.
Industry Challenges
- Agile certification bottlenecks:Two-week sprint methodologies require continuous retraining as frameworks evolve, straining HR development budgets.
- Legacy system integration friction:Core banking platforms built on COBOL architectures resist API-native connectivity, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland IT Software and Service Market |
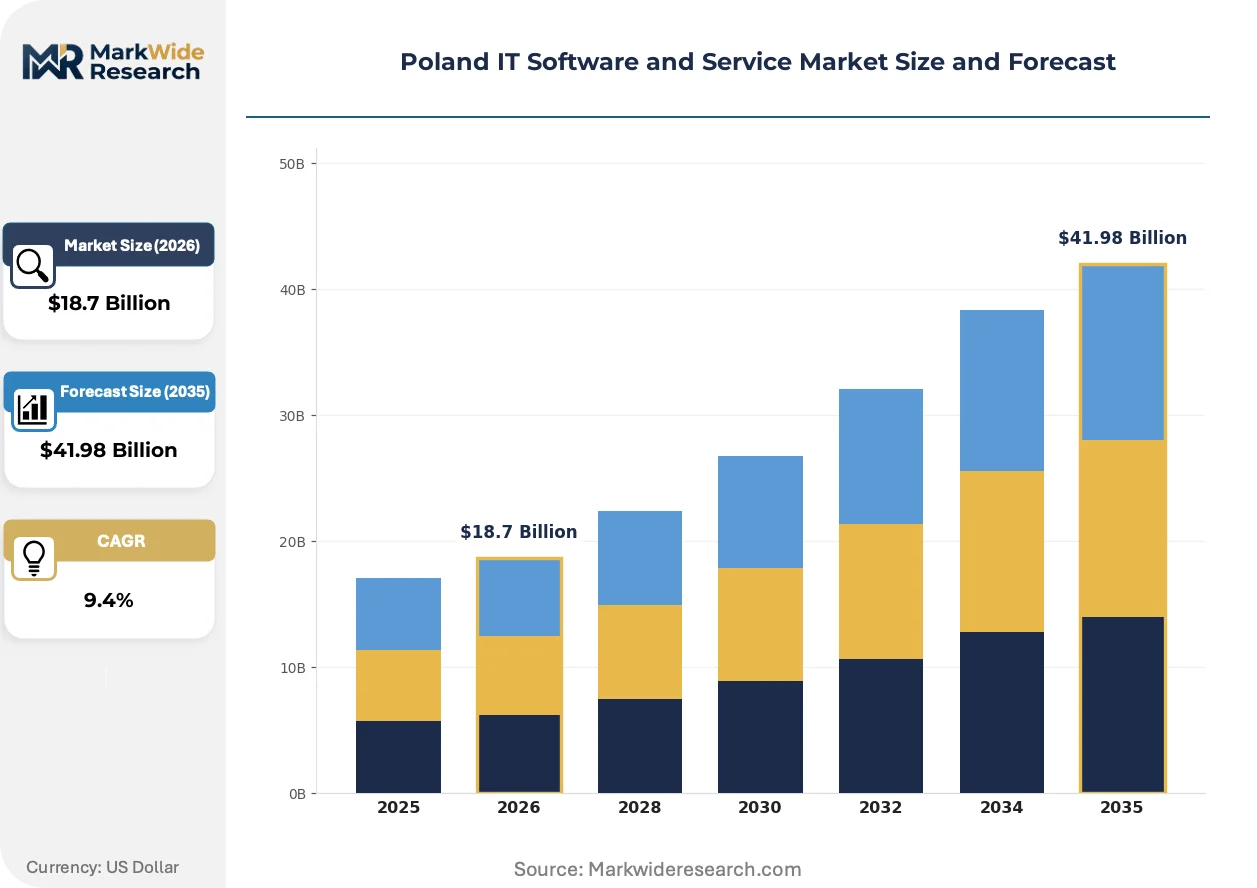
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Software, Cloud Solutions, Cybersecurity Services, IT Consulting Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud End User: Healthcare Providers, Financial Institutions, Manufacturing Firms, Retail Chains Technology: Artificial Intelligence, Machine Learning, Blockchain, IoT |
| Companies Covered | Netguru, Scalo, TTMS, 10Clouds, The Software House, Future Processing, STX Next, Miquido, Spyrosoft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland IT Software and Service Market Evolving Landscape
Cloud-native architectures are fragmenting monolithic enterprise applications into composable services, while regulatory pressure accelerates automation of compliance workflows across Polish regulated industries.
Microservices architecture is modularizing enterprise software delivery. Polish banking groups decompose core banking platforms into containerized functions to accelerate feature deployment. This structural shift compresses vendor lock-in durations and enables multi-cloud portability.
EU AI Act enforcement is redrawing procurement criteria for algorithmic systems. Healthcare providers in Poland must document risk-management protocols before deploying diagnostic AI. Financial institutions are pre-emptively engaging notified bodies to secure conformity assessments.
Subscription-based managed services are displacing perpetual license models in mid-market manufacturing. Polish firms in the Warsaw-Kraków corridor now prefer outcome-aligned contracts with infrastructure-as-code delivery. This preference shift concentrates vendor selection on operational excellence metrics rather than upfront functionality comparisons.
Poland IT Software and Service Market Segmentation
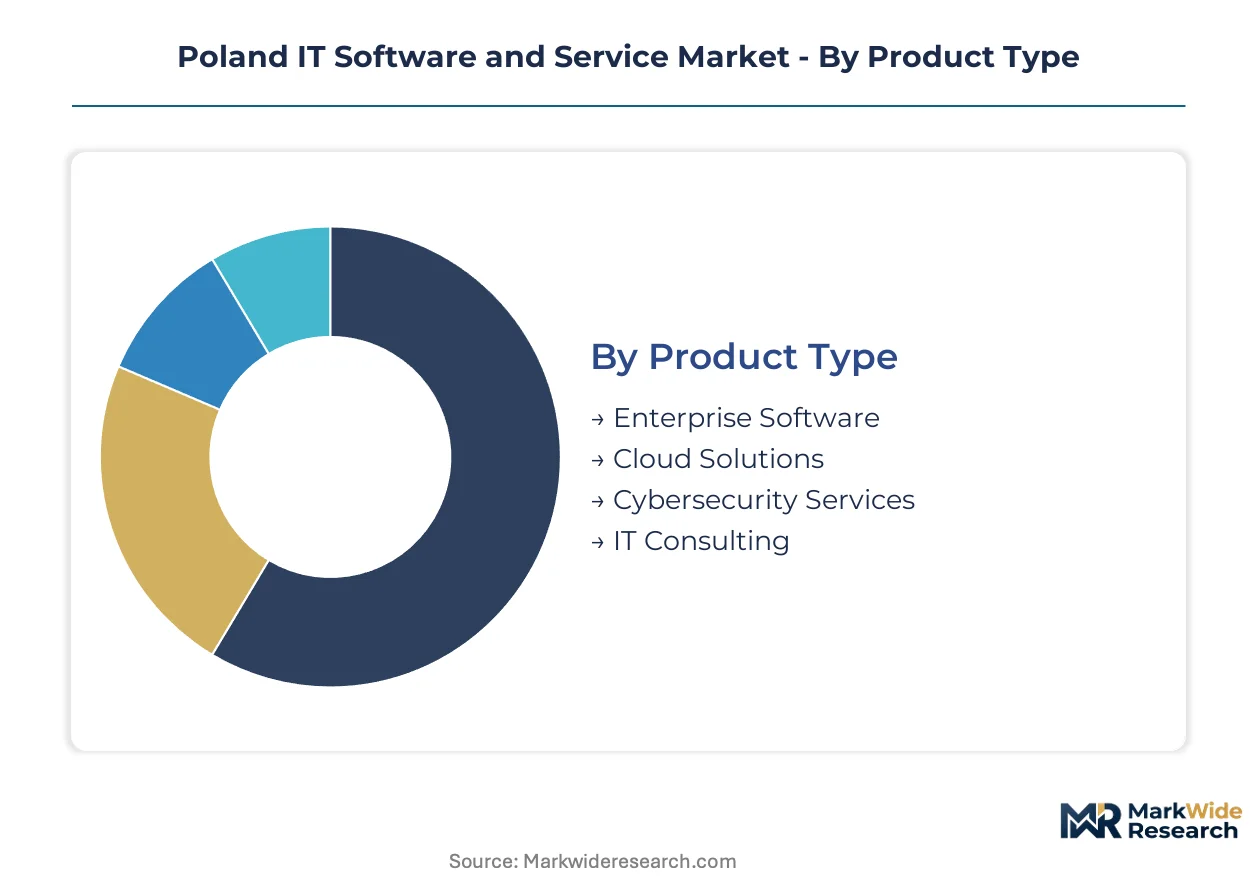
Polish enterprise procurement teams evaluate IT services through four distinct lenses: solution architecture, infrastructure topology, vertical compliance requirements, and emerging technology integration. These segmentation dimensions shape vendor selection criteria and contract structures across the Warsaw-Kraków corridor.
Product Type:
Enterprise buyers prioritize total cost of ownership and regulatory alignment when selecting solution categories.
- Enterprise Software:Core systems span ERP, CRM, and SCM platforms with modular licensing structures. Polish banking groups drive demand in this segment as BIS certification requirements elevate quality benchmarks for government contracts.
- Cloud Solutions:Infrastructure-as-code delivery models dominate mid-market manufacturing procurement. The CSRD carbon-accounting mandate accelerates migration to energy-efficient hyperscaler regions serving Polish enterprise clients.
- Cybersecurity Services:Managed detection and response offerings capture expanding margin pools as NIS2 transposition tightens liability frameworks for critical infrastructure operators.
- IT Consulting:Advisory engagements concentrate on agile transformation and legacy modernization for COBOL-era banking platforms.
Volume sits with Enterprise Software; growth tilts toward Cybersecurity Services.
Deployment Model:
Infrastructure decisions reflect data sovereignty requirements and workload sensitivity patterns across regulated industries.
- On-Premises:Retained for core banking ledger systems and classified government workloads. Polish financial institutions maintain captive infrastructure to satisfy EU supervisory expectations for operational resilience.
- Public Cloud:Analytics bursting and development environments leverage hyperscaler economies. Manufacturing firms in Silesia deploy public infrastructure for non-sensitive simulation workloads.
- Private Cloud:Single-tenant virtualized environments serve healthcare providers managing patient diagnostic archives under GDPR constraints.
- Hybrid Cloud:Integrated on-premises and public infrastructure supports manufacturing operational data with elastic analytics capacity. Mid-market firms struggle with integration complexity despite strategic preference.
Hybrid Cloud commands the largest project pipeline; Public Cloud exhibits the steepest expansion trajectory.
End User:
Vertical-specific compliance burdens and digital maturity gaps create divergent procurement velocities.
- Healthcare Providers:Diagnostic AI deployment accelerates under EU AI Act risk-classification mandates. Polish hospitals revalidate algorithmic tools before procurement clearance.
- Financial Institutions:Digital platform budgets expand to meet ECB supervisory expectations for operational resilience. Algorithmic audit services emerge as a discrete procurement category.
- Manufacturing Firms:Industrial IoT demand from German OEM supply chains intersects with embedded systems expertise in Silesia. Subscription-based managed services displace perpetual licenses.
- Retail Chains:Omnichannel platform investments concentrate in the Warsaw-Kraków corridor near developer talent pools.
Financial Institutions anchor current spending; Healthcare Providers show the fastest adoption acceleration.
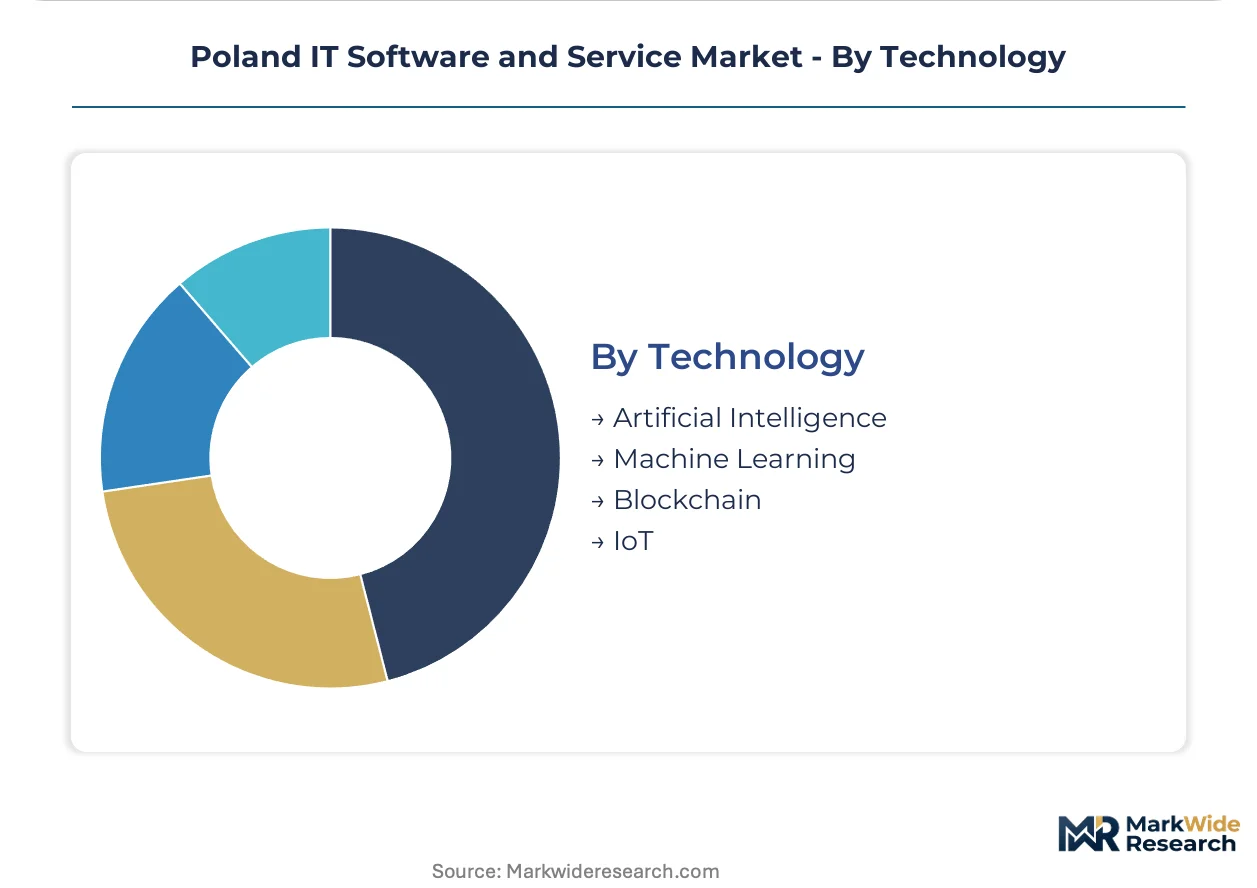
Technology:
Integration complexity and skills scarcity determine which emerging technologies penetrate Polish enterprise environments.
- Artificial Intelligence:High-risk system deployments require notified body conformity assessments under EU AI Act enforcement. Banking and healthcare dominate validated use cases.
- Machine Learning:Predictive maintenance models serve manufacturing operational optimization. Cloud-native MLOps pipelines reduce deployment friction for mid-market firms.
- Blockchain:Supply chain traceability pilots attract automotive software engineering investment. Limited production deployment outside proof-of-concept stages.
- IoT:Sensor networks and edge computing layers support smart factory initiatives. German OEM supply chain requirements drive specification standards.
Machine Learning delivers the broadest deployment base; Artificial Intelligence shows the most concentrated regulatory investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw anchors Poland's IT software and service concentration through the Warsaw-Kraków corridor, where developer talent pools and enterprise headquarters cluster to reduce recruitment friction for agile delivery teams.
Masovian Voivodeship
Warsaw's financial services sector drives enterprise software procurement as Polish banking groups expand digital platform budgets to meet ECB supervisory expectations for operational resilience. The EU AI Act risk-classification system forces financial institutions to revalidate algorithmic decision systems before deployment, compressing procurement timelines. The capital's concentration of fintech headquarters and regulatory expertise positions it as the primary demand center for compliance-heavy IT services.
Lesser Poland Voivodeship
Kraków's technology hub attracts cloud solutions investment from mid-market manufacturing firms seeking hybrid infrastructure deployment. GDPR constraints and data sovereignty requirements push healthcare providers toward private cloud architectures for patient diagnostic archives. The city's technical universities feed specialized developer pipelines into embedded systems and automotive software engineering clusters.
Silesian Voivodeship
Industrial IoT demand from German OEM supply chains intersects with embedded systems expertise concentrated in Katowice and surrounding manufacturing zones. NIS2 transposition tightens cybersecurity liability frameworks for critical infrastructure operators, compelling manufacturers to outsource security operations. Subscription-based managed services displace perpetual license models as Polish firms prefer outcome-aligned contracts with infrastructure-as-code delivery.
Lower Silesian Voivodeship
Wrocław's secondary market position offers lower cost bases for delivery centers while maintaining proximity to Warsaw enterprise clients. CSRD carbon-accounting mandates pivot procurement toward software stacks that automate Scope 3 emissions tracking and EU Green Deal reporting. The city's emerging technology parks attract machine learning operations pipelines serving manufacturing operational optimization.
Łódź Voivodeship
Łódź sub-market expansion targets mid-tier enterprises seeking reduced service delivery costs without sacrificing corridor connectivity. BIS certification requirements shape software quality benchmarks for government contracts, elevating compliance spend for public-sector tender participants. The city's logistics and retail technology clusters drive omnichannel platform investments near Warsaw-Kraków developer talent pools.
Poland IT Software and Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specialization depth and regulatory compliance capabilities. The vendor base organizes into three tiers: global systems integrators capturing transformation programs, mid-cap Polish specialists dominating vertical niches, and boutique development houses competing on agile velocity. Strategic archetypes include banking-focused compliance specialists, Python-centric development pure-plays, and embedded systems engineers serving automotive supply chains. Competitive moves concentrate on vertical specialization through industry-specific certification acquisition and geographic expansion into secondary Polish cities.
Within the banking and healthcare specialization tier, Future Processing anchors competitive positioning through deep regulated industry expertise. STX Next occupies a distinctive position as the dominant Python-centric development specialist. Spyrosoft exemplifies the embedded systems convergence archetype, extending capabilities across automotive software engineering and industrial IoT demand channels from Silesian delivery centers. These three entities represent the primary competitive anchors within Poland's IT software and service vendor landscape.
| Leading Market Players |
|---|
| Netguru |
| Scalo |
| TTMS |
| 10Clouds |
| The Software House |
| Future Processing |
| STX Next |
| Miquido |
| Spyrosoft |
| Others |
Value Network & Pricing Analysis
CSRD carbon-accounting mandates are compressing procurement timelines for energy-efficient cloud infrastructure, forcing Polish service providers to absorb hyperscaler cost premiums or risk losing Warsaw-Kraków corridor contracts to certified competitors with lower operational footprints.
Pricing Analysis
Outcome-aligned subscription contracts anchor value-based pricing for mid-market manufacturing clients. Three-tier pricing structure across premium, standard, and economy levels stratifies by ENISA cybersecurity certification grade and vertical specialization depth. Cost compression in economy-tier project delivery is intensifying because boutique development houses compete on agile velocity without compliance overhead. Financial institutions show least price sensitivity due to ECB supervisory mandates; logistics firms in Łódź sub-markets exhibit highest sensitivity.
Supply Chain Analysis
ENISA certification gating restricts vendor eligibility for Polish public-sector tenders, fragmenting procurement pools across divergent national implementation timelines. Talent supply concentrates in Poland, Romania, and Ukraine for cloud-native engineering skills. Raw material dependencies span hyperscaler compute capacity, specialized cybersecurity tooling, and GDPR-compliant data residency infrastructure. Single-source vulnerability runs through Warsaw-Kraków corridor developer concentration. Distribution runs through direct enterprise sales teams and channel partners serving Silesian manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act enforcement is consolidating Poland's IT services landscape as compliance costs force undifferentiated development houses toward acquisition or exit.
For Market Incumbents: Deploy algorithmic audit capabilities to capture EU AI Act-driven demand from Polish banking groups. Acquire embedded systems specialists in Silesia before German OEM supply chain requirements harden vendor qualifications. Certification investment in ENISA schemes protects public-sector tender eligibility against fragmentation risk. For New Entrants and Emerging Players: The price-point gap between premium compliance-heavy services and economy-tier agile delivery creates entry space for mid-market cybersecurity specialists. Łódź and Wrocław sub-markets offer lowest competitive density for carbon-accounting software stacks. Go-to-market through manufacturing associations accelerates trust-building with CSRD-mandated procurement teams. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with banking and healthcare regulatory depth. Long-term viability hinges on capturing recurring managed services revenue rather than project-based development. Watch NIS2 enforcement intensity as the inflection signal for cybersecurity services margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ENISA Certification Investment | Unlocks Polish public-sector tender eligibility as cybersecurity schemes fragment nationally. |
| Algorithmic Audit Service Launch | Captures EU AI Act compliance spend from Warsaw financial institutions revalidating decision systems. |
| Łódź Delivery Center Expansion | Reduces cost base while maintaining corridor connectivity to Kraków enterprise clients. |
| Embedded Systems Acquisition | Consolidates Silesian automotive software expertise serving German OEM supply chains. |
| Carbon-Accounting Platform Integration | Aligns with CSRD mandates pivoting enterprise procurement toward automated Scope 3 tracking. |
Research Methodology
Document review covered hyperscaler capex disclosures, ENISA certification databases, and Polish public procurement records, complemented by interviews with CTOs at Warsaw banking groups, IT procurement officers in Silesian manufacturing, platform engineers at Kraków cloud specialists, and channel partners serving Łódź logistics firms. Secondary validation drew from SEC filings of listed IT services firms, EU regulatory impact assessments, and Polish Office of Competition and Consumer Protection enforcement notices. Bottom-up project pipeline analysis triangulated against top-down spending estimates from enterprise technology budget surveys.
Segment-level revenue projections across the analysis window modeled deployment model, organization size, vertical compliance requirements, integration complexity, and regional adoption patterns. CAGRs derived from weighted average of historical growth trajectories and regulatory-driven demand step-changes. Forecast inputs incorporated NIS2 transposition timelines, EU AI Act enforcement phases, and CSRD reporting deadline clustering effects.
Underlying measurement precision varies by segment; cybersecurity services and cloud solutions carry tighter precision than emerging technology integration categories due to established procurement tracking. Forecasts reflect documented assumptions about regulatory implementation velocity and talent pool expansion rates. A model refresh is warranted upon material change in ENISA certification scheme harmonization or ECB supervisory technology mandate intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Global Survey Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Client Virtualization Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Cemetery Management Software Market
Software & Services
Global Microscope Software Market
Software & Services
HR Tech Market
Software & Services
Live Chat Software Market
Software & Services
POS Software Market
Software & Services
Video Communications Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Invoice Processing Software Market