
 Global Pickleball Equipment Market | 2026-2036
Global Pickleball Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pickleball Equipment Market Outlook
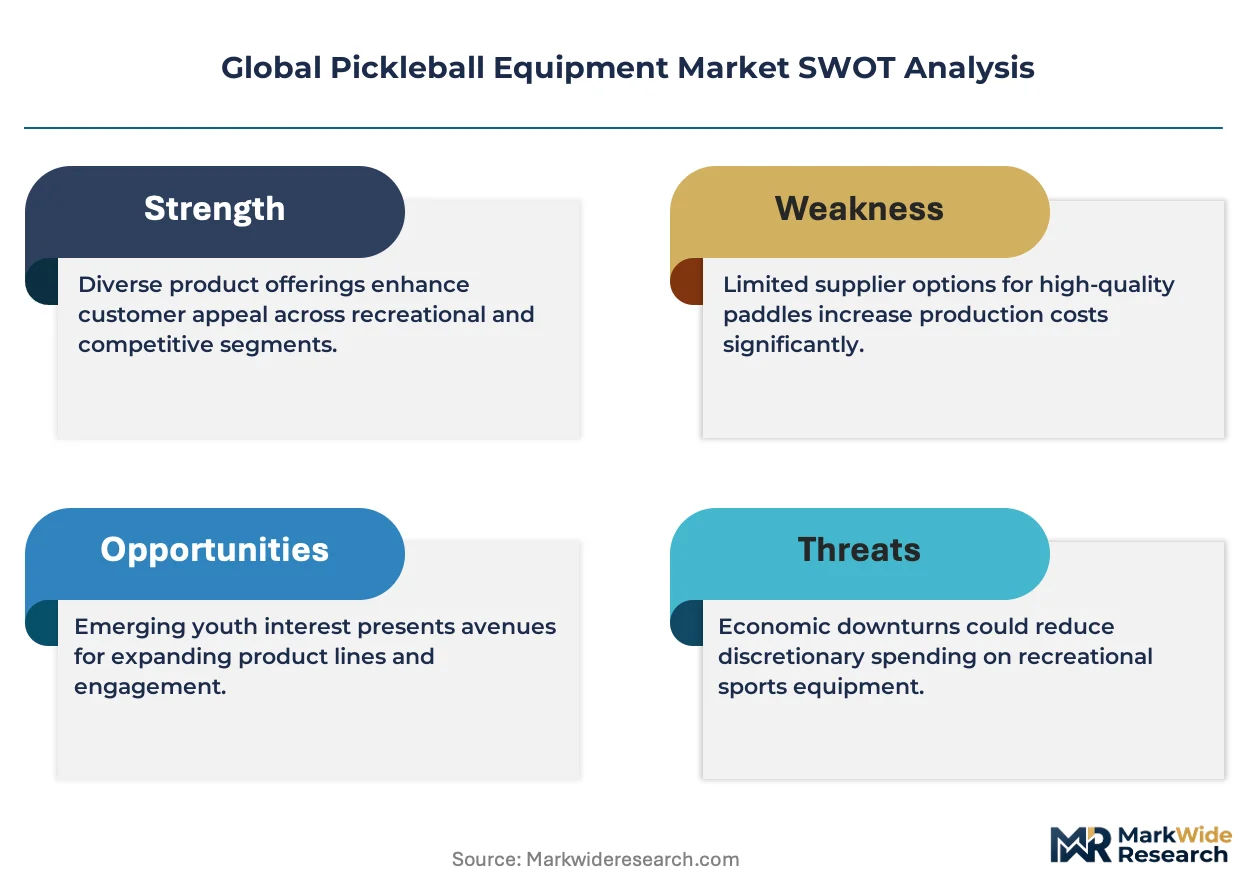
The premium paddle segment is recalibrating away from commodity wood and aluminum offerings as carbon fiber composites command higher price points and tournament-grade performance standards. Selkirk Sport leverages proprietary face technology to dominate the high-performance tier, while Franklin Sports anchors the mass retail channel through broad sporting goods distribution. Gearbox competes on manufacturing scale with its in-house production of edgeless paddle designs.
Pickleball equipment encompasses paddles, balls, nets, and accessories engineered to standardized dimensions and rebound specifications for court-based racket sport play. Composite paddles typically integrate polymer honeycomb cores with fiberglass or carbon fiber face sheets to optimize power-to-control ratios for varying skill levels. Paddles lead equipment value contribution as replacement cycles shorten with competitive intensity, while accessories capture expanding margin pools through branded bags, grips, and protective gear. Online retail channels now outpace specialty stores in volume throughput as direct-to-consumer brands bypass traditional intermediaries.
The US Consumer Product Safety Commission monitors paddle surface roughness standards, while ISO equipment durability protocols and USA Pickleball equipment certification rules shape product compliance requirements for tournament eligibility. These frameworks elevate manufacturing precision thresholds and filter non-compliant imports from market access. Stakeholders must monitor evolving material sustainability mandates and certification granularity as the sport's Olympic petition advances and international federation standards consolidate.
Market Dynamics
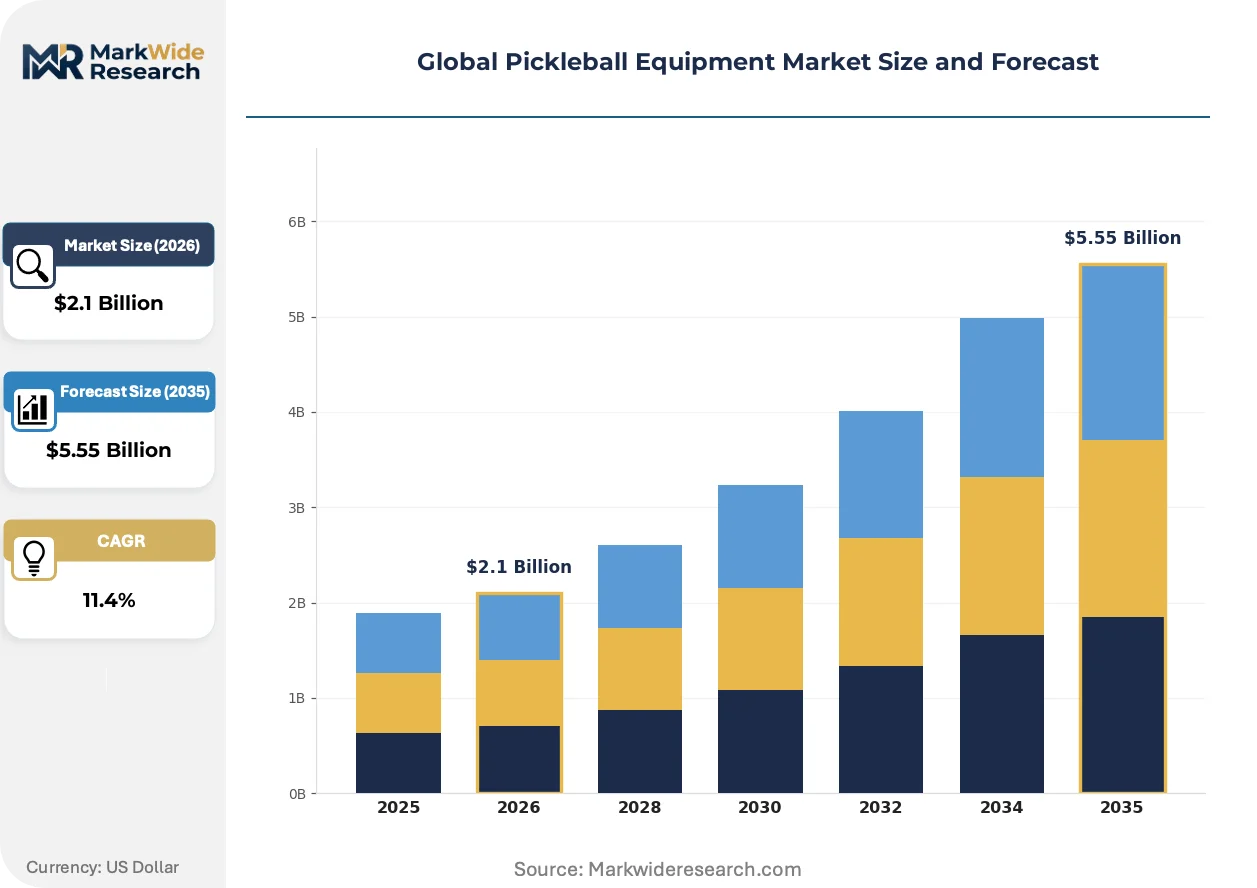
Municipal infrastructure buildouts across North America are accelerating court availability, while carbon fiber paddle construction is compressing replacement cycles and elevating performance benchmarks across competitive tiers.
Growth Catalysts
- USA Pickleball equipment certification:Tournament eligibility rules mandate certified paddle surfaces, creating recurring compliance demand that filters non-compliant imports from sanctioned play.
- Polymer honeycomb cores:Advanced core materials enable thinner face constructions that improve power-to-weight ratios for recreational players seeking tournament-grade feel.
- Municipal parks departments:Public court construction in the United States, Canada, and Australia is expanding accessible participation bases beyond private club membership.
Market Restraints
- Carbon fiber supply concentration:Aerospace and automotive sectors dominate carbon fiber offtake, constraining availability and pricing stability for paddle manufacturers.
- ISO equipment durability protocols:Testing certification timelines extend product development cycles, delaying market entry for new composite formulations.
- Wood and aluminum substitutes:Entry-level price points retain volume share in emerging markets where tournament participation remains limited.
Strategic Opportunities
- India municipal recreation budgets:Underdeveloped court infrastructure presents first-mover positioning as urban sports facility investment accelerates.
- Direct-to-consumer channels:E-commerce platforms bypass traditional sporting goods intermediaries, capturing margin expansion and customer data ownership.
- EU Green Deal material mandates:Sustainability certification requirements favor domestic manufacturers with recyclable composite supply chains.
Industry Challenges
- Composite engineering talent scarcity:Specialized polymer chemists and racket-sport product designers command premium compensation, constraining R&D scaling.
- USA Pickleball surface roughness compliance:Manufacturing tolerance tightening requires capital investment in precision machining and quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pickleball Equipment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paddles, Balls, Nets, Accessories Material: Composite, Wood, Aluminum, Plastic End User: Recreational Players, Professional Players, Coaches, Clubs Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Stores, Others |
| Companies Covered | Onix, Gearbox, Selkirk Sport, Wilson Sporting Goods, Franklin Sports, JOOLA, Engage Pickleball, ProKennex, Paddletek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pickleball Equipment Market Strategic Shifts
Material science advances are rewriting durability expectations while certification granularity tightens competitive filters. Distribution disintermediation is collapsing traditional retail hierarchies.
Carbon fiber face sheet technology is converging with thermoplastic edge bonding to eliminate traditional paddle edge guards. Tournament players and competitive clubs in the United States are adopting edgeless designs at accelerating rates. This construction shift is compressing differentiation timelines as manufacturing scale advantages consolidate among in-house composite producers.
REACH substance restrictions in Europe are mandating phased elimination of certain resin hardeners and surface coatings used in paddle construction. Manufacturers serving EU distribution channels must reformulate supply chains or risk market exclusion. Composite paddle producers with European assembly operations are accelerating alternative chemistry validation to maintain certification continuity.
Subscription-based equipment refresh programs are displacing outright purchase patterns among frequent players. Direct-to-consumer brands in North America are bundling paddle replacement with grip, bag, and accessory rotations. This model concentrates most visibly in the United States, where league participation density supports predictable consumption forecasting.
Global Pickleball Equipment Market Segmentation
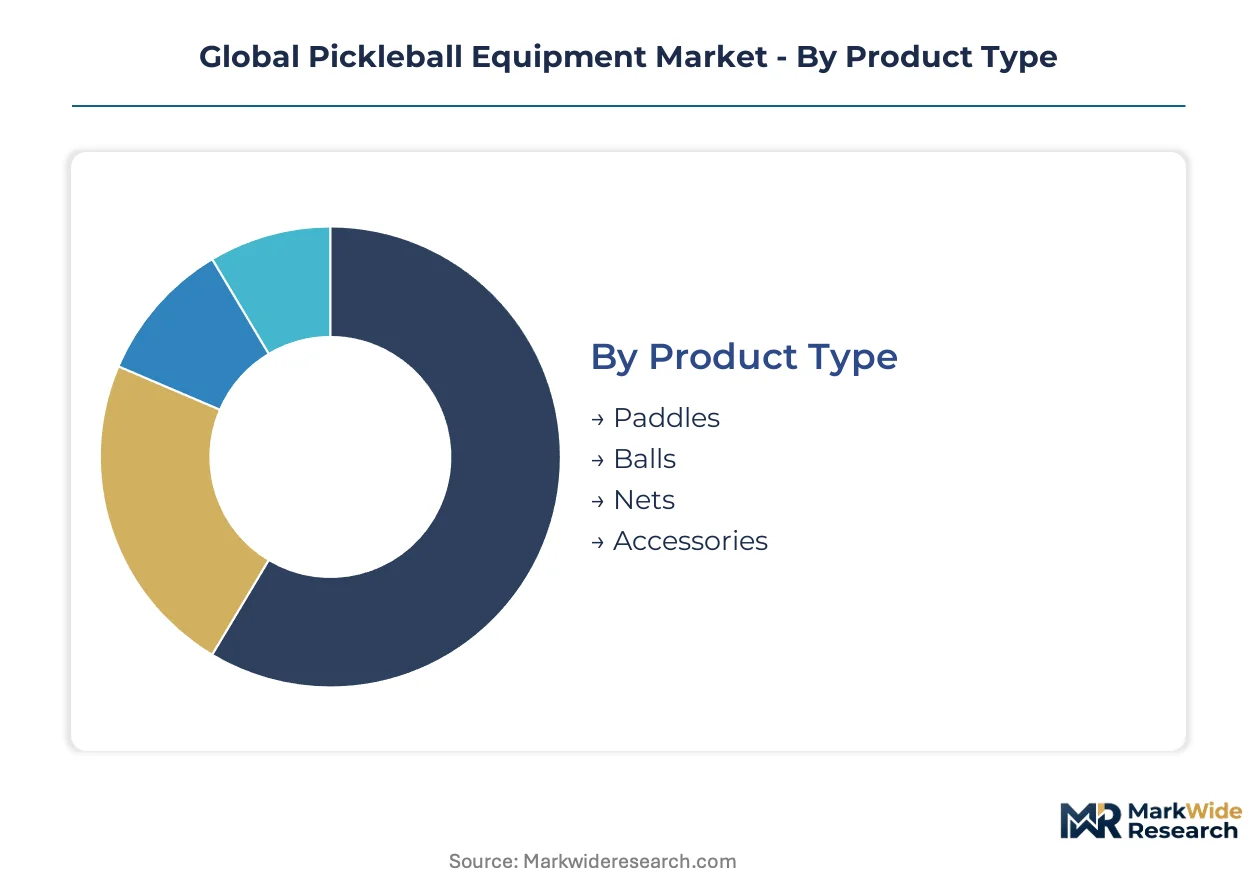
Pickleball equipment segmentation reveals divergent margin profiles across product categories and channel structures. Material composition and player skill tier drive replacement velocity and price elasticity variations that reshape vendor portfolio priorities.
Product Type:
Volume concentrates in consumable categories with short replacement cycles, while premium durability commands disproportionate value capture in structural equipment.
- Paddles:Composite constructions integrate polymer honeycomb cores with carbon fiber or fiberglass face sheets to optimize power-to-control ratios. Tournament-grade certification requirements in the United States compress replacement timelines as competitive intensity rises and surface roughness standards tighten.
- Balls:Molded plastic formulations with precisely calibrated hole patterns ensure standardized flight characteristics across indoor and outdoor court surfaces. Municipal parks departments in Australia and Canada drive bulk procurement volumes as public court infrastructure expands.
- Nets:Portable frame systems with tension-adjustable mesh dominate recreational deployment. Metal post installations anchor permanent court construction in the United States.
- Accessories:Branded bags, replacement grips, and protective gear capture expanding margin pools through direct-to-consumer bundling strategies.
Today's leader: Paddles. Tomorrow's challenger: Accessories.
Material:
Performance tier differentiation separates tournament-eligible constructions from entry-level alternatives across price-sensitive and premium segments.
- Composite:Carbon fiber and fiberglass face laminates bonded to polymer cores deliver optimal stiffness-to-weight ratios for competitive play. USA Pickleball certification mandates filter non-compliant imports from sanctioned tournament access in the United States.
- Wood:Solid timber constructions retain volume presence in emerging markets and institutional procurement where cost minimization dominates specification criteria.
- Aluminum:Metal face sheets offer intermediate durability at mid-market price points, though weight penalties limit adoption among frequent players.
- Plastic:Injection-molded polymer paddles serve absolute entry-level price tiers and youth programming where equipment loss rates remain elevated.
Composite constructions now anchor premium positioning. Wood and plastic alternatives defend accessible entry points.
End User:
Participation intensity and equipment sophistication create distinct procurement patterns across casual and committed player bases.
- Recreational Players:Casual participants prioritize durability and value in equipment selection, with municipal court access in Canada and Australia expanding addressable population bases beyond private club membership.
- Professional Players:Elite competitors demand tournament-certified specifications with optimized power-to-control characteristics, driving shortest replacement cycles and highest per-unit expenditure.
- Coaches:Instruction professionals require durable equipment inventories for lesson programming and player development curricula.
- Clubs:Facility operators balance equipment durability against member satisfaction metrics in bulk procurement decisions.
Recreational players now generate the steepest volume expansion trajectory. Professional players concentrate value capture.
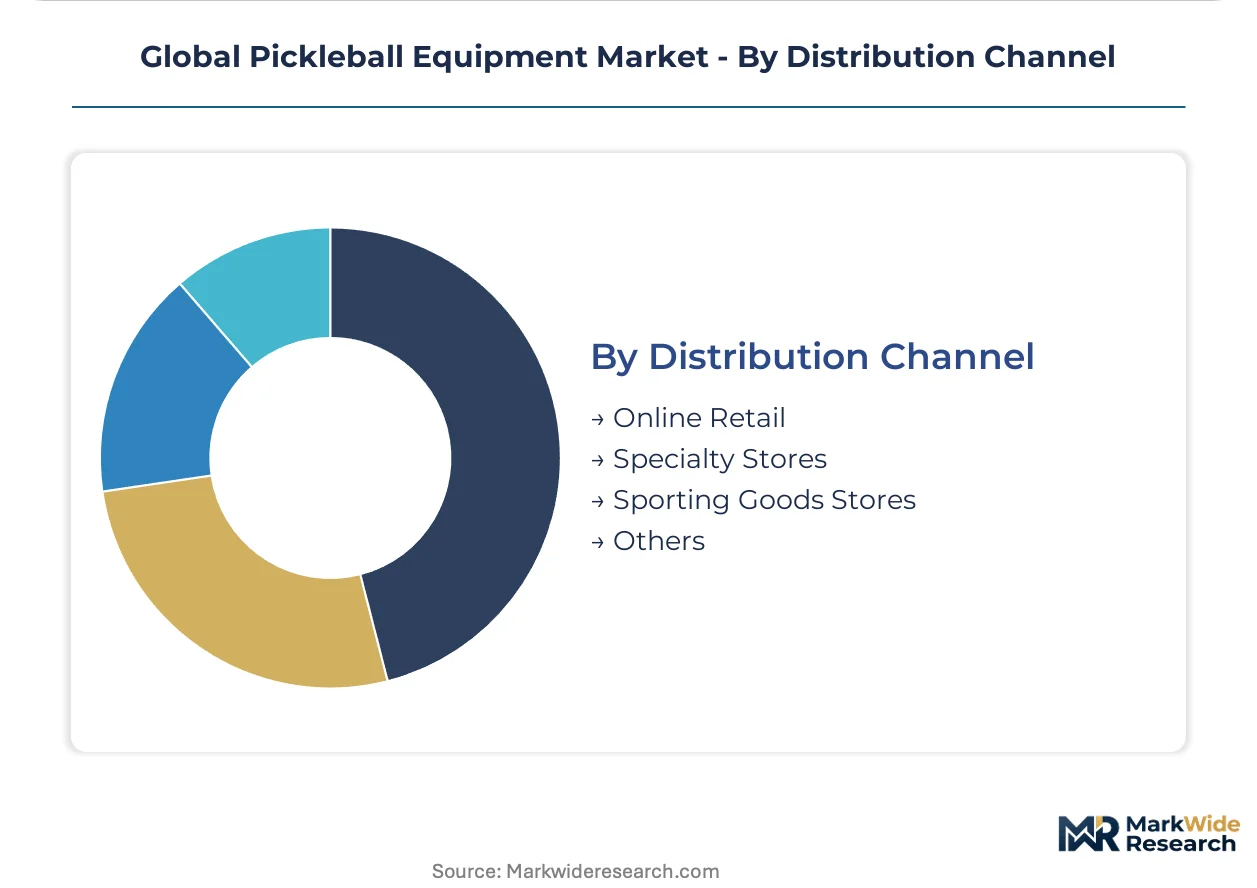
Distribution Channel:
Channel selection determines margin retention, customer data ownership, and brand positioning control for equipment vendors.
- Online Retail:Direct-to-consumer platforms bypass traditional sporting goods intermediaries, enabling subscription-based refresh programs and predictive inventory management in North America.
- Specialty Stores:Dedicated pickleball retailers provide expert fitting services and tournament-grade certification verification for competitive players.
- Sporting Goods Stores:Mass retail chains anchor volume distribution for entry-level equipment through broad geographic coverage.
- Others:Club pro shops and event-based sales capture impulse purchases and replacement demand at point of play.
Online retail is gaining share fastest. Specialty stores defend certification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified composite engineers and polymer chemists concentrate in established sporting goods manufacturing corridors across the United States, Germany, and China. Municipal recreation departments and private club operators drive equipment procurement intensity in these talent clusters.
United States
Municipal parks departments in Arizona, Florida, and California are deploying capital budgets toward permanent court construction at accelerating rates. USA Pickleball equipment certification mandates filter non-compliant imports from sanctioned tournament play. Phoenix and Naples anchor manufacturing scale for carbon fiber paddle production.
Germany
REACH substance restrictions are mandating reformulation of resin hardeners and surface coatings used in paddle construction. The EU Green Deal material mandates favor domestic manufacturers with recyclable composite supply chains. Stuttgart and Munich host precision machining clusters serving tournament-grade equipment tolerance requirements.
China
Injection-molded polymer paddle production serves absolute entry-level price tiers for youth programming and emerging market export. GB standards and MIIT industrial policy shape manufacturing compliance frameworks for sporting goods exporters. Dongguan and Shenzhen concentrate composite face sheet lamination capacity for mid-market global brands.
Canada
Municipal recreation infrastructure in Ontario and British Columbia is expanding accessible court bases beyond private club membership. Health Canada product safety monitoring aligns with US CPSC surface roughness standards for cross-border equipment compatibility. Toronto and Vancouver anchor specialty retail distribution for tournament-certified imports.
Australia
Public court construction in New South Wales and Queensland is driving bulk procurement volumes for molded plastic balls and portable net systems. TGA consumer product oversight applies to protective gear and accessory imports. Melbourne and Sydney concentrate coaching professional development programs that sustain equipment replacement demand.
Global Pickleball Equipment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the equipment value chain. In-house composite manufacturing operations in the United States and Asia-Pacific face off against brands outsourcing fabrication to certified foundries. Three archetypes dominate: integrated composite producers controlling polymer core and face sheet production, direct-to-consumer specialists capturing margin through subscription refresh programs, and mass retail anchors distributing entry-level wood and aluminum alternatives. Strategic moves concentrate on manufacturing scale expansion and certification compliance investment.
Among integrated producers, Selkirk Sport and Gearbox exemplify the capital-intensive archetype with proprietary face technology and in-house edgeless design production. Franklin Sports occupies the mass retail channel position through broad sporting goods distribution networks. Wilson Sporting Goods represents the diversified sporting goods conglomerate model leveraging existing racket sport expertise across multiple product tiers.
| Leading Market Players |
|---|
| Onix |
| Gearbox |
| Selkirk Sport |
| Wilson Sporting Goods |
| Franklin Sports |
| JOOLA |
| Engage Pickleball |
| ProKennex |
| Paddletek |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber prepreg costs cascade through paddle manufacturing tiers, compressing margins at the premium composite level while wood and aluminum alternatives defend entry-level price floors in municipal procurement channels across the United States and Canada.
Pricing Analysis
Subscription-based equipment refresh programs separate direct-to-consumer pricing from transactional retail models. Pricing stratifies across premium, standard, and economy tiers based on USA Pickleball certification grade and carbon fiber face sheet quality. Cost compression in the mid-market intensifies as polymer honeycomb core suppliers compete on volume scale. Recreational players in municipal programs exhibit highest price sensitivity, while competitive club members accept premium positioning for tournament-grade specifications.
Supply Chain Analysis
Single-source vulnerability sits with aerospace-dominated carbon fiber offtake in Japan and the United States, constraining sporting goods allocation. Manufacturing draws from polymer core production in China, face sheet lamination in Dongguan, and precision machining clusters in Germany. Tariff exposure on composite imports from Asia threatens margin stability for North American brands. Distribution runs through direct-to-consumer platforms, specialty retailers, and mass sporting goods chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-mandated reformulation costs in Europe and less stringent chemical compliance in North American production, rewarding manufacturers with dual-region assembly footprints.
For Market Incumbents: To counter direct-to-consumer subscription models eroding retail channel control, Selkirk Sport and Gearbox should deepen in-house composite production to capture margin upstream. Certification investment in USA Pickleball surface roughness compliance creates defensive moats against import competition.
For New Entrants and Emerging Players: Edgeless thermoplastic bonding technology offers white-space entry against legacy edge-guard designs. Target India's underdeveloped municipal court infrastructure with portable net systems and molded plastic paddles. Launch through municipal procurement channels rather than retail intermediaries.
For Investors and Strategic Acquirers: Roll-up economics work for direct-to-consumer specialists because subscription refresh programs generate predictable recurring revenue with low customer acquisition costs in league-dense geographies. Watch USA Pickleball Olympic petition advancement as inflection signal for international certification standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| In-House Composite Manufacturing | Captive carbon fiber face sheet production insulates margin from aerospace sector offtake competition. |
| Subscription Equipment Refresh Programs | Predictable replacement cycles in the United States concentrate customer lifetime value for direct-to-consumer brands. |
| REACH Compliance Reformulation | Alternative resin chemistry validation secures EU market access as Green Deal mandates tighten. |
| Municipal Procurement Channel Development | Bulk paddle and net orders from parks departments in Canada and Australia bypass retail margin extraction. |
| Edgeless Design Patent Portfolio | Thermoplastic bonding IP blocks follower brands in tournament-grade paddle construction. |
Study Parameters
Multiple input streams — executive interviews with paddle manufacturers, procurement managers at municipal parks departments, and specialty retail buyers — were reconciled against USA Pickleball certification databases, customs trade records for composite material imports, and sporting goods distribution data. Primary conversations with polymer chemists, composite engineers, and tournament equipment inspectors informed material science trajectory assessments. Secondary validation drew from SEC filings of diversified sporting goods conglomerates, municipal capital budget disclosures in Arizona and Florida, and ECHA substance restriction updates. Bottom-up paddle shipment estimates and top-down equipment expenditure surveys were cross-referenced for triangulation.
Historical volume patterns from trade associations and industry panels were cross-referenced against forward-looking procurement intentions from club operators and recreation departments across the analysis window. Segmentation modeling incorporated product type, material composition, end-user tier, and distribution channel dimensions. CAGRs were derived from slope analysis of replacement cycle compression and court infrastructure expansion curves, with carbon fiber supply elasticity and certification timeline variables feeding sensitivity ranges.
The model holds under continued municipal recreation budget growth and stable aerospace carbon fiber allocation; deviation in trade policy or REACH substance ban acceleration would shift trajectory bounds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Trail Shoes Market
Sports Equipment
Running Gear Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Tetherball Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Figure Skating Equipment Market