
 Sports and Leisure Equipment Market | 2026-2036
Sports and Leisure Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sports and Leisure Equipment Market Outlook
Specialty retail and direct-to-consumer channels is reconfiguring how sports equipment reaches end buyers, with digital storefronts displacing traditional wholesale relationships. Nike Inc. leverages its membership ecosystem to sustain repeat purchases and reduce customer acquisition costs. Adidas AG anchors its European manufacturing base while competing aggressively in Asian markets through localized production partnerships. Decathlon S.A. differentiates through vertical control of design-to-retail operations, occupying a distinct value position against premium competitors.
Sports and leisure equipment encompasses mechanically engineered apparatus, protective gear, and performance apparel fabricated from advanced polymers, carbon fiber composites, and technical textiles designed to enhance athletic output, ensure user safety, or enable recreational participation. Fitness Equipment commands the largest revenue pool as home gym installations and corporate wellness programs expand procurement volumes, while Water Sports Equipment represents the fastest-expanding category driven by coastal tourism recovery and paddle sport democratization. The Online Retail distribution channel captures disproportionate growth velocity as augmented reality fitting tools and subscription replenishment models reduce purchase friction for repeat buyers.
The US Consumer Product Safety Commission enforces stringent equipment safety standards that elevate compliance costs but barrier substandard imports, while the EU's REACH chemicals regulation and CE marking requirements shape material selection across European supply chains. China's SAMR implements national standard GB revisions that increasingly align with international testing protocols, facilitating export market access for compliant domestic manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions as sustainability mandates and digital product passport requirements reshape competitive access conditions.
Market Dynamics
The EU Green Deal's extended producer responsibility framework is forcing manufacturers to reconfigure material sourcing, while China's urban demand clusters and post-pandemic home fitness normalization create divergent supply chain pressures across the value chain.
Growth Catalysts
- REACH chemical compliance:European manufacturers redesigning polymer formulations to meet restricted substance lists are unlocking premium positioning in regulated export markets.
- Home gym equipment:Individual consumers sustaining post-pandemic workout routines are expanding replacement cycles for connected fitness hardware.
- Shanghai-Beijing corridor:Concentrated government sports infrastructure investment in China's tier-one cities is generating equipment procurement volumes exceeding provincial averages.
Market Restraints
- Carbon fiber supply concentration:Japanese and Taiwanese precursor manufacturers control high-modulus fiber output, creating input bottlenecks for premium composite equipment.
- CE marking friction:Small-batch European producers face disproportionate testing costs relative to Asian competitors with scaled certification runs.
- Natural rubber volatility:Southeast Asian latex supply disruptions transmit directly to mat and resistance band pricing.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for technical textiles are attracting synthetic fabric investments serving athletic apparel.
- Augmented reality fitting:AR visualization tools are compressing return rates for online eyewear and helmet purchases.
- Corporate wellness mandates:Employer-funded fitness subsidies in Germany and Netherlands are institutionalizing B2B procurement channels.
Industry Challenges
- Composite repair technician scarcity:Carbon fiber bicycle and paddleboard manufacturers face qualified workforce gaps in European assembly facilities.
- GB standard harmonization:Chinese exporters must maintain parallel testing protocols for domestic SAMR compliance versus target market certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports and Leisure Equipment Market |
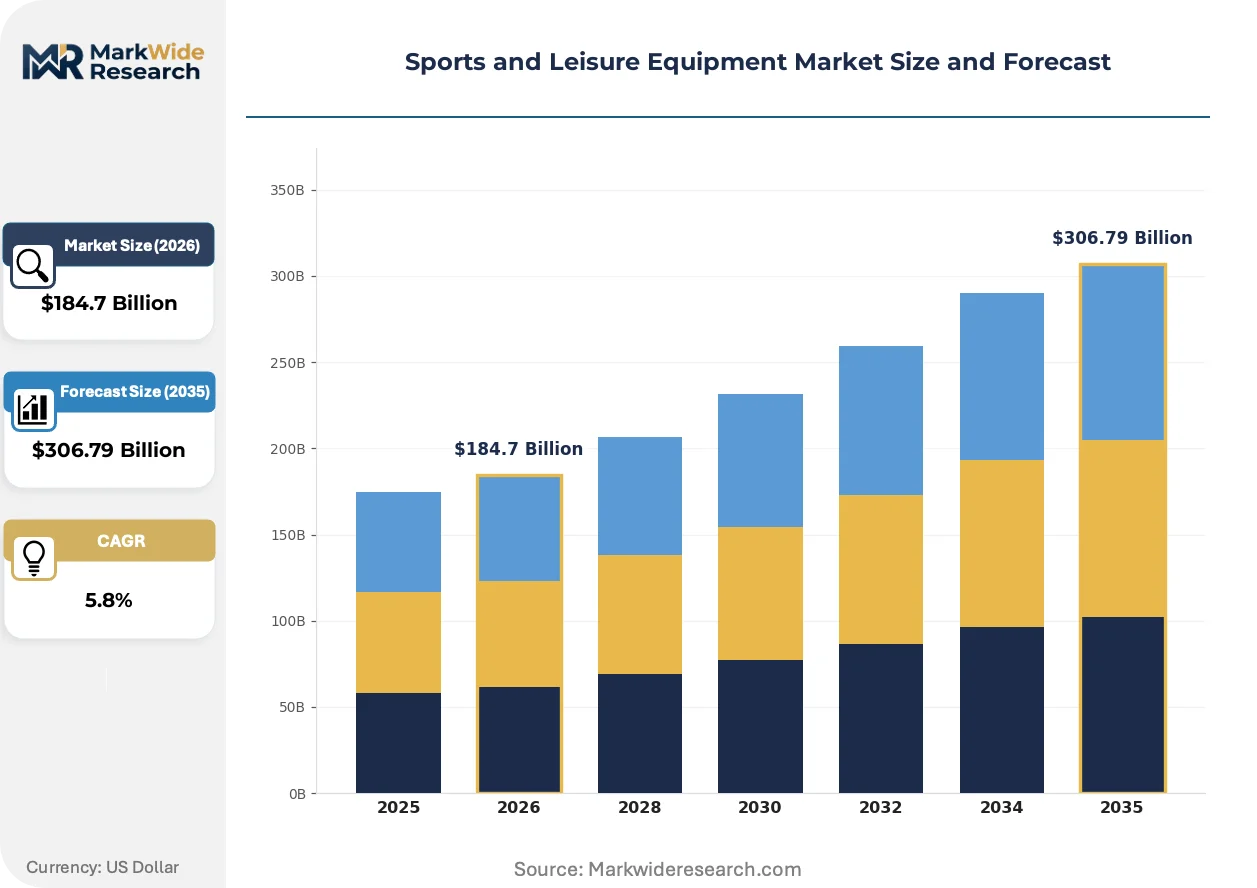
| Market Size in 2026 | $184.7 Billion |
| Market Size in 2035 | $306.79 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Equipment, Team Sports Gear, Water Sports Equipment, Outdoor Equipment End User: Individuals, Schools, Gyms, Sports Clubs Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Anta Sports Products Limited, Callaway Golf Company, Nike Inc., ASICS Corporation, Li-Ning Company Limited, Adidas AG, Under Armour Inc., Amer Sports Corporation, Decathlon S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports and Leisure Equipment Market Strategic Shifts
Material science breakthroughs and regulatory transparency mandates are compressing product development cycles while digital channels rewrite how equipment reaches end users.
Recycled ocean plastic is migrating from marketing narrative to structural load-bearing applications in kayak hulls and surfboard cores. Coastal equipment brands in Portugal and California are specifying rPET-PETG blends for UV-resistant exterior components. Performance parity with virgin polymers is migrating from niche positioning to baseline procurement specifications among sustainability-scrutinized buyers.
ECHA's SCIP database requirements for Substances of Concern are compelling full material disclosure across European supply chains. Manufacturers must now map polymer additives and metal alloys through tier-three suppliers. Fitness equipment with embedded electronics faces intensified due diligence obligations under WEEE directive extensions.
Subscription-based equipment access is displacing outright purchase for high-ticket home gym systems. Nordic and Benelux consumers increasingly favor monthly hardware-as-a-service arrangements with bundled content. This model concentrates inventory risk with manufacturers while capturing lifetime value through consumable and content attach rates.
Sports and Leisure Equipment Market Segmentation
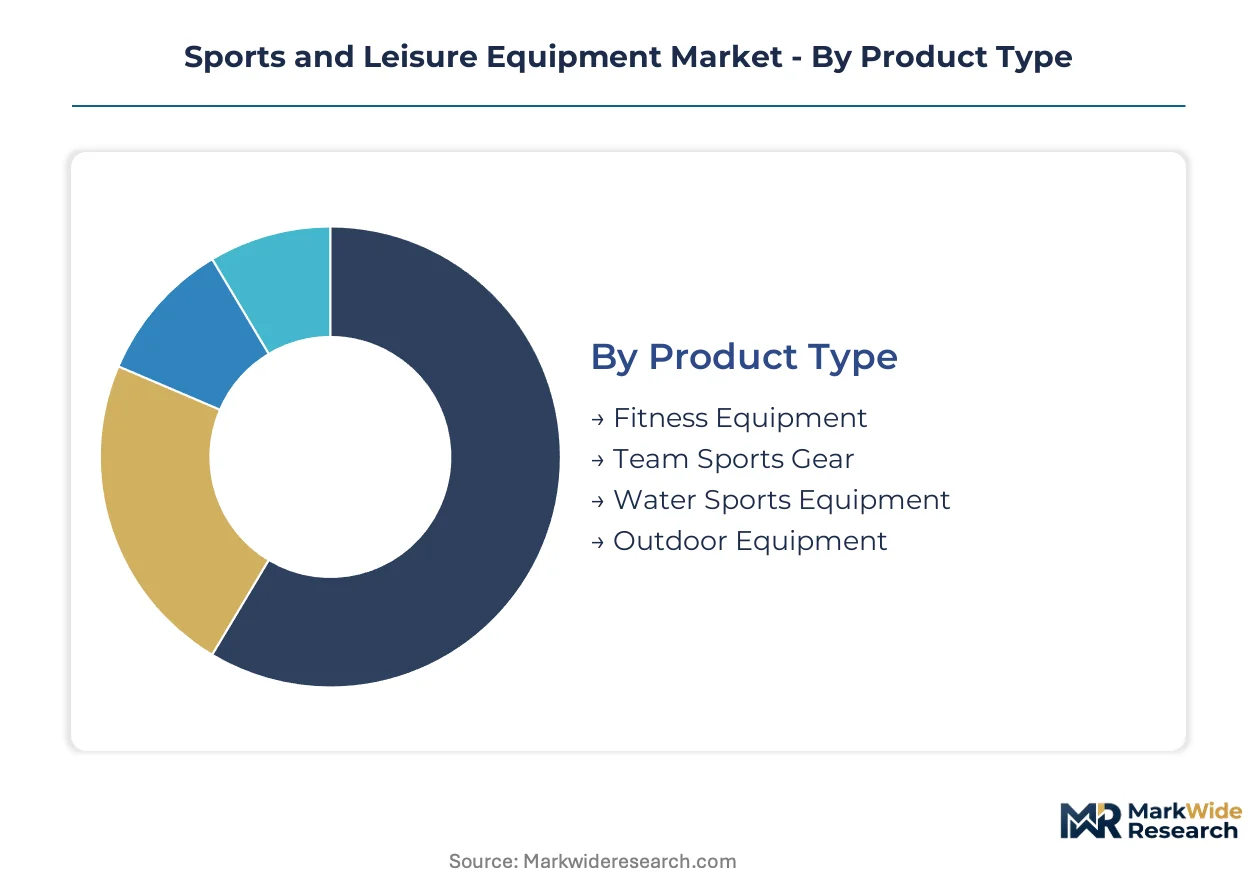
Segmentation reveals how equipment specifications, procurement channels, and price positioning create distinct competitive arenas. Manufacturers must align R&D investment and distribution strategy with the divergent requirements of home fitness enthusiasts versus institutional buyers.
Product Type:
Use-case spectrum spans solitary conditioning apparatus through collaborative competitive gear to environmental exposure equipment.
- Fitness Equipment:Mechanically engineered resistance and cardio apparatus fabricated from steel tubing, polymer coatings, and embedded sensor arrays. Home gym installations in China's tier-one cities and corporate wellness programs in Germany are absorbing connected hardware with subscription content bundles.
- Water Sports Equipment:Hydrodynamic hulls, paddles, and flotation devices utilizing carbon fiber composites and thermoformed plastics. Coastal tourism recovery in Portugal and paddle sport democratization across California's municipal waterways are compressing replacement cycles for recreational kayaks and stand-up paddleboards.
- Team Sports Gear:Protective padding, footwear, and implements designed for collision or projectile dynamics in organized competition.
- Outdoor Equipment:Portable shelter, navigation, and survival systems engineered for extended environmental exposure in remote terrain.
The dominant share belongs to Fitness Equipment, while Water Sports Equipment is closing the gap fastest.
End User:
Procurement authority concentrates in four distinct organizational forms with divergent volume scales and specification requirements.
- Individuals:Single-point purchasers selecting equipment for personal use across home, recreational, or travel contexts. Post-pandemic workout routine normalization has sustained replacement demand for connected fitness hardware in US suburban markets.
- Gyms:Commercial facility operators procuring durable apparatus for high-frequency multi-user environments. Equipment financing arrangements and preventive maintenance contracts are restructuring capital deployment across European independent operators.
- Schools:Public and private educational institutions acquiring gear for physical education curricula and interscholastic competition.
- Sports Clubs:Member-governed organizations managing competitive programs across amateur through semi-professional tiers.
Individuals command the largest addressable base, though Gyms are consolidating procurement volume fastest through equipment-as-a-service transitions.
Distribution Channel:
Channel economics diverge sharply between inventory-light digital fulfillment and experience-dependent physical retail.
- Online Retail:Digital storefronts leveraging augmented reality visualization and algorithmic recommendation engines. AR fitting tools for helmets and eyewear are compressing return rates among Nordic consumers, while subscription replenishment models capture repeat purchases for consumable training accessories.
- Specialty Stores:Curated retail environments staffed with technical product expertise and fitting services. European cycling specialists and running gait analysis centers are defending margin position against digital competitors through biomechanical assessment services.
- Department Stores:General merchandise retailers allocating seasonal floor space to recreational equipment categories.
- Direct Sales:Manufacturer-controlled channels bypassing wholesale intermediaries through owned digital properties or field sales organizations.
Online Retail is expanding most quickly, yet Specialty Stores retain pricing power in technical categories requiring expert fitting.
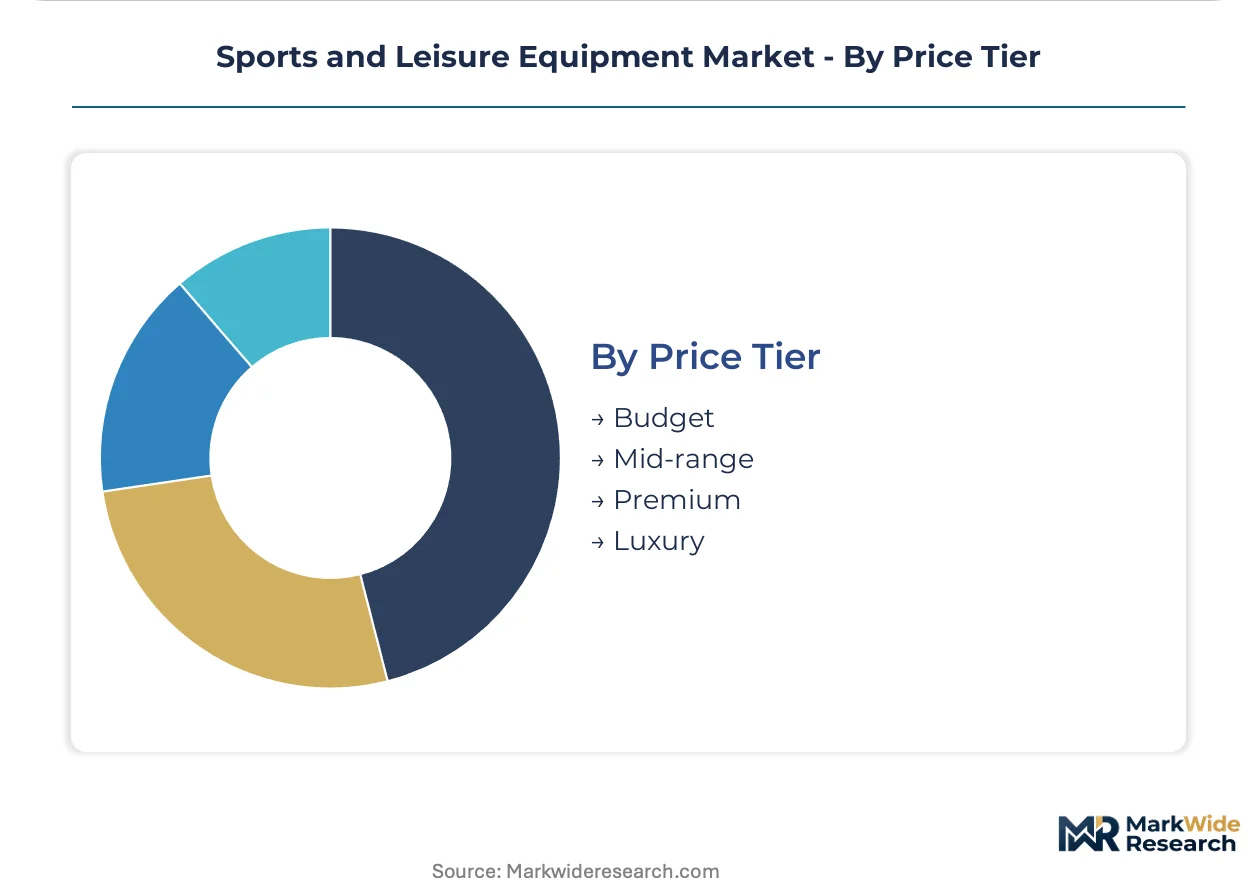
Price Tier:
Cost stratification reflects materials engineering depth, brand equity accumulation, and certification grade rather than manufacturing scale alone.
- Premium:Professional-grade specifications utilizing aerospace-derived materials and proprietary biomechanical research. REACH-compliant polymer formulations and carbon fiber layup optimization are unlocking positioning in regulated European export markets.
- Mid-range:Performance-adequate equipment balancing durability and accessibility for committed recreational users. Chinese manufacturers achieving GB standard harmonization are penetrating this tier through compliant domestic production.
- Budget:Price-optimized specifications utilizing standardized components and reduced warranty coverage.
- Luxury:Exclusivity-positioned collections emphasizing craftsmanship narrative and limited production runs.
Premium tier holds the revenue concentration, while Mid-range is gaining share fastest as quality thresholds rise across mass-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European distribution networks for carbon fiber composites and technical textiles serving cycling and watersports manufacturers.
United States
Suburban home gym installations and corporate wellness subsidies sustain demand for connected fitness hardware. The Consumer Product Safety Commission enforces equipment safety standards that elevate compliance costs for importers. Southern California's coastal cluster concentrates paddleboard and surfboard design studios near polymer composite suppliers.
Germany
Employer-funded fitness mandates in the Netherlands and Germany institutionalize B2B procurement channels for commercial gym operators. ECHA's SCIP database requirements compel full material disclosure across polymer supply chains. Bavaria's sporting goods manufacturing belt hosts precision engineering firms serving alpine and cycling equipment segments.
China
Rising disposable incomes in tier-one cities and government-backed sports infrastructure investment generate concentrated equipment procurement volumes. SAMR implements GB standard revisions that increasingly align with international testing protocols. The Shanghai-Beijing corridor absorbs premium fitness hardware volumes exceeding provincial averages.
Japan
High-modulus carbon fiber precursor production concentrates among domestic chemical conglomerates supplying bicycle and paddleboard manufacturers. METI oversees industrial standards harmonization with ISO protocols for export market access. Osaka-Kobe's polymer research cluster advances thermoplastic composite formulations for recreational marine applications.
India
Production-linked incentives for technical textiles attract synthetic fabric investments serving athletic apparel export contracts. BIS certification requirements shape domestic market entry for imported equipment. Tamil Nadu's textile belt scales polyester knit production for compression wear and performance base layers.
Sports and Leisure Equipment Market Competitive Environment
On the supply side, the industry is tiered between vertically integrated multinationals, specialized component fabricators, and private-label assemblers. Premium positioning depends on proprietary material formulations and membership ecosystem lock-in rather than manufacturing scale alone. Three archetypes dominate: brand-asset licensors controlling design and distribution, captive manufacturers with in-house composite production, and retail-integrated operators spanning design-to-shelf control. Competitive moves concentrate on strategic partnerships for localized Asian production and portfolio diversification into adjacent wellness categories.
Among membership-ecosystem operators, Nike Inc. exemplifies recurring-revenue architecture through digital content bundling. Adidas AG anchors European manufacturing heritage while competing in Asian markets through partnership structures. Decathlon S.A. occupies a distinct value position through retail-integrated operations controlling design-to-shelf margins.
| Leading Market Players |
|---|
| Anta Sports Products Limited |
| Callaway Golf Company |
| Nike Inc. |
| ASICS Corporation |
| Li-Ning Company Limited |
| Adidas AG |
| Under Armour Inc. |
| Amer Sports Corporation |
| Decathlon S.A. |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber precursor concentration among Japanese and Taiwanese chemical conglomerates determines both premium-equipment pricing spreads and composite supply chain configuration across cycling and watersports manufacturing.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships between large-format retailers and equipment manufacturers. Premium-mid-economy pricing differentiation reflects certification grade divergence, with REACH-compliant polymer formulations commanding positioning in regulated European export markets. Cost compression in mid-range tiers is intensifying because Chinese manufacturers achieving GB standard harmonization are penetrating through compliant domestic production. Individual consumers show highest price sensitivity, while corporate wellness program administrators demonstrate lowest sensitivity due to employer-funded subsidy structures.
Supply Chain Analysis
Extended payment terms from European specialty retailers are compressing manufacturer working capital cycles across the value chain. Manufacturing concentration in China, Vietnam, and Bangladesh feeds apparel and accessory production, while Japan and Taiwan anchor carbon fiber precursor supply. Raw material dependencies include high-modulus carbon fiber, technical polyester textiles, and natural rubber latex. Single-source vulnerability concentrates in Japanese Toray-grade precursor for aerospace-derived composite applications. Distribution runs through Rotterdam-port container networks serving European cycling and watersports manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a post-pandemic equipment replacement cycle as home fitness normalization sustains hardware refresh demand among individual consumers.
For Market Incumbents: Build certification-grade moats through REACH-compliant polymer formulation investments that barrier Asian competitors from European premium positioning. Deepen backward integration into carbon fiber layup operations to reduce precursor cost volatility exposure. Channel control through owned retail footprints in China's tier-one cities defends margin position against direct-to-consumer entrants. For New Entrants and Emerging Players: Pursue India's technical textile production-linked incentive zones for synthetic fabric investments serving athletic apparel export contracts. Target corporate wellness mandate jurisdictions in Germany and Netherlands where employer-funded subsidies reduce end-user price sensitivity. Launch through equipment-as-a-service subscription models capturing lifetime value through content and consumable attach rates. For Investors and Strategic Acquirers: The market sits at an inventory-normalization phase that favors retail-integrated operators with design-to-shelf margin control. Long-term viability across the analysis window hinges on sustainability-scrutinized buyer procurement specifications migrating from niche to baseline. Watch ECHA SCIP database compliance costs as inflection indicator for competitive access conditions in European markets.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | Unlocks premium positioning in regulated European export markets for polymer-dependent equipment categories. |
| Direct-to-Consumer Digital Launch | Nike's membership ecosystem demonstrates recurring-revenue architecture reducing customer acquisition costs. |
| Asian Localized Production Partnership | Adidas anchors European heritage while competing through partnership structures in Chinese urban demand clusters. |
| Equipment-as-a-Service Transition | Nordic subscription models concentrate inventory risk with manufacturers while capturing lifetime value. |
| Vertical Design-to-Retail Integration | Decathlon's control of margins from specification through shelf placement occupies distinct value position. |
Study Parameters
A spread of perspectives from equipment R&D directors, specialty retail buyers, corporate wellness program administrators, and carbon fiber procurement managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade records, SEC 10-K equipment segment disclosures, and ECHA regulatory filing databases. Bottom-up equipment shipment tallies triangulated against top-down consumer expenditure surveys.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user procurement authority, distribution channel economics, and price tier certification requirements. CAGRs derived from equipment replacement cycle analysis and coastal tourism recovery trajectories. Forecast inputs incorporated SAMR GB standard revision timelines and EU Green Deal extended producer responsibility implementation schedules.
Sensitivities concentrate around carbon fiber precursor supply disruptions, REACH substance restriction list expansions, and coastal tourism demand volatility. Forecasts reflect documented assumptions on replacement cycle normalization and regulatory harmonization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
US Fencing Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Go Kart Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Mouthguard Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Rowing Oars Market