
 C-RAN Market | 2026-2036
C-RAN Market Size, Share, and Industry Trends Forecast 2026-2036
C-RAN Market Analysis
Network-as-a-service financing and infrastructure leasing is reshaping competitive entry in C-RAN deployment, lowering capital barriers for regional challengers. Telefonaktiebolaget LM Ericsson leverages its optical transport integration to anchor large-scale European centralization projects. Nokia Corporation sustains R&D intensity in cloud-native baseband software, competing against vertically integrated Asian suppliers. Huawei Technologies Co., Ltd. dominates domestic deployment scale while navigating export restrictions through captive semiconductor sourcing.
Cloud-RAN architecture pools baseband processing resources from distributed cell sites into centralized data centers, using fronthaul fiber links with sub-100-microsecond latency budgets to coordinate remote radio heads across macro and small-cell layers. The architecture's primary purpose is to enable statistical multiplexing of compute resources and simplify coordination for advanced antenna techniques. Cloud-based deployment models capture the fastest expansion trajectory as hyperscaler partnerships reduce operator capex cycles, while remote radio units remain the largest component spend category due to massive MIMO antenna array complexity. Virtualization technology separates hardware from baseband software, shifting margin pools toward containerized orchestration platforms.
FCC spectrum allocation rules in the United States, MIIT 5G infrastructure directives in China, and EU Green Deal energy-efficiency standards collectively shape equipment certification timelines and procurement specifications across major economies. ETSI Open RAN standards and O-RAN Alliance interoperability mandates are forcing incumbent vendors to disaggregate proprietary stacks, creating qualification overhead for new entrants. Stakeholders must monitor how national security reviews of foreign telecom equipment reshape supplier eligibility lists and contract award patterns.
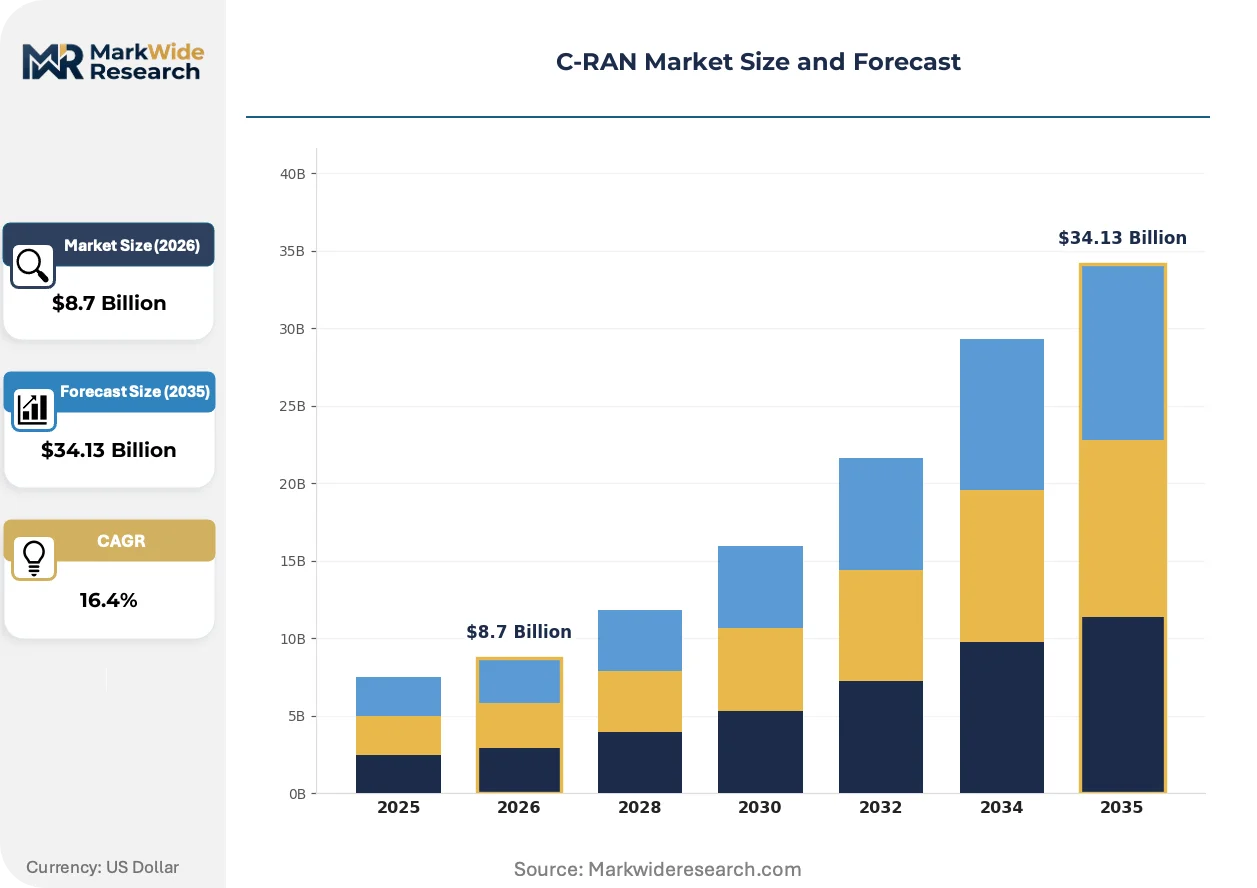
Market Dynamics
Open RAN disaggregation mandates and hyperscaler cloud partnerships are compressing traditional vendor lock-in cycles while redistributing margin pools toward software orchestration layers and managed infrastructure services.
Growth Catalysts
- ETSI Open RAN standards:European interoperability mandates force proprietary stack disaggregation, opening procurement to non-incumbent radio unit suppliers and containerized baseband vendors.
- Massive MIMO antenna densification:Urban fiber corridors in Germany, Japan, and South Korea concentrate centralized processing demand where statistical multiplexing yields maximum spectral efficiency gains.
- Network-as-a-service financing:Infrastructure leasing models lower capital barriers for regional challengers entering C-RAN deployment without legacy asset bases.
Market Restraints
- Fronthaul fiber latency budgets:Sub-100-microsecond coordination requirements constrain remote radio head placement distances and exclude copper-dependent legacy backhaul regions from centralization.
- Captive semiconductor sourcing:Export restriction compliance costs for advanced baseband processors concentrate supply risk among vertically integrated Asian fabricators with in-house wafer capacity.
- O-RAN Alliance qualification overhead:Multi-vendor integration testing timelines extend deployment schedules and inflate system integration costs versus single-vendor turnkey alternatives.
Strategic Opportunities
- EU Green Deal energy-efficiency standards:Power consumption metrics in equipment certification create procurement preference for liquid-cooled centralized data centers over distributed air-conditioned cell sites.
- Cloud-native baseband software:Containerized orchestration platforms enable Kubernetes-based scaling that hyperscaler partnerships can operationalize for tier-two operators lacking internal cloud competency.
- India TRAI infrastructure sharing directives:Passive infrastructure unbundling mandates accelerate neutral host C-RAN deployment models for enterprise private networks and railway corridors.
Industry Challenges
- Legacy 4G baseband integration:Multi-generational radio access network coexistence demands backward-compatible orchestration stacks that complicate cloud-native migration roadmaps.
- Specialized fiber splicing workforce:Fronthaul dark fiber deployment rates outpace qualified technician supply in markets with limited telecom construction labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C-RAN Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Distributed Component Type: Remote Radio Units, Baseband Units, Optical Transport Network, Network Management System Technology: Virtualization, Centralization, Cloud Computing, Massive MIMO End User: Telecom Operators, Enterprises, Managed Service Providers, System Integrators |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Nokia Corporation, Huawei Technologies Co., Ltd., ZTE Corporation, Samsung Electronics Co Ltd, Cisco Systems, Inc., Intel Corporation, NEC Corporation, FUJITSU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C-RAN Market Emerging Trajectories
Virtualization technology is separating hardware from baseband software, shifting competitive advantage toward container orchestration expertise and API-native management platforms that reduce operator dependency on proprietary vendor ecosystems.
vRAN architecture is hybridizing centralized and distributed processing models through split-option flexibility that places real-time functions at cell sites while pooling non-real-time workloads in edge data centers. Tier-one operators in South Korea and Germany are deploying this split at scale for stadium and industrial campus scenarios. The approach is hybridizing procurement patterns by forcing incumbents to disaggregate previously integrated offerings while enabling specialist vendors to capture sub-system contracts.
MIIT 5G infrastructure directives in China mandate domestic equipment certification timelines that compress foreign vendor qualification windows and accelerate captive supply chain development for baseband processors and massive MIMO arrays. State-backed procurement specifications favor suppliers with in-house semiconductor fabrication. Domestic operators are responding by consolidating awards among vertically integrated national champions with captive wafer capacity.
Telecom equipment buyers are unbundling radio unit supply from baseband software contracts, fragmenting historically integrated vendor relationships and introducing multi-source qualification overhead. Neutral host infrastructure providers and enterprise private network deployers are driving this pattern most visibly in Germany and Japan, where Open RAN mandates accelerate disaggregated sourcing. The shift compresses incumbent margin pools while elevating system integrator and test-equipment vendor influence in deployment workflows.
C-RAN Market Segmentation
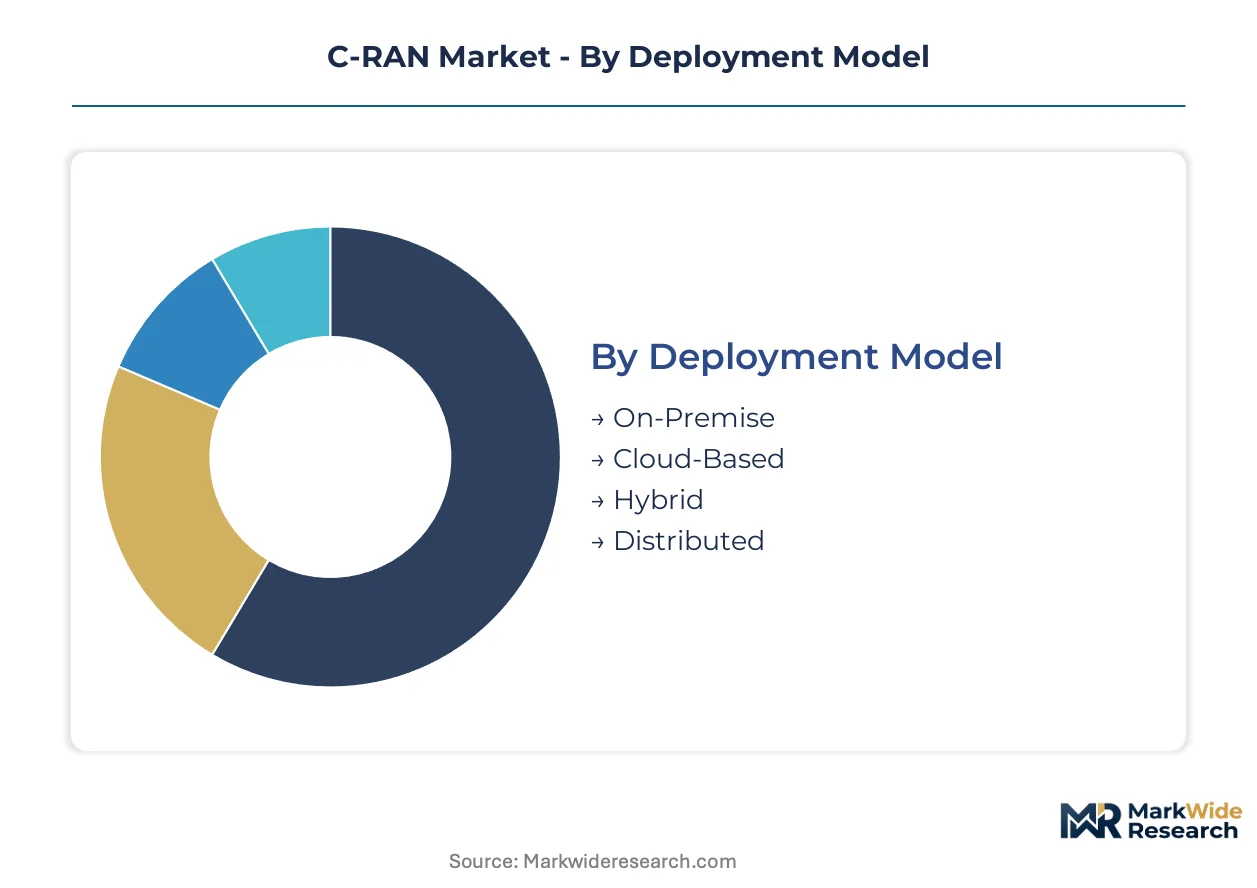
C-RAN segmentation reveals how architectural choices distribute value across hardware, software, and service layers. Deployment models determine capital intensity and operational control, while component types expose where vendor margins concentrate in disaggregated supply chains.
Deployment Model:
Use-case spectrum spans hyperscaler partnerships to sovereign data center requirements.
- On-Premise:Operator-owned data centers house centralized baseband processing pools with direct hardware control. Telecom operators in Germany and Japan favor this model for stadium and industrial campus deployments where latency budgets demand sub-100-microsecond fronthaul coordination.
- Cloud-Based:Hyperscaler infrastructure hosts virtualized baseband functions on Kubernetes-orchestrated containers. Managed service providers in South Korea operationalize this for tier-two operators lacking internal cloud competency, compressing capex cycles through pay-as-you-scale consumption.
- Hybrid:Split-option architectures place real-time functions at cell sites while pooling non-real-time workloads in edge data centers. Enterprises deploying private 5G networks favor this for operational flexibility.
- Distributed:Fully decentralized processing maintains baseband at each radio site, serving legacy backhaul regions where fiber densification remains uneconomical.
Established volume favors On-Premise; emerging adoption favors Cloud-Based.
Component Type:
Cost tier stratification separates commodity hardware from software-defined value capture.
- Remote Radio Units:Massive MIMO antenna arrays with 64T64R configurations dominate component spend due to beamforming complexity and thermal management requirements. German operators concentrate procurement for urban macro layer densification where spectral efficiency gains justify unit premiums.
- Baseband Units:Cloud-native software separates hardware from Layer 2/3 processing, shifting margin pools toward containerized orchestration platforms. South Korean deployments lead in virtualized baseband adoption for 5G standalone core integration.
- Optical Transport Network:Fronthaul fiber links with strict latency budgets connect centralized pools to remote radio heads. Dark fiber deployment rates outpace qualified splicing technician supply in fiber-scarce markets.
- Network Management System:API-native orchestration platforms enable multi-vendor interoperability under O-RAN Alliance specifications, elevating system integrator influence in deployment workflows.
Hardware margins concentrate in Remote Radio Units; software value migrates toward Baseband Units.
Technology:
Application maturity separates proven centralization from emerging virtualization architectures.
- Virtualization:Container orchestration decouples baseband software from proprietary hardware, enabling Kubernetes-based scaling that hyperscalers operationalize. ETSI Open RAN standards accelerate adoption by mandating disaggregated interfaces.
- Centralization:Statistical multiplexing of compute resources across pooled cell sites remains the foundational C-RAN value proposition, maximizing utilization in dense urban corridors with fiber-rich infrastructure.
- Cloud Computing:Edge data center placement optimizes workload distribution for non-real-time functions, with EU Green Deal energy standards favoring liquid-cooled centralized facilities over distributed air-conditioned sites.
- Massive MIMO:Advanced antenna techniques demand tight coordination between centralized processors and remote radio heads, driving fronthaul capacity requirements in Japan and South Korea spectrum deployments.
Deployment scale favors Centralization; capability expansion favors Virtualization.
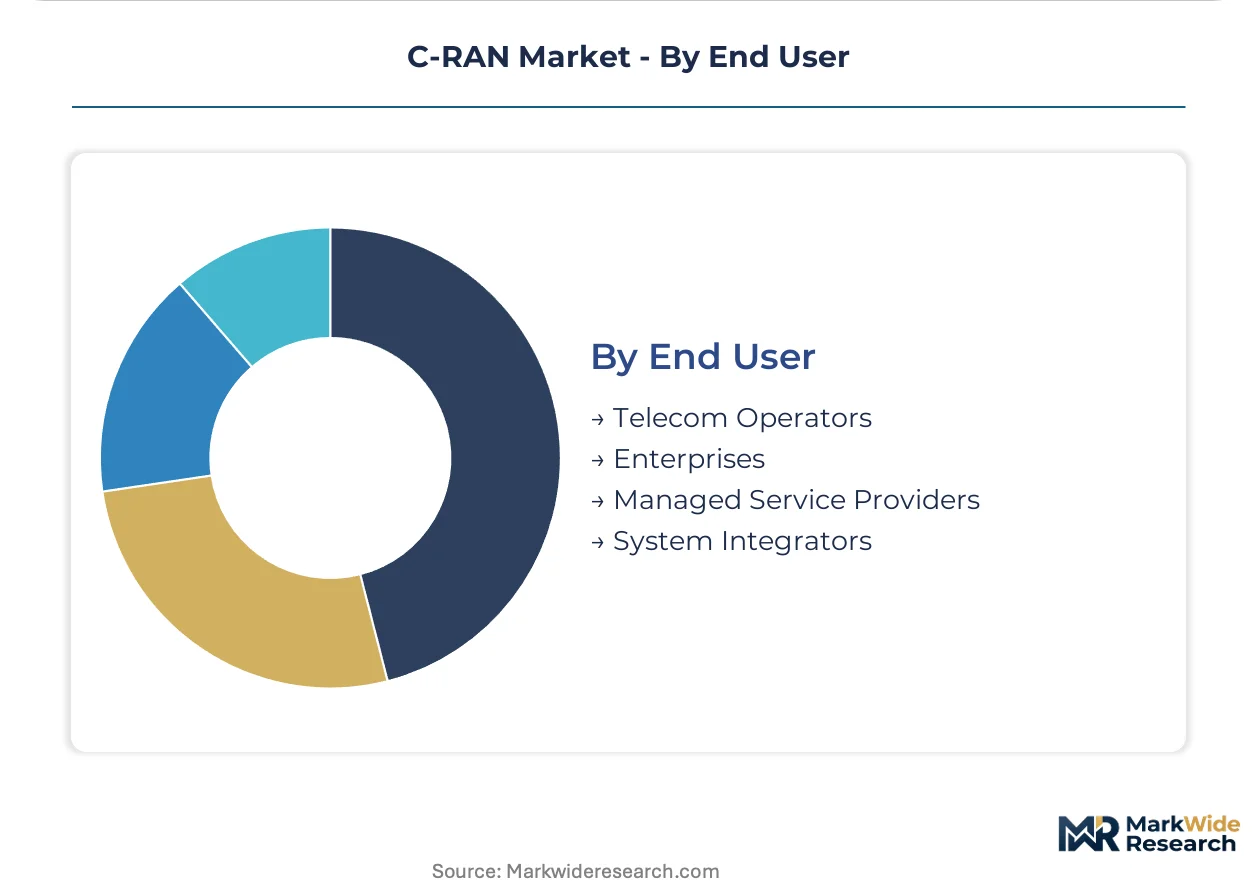
End User:
Customer type determines procurement sophistication and integration complexity tolerance.
- Telecom Operators:Tier-one carriers in Germany, Japan, and South Korea drive volume through 5G spectrum auction commitments and Open RAN mandate compliance, fragmenting historically integrated vendor relationships.
- Enterprises:Manufacturing campuses and logistics hubs deploy private 5G networks with neutral host C-RAN models, particularly in India where TRAI infrastructure sharing directives accelerate unbundling.
- Managed Service Providers:Network-as-a-service financing lowers capital barriers for regional challengers entering deployment without legacy asset bases.
- System Integrators:Multi-vendor qualification overhead elevates their role in O-RAN Alliance conformance testing and deployment workflow orchestration.
Procurement volume concentrates with Telecom Operators; growth velocity favors Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export restrictions on advanced baseband semiconductors reshape supplier eligibility across major economies, while import-dependent markets accelerate domestic equipment certification programs. Spectrum auction commitments in Germany, Japan, and South Korea concentrate deployment capital in fiber-rich urban corridors. Regulatory fragmentation around Open RAN interoperability standards creates qualification overhead that favors vertically integrated suppliers with captive wafer capacity.
United States
FCC spectrum allocation rules compress equipment certification timelines for 5G standalone core integration. National security reviews of foreign telecom equipment under CFIUS frameworks reshape supplier eligibility lists for federal procurement. Dense fiber corridors in the Northeast Corridor and California support massive MIMO centralization projects where statistical multiplexing yields maximum spectral efficiency.
Germany
ETSI Open RAN standards force proprietary stack disaggregation, opening procurement to non-incumbent radio unit suppliers. EU Green Deal energy-efficiency standards create procurement preference for liquid-cooled centralized data centers over distributed air-conditioned cell sites. Industrial clusters in Bavaria and North Rhine-Westphalia anchor private 5G network deployments for manufacturing campuses.
China
MIIT 5G infrastructure directives mandate domestic equipment certification timelines that compress foreign vendor qualification windows. State-backed procurement specifications favor suppliers with in-house semiconductor fabrication through captive wafer capacity. Yangtze River Delta and Pearl River Delta regions concentrate deployment scale among vertically integrated national champions.
Japan
METI industrial policy coordinates spectrum allocation with infrastructure sharing frameworks for railway and stadium corridors. JIS standards interoperability requirements elevate system integrator influence in multi-vendor deployment workflows. Kanto and Kansai regions drive urban fiber densification supporting centralized baseband processing pools.
South Korea
Ministry of Science and ICT spectrum auctions tie deployment commitments to Open RAN interoperability mandates. Government-backed 5G+ R&D programs accelerate cloud-native baseband software adoption through hyperscaler partnerships. Seoul Capital Area and Busan-Ulsan corridors concentrate vRAN deployment for industrial campus and maritime logistics applications.
C-RAN Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: vertically integrated Asian fabricators with captive semiconductor capacity, European optical transport specialists leveraging fronthaul integration expertise, and cloud-native software vendors capturing margin migration toward container orchestration platforms. Incumbent radio access network vendors defend position through split-option flexibility that hybridizes centralized and distributed processing models. Specialist system integrators and test-equipment vendors capture value from O-RAN Alliance multi-vendor qualification overhead.
Among vertically integrated suppliers, Huawei Technologies Co., Ltd. and ZTE Corporation exemplify the captive fabrication archetype that state-backed procurement specifications increasingly favor. Telefonaktiebolaget LM Ericsson occupies a position within the European optical transport tier where fronthaul integration capabilities anchor large-scale centralization projects. Nokia Corporation represents the cloud-native software pivot, competing through containerized baseband platforms against hardware-centric alternatives. Samsung Electronics Co Ltd sits within the Asian integrated tier with demonstrated scale in massive MIMO array deployment.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Huawei Technologies Co., Ltd. |
| ZTE Corporation |
| Samsung Electronics Co Ltd |
| Cisco Systems, Inc. |
| Intel Corporation |
| NEC Corporation |
| FUJITSU |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam maritime freight corridors transmit cost volatility through C-RAN equipment supply chains, amplifying price differentiation between captive-fabrication vendors and import-dependent integrators while compressing margins for neutral host operators without scale purchasing power.
Pricing Analysis
Telecom operators anchor pricing structures around contract-based long-term offtake agreements with incumbent radio access network vendors. Price differentiation separates liquid-cooled centralized baseband pools from air-conditioned distributed cell sites, with EU Green Deal energy-efficiency certification tiers commanding procurement preference. Cost compression in remote radio units intensifies as massive MIMO array commoditization accelerates. Regional challengers exhibit highest price sensitivity due to network-as-a-service financing constraints, while tier-one carriers leverage spectrum auction scale for volume discounts.
Supply Chain Analysis
Export control regimes on advanced baseband semiconductors restrict flows from Taiwan, South Korea, and USA to Chinese equipment fabricators, fragmenting historical supplier relationships. Supply chains draw from captive wafer fabrication in Yangtze River Delta, specialized optical transport component manufacturing in Germany, and massive MIMO antenna array production in Japan. Single-source vulnerability concentrates around 7-nanometer baseband processor supply. Distribution runs through vertically integrated national champions in China, system integrator-led consortia in Germany, and hyperscaler partnership channels in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
C-RAN deployment cycles track 5G spectrum auction waves, positioning the market for cyclical recovery as Germany, Japan, and South Korea release mid-band frequencies for industrial private networks.
For Market Incumbents: Pre-empt disaggregation margin erosion by accelerating split-option architecture roadmaps that hybridize centralized and distributed processing. Threats from cloud-native software vendors capturing orchestration layer value demand defensive R&D intensity in Kubernetes-based baseband platforms. Backward integration into fronthaul fiber deployment capabilities anchors large-scale European centralization projects against specialist optical transport competitors. For New Entrants and Emerging Players: India's railway corridor infrastructure sharing mandates represent underpenetrated white-space for neutral host C-RAN deployment models. Enterprise private 5G networks in German industrial clusters offer second entry vector with lower qualification overhead than tier-one operator procurement. Go-to-market positioning through managed service provider partnerships bypasses direct incumbent competition for cloud competency-constrained buyers. For Investors and Strategic Acquirers: Carve-out targets emerge from telecom equipment divisions undergoing Open RAN restructuring, particularly radio unit specialists with O-RAN Alliance conformance testing capabilities. Long-term viability favors suppliers with demonstrated hyperscaler partnership operationalization and containerized baseband software revenue streams. Signal to watch: MIIT domestic procurement specification revisions accelerating captive supply chain consolidation among Chinese national champions.| Strategic Initiative | Industry Significance |
|---|---|
| Split-Option Architecture Deployment | Hybrid processing models enable Ericsson and Nokia to defend position against cloud-native disaggregation. |
| Hyperscaler Partnership Formation | AWS and Azure collaborations compress capex cycles for South Korean tier-two operators lacking internal cloud competency. |
| O-RAN Alliance Certification Investment | Conformance testing capabilities elevate specialist system integrator influence in German multi-vendor deployment workflows. |
| Liquid-Cooled Data Center Transition | EU Green Deal energy standards create procurement preference advantage over air-conditioned distributed alternatives. |
| Captive Semiconductor Fabrication Expansion | In-house wafer capacity insulates Huawei and ZTE from export control supply disruption in domestic Chinese deployments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with network planning executives at tier-one telecom operators, baseband software engineering leads, optical transport procurement managers, and neutral host infrastructure providers; and secondary validation through FCC equipment authorization databases, MIIT 5G infrastructure directive filings, ETSI Open RAN specification releases, and O-RAN Alliance interoperability test reports. Bottom-up deployment volume estimates triangulated against top-down spectrum auction commitment aggregates.
Forecast inputs considered deployment model segmentation across on-premise, cloud-based, hybrid, and distributed architectures; component type stratification between remote radio units, baseband units, optical transport networks, and network management systems; technology adoption curves for virtualization, centralization, cloud computing, and massive MIMO; and end-user differentiation among telecom operators, enterprises, managed service providers, and system integrators. CAGRs derived from regression analysis of historical deployment trajectories against spectrum release schedules and fiber densification investment cycles.
Practitioners should monitor export control regime expansions, Open RAN mandate enforcement timelines, and hyperscaler partnership exclusivity terms for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Core Market
Telecommunications
Nigeria Telecom Market
Telecommunications
5G System Integration Market
Telecommunications
Peru Telecom Market
Telecommunications
DWDM System Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
South Africa Telecom Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
5G in Defense Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Mftpaas Market
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Spain ICT Market