
 Home Beer Brewing Machine Market | 2026-2036
Home Beer Brewing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Home Beer Brewing Machine Market Outlook
The EU F-Gas Regulation is repositioning appliance manufacturers toward low-global-warming-potential refrigerants and energy-efficient heating elements in brewing hardware. Grainfather leverages its vertical integration into stainless-steel fabrication to control component quality across its all-in-one systems. PicoBrew anchors its position through proprietary recipe-cloud connectivity that sustains recurring engagement from home brewers. Speidel differentiates by dominating the European kettle segment with German-engineered temperature precision.
A home beer brewing machine is an electromechanical or manually operated appliance designed to execute mashing, boiling, fermentation, and conditioning of malt-based beverages within residential or small-scale settings, typically incorporating stainless-steel vessels, digital temperature controllers, and pump-driven recirculation systems rated between 1 and 10 gallon capacities. All-in-one systems capture the largest revenue share by collapsing multiple brewing stages into single-footprint units that appeal to space-constrained urban consumers. Automated technology is expanding fastest as Bluetooth-enabled systems with programmable mash schedules reduce operator error and improve batch consistency for hobbyists. Electric systems lead in margin pools due to higher unit economics and compatibility with smart-home energy management protocols.
The US Department of Energy appliance standards and the EU Ecodesign Directive shape minimum efficiency thresholds for heating elements and pump motors, directly influencing R&D allocation and product roadmaps. The FDA's Food Code provisions on home food processing equipment and the EU's CE marking requirements for electrical safety create compliance layers that filter out low-cost, uncertified entrants. Stakeholders must monitor how evolving energy-labeling regimes and state-level home alcohol production limits in the US reshape addressable demand and distribution eligibility.
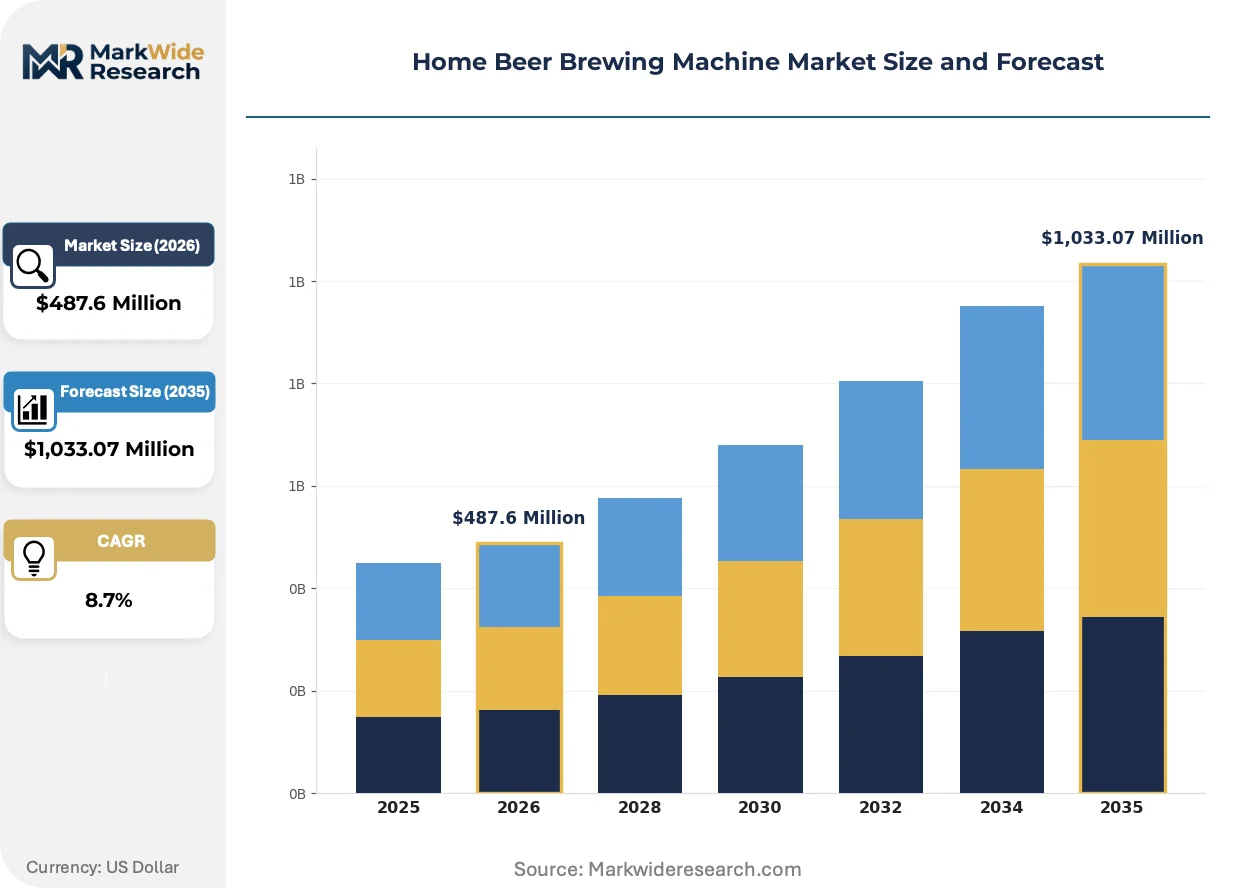
Market Dynamics
The EU F-Gas Regulation and US Department of Energy appliance standards are forcing simultaneous redesigns of heating elements and refrigerant systems, compressing product development cycles while elevating compliance costs for manufacturers targeting transatlantic distribution.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency thresholds for electric heating elements accelerate replacement demand among German and Dutch hobbyists seeking certified systems.
- Smart-home integration:Bluetooth-enabled mash schedule programming attracts tech-forward urban millennials in Seattle and Copenhagen who prioritize batch consistency.
- Stainless-steel supply localization:Captive fabrication capabilities in Wisconsin and Bavaria reduce component lead times for premium all-in-one system manufacturers.
Market Restraints
- Copper and nickel price volatility:Input cost swings for kettle alloys compress gross margins on mid-tier electric systems.
- FDA Food Code fragmentation:State-level home alcohol production limits in Utah, Alabama, and Mississippi restrict addressable demand and channel eligibility.
- Manual system substitution:Low-cost stovetop brewing setups retain preference among price-sensitive hobbyists in Eastern Europe.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Norway show rising interest in compact countertop systems among apartment-dwelling craft beer enthusiasts.
- Recipe-cloud subscription models:Recurring revenue streams from proprietary ingredient packs and fermentation profiles deepen customer lifetime value.
- CE marking harmonization:Unified electrical safety certification across EU member states reduces duplicate testing costs for new entrants.
Industry Challenges
- Microbiology skill gaps:Home brewers lack training in contamination prevention, elevating return rates and warranty claims.
- CE marking timeline compression:Accelerated EU conformity assessment procedures strain quality assurance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Beer Brewing Machine Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-in-One Systems, Fermenters, Kettles, Brewing Kits Capacity: 1 Gallon, 5 Gallon, 10 Gallon, Custom Size Technology: Electric, Manual, Automated, Hybrid End User: Home Brewers, Hobbyists, Small Scale Producers, Educators |
| Companies Covered | Grainfather, HOPii, Brewie, Brauhaus Technik, Czech Brewery System, PicoBrew, iGulu, Speidel, MiniBrew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Beer Brewing Machine Market Strategic Shifts
Electrification of heating systems is converging with connected-device protocols to reshape how hobbyists interact with brewing hardware. Regulatory pressure on refrigerants and energy consumption is accelerating hardware redesign cycles.
Induction heating technology is electrifying traditional resistive-element kettles by delivering faster boil times and precise temperature stability. Urban apartment brewers in Berlin and Portland are adopting these systems at accelerating rates. This shift is electrifying the premium tier while rendering basic electric coils obsolete in space-constrained kitchens.
The EU F-Gas Regulation is mandating low-global-warming-potential refrigerants in fermentation chamber cooling systems. Appliance manufacturers must redesign compressor architectures and retest thermal performance. German-engineered systems face the steepest compliance curve due to their dominant share of temperature-controlled brewing hardware.
Direct-to-consumer ingredient subscription models are displacing traditional homebrew shop retail. Specialty malt and hop suppliers now bypass distributors to reach hobbyists through proprietary mobile apps. This channel shift is most visible in California and Ontario, where craft beer culture intersects with e-commerce maturity.
Home Beer Brewing Machine Market Segmentation
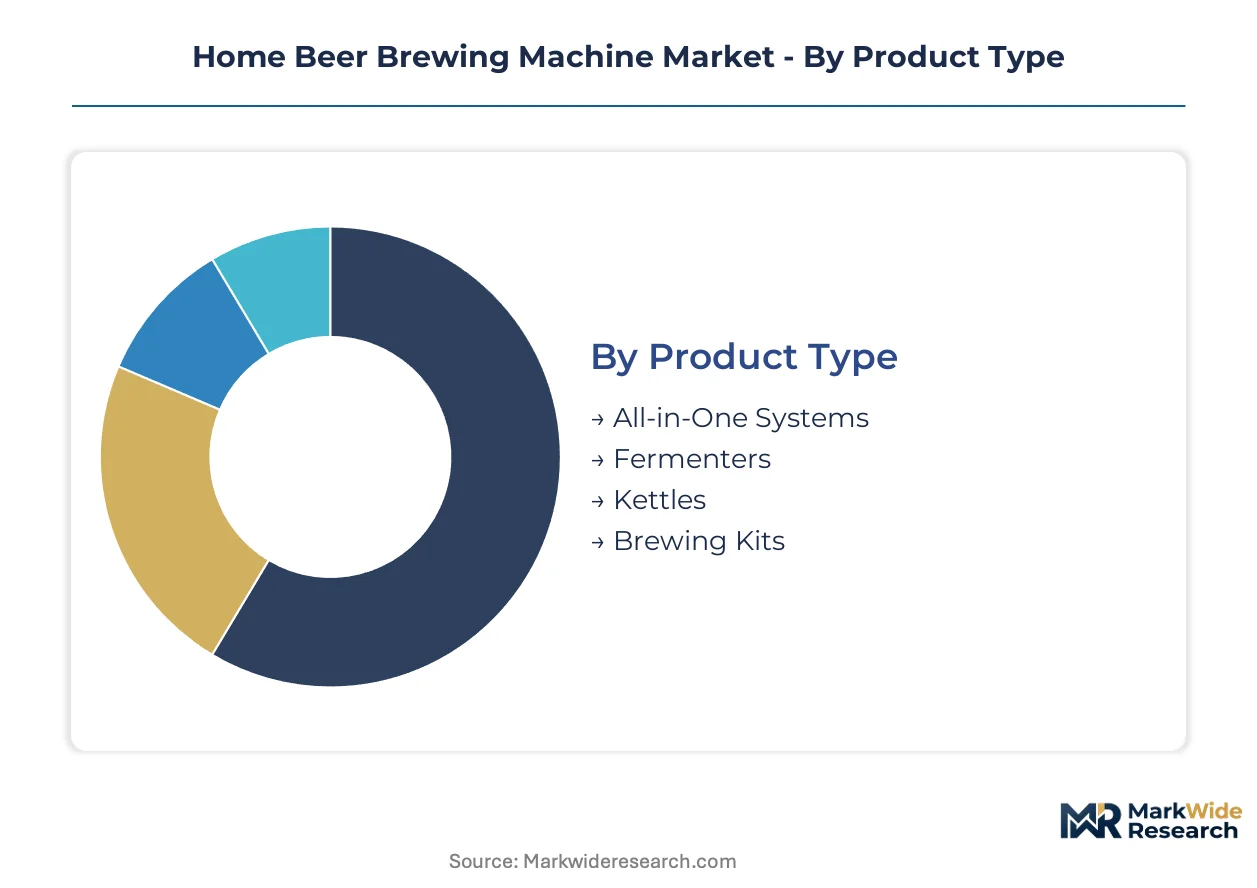
Segmentation in home beer brewing machines reveals how supply-side capabilities align with distinct user workflows. Manufacturers configure stainless-steel fabrication, heating architectures, and control systems differently for space-constrained apartments versus garage-scale operations.
Product Type:
Supply concentration in Bavarian and Wisconsin metalworking clusters favors integrated system producers with captive fabrication capabilities.
- All-in-One Systems:Single-footprint units consolidate mashing, boiling, and fermentation stages through pump-driven recirculation and digital temperature controllers. Demand concentrates among urban millennials in Berlin and Seattle where kitchen space constraints override modularity preferences. Grainfather and PicoBrew anchor this tier through backward integration into stainless-steel vessel production.
- Fermenters:Temperature-controlled chambers with compressor-based cooling systems enable precise conditioning cycles. Speidel dominates European demand through German-engineered thermal precision, though EU F-Gas Regulation compliance is elevating redesign costs for refrigerant architectures.
- Kettles:Standalone boiling vessels with resistive or induction heating elements serve brewers who source fermentation hardware separately.
- Brewing Kits:Entry-level stovetop configurations with basic pots and sanitization supplies retain preference among price-sensitive hobbyists in Eastern Europe.
Today's leader: All-in-One Systems. Tomorrow's challenger: Fermenters.
Capacity:
Cost tier differentiation separates premium precision engineering from commoditized volume production.
- 5 Gallon:The standard batch size for North American homebrewing tradition balances ingredient accessibility with manageable fermentation logistics. This tier captures the deepest installed base among Seattle and Portland hobbyists seeking consistency without industrial-scale commitment.
- 1 Gallon:Compact countertop systems enable apartment-dwelling enthusiasts in Copenhagen and Stockholm to experiment with recipe variables before scaling. Induction-compatible designs are gaining share fastest in Nordic markets where kitchen footprints are smallest.
- 10 Gallon:Larger vessels target semi-commercial producers and club brewing collectives with dedicated utility space.
- Custom Size:Bespoke configurations accommodate specialized grain bills or barrel-aging workflows for advanced practitioners.
The 5-gallon tier commands margin premiums through precision components; 1-gallon systems are expanding most quickly via urban channel penetration.
Technology:
Application-specific heating and control architectures determine compatibility with smart-home protocols and energy-labeling regimes.
- Electric:Resistive-element and induction systems dominate margin pools through higher unit economics and DOE appliance standards compliance. Portland and Copenhagen apartment brewers are electrifying fastest as induction delivers sub-10-minute boil times with programmable stability.
- Automated:Bluetooth-enabled mash schedule programming with cloud-connected recipe libraries reduces operator error for consistency-focused hobbyists. This tier is climbing the fastest as firmware updates extend hardware lifecycles and deepen recurring engagement.
- Manual:Stovetop configurations with analog thermometers serve traditionalists and developing-market price sensitivity.
- Hybrid:Modular designs allow manual override of automated sequences for users seeking graduated skill-building.
Electric systems anchor current profitability; automated architectures are gaining share fastest through subscription-linked revenue models.
End User:
Customer type fragmentation across skill levels and production intent shapes warranty terms, instructional content investment, and channel strategy.
- Home Brewers:Residential enthusiasts executing full brewing cycles for personal consumption represent the core addressable market. Microbiology skill gaps in this segment elevate return rates and warranty claims, pressuring manufacturers to expand video-based contamination prevention training.
- Hobbyists:Casual experimenters prioritizing social brewing experiences over technical mastery favor 1-gallon electric systems with simplified cleaning protocols.
- Small Scale Producers:Nano-brewery operators and farmstead beverage businesses leverage 10-gallon automated systems for limited commercial distribution where state licensing permits.
- Educators:University fermentation science programs and culinary institutes require CE-marked systems with data-logging capabilities for curriculum integration.
Home Brewers dominate current volume; Small Scale Producers represent the steepest expansion trajectory as licensing liberalization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home brewing machinery traces its commercial origins to Bavaria's centuries-old brewing culture, where precision temperature control traditions spawned the first automated kettle systems. German engineering standards subsequently shaped global product architectures for thermal stability and vessel durability.
United States
Seattle and Portland apartment dwellers drive demand for compact induction-compatible systems that deliver sub-10-minute boil times. The Department of Energy appliance standards enforce minimum efficiency thresholds for electric heating elements, compressing development cycles for transatlantic exporters. Wisconsin metalworking clusters supply captive stainless-steel fabrication to premium all-in-one manufacturers.
Germany
Berlin's urban millennials merge smart-home adoption with Reinheitsgebot-influenced brewing traditions, creating demand for Bluetooth-enabled mash controllers. The EU F-Gas Regulation mandates low-global-warming-potential refrigerants in fermentation cooling systems, forcing compressor redesigns. Bavarian vessel fabricators dominate European supply through backward integration into precision temperature hardware.
Sweden
Stockholm's space-constrained apartment brewers favor 1-gallon countertop systems with simplified cleaning protocols. CE marking harmonization across EU member states reduces duplicate electrical safety testing for equipment importers. Nordic kitchen footprints accelerate induction heating adoption faster than resistive-element alternatives.
Canada
Toronto and Vancouver hobbyists intersect craft beer culture with mature e-commerce channels for direct-to-consumer ingredient subscriptions. Health Canada electrical safety requirements parallel CE marking standards, streamlining certification for European exporters. Ontario's fermentation science programs generate institutional demand for data-logging curriculum equipment.
Netherlands
Amsterdam and Rotterdam urban consumers prioritize batch consistency through automated mash scheduling. The EU Ecodesign Directive accelerates replacement demand among Dutch hobbyists seeking certified energy-efficient systems. Randstad logistics infrastructure enables rapid distribution of compact systems to apartment-dwelling enthusiasts.
Home Beer Brewing Machine Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent manufacturing models. Stainless-steel foundries with captive fabrication capabilities command premium positioning through vessel quality control, while assembly-focused brands rely on contract manufacturing for cost-tier penetration. Three archetypes dominate: vertically integrated precision engineers, cloud-connected platform builders, and regional kettle specialists. Competitive maneuvering concentrates on backward integration into metalworking and proprietary recipe-ecosystem development.
Within the integrated-manufacturing tier, Grainfather exemplifies captive supply chain control through in-house stainless-steel production. PicoBrew anchors the platform-builder archetype with cloud-connected recipe libraries that sustain recurring user engagement. Speidel occupies a position among European precision specialists, representing German-engineered thermal control traditions. These three players illustrate how divergent capability investments—fabrication depth, software ecosystems, and regional engineering heritage—create non-overlapping competitive terrain.
| Leading Market Players |
|---|
| Grainfather |
| HOPii |
| Brewie |
| Brauhaus Technik |
| Czech Brewery System |
| PicoBrew |
| iGulu |
| Speidel |
| MiniBrew |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between CE-marked precision systems and uncertified manual alternatives bifurcates the market into premium automated tiers and commoditized entry-level equipment, with this split manifesting in both component sourcing strategies and final price positioning across German-engineered and Asian-assembled supply chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with CE certification and induction heating technology commanding the widest spreads. Stainless-steel grade and smart-home protocol compatibility differentiate the premium tier from resistive-element manual systems. Pricing pressure stems from copper and nickel alloy volatility compressing margins on mid-tier electric kettles. Hobbyists in Eastern Europe exhibit highest price sensitivity, while Seattle and Copenhagen apartment brewers absorb premium positioning for space-constrained induction designs.
Supply Chain Analysis
Skilled metalworking labor availability in Bavaria and Wisconsin anchors precision vessel fabrication, while assembly operations draw from lower-cost Eastern European and Mexican manufacturing zones. Stainless-steel sheet, temperature controller modules, and compressor refrigerant systems constitute critical input dependencies. Single-source vulnerability concentrates in Bavarian thermal engineering specialists serving fermentation cooling architectures. Distribution runs through direct-to-consumer channels and specialty homebrew retailers, with ingredient subscription platforms bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in automated system tiers where firmware-linked ingredient subscriptions transform hardware sales into recurring revenue streams, while induction heating adoption in urban kitchens justifies premium positioning.
For Market Incumbents: Extend backward integration into stainless-steel foundry operations to defend against input cost volatility and quality inconsistency from contract fabricators. Deepen proprietary recipe-cloud ecosystems to lock in switching costs against emerging platform competitors. Prioritize CE marking pre-certification to compress EU market entry timelines for new product families. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription bundles targeting underpenetrated Nordic apartment markets where compact 1-gallon systems face limited established competition. Exploit white space in educational institutional procurement for data-logging fermentation curriculum equipment. Anchor initial positioning through simplified cleaning protocols addressing microbiology skill gaps that elevate incumbent warranty costs. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-connected platform builders lack captive fabrication capabilities and face margin erosion from stainless-steel supply bottlenecks. Long-term viability favors vertically integrated precision engineers with proprietary thermal control IP over assembly-dependent brands. Monitor EU F-Gas Regulation compliance timelines as inflection indicator for refrigeration-dependent fermentation hardware valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless-Steel Fabrication | Captive vessel production insulates Grainfather and Speidel from alloy price swings and quality variance. |
| Recipe-Cloud Platform Development | PicoBrew's proprietary ingredient subscription transforms one-time hardware purchases into recurring revenue streams. |
| CE Marking Harmonization Investment | Pre-certified electrical safety reduces duplicate testing costs and accelerates EU market penetration timelines. |
| Induction Heating Architecture Shift | Sub-10-minute boil times in Portland and Berlin apartments justify premium pricing over resistive-element alternatives. |
| Educational Channel Partnership | Ontario fermentation science programs and culinary institutes generate institutional demand for data-logging curriculum systems. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with product development leads at brewing equipment manufacturers, procurement managers at specialty malt distributors, and regulatory affairs specialists navigating FDA Food Code and EU Ecodesign compliance. Secondary validation drew from DOE appliance standard filings, EU F-Gas Regulation implementation guidance, customs trade data on stainless-steel imports, and SEC disclosures from publicly traded parent companies. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Historical reference periods anchored the projection horizon through documented replacement cycles for electric brewing systems and fermentation hardware upgrade patterns. Segmentation dimensions spanned product architecture, heating technology, capacity tier, and end-user skill level, with geographic regulatory clusters layered across country-specific compliance pathways. CAGRs derived from fitted growth curves applied to installed base expansion and premium tier penetration rates, incorporating smart-home protocol adoption curves and induction heating cost-down trajectories as industry-specific inputs.
Several conditions sit outside the modeled scope, including state-level home alcohol production limit liberalization timelines, copper and nickel commodity price shock scenarios, and compressor refrigerant technology transition costs under EU F-Gas mandates. Forecasts reflect assumptions on urban millennial household formation rates and craft beer culture diffusion patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
South Africa Beverages Market