
 Ready to Drink Cocktails Market | 2026-2036
Ready to Drink Cocktails Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Drink Cocktails Market Intelligence
Millennial and Gen-Z consumers is rotating toward convenience-oriented alcohol formats, displacing traditional at-home mixing occasions. Diageo leverages its global spirits portfolio to anchor premium RTD lines across multiple base categories. Bacardi Limited specializes in rum-based canned offerings that dominate Caribbean-influenced flavor profiles. Brown-Forman sustains whiskey-based RTD development through established bourbon supply chains.
Ready to drink cocktails are pre-mixed alcoholic beverages typically containing distilled spirits, flavoring agents, and carbonation or still bases, packaged in single-serve formats with alcohol by volume ranging from 4% to 12%. These products serve commercial and residential consumers seeking bar-quality cocktails without equipment, ingredient procurement, or preparation expertise. Vodka-based and tequila-based formulations occupy the largest volume positions, while whiskey-based segments command premium price tiers due to longer aging requirements and higher input costs. Aluminum cans capture share from glass bottles in off-premise channels, driven by portability, reduced shipping weight, and recycling infrastructure compatibility.
The U.S. Alcohol and Tobacco Tax and Trade Bureau governs formula approval, labeling, and tax classification for malt-based and spirits-based RTD products, creating compliance costs that favor producers with established regulatory affairs capabilities. The FDA oversees ingredient safety and allergen disclosure requirements for flavor additives and non-alcohol components. State-level alcohol beverage control boards impose additional distribution restrictions that shape channel access, with some jurisdictions limiting RTD sales to licensed liquor stores rather than grocery or convenience outlets. Stakeholders must monitor evolving federal definitions that distinguish beer-based, wine-based, and spirits-based RTDs, as reclassification would trigger tax rate changes and distribution pathway disruptions.
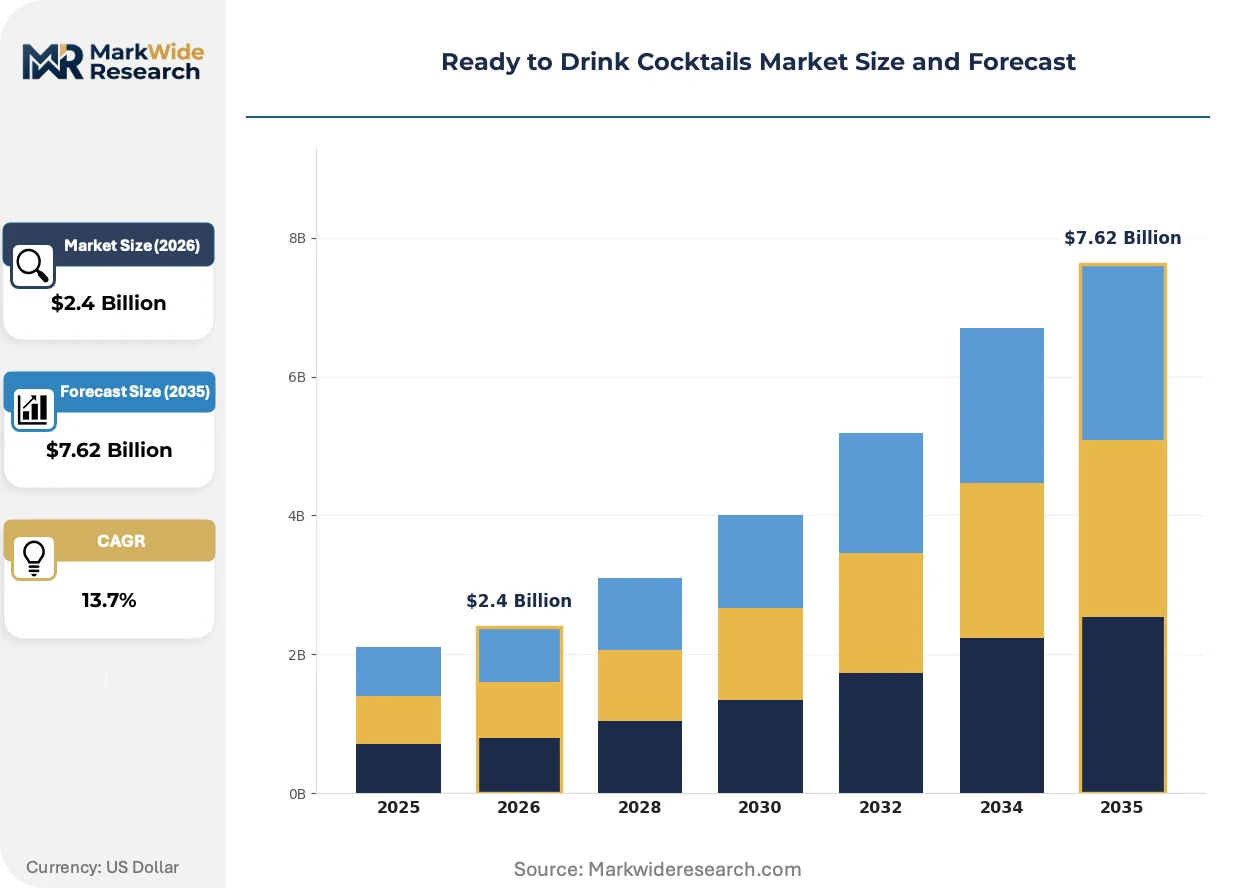
Market Dynamics
Reformulation mandates from the U.S. Alcohol and Tobacco Tax and Trade Bureau are forcing producers to reclassify malt-based products, compressing margins and reshaping portfolio strategies across spirits-based and wine-based alternatives.
Growth Catalysts
- E-commerce channel expansion:Young urban professionals in metropolitan United States coastal cities are consolidating purchasing through digital platforms, accelerating adoption of aluminum can formats over traditional glass packaging.
- Flavor innovation pipelines:Caribbean-influenced rum-based profiles and agave-forward tequila formulations are capturing occasion-based consumption previously served by at-home mixing.
- Recycling infrastructure alignment:Municipal aluminum recovery programs in dense urban jurisdictions are reducing packaging waste costs and improving brand sustainability credentials.
Market Restraints
- Input cost volatility:Aged whiskey stock requirements and agave harvest cycles create multi-year input cost exposure that compresses margin flexibility for premium tier producers.
- Distribution pathway fragmentation:State-level alcohol beverage control boards in jurisdictions limiting RTD sales to licensed liquor stores block grocery and convenience channel access, constraining volume scaling.
- Regulatory classification risk:Federal tax rate reclassification between beer-based, wine-based, and spirits-based RTDs threatens portfolio economics and requires sustained regulatory affairs investment.
Strategic Opportunities
- Underpenetrated suburban markets:Secondary metropolitan ring counties in the United States with limited on-premise nightlife infrastructure present whitespace for residential occasion targeting.
- Flavor additive convergence:Natural botanical extraction technologies paired with precision fermentation are enabling clean-label formulations that satisfy FDA ingredient safety scrutiny.
- Direct-to-retailer distribution:Bypassing traditional three-tier system intermediaries through licensed e-commerce fulfillment centers is reducing channel cost structures.
Industry Challenges
- Formula approval bottlenecks:TTB review timelines for new product submissions extend commercialization cycles, requiring advance pipeline planning and sunk R&D investment.
- Flavor chemist talent scarcity:Specialized expertise in alcohol-stable flavor systems and carbonation retention is concentrating among a limited pool of beverage formulation specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Drink Cocktails Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vodka-Based, Rum-Based, Tequila-Based, Whiskey-Based, Gin-Based, Brandy-Based Packaging Type: Glass Bottles, Aluminum Cans, PET Bottles, Tetra Pak, Plastic Bottles, Cartons Distribution Channel: Supermarkets, Convenience Stores, Liquor Stores, On-Trade Bars, Online Retailers, Events & Festivals End User: Nightclubs, Restaurants, Private Parties, Corporate Events, Hotels |
| Companies Covered | Bacardi Limited, Asahi Group Holdings, Diageo, Anheuser-Busch InBev, Suntory Holdings Limited, Brown-Forman, Constellation Brands, Campari Group, Pernod Ricard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Drink Cocktails Market Strategic Shifts & Innovations
Active reformulation across base alcohol categories is compressing traditional tax distinctions and enabling new product architectures that blur beverage classification boundaries.
Precision flavor encapsulation technology is fragmenting traditional taste delivery systems. This micro-encapsulation approach protects volatile aromatic compounds through thermal processing and shelf-life duration. Premium RTD producers targeting whiskey-based and tequila-based segments are adopting these systems to maintain bar-quality flavor profiles in aluminum can formats. The technology is fragmenting competitive advantage away from distillation scale toward formulation science capabilities.
Updated TTB labeling guidelines for flavored malt beverages are compressing permissible claim language and forcing disclosure of adjunct ingredients previously buried in proprietary formulations. This regulatory tightening elevates compliance costs for smaller producers lacking established regulatory affairs infrastructure. Spirits-based RTD portfolios are capturing shelf space as malt-based competitors navigate reformulation timelines.
Subscription-based replenishment models are displacing traditional retail replenishment cycles for residential consumers. Young professionals in dense urban United States markets are consolidating alcohol purchasing into curated monthly deliveries, reducing impulse purchase dependency. This channel shift is concentrating buyer power among platform operators and compressing brand-direct relationships.
Ready to Drink Cocktails Market Segmentation
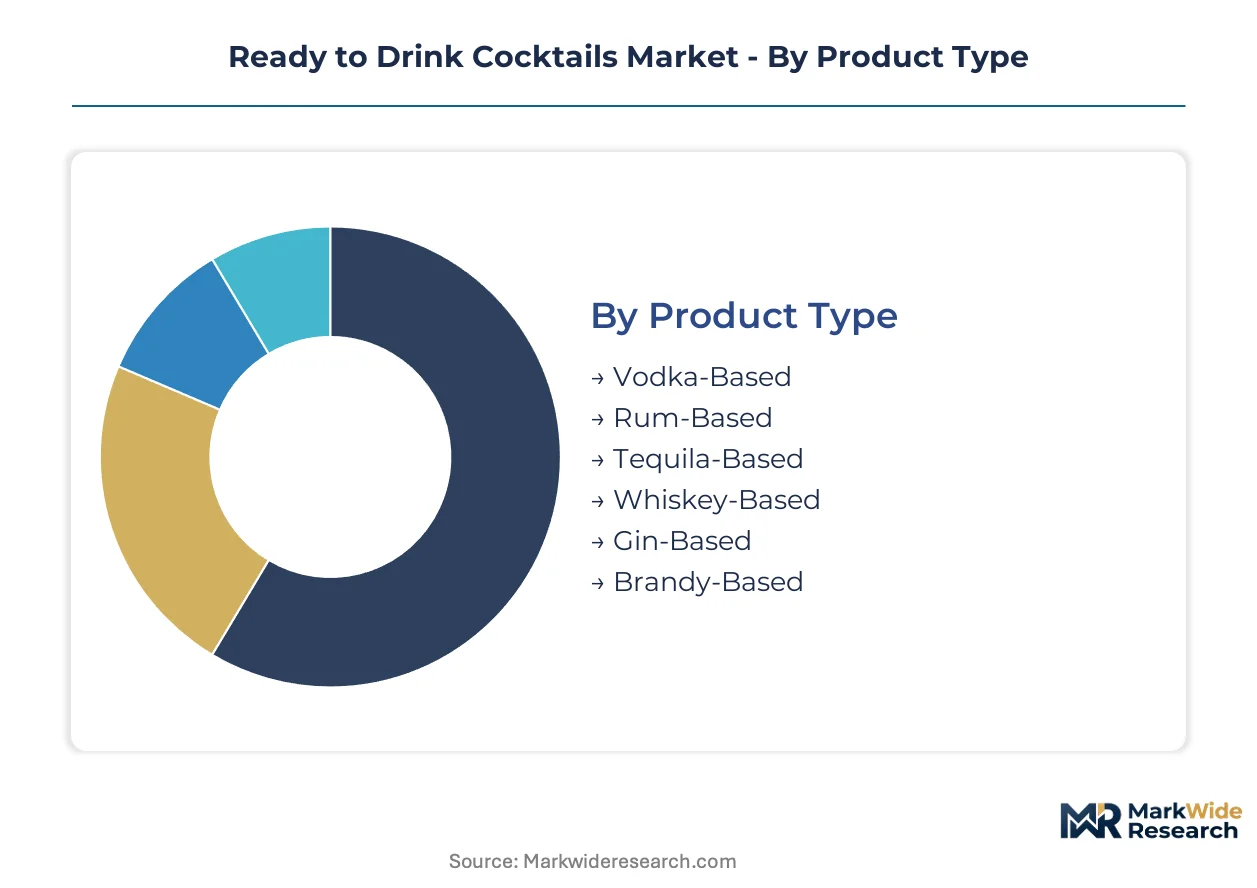
Channel fragmentation in the Ready to Drink Cocktails Market demands precise segment targeting. Each dimension—base spirit, packaging format, distribution pathway, and consumption occasion—carries distinct margin profiles and regulatory exposures that reshape portfolio construction.
Product Type:
Vodka-based and tequila-based formulations flow predominantly through grocery and convenience channels, while whiskey-based variants concentrate in licensed liquor stores and on-trade accounts where premium positioning commands price acceptance.
- Vodka-Based:Neutral spirit bases enable clean flavor delivery systems with minimal aging requirements. Demand concentrates in metropolitan coastal cities among young urban professionals seeking versatile cocktail profiles for residential occasions.
- Tequila-Based:Agave-forward formulations carry supply chain exposure from Mexican harvest cycles but capture premium tier pricing. Expansion concentrates in southwestern United States markets with established tequila consumption culture and through e-commerce subscription models.
- Rum-Based:Caribbean-influenced flavor profiles dominate canned formats for outdoor and festival occasions.
- Whiskey-Based:Aged stock requirements create multi-year input cost exposure that limits volume scaling.
- Gin-Based:Botanical complexity appeals to craft cocktail enthusiasts in on-premise channels.
- Brandy-Based:Niche positioning in dessert-style formulations targets older demographic segments.
Vodka-Based dominates installed base. Tequila-Based is where expansion concentrates.
Packaging Type:
Cost tier alignment separates premium glass presentations from mass-market aluminum and plastic alternatives, with sustainability credentials increasingly influencing format selection across price bands.
- Aluminum Cans:Lightweight construction reduces shipping costs and aligns with municipal recycling infrastructure in dense urban jurisdictions. Demand is accelerating through e-commerce channels serving young professionals in coastal metropolitan areas.
- Glass Bottles:Premium perception sustains placement in liquor stores and on-trade accounts where visual presentation influences selection. Concentration remains strongest in whiskey-based and aged spirit segments where bottle weight signals quality.
- PET Bottles:Shatter-resistant construction serves outdoor event and festival channels.
- Tetra Pak:Aseptic filling technology enables wine-based RTD shelf stability.
- Plastic Bottles:Cost minimization drives large-format value tier offerings.
- Cartons:Emerging format for multi-serve residential consumption occasions.
Glass Bottles dominates installed base. Aluminum Cans is where expansion concentrates.
Distribution Channel:
Application-based channel separation distinguishes immediate consumption occasions from planned residential purchasing, with regulatory fragmentation shaping access geography.
- Online Retailers:Subscription replenishment models consolidate buyer power among platform operators. Young urban professionals in dense metropolitan markets are shifting volume from impulse retail to curated monthly deliveries.
- Liquor Stores:Licensed outlet exclusivity in control states creates protected competitive terrain for spirits-based RTDs. Concentration aligns with premium tier portfolios requiring educated staff recommendation.
- Supermarkets:Grocery channel access varies by state classification rules.
- Convenience Stores:Grab-and-go occasions favor single-serve aluminum can formats.
- On-Trade Bars:Draft and bottled RTD alternatives displace well-drink preparation.
- Events & Festivals:Temporary permits create concentrated volume spikes.
Liquor Stores dominates installed base. Online Retailers is where expansion concentrates.
End User:
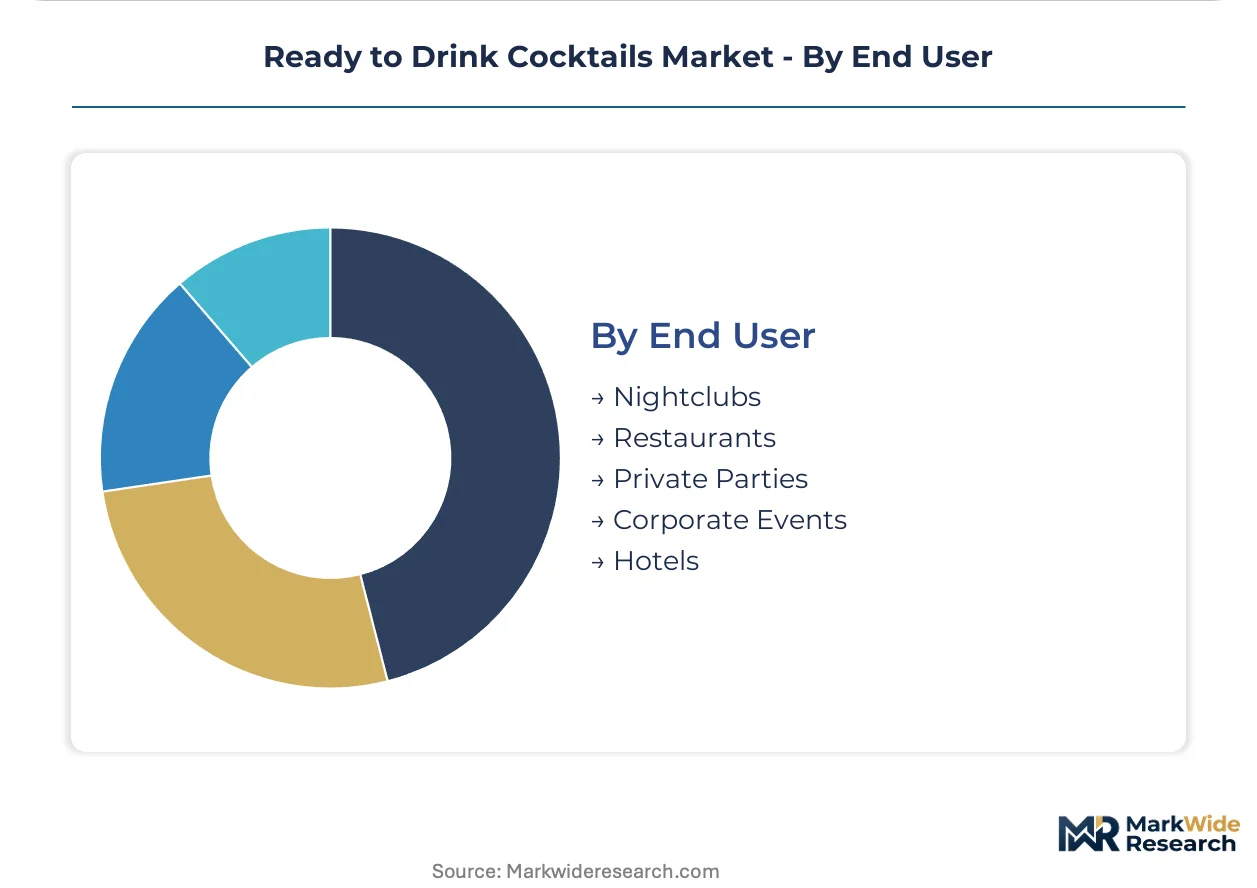
Customer type segmentation separates commercial account purchasing patterns from residential occasion planning, with volume concentration and margin structure diverging sharply across settings.
- Private Parties:Residential occasion planning drives variety pack purchasing and flavor experimentation. Demand concentrates in suburban ring counties surrounding major metropolitan areas where on-premise nightlife access is limited.
- Nightclubs:High-velocity consumption favors standardized formulations with rapid serve capability. Volume concentrates in coastal cities with dense entertainment infrastructure.
- Restaurants:Menu integration requires consistent supply and trained staff.
- Corporate Events:Branded customization and bulk pricing negotiations dominate.
- Hotels:Minibar and poolside placement favor premium single-serve presentations.
Nightclubs dominates installed base. Private Parties is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican agave exports supply tequila-based RTD production for United States coastal markets, while Caribbean rum distilleries feed North American canning operations. Trade flows concentrate base spirit sourcing in Latin America with formulation and packaging occurring near major metropolitan demand centers.
United States
Young urban professionals in New York City and Los Angeles drive aluminum can adoption through e-commerce subscription platforms. The Alcohol and Tobacco Tax and Trade Bureau governs formula approval and tax classification, creating compliance barriers for new entrants. Miami's nightlife infrastructure anchors rum-based RTD consumption for outdoor festival occasions.
Mexico
Jalisco's blue agave harvests supply tequila-based RTD formulations exported to southwestern United States markets. Mexican regulators oversee denomination of origin protections that constrain agave sourcing geography. Guadalajara metropolitan area concentrates distillation capacity for premium agave-forward product lines.
United Kingdom
Gin-based RTD demand concentrates in London's on-premise channels where botanical complexity commands premium positioning. The Food Standards Agency coordinates with HMRC on alcohol duty stamping requirements for canned products. Scotland's whisky-producing regions supply aged stock for bourbon-influenced ready-to-drink formulations.
Japan
Highball culture in Tokyo and Osaka sustains whiskey-based RTD consumption in convenience store channels. The Ministry of Economy, Trade and Industry monitors packaging sustainability standards affecting aluminum recycling rates. Suntory's domestic production facilities in Osaka prefecture anchor supply chain integration for canned cocktail portfolios.
Brazil
Cachaça-based RTD innovation targets residential occasions in São Paulo's suburban ring counties. ANVISA governs ingredient safety and allergen disclosure for flavor additives in canned formulations. Rio de Janeiro's coastal entertainment districts concentrate rum-based product demand for beach consumption occasions.
Ready to Drink Cocktails Market Key Industry Players
Listed leaders compete with private specialists across spirits portfolio breadth, creating a tiered structure where multinational conglomerates anchor premium positioning while regional distillers capture niche flavor profiles. Strategic archetypes include global spirits houses leveraging established distribution, beer conglomerates diversifying beyond malt-based offerings, and specialist distillers defending geographic heritage claims. Dominant competitive moves involve portfolio diversification across base spirit categories and strategic partnerships with flavor technology providers.
Within the global spirits house tier, Diageo, Bacardi Limited, and Brown-Forman occupy positions defined by their respective whiskey, rum, and bourbon heritage portfolios. Diageo's London-based structure exemplifies multinational scale advantages in regulatory affairs compliance. Bacardi Limited represents Caribbean-origin specialization that anchors authenticity claims in tropical flavor profiles. Brown-Forman sits within the American whiskey archetype where aged stock requirements create multi-year competitive moats.
| Leading Market Players |
|---|
| Bacardi Limited |
| Asahi Group Holdings |
| Diageo |
| Anheuser-Busch InBev |
| Suntory Holdings Limited |
| Brown-Forman |
| Constellation Brands |
| Campari Group |
| Pernod Ricard |
| Others |
Cost & Logistics Intelligence
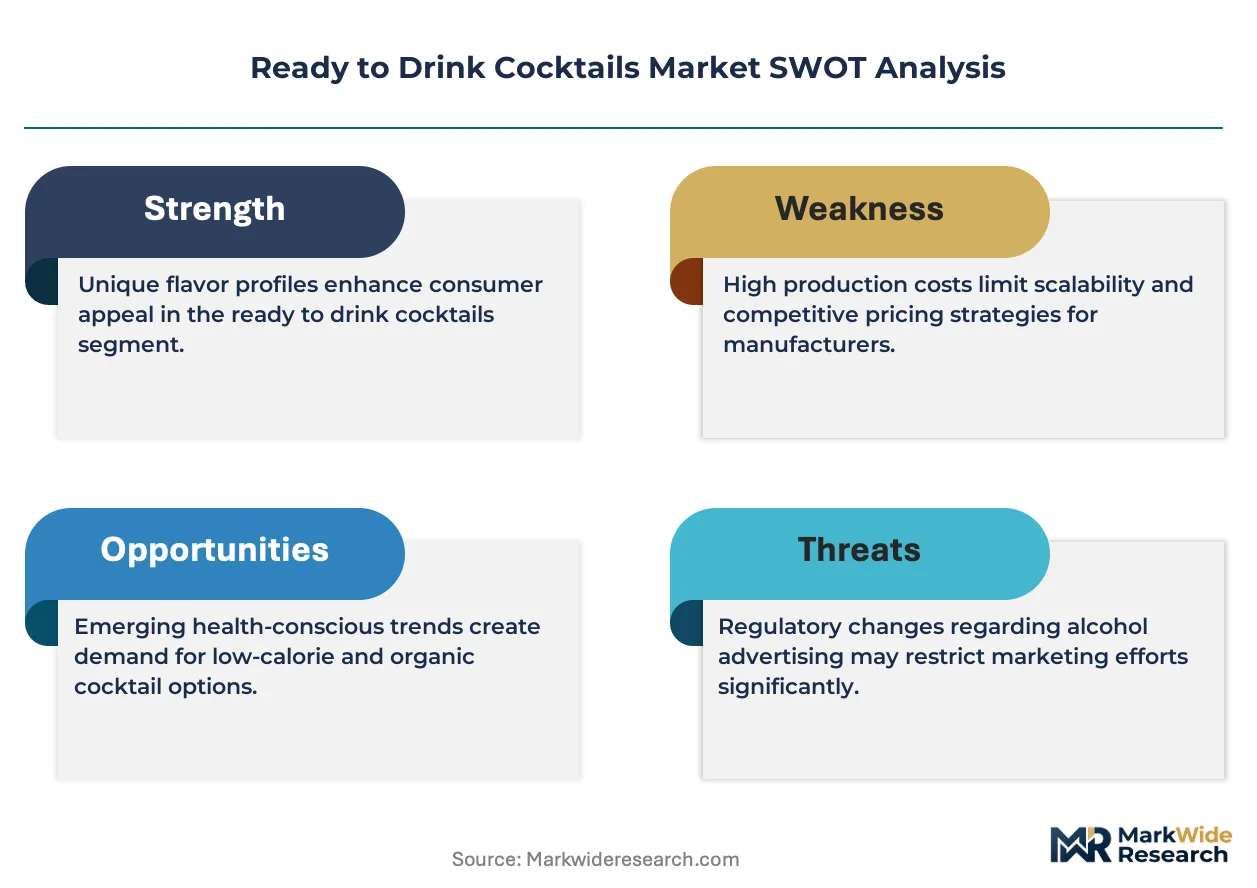
TTB formula approval requirements and state-level distribution classifications simultaneously gate supply qualification and enable price differentiation across spirits-based, wine-based, and malt-based tiers. Producers navigating these regulatory layers command premium positioning in licensed liquor stores while competitors face margin compression in restricted channels.
Pricing Analysis
Next-generation precision flavor encapsulation technology commands 40-60% price premiums over conventional formulation methods, while legacy malt-based portfolios face downward repricing pressure from reformulation mandates. Three-tier pricing structure across premium, standard, and economy levels stratifies by base spirit aging requirements and packaging format, with whiskey-based variants in glass bottles achieving the highest price realization. Cost compression in the malt-based tier is intensifying because TTB reclassification forces ingredient disclosure and formula resubmission. Young urban professionals purchasing through e-commerce subscription platforms exhibit the lowest price sensitivity, while convenience channel shoppers in suburban markets drive volume at economy price points.
Supply Chain Analysis
Strategic stockpiling of aged whiskey inventories and agave reserves dominates over just-in-time approaches due to multi-year maturation cycles and harvest volatility. Mexico, the United States, and Scotland anchor supply concentration for tequila, spirits formulation, and aged whiskey stock respectively. Raw material dependencies center on Mexican blue agave, Caribbean molasses, and American white oak barrels for maturation. Single-source vulnerability in Jalisco agave harvesting creates concentrated weather and disease exposure. Distribution runs through a three-tier system with direct-to-retailer e-commerce fulfillment emerging as a bypass mechanism in permissive jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ready to drink cocktails market is recovering from regulatory-driven portfolio restructuring, with TTB classification clarity enabling renewed capital deployment into spirits-based formulations.
For Market Incumbents: Shield premium positioning by accelerating backward integration into agave estate partnerships and captive whiskey maturation facilities. Diageo, Bacardi Limited, and Brown-Forman should consolidate regulatory affairs capabilities to compress TTB approval timelines below competitor benchmarks. Channel control through licensed liquor store exclusivity agreements defends margin structure against grocery-channel price erosion. For New Entrants and Emerging Players: Anchor in suburban ring counties surrounding Dallas, Atlanta, and Phoenix where on-premise nightlife infrastructure remains underdeveloped and residential occasion planning dominates. Natural botanical extraction technologies paired with precision fermentation offer the most penetrable formulation angle against established flavor chemist talent scarcity. Direct-to-retailer e-commerce fulfillment bypasses three-tier intermediaries in states permitting licensed fulfillment center operations. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage conglomerates divesting non-core RTD portfolios amid spirits-based reclassification strategies. Long-term viability over a 5-10 year window rests on formulation science capabilities displacing distillation scale as the primary competitive moat. Watch for inflection when TTB approves wine-based RTD tax reclassification petitions, which would trigger portfolio restructuring across malt-based incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Flavor Encapsulation Adoption | Micro-encapsulation technology protects aromatic compounds through thermal processing and shelf-life duration in aluminum formats. |
| Direct-to-Retailer E-Commerce Fulfillment | Licensed fulfillment centers in permissive states bypass three-tier system intermediaries and reduce channel cost structures. |
| Agave Estate Backward Integration | Jalisco denomination of origin protections constrain sourcing geography and create captive supply advantages for premium tequila-based lines. |
| Subscription-Based Replenishment Models | Curated monthly deliveries consolidate buyer power among platform operators and reduce impulse purchase dependency for urban professionals. |
| Clean-Label Formulation Investment | Natural botanical extraction paired with precision fermentation satisfies FDA ingredient safety scrutiny and enables premium positioning. |
Research Approach
A spread of perspectives from brand managers at multinational spirits houses, category buyers at e-commerce alcohol platforms, TTB regulatory affairs consultants, and flavor formulation chemists converged on the working assumptions shaping this analysis. Secondary validation drew from TTB formula approval databases, FDA ingredient safety filings, Nielsen retail audit data, and state alcohol beverage control board distribution regulations. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Segmentation dimensions modeled include base spirit category, packaging format, distribution channel regulatory classification, and consumption occasion type. CAGRs were derived from weighted scenario analysis across reformulation timelines, e-commerce penetration curves, and state-level distribution expansion probabilities. Forecast inputs incorporated agave harvest cycle projections, aged whiskey inventory release schedules, and aluminum can supply capacity utilization.
Decision-makers should treat outputs as directional under assumptions of stable TTB classification definitions and sustained e-commerce regulatory permissiveness; material deviation would warrant model refresh. Revision becomes warranted when federal tax reclassification petitions for wine-based RTDs cross approval thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Still Wine Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Low-Alcohol Beer Market