
 Online Investment Platform Market | 2026-2036
Online Investment Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Online Investment Platform Market Intelligence
SEC Registered Investment Adviser qualification is rotating toward algorithmic and API-driven platform architectures, raising technical barriers for new entrants. Fidelity Investments leverages its captive mutual fund ecosystem to sustain integrated wealth management workflows. Charles Schwab anchors its competitive position through scale advantages in trade execution infrastructure. Robinhood competes on zero-commission positioning and mobile-native user acquisition channels.
Online investment platforms are digital intermediaries that match capital providers with securities, funds, or alternative assets through cloud-hosted order management systems, typically processing transactions via FIX protocol or proprietary API gateways with sub-second latency requirements. Their primary commercial purpose is to reduce distribution friction and custody costs between asset originators and fragmented investor bases. Robo-advisory services within the service type dimension are capturing margin pools through automated rebalancing and tax-loss harvesting at scale, while trade execution remains a mature, volume-dependent segment with compressed per-unit economics. The client type split shows retail investors driving user growth velocity, though high net worth individuals concentrate fee revenue and cross-sell potential across wealth management and portfolio analysis offerings.
SEC oversight through Regulation Best Interest and FINRA rulemaking on digital engagement practices are reshaping product design and disclosure architectures for US-domiciled platforms. GDPR and the EU AI Act create parallel compliance obligations for platforms serving European retail clients or deploying algorithmic recommendation engines across borders. Stakeholders must monitor evolving definitions of fiduciary duty in automated advice channels and calibrate technology roadmaps against fragmented supervisory expectations across multiple jurisdictions.
Market Dynamics
Algorithmic execution infrastructure is compressing latency thresholds below 50 milliseconds while SEC Regulation Best Interest and FINRA digital engagement rules force simultaneous compliance investments, creating a dual-track pressure environment where technical capability and regulatory architecture must advance in lockstep.
Growth Catalysts
- Mobile-native brokerage adoption:Millennial and Gen Z retail investors in the United States are migrating wealth management activities to smartphone-first interfaces, expanding addressable user bases for automated portfolio tools.
- API gateway standardization:FIX protocol and proprietary REST architectures enable sub-second order routing, reducing custody friction between fragmented investor bases and asset originators.
- Tax-loss harvesting automation:Robo-advisory engines deploy algorithmic rebalancing at scale, capturing recurring fee streams through systematic portfolio optimization without human adviser intervention.
Market Restraints
- Cloud infrastructure concentration:Platform resilience depends on hyperscale providers in limited geographic zones, creating systemic vulnerability to regional outages or latency spikes.
- SEC disclosure architecture costs:Regulation Best Interest mandates layered documentation workflows that increase compliance overhead for algorithmic recommendation channels.
- Human adviser substitution ceiling:High net worth individuals retain preference for personalized wealth management relationships, capping automated service penetration in premium fee tiers.
Strategic Opportunities
- GDPR-aligned European expansion:Platforms architecting privacy-by-design data frameworks can access EU retail markets with reduced regulatory friction versus retrofitted compliance approaches.
- Alternative asset tokenization:Blockchain settlement layers converging with traditional custody infrastructure enable fractional exposure to real estate and private credit previously reserved for institutional allocators.
- Embedded finance distribution:Banking-as-a-Service partnerships allow investment functionality integration into consumer fintech applications, bypassing standalone customer acquisition economics.
Industry Challenges
- Cybersecurity engineering scarcity:Platform operators face acute competition for talent capable of architecting zero-trust perimeter defenses around real-time transaction processing systems.
- Legacy core banking integration:Established custodians operate on decades-old batch processing architectures that resist real-time API synchronization with modern order management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Investment Platform Market |
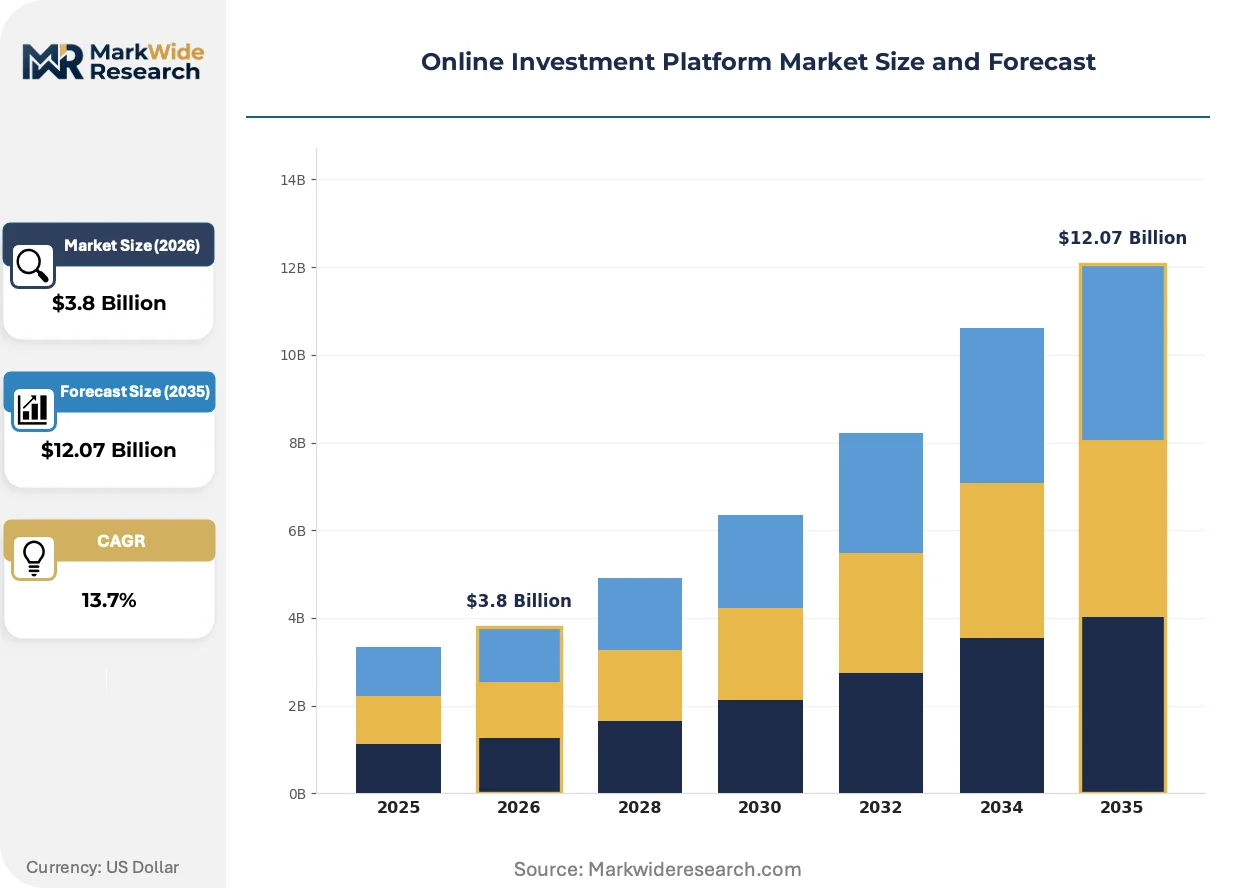
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Growth, Income, Value, Balanced Client Type: Institutional Investors, Retail Investors, High Net Worth Individuals, Corporate Clients Service Type: Wealth Management, Robo-Advisory, Trade Execution, Portfolio Analysis Platform Features: Mobile Access, AI Insights, Automated Trading, Social Investing |
| Companies Covered | BlackRock, E*TRADE, Fidelity Investments, SoFi Active Investing, Webull, Charles Schwab, Robinhood, Wealthfront, Vanguard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Investment Platform Market Strategic Shifts & Innovations
Execution infrastructure and regulatory disclosure frameworks are advancing on parallel tracks, forcing platform architects to engineer simultaneous improvements in latency performance and compliance automation without trading one priority against the other.
Embedded order routing technology is bifurcating platform architectures into two performance tiers. High-frequency capable infrastructure serves institutional and active retail segments demanding microsecond precision, while simplified routing layers satisfy passive investors prioritizing cost minimization over execution speed. This technical stratification enables tiered service pricing without overlapping infrastructure investments.
FINRA rulemaking on digital engagement practices is mandating redesigned disclosure interfaces for US-domiciled platforms. The industrial consequence requires engineering teams to rebuild user-facing recommendation engines with embedded suitability documentation trails. Retail-facing robo-advisory segments are responding by hiring former regulatory examination staff to pre-validate algorithmic logic against enforcement precedent.
Wealth management procurement is fragmenting across unbundled service components. Investors increasingly separate custody, execution, and advisory functions across specialized providers rather than accepting integrated packages from single institutions. This pattern is most visible among mass-affluent segments in the United States, where switching costs have fallen below $50 in aggregate platform transfer fees.
Online Investment Platform Market Segmentation
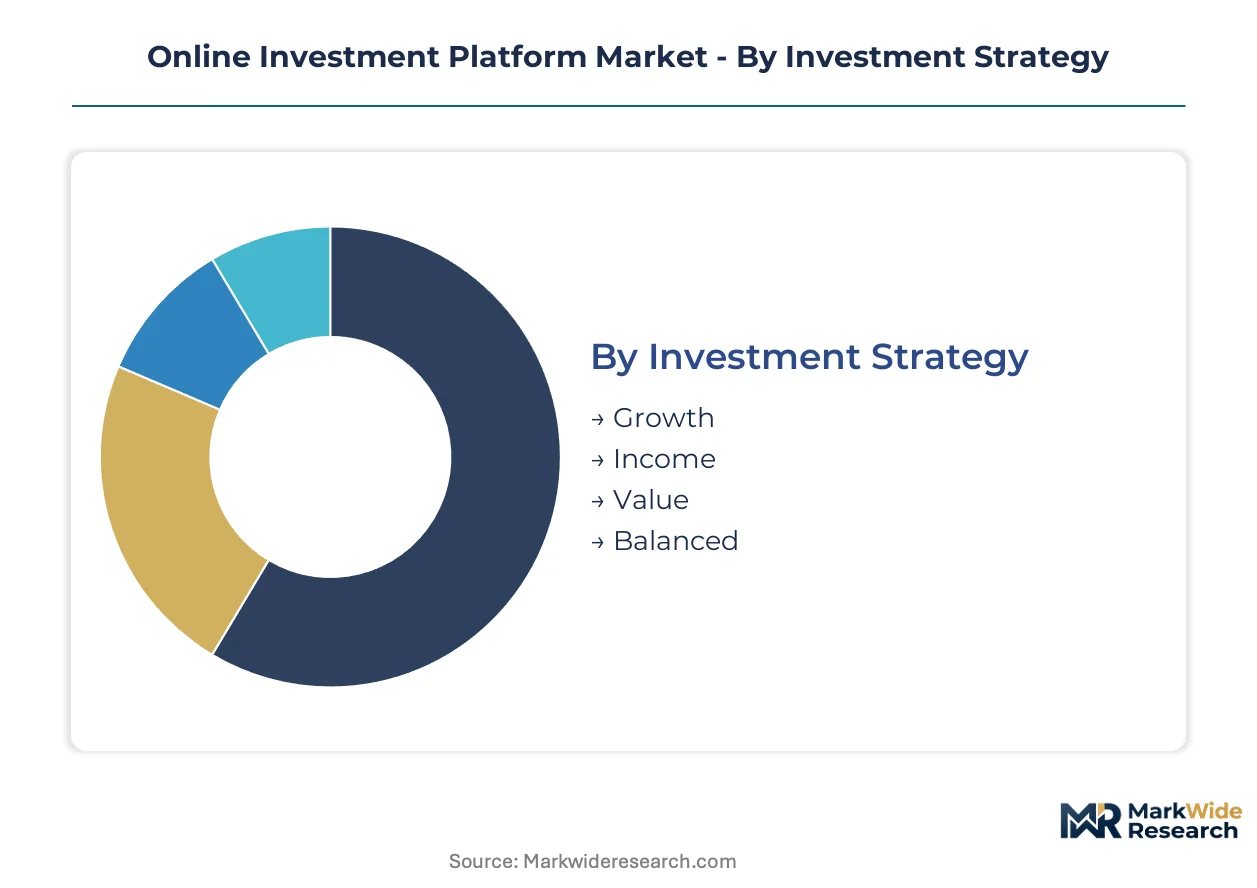
Segmentation in online investment platforms determines how compliance architectures, latency requirements, and fee structures align with distinct investor risk profiles and service expectations. Each dimension carries specific regulatory obligations under SEC, FINRA, and emerging EU AI Act frameworks.
Investment Strategy:
SEC Regulation Best Interest mandates differentiated suitability documentation across risk profiles, with algorithmic recommendation engines requiring embedded audit trails for each strategic category.
- Growth:Aggressive equity and alternative asset allocation targeting capital appreciation through volatile instruments. Millennial and Gen Z retail investors in the United States concentrate here, driven by mobile-native brokerage adoption and extended investment horizons that tolerate drawdown volatility.
- Income:Fixed-income and dividend-focused portfolios emphasizing yield generation over price appreciation. High net worth individuals and corporate treasury departments favor this segment for predictable cash flow matching, though compressed bond yields are constraining target return achievement.
- Value:Systematic identification of underpriced securities using fundamental screening algorithms. Demand clusters among sophisticated retail investors seeking contrarian positioning outside momentum-driven market regimes.
- Balanced:Hybrid equity-fixed income construction maintaining moderate risk exposure across market cycles. Robo-advisory engines deploy automated rebalancing here at scale, capturing recurring fee streams through systematic optimization.
Established volume favors Balanced; emerging adoption favors Growth.
Client Type:
Fee revenue concentration and cross-sell potential vary dramatically across client tiers, with institutional segments demanding FIX protocol integration while retail flows prioritize mobile UX simplicity.
- Institutional Investors:Pension funds, endowments, and asset managers requiring microsecond execution precision and direct market access infrastructure. United States-based allocators drive demand for high-frequency capable order routing with sub-50 millisecond latency thresholds.
- Retail Investors:Individual account holders accessing markets through smartphone-first interfaces. This segment is expanding most quickly among millennial and Gen Z cohorts migrating wealth management activities to zero-commission platforms.
- High Net Worth Individuals:Clients with investable assets above SEC accredited investor thresholds. Personalized wealth management relationships retain preference here, capping automated service penetration in premium fee tiers.
- Corporate Clients:Treasury departments managing excess cash and employee benefit plans. Demand concentrates for custody-execution unbundling and API-driven reporting integration with enterprise ERP systems.
Fee yield concentrates in High Net Worth Individuals; user velocity concentrates in Retail Investors.
Service Type:
Margin architecture diverges between automated scale services and relationship-dependent advisory, with robo-advisory capturing recurring revenue through algorithmic efficiency.
- Wealth Management:Comprehensive financial planning integrating tax, estate, and insurance coordination. High net worth individuals in the United States sustain demand here despite fee compression in passive investment alternatives.
- Robo-Advisory:Algorithmic portfolio construction with automated rebalancing and tax-loss harvesting. This segment is gaining share fastest as platforms deploy systematic optimization without human adviser intervention.
- Trade Execution:Order routing and settlement processing with custody integration. Per-unit economics have compressed significantly, making volume scale essential for profitability.
- Portfolio Analysis:Risk attribution and performance reporting tools for self-directed investors. Demand is climbing among retail segments seeking institutional-grade analytics without advisory fees.
Margin stability favors Wealth Management; automation scalability favors Robo-Advisory.
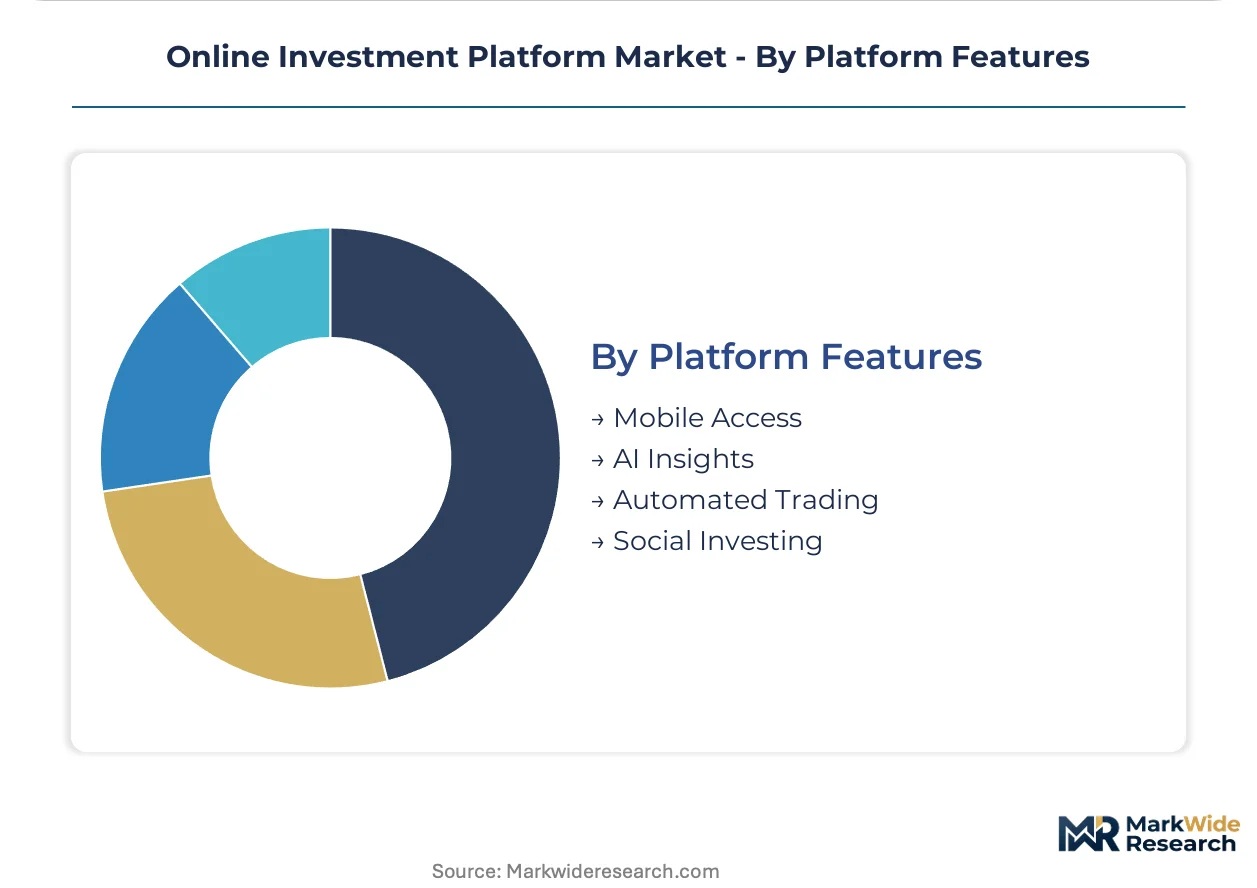
Platform Features:
Technical differentiation now requires simultaneous advancement in latency performance and regulatory disclosure automation, with FINRA digital engagement rules reshaping interface design obligations.
- Mobile Access:Smartphone-native account management with biometric authentication and push notification alerts. United States millennial and Gen Z investors treat this as table stakes, not premium feature.
- AI Insights:Natural language processing of market data and personalized recommendation engines. EU AI Act compliance costs are creating regulatory friction for platforms deploying algorithmic advice across borders.
- Automated Trading:Rule-based order execution triggered by price, volume, or technical indicator thresholds. Active retail segments demand this for strategy implementation without manual monitoring.
- Social Investing:Portfolio transparency and copy-trading functionality enabling mimicry of high-performing peers. SEC scrutiny of gamification risks is constraining feature expansion in this category.
Defensive necessity favors Mobile Access; differentiation potential favors AI Insights.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z retail investors in the United States concentrate platform adoption, with mobile-first brokerage interfaces capturing the fastest user velocity across developed markets. Regulatory divergence between SEC disclosure mandates and EU AI Act compliance costs is fragmenting platform architectures by jurisdiction.
United States
Retail investor migration to zero-commission smartphone interfaces drives platform expansion, particularly among younger cohorts seeking automated portfolio tools. SEC Regulation Best Interest and FINRA digital engagement rules impose layered documentation workflows that increase compliance overhead for algorithmic recommendation channels. New York and San Francisco financial technology clusters host the densest concentration of robo-advisory engineering talent and venture deployment.
Germany
Mass-affluent investors exhibit rising preference for custody-execution unbundling across specialized providers rather than integrated wealth management packages. GDPR and the EU AI Act create parallel compliance obligations for platforms deploying algorithmic advice engines. Frankfurt's banking infrastructure anchors custody integration efforts, while Berlin's startup ecosystem incubates mobile-native brokerage challengers targeting pan-European retail flows.
United Kingdom
Self-directed investors demand institutional-grade portfolio analytics without advisory fees, fragmenting procurement across unbundled service components. The Financial Conduct Authority's consumer duty rules reshape disclosure architectures for digital investment platforms serving UK retail clients. London's asset management concentration sustains demand for high-frequency capable order routing infrastructure with sub-50 millisecond latency thresholds.
Japan
Corporate treasury departments drive demand for API-driven reporting integration with enterprise ERP systems, particularly for custody-execution separation. METI guidelines on financial technology interoperability influence platform technical standards for institutional client onboarding. Tokyo's securities exchange infrastructure and Osaka's regional banking hubs concentrate platform operator technical operations and compliance staffing.
India
Retail investor account growth accelerates through smartphone-first interfaces, with younger demographics bypassing traditional branch-based wealth management relationships. SEBI's tightening disclosure norms for algorithmic trading and investment advisory services elevate technical barriers for new platform entrants. Mumbai's financial district and Bangalore's technology corridor host competing clusters of traditional brokerage incumbents and fintech-native challengers.
Online Investment Platform Market Key Industry Players
Player mix skews toward diversified financial conglomerates with captive asset management ecosystems, though mobile-native specialists carve distinct user acquisition channels. Consolidation pressure intensifies as scale advantages in trade execution infrastructure determine profitability in compressed per-unit economics. Three archetypes dominate: integrated wealth managers with mutual fund manufacturing, zero-commission mobile brokers, and algorithmic robo-advisory engines. Competitive moves concentrate on strategic partnerships for embedded finance distribution and technology licensing for API gateway standardization.
Within the integrated wealth management tier, Fidelity Investments and Charles Schwab exemplify scale-driven positioning through captive fund ecosystems and execution infrastructure ownership. Robinhood occupies a position representing mobile-native zero-commission acquisition strategies targeting younger retail cohorts. These three anchors illustrate the structural divergence between relationship-dependent advisory models and automated self-service platforms competing for overlapping investor segments.
| Leading Market Players |
|---|
| BlackRock |
| E*TRADE |
| Fidelity Investments |
| SoFi Active Investing |
| Webull |
| Charles Schwab |
| Robinhood |
| Wealthfront |
| Vanguard |
| Others |
Cost & Logistics Intelligence
Execution infrastructure scale economies at Charles Schwab and Fidelity Investments compress per-unit clearing costs below smaller competitors' breakeven thresholds, anchoring price floors for retail brokerage services while concentrating custody and order routing capacity in United States financial technology clusters.
Pricing Analysis
Cost-plus contracts with indexation to cloud compute and FIX protocol gateway fees dominate platform-provider agreements. Three-tier pricing structure across premium active-trader, standard self-directed, and economy robo-advisory levels separates execution speed guarantees from basic order routing. Price differentiation rests on latency tier and regulatory compliance bundle depth. Cost compression in standard-tier trade execution is intensifying because zero-commission positioning has eliminated explicit per-trade revenue. Retail investors exhibit highest price sensitivity, while institutional allocators prioritize execution quality over fee minimization.
Supply Chain Analysis
Inventory and lead-time compression for real-time market data feeds now operates below 50 milliseconds, tethering platform resilience to hyperscale cloud concentration in United States East Coast and West Coast zones. Raw material dependencies center on semiconductor chips for co-location servers, subsea fiber capacity for cross-venue connectivity, and proprietary market data licenses from exchanges. Single-source vulnerability concentrates in Amazon Web Services and Microsoft Azure infrastructure serving majority of retail-facing platforms. Distribution runs through API gateway architectures connecting fragmented investor bases to centralized custody and clearing utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are recovering from cyclical compression in per-trade revenue, driven by renewed retail account velocity and automated advisory fee expansion across millennial and Gen Z cohorts.
For Market Incumbents: Secure captive mutual fund manufacturing ecosystems to defend margin position against unbundling pressure from specialized execution and custody providers. Anchor scale advantages in co-located server infrastructure to maintain sub-50 millisecond latency thresholds that active retail segments demand. Deepen API standardization investments to lock in enterprise treasury department workflows before banking-as-a-service partnerships fragment distribution.
For New Entrants and Emerging Players: Lead with embedded finance distribution partnerships that bypass standalone customer acquisition economics in saturated United States retail markets. Target European Union expansion with privacy-by-design data architectures that reduce GDPR and EU AI Act compliance friction versus retrofitted approaches. Penetrate corporate treasury segments through ERP-integrated reporting tools that established custodians have neglected.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among robo-advisory engines with automated rebalancing and tax-loss harvesting capabilities, positioning these archetypes for sustained cash flow quality across the analysis window. Prioritize acquisition targets with algorithmic recommendation engines pre-validated against SEC Regulation Best Interest and FINRA digital engagement precedent. Monitor enforcement actions against gamification features as an inflection indicator for regulatory risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| API Gateway Standardization | FIX protocol and REST architecture convergence enables sub-second order routing across fragmented custody networks. |
| Robo-Advisory Engine Development | Algorithmic portfolio construction with embedded tax-loss harvesting captures recurring fees without human adviser overhead. |
| Embedded Finance Partnership | Banking-as-a-Service integration bypasses standalone customer acquisition costs in saturated retail channels. |
| European Privacy-by-Design Expansion | GDPR-aligned data frameworks reduce regulatory friction versus retrofitted compliance approaches in EU markets. |
| Alternative Asset Tokenization Platform | Blockchain settlement convergence with traditional custody enables fractional real estate and private credit exposure. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC disclosure filings, FINRA regulatory releases, and exchange infrastructure documentation. Primary interviews engaged platform engineering executives, regulatory compliance officers at SEC-registered investment advisers, retail brokerage product managers, and cloud infrastructure procurement leads. Secondary validation drew from exchange co-location agreements, hyperscaler capex disclosures, and venture capital deployment databases tracking fintech-native challengers. Bottom-up account growth modeling and top-down addressable wealth stock estimation triangulate market size outputs.
Segmentation dimensions modeled include investment strategy profile, client type tier, service type architecture, and platform feature configuration across the projection horizon. CAGRs derive from cohort-specific adoption curves calibrated against historical retail brokerage account opening velocity. Forecast inputs incorporate mobile-native user acquisition cost trajectories and automated advisory fee compression elasticities observed across robo-advisory competitive dynamics.
Forecasts assume regulatory continuity in SEC and FINRA frameworks; material policy shifts on fiduciary duty definitions or digital engagement restrictions would require re-modeling. Outputs reflect assumptions on sustained millennial and Gen Z wealth accumulation velocity and hyperscale cloud infrastructure pricing stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Healthcare Finance Solutions Market
Financial Services
Foreign Exchange Services Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Liquidation Service Market
Financial Services
Europe B2B Legal Services Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
India Legal Services Market
Financial Services
Africa Factoring Services Market
Financial Services
E-Invoicing Market
Financial Services
India Security Brokerage Market
Financial Services
Global Treasury Software Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Southeast Asia E-Invoicing Market
Financial Services
Global Business Management Consulting Service Market