
 Factoring Services Market | 2026-2036
Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Factoring Services Market Intelligence
A shortage of certified trade finance underwriters is rotating talent toward technology-enabled platforms that automate credit decisioning. Triumph Business Capital leverages its transportation sector specialization to dominate freight factoring corridors across North America. altLINE sustains competitive positioning through its bank-backed funding model, which offers lower cost of capital than independent funders. eCapital anchors its growth strategy in healthcare and staffing verticals, where invoice cycles are predictable but elongated.
Factoring services constitute a form of accounts receivable financing wherein a business sells its invoices to a third party at a discount, typically advancing 70-90% of invoice value within 24-48 hours while assuming collection risk based on contract structure. The primary commercial purpose is to convert illiquid receivables into immediate operating cash without diluting equity or adding debt to the balance sheet. Recourse factoring retains credit risk with the seller and commands lower discount rates, while non-recourse factoring transfers buyer default risk to the factor at a premium pricing tier. Small businesses represent the fastest-expanding client type as digital onboarding reduces minimum invoice thresholds that previously excluded micro-enterprises.
The European Banking Authority's prudential standards for fintech credit institutions are reshaping capital reserve requirements for cross-border factoring platforms operating under EU passporting rules. In the United States, the Uniform Commercial Code Article 9 governs perfection of security interests in receivables, creating jurisdictional complexity for factors operating across state lines. India's RBI mandates priority sector lending classifications for certain invoice financing products, directing bank-affiliated factors toward agricultural and micro-enterprise supply chains. Stakeholders must monitor how central bank digital currency pilots in major economies could disintermediate traditional invoice verification and settlement rails.
Market Dynamics
Open banking APIs are compressing origination timelines from weeks to hours, forcing traditional factors to restructure their credit decisioning workflows or cede market position to algorithmic platforms.
Growth Catalysts
- Real-time credit scoring:Machine learning models trained on alternative data streams enable instant buyer risk assessment, reducing onboarding friction for micro-enterprises previously excluded by manual underwriting thresholds.
- India's regulatory sandbox:The Reserve Bank of India's fintech licensing framework expands invoice financing access to unbanked suppliers in agricultural and manufacturing supply chains.
- Working capital constraints:Elongated payment terms from large buyers are pushing small and mid-sized enterprises toward receivables monetization as an alternative to dilutive equity raises.
Market Restraints
- Certified trade finance underwriter shortage:Talent scarcity in traditional credit assessment functions limits scaling capacity for human-in-the-loop platforms.
- Cross-border jurisdictional complexity:The Uniform Commercial Code Article 9 in the United States creates perfection-of-security-interest fragmentation across state lines, elevating legal costs for multi-state factors.
- Central bank digital currency pilots:Experimental CBDC programs in major economies threaten to disintermediate invoice verification and settlement rails that factors currently monetize.
Strategic Opportunities
- Healthcare vertical specialization:Predictable but elongated invoice cycles in medical staffing and equipment supply chains create attractive risk-adjusted returns for factors with sector-specific expertise.
- Transportation corridor dominance:Freight factoring in North American logistics hubs offers embedded financing opportunities tied to fuel advances and load matching platforms.
- EU passporting optimization:The European Banking Authority's prudential standards for fintech credit institutions create a path for cross-border platform expansion under unified capital reserve requirements.
Industry Challenges
- Legacy system integration complexity:Enterprise resource planning connectivity requirements delay deployment for factors targeting mid-market manufacturers with heterogeneous technology stacks.
- Recourse versus non-recourse pricing transparency:Buyer default risk transfer mechanisms vary opaquely across contracts, complicating customer education and competitive positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Factoring Services Market |
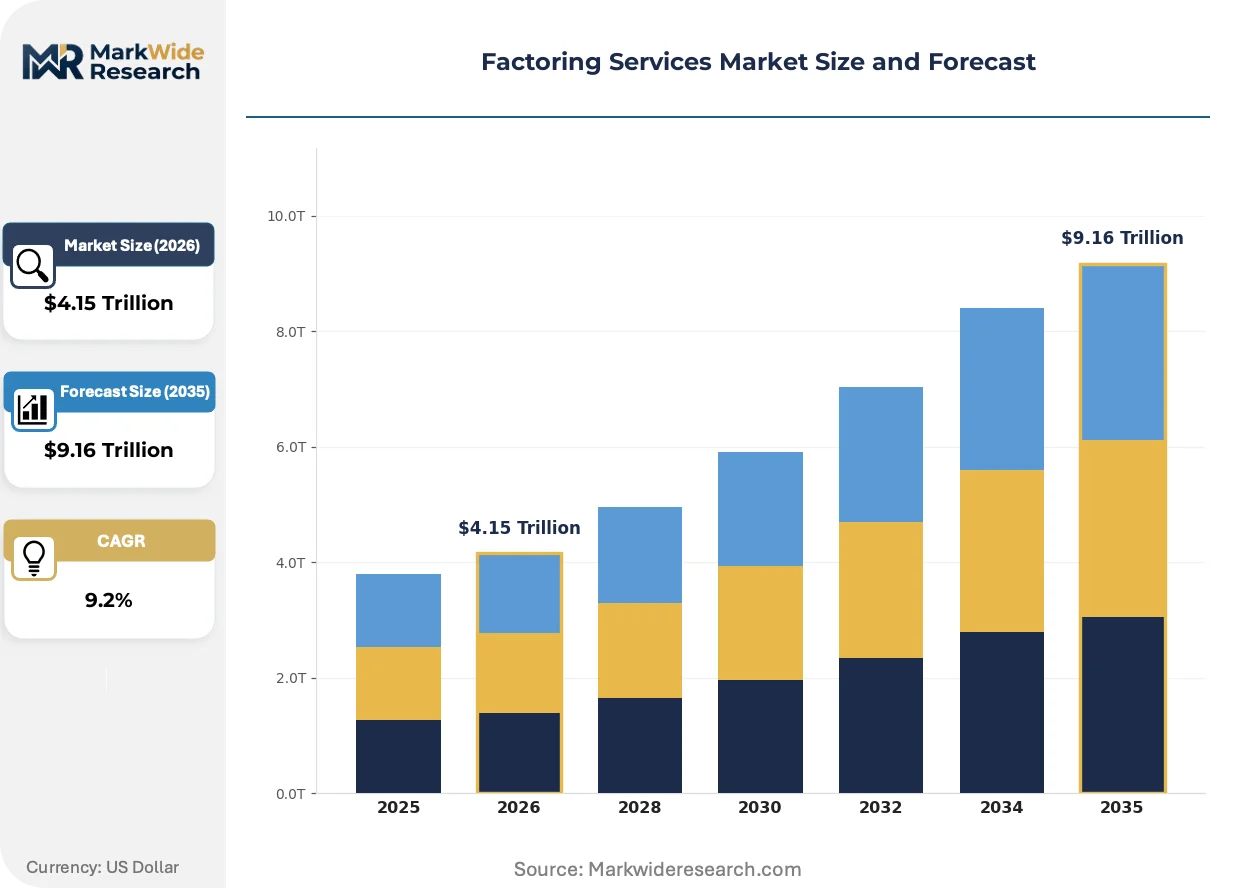
| Market Size in 2026 | $4.15 Trillion |
| Market Size in 2035 | $9.16 Trillion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-Recourse Factoring, Invoice Discounting, Full-Service Factoring Industry Vertical: Manufacturing, Wholesale, Retail, Transportation Client Type: Small Businesses, Mid-Sized Enterprises, Large Corporations, Startups Transaction Size: Small Transactions, Medium Transactions, Large Transactions, Bulk Transactions |
| Companies Covered | Triumph Business Capital, altLINE, Riviera Finance, Universal Funding, Viva Capital, eCapital, Scale Funding, Apex Capital Corp, RTS Financial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Factoring Services Market Strategic Shifts & Innovations
Algorithmic underwriting is compressing the factor's value chain from origination through collections, collapsing traditional role distinctions between credit analyst, relationship manager, and collections agent into unified platform workflows.
Application programming interfaces for bank account data aggregation are supplanting manual financial statement review in SME credit decisions. Transportation and healthcare factors deploy these tools to verify invoice authenticity against actual cash flows rather than static credit reports. The structural consequence is collapsing minimum invoice thresholds that previously excluded micro-enterprises from formal receivables financing.
The European Banking Authority's prudential standards for fintech credit institutions are tightening capital reserve requirements for cross-border factoring platforms operating under EU passporting rules. Non-bank factors must now hold proportionally higher buffers against concentrated buyer exposures. German and French platforms are responding by syndicating large invoice pools across multiple funding sources rather than retaining full risk positions.
Buyer-led supply chain finance programs are rotating procurement preferences toward approved-factor networks that offer dynamic discounting alongside traditional factoring. Large manufacturers in automotive and retail verticals now mandate pre-approved factor relationships for tier-two suppliers. This concentration is most visible in India, where RBI-mandated priority sector lending classifications direct bank-affiliated factors toward agricultural supply chains with embedded financing requirements.
Factoring Services Market Segmentation
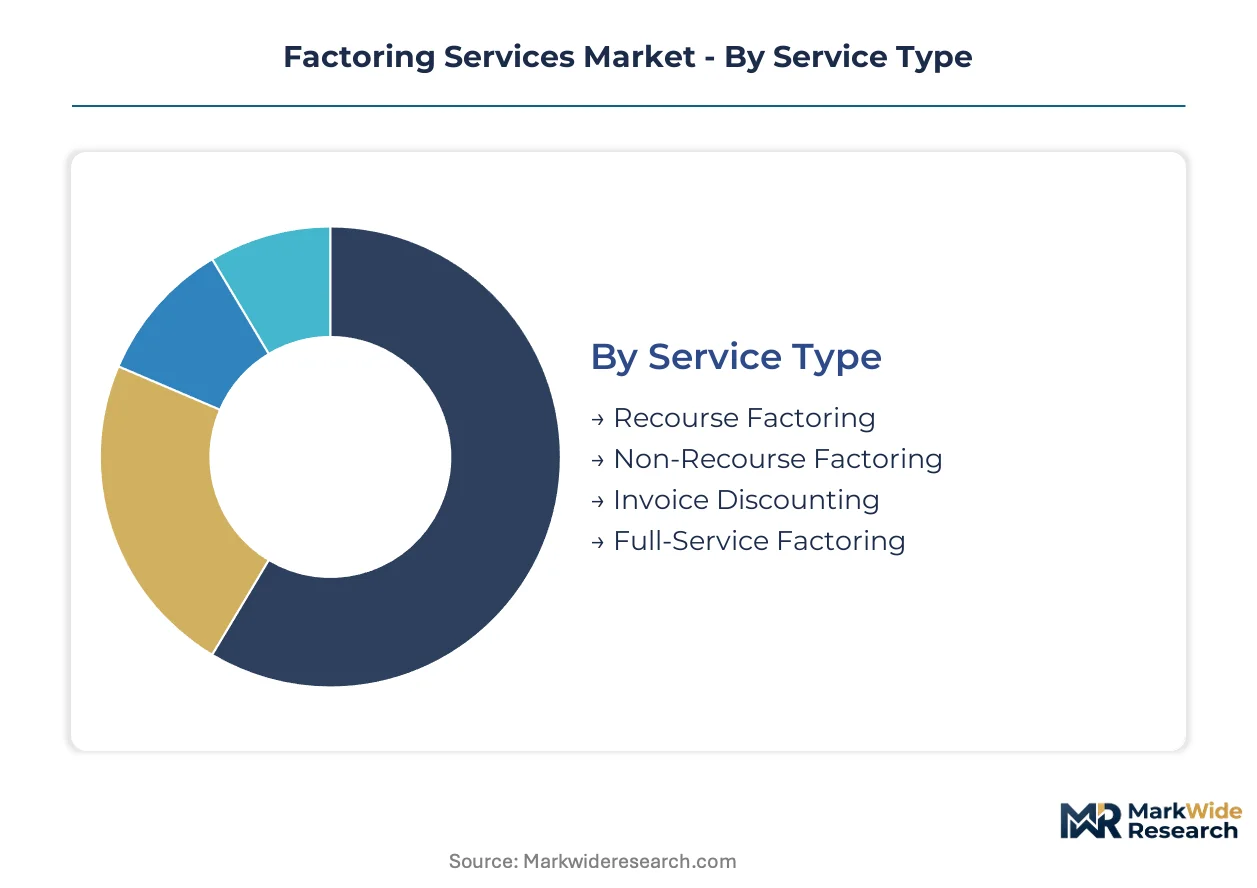
Segmentation in factoring services determines risk pricing, operational workflows, and technology stack requirements. Each dimension shapes how factors structure credit decisioning, collection protocols, and buyer verification processes.
Service Type:
Substitution pressure from supply chain finance platforms and dynamic discounting tools threatens traditional recourse structures most acutely, while non-recourse products defend their premium through risk transfer value.
- Recourse Factoring:Credit risk remains with the invoice seller, enabling factors to advance capital at lower discount rates. Demand concentrates among mid-sized manufacturers in Germany and France where buyers maintain investment-grade ratings, reducing default probability and making recourse terms commercially tolerable for suppliers.
- Non-Recourse Factoring:The factor assumes buyer default risk entirely, commanding premium pricing tiers. Transportation corridors across Texas and California anchor volume here, where freight brokers face elongated payment cycles from shippers but possess limited balance sheet capacity to absorb counterparty failure.
- Invoice Discounting:Confidential arrangements where sellers retain collection responsibility while accessing advance funding. Retail distributors in India's tier-two cities deploy this structure to mask liquidity constraints from large buyers.
- Full-Service Factoring:Bundled credit protection, ledger management, and collection services. Agricultural supply chains under RBI priority sector mandates favor this comprehensive approach for unbanked supplier onboarding.
Recourse factoring retains volume leadership; non-recourse factoring holds the steepest expansion curve.
Industry Vertical:
Margin compression varies sharply across verticals, with transportation factors defending spreads through fuel advance embedding while retail faces buyer consolidation pressure.
- Manufacturing:Elongated production cycles and inventory-heavy balance sheets drive receivables monetization demand. Automotive tier-one suppliers in Michigan and Ohio concentrate here, where OEM payment terms stretch past ninety days.
- Wholesale:Thin margin structures amplify working capital sensitivity. Food and beverage distributors in São Paulo leverage factoring to bridge seasonal procurement spikes without equity dilution.
- Retail:High invoice velocity and seasonal volatility characterize this vertical. E-commerce fulfillment providers in the Netherlands face buyer concentration risk from platform-dependent revenue streams.
- Transportation:Freight factoring dominates North American logistics corridors with embedded fuel advances and load-matching platform integrations. Owner-operators in Illinois and Georgia represent the core client base.
Transportation anchors revenue concentration; manufacturing delivers the most stable renewal rates.
Client Type:
Customer acquisition cost tiers stratify sharply, with digital onboarding collapsing minimum thresholds for micro-enterprises while enterprise mandates require bespoke structuring.
- Small Businesses:Micro-enterprises previously excluded by manual underwriting now access receivables financing through API-driven cash flow verification. India's unbanked agricultural suppliers exemplify this expansion under RBI sandbox frameworks.
- Mid-Sized Enterprises:The fastest-expanding client type as working capital constraints intensify without equity market access. German Mittelstand manufacturers in Baden-Württemberg typify this segment's risk-return profile.
- Large Corporations:Sophisticated treasury functions deploy factoring selectively for off-balance-sheet treatment of specific receivable pools. French CAC 40 subsidiaries utilize this for emerging market buyer exposure.
- Startups:Venture-backed companies with limited operating history face higher discount rates. SaaS providers in Tel Aviv leverage factoring against annual contract value to bridge cash conversion cycles.
Mid-sized enterprises command the steepest volume growth; large corporations sustain the lowest churn rates.
Transaction Size:
Operational cost structures favor scale in large transactions, while algorithmic underwriting enables profitably serving previously unviable small-ticket volumes.
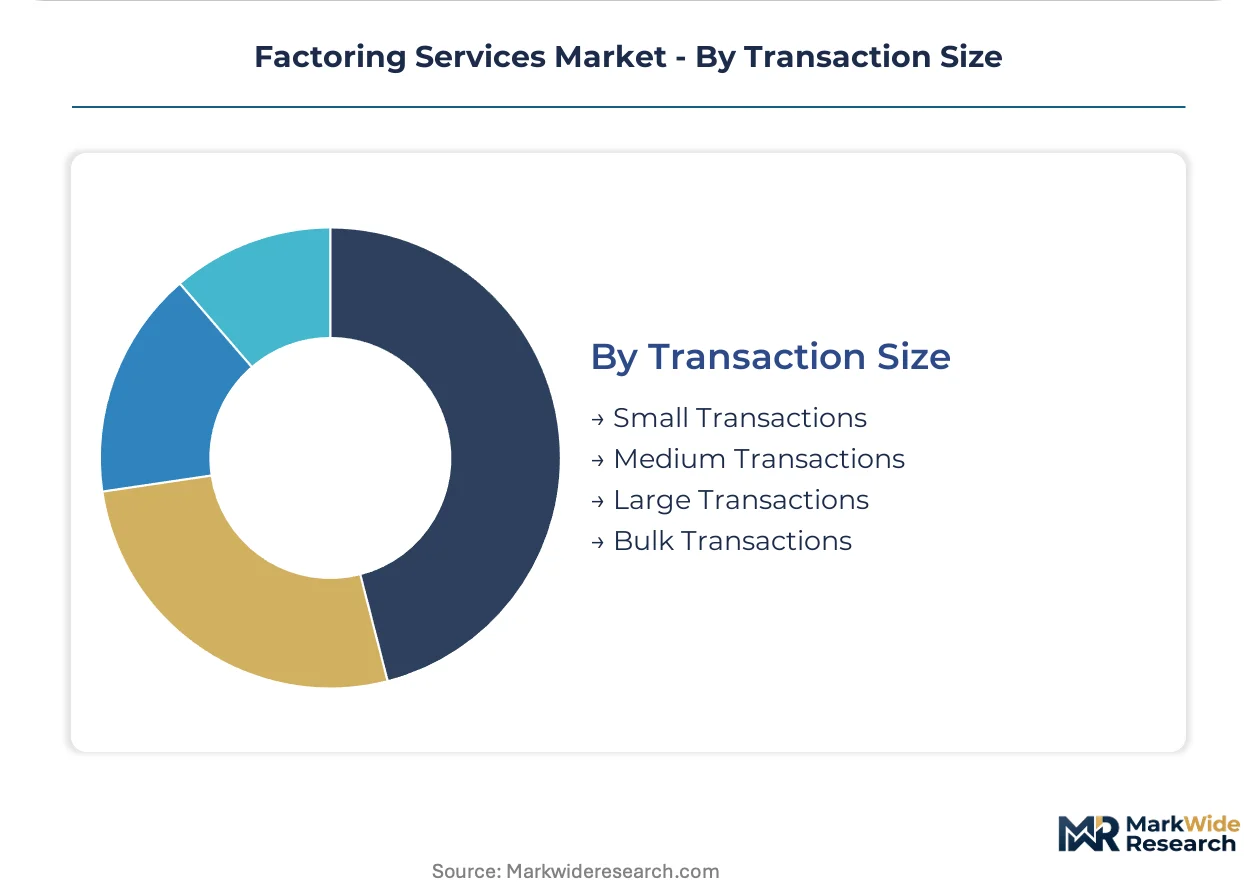
- Small Transactions:Individual invoices below ten thousand dollars. Open banking APIs in the United Kingdom enable automated verification, collapsing origination costs for sole proprietors in Manchester and Birmingham.
- Medium Transactions:The operational sweet spot for most independent factors. Regional staffing agencies in Texas concentrate here, with predictable invoice cycles supporting standardized underwriting.
- Large Transactions:Single-invoice exposures requiring syndication across multiple funding sources. German automotive supplier receivables often necessitate this structure under EBA concentration limits.
- Bulk Transactions:Whole-ledger purchases with master servicing agreements. Healthcare systems in Florida deploy this for medical equipment supply chain financing at portfolio scale.
Medium transactions retain volume leadership; small transactions are climbing the fastest as digital onboarding matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI's regulatory sandbox for fintech lenders anchors the dominant geography, expanding invoice financing access to unbanked suppliers across India's agricultural and manufacturing supply chains.
United States
Freight factoring corridors across Texas and Illinois drive volume concentration, with owner-operators monetizing receivables against elongated shipper payment cycles. The Uniform Commercial Code Article 9 governs perfection of security interests, creating jurisdictional complexity for factors operating across state lines. Transportation hubs in Dallas-Fort Worth and Atlanta anchor embedded financing tied to fuel advances.
Germany
Mittelstand manufacturers in Baden-Württemberg and Bavaria deploy recourse factoring to bridge working capital gaps without diluting family ownership structures. The European Banking Authority's prudential standards reshape capital reserve requirements for cross-border platforms operating under EU passporting rules. Automotive supplier clusters in Stuttgart and Munich concentrate receivables monetization demand from tier-one OEM relationships.
India
Unbanked agricultural suppliers in Maharashtra and Gujarat access invoice financing through RBI-mandated priority sector lending classifications for bank-affiliated factors. The central bank's fintech licensing framework expands digital onboarding for micro-enterprises previously excluded by manual underwriting thresholds. Manufacturing corridors in Pune and Ahmedabad drive adoption among small and mid-sized enterprises facing working capital constraints.
United Kingdom
Open banking APIs in Manchester and Birmingham collapse origination timelines for sole proprietors seeking small-ticket receivables financing. The Financial Conduct Authority's oversight of alternative lending platforms shapes disclosure requirements for recourse versus non-recourse product differentiation. Fintech clusters in London deploy real-time credit scoring against cash flow data rather than static credit reports.
France
CAC 40 subsidiaries utilize full-service factoring for off-balance-sheet treatment of emerging market buyer exposures. The Autorité de Contrôle Prudentiel et de Résolution supervises capital adequacy for bank-affiliated factors serving agricultural supply chains. Industrial basins in Lyon and Lille concentrate demand from food and beverage distributors managing seasonal procurement spikes.
Factoring Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the factoring services landscape. Bank-backed platforms sustain lower cost of capital than independent funders, while algorithmic specialists compress origination timelines through API-driven underwriting. The market structures around three archetypes: transportation sector specialists, vertical-focused healthcare and staffing factors, and diversified independent platforms. Competitive moves concentrate on embedded financing integrations with load-matching platforms and ERP connectivity for mid-market manufacturers.
Within the transportation specialization tier, Triumph Business Capital and Apex Capital Corp exemplify corridor-dominant positioning across North American logistics hubs. altLINE occupies a position representing bank-backed funding models that compete on cost of capital rather than speed. eCapital anchors the vertical-focused archetype, with its healthcare and staffing concentration reflecting predictable invoice cycle characteristics. These three entities collectively illustrate how sector depth, funding structure, and technology stack differentiate competitive positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| Triumph Business Capital |
| altLINE |
| Riviera Finance |
| Universal Funding |
| Viva Capital |
| eCapital |
| Scale Funding |
| Apex Capital Corp |
| RTS Financial |
| Others |
Cost & Logistics Intelligence
The European Banking Authority's prudential standards for fintech credit institutions gate both factor qualification and price differentiation simultaneously, mandating higher capital reserves for non-bank platforms that assume concentrated buyer risk while permitting bank-affiliated factors to price more aggressively through lower funding costs. This regulatory bifurcation compresses margins for independent funders in cross-border corridors while rewarding institutions with diversified funding bases.
Pricing Analysis
Geographic price spreads between German Mittelstand manufacturers and Indian agricultural suppliers exceed five hundred basis points on equivalent invoice tenors, reflecting divergent funding costs and default risk assessments. Recourse factoring dominates European pricing structures with discount rates anchored by buyer credit quality, while non-recourse products in North American transportation corridors command premium spreads for risk transfer. Price differentiation rests on certification tier — factors with EBA fintech licensing versus unregulated independents — and volume scale, with bulk-ledger clients securing fifteen to twenty percent rate reductions. Cost compression in recourse products is intensifying because open banking APIs collapsed origination expenses, eroding the rate premiums that previously covered manual underwriting. Small business segments exhibit acute price sensitivity, while large corporate treasury functions prioritize balance sheet treatment over marginal rate differences.
Supply Chain Analysis
Just-in-time funding preferences dominate the factoring supply chain, with factors deploying API-driven disbursement within twenty-four hours to match supplier working capital cycles rather than maintaining strategic liquidity reserves. Geographic supply concentration centers on the United States, Germany, and India, where transportation corridors, automotive supplier clusters, and RBI-sanctioned fintech platforms anchor origination capacity. Raw material dependencies include bank funding lines, securitization conduits, and institutional investor capital pools that determine advance rates and pricing floors. Single-source vulnerability in wholesale funding markets poses structural risk, as rate spikes in interbank markets transmit directly to factor pricing power. Distribution runs through embedded ERP integrations, load-matching platforms, and direct sales forces targeting mid-market manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through large manufacturer procurement mandates that pre-approve factor networks for tier-two suppliers, fragmenting pricing autonomy across automotive and retail supply chains.
For Market Incumbents: Consolidate corridor dominance through exclusive fuel advance integrations with load-matching platforms in Texas and Illinois, defending against algorithmic entrants that compress origination timelines. Deepen backward integration into credit data assets by acquiring alternative scoring providers, reducing dependency on bureau reports that delay underwriting. Bank-affiliated factors should exploit EBA licensing advantages to expand EU passporting coverage before capital reserve requirements tighten further. For New Entrants and Emerging Players: Micro-enterprise onboarding gaps in India's tier-two agricultural supply chains offer the most penetrable white-space, where RBI sandbox frameworks reduce licensing friction for fintech lenders. Target healthcare staffing verticals in Florida and Georgia with invoice verification tools that authenticate medical claim cycles against actual cash flows. Deploy API-first go-to-market strategies that embed directly into QuickBooks and Sage accounting systems used by sole proprietors. For Investors and Strategic Acquirers: The Reserve Bank of India's fintech licensing expansion reshapes the acquisition landscape, privileging platforms with priority sector lending classifications that direct capital toward agricultural supply chains. Long-term viability across the analysis window favors factors with diversified funding structures spanning bank lines, securitization, and institutional capital rather than single-source dependent independents. Watch central bank digital currency pilot programs as the critical inflection signal, since disintermediation of invoice verification rails would eliminate core revenue streams for traditional factors.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Integration Partnership | Embedded onboarding through SAP and Oracle systems captures mid-market manufacturers in Baden-Württemberg. |
| Fuel Advance Embedding | Load-matching platform ties in Dallas-Fort Worth anchor owner-operator loyalty against rate competition. |
| RBI Sandbox Licensing | Priority sector lending classifications in Maharashtra direct bank capital toward unbanked agricultural suppliers. |
| Alternative Data Acquisition | Purchase of cash-flow verification APIs collapses underwriting costs for micro-enterprise segments. |
| EU Passporting Expansion | EBA fintech licensing enables cross-border servicing from Stuttgart to Lyon under unified capital rules. |
Research Approach
The analysis maps recourse factoring, non-recourse factoring, invoice discounting, and full-service factoring segments, each validated through credit risk officers at bank-affiliated platforms, independent factor underwriting directors, SME treasury managers, and ERP integration specialists. Primary interviews with transportation fleet operators in Illinois and healthcare staffing administrators in Texas informed operational workflow assessments. Secondary validation drew from RBI fintech licensing disclosures, EBA prudential standard consultations, Uniform Commercial Code filing databases, and open banking API documentation. Bottom-up invoice volume estimates triangulated against top-down receivables monetization penetration rates by country.
Consistency checks against external benchmarks validated model outputs against disclosed advance rate ranges and discount pricing tiers reported across regulatory filings. The analytical framework projects volume and value across service type, industry vertical, client type, and transaction size dimensions throughout the forecast period. CAGRs were derived from invoice velocity growth in manufacturing supply chains, transportation corridor expansion, and fintech platform adoption curves. Key inputs included working capital constraint indices, buyer payment term elongation trends, and API penetration rates in SME banking.
Material uncertainties — central bank digital currency disintermediation, cross-border jurisdictional harmonization failures, and certified trade finance underwriter scarcity — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory sandbox expansion continuity and open banking API standardization trajectories. Practitioners should keep alternative scenarios live as CBDC pilot programs and EBA capital reserve calibrations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Digital Account Opening Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Middle East Islamic Finance Market
Financial Services
Foreign Exchange Services Market
Financial Services
Europe E-Brokerages Market
Financial Services
Australia Gift Card and Incentive Card Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Global Temporary Labor Market
Financial Services
Global Product Cost Management Market
Financial Services
Check Cashing Services Market
Financial Services
Online Investment Platform Market
Financial Services
Banknote Counters Market
Financial Services
Germany E-Brokerage Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
Benefits Consulting Service Market