
 Financial Advisory Services Market | 2026-2036
Financial Advisory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Advisory Services Market Analysis
Ultra-high-net-worth family office demand is realigning the competitive landscape for institutional-grade advisory platforms. Goldman Sachs Group Inc. leverages its private wealth infrastructure to anchor ultra-affluent client relationships across North America. Deloitte competes through integrated tax-advisory bundling that extends across multinational corporate treasury functions. PwC specializes in regulatory-driven transformation consulting, occupying a distinct position where compliance complexity intersects with strategic finance.
Financial advisory services encompass fee-based professional guidance on capital allocation, risk management, and regulatory compliance delivered through human advisors, algorithmic platforms, or hybrid models. The discipline requires fiduciary duty adherence, securities licensing, and ongoing continuing education to maintain practice authority across jurisdictions. Wealth management and investment advisory dominate current revenue pools, though subscription-based engagement models are capturing fastest growth as younger investors reject traditional commission structures. Retirement planning retains mature, sticky client bases but faces margin compression from automated portfolio construction tools.
The SEC enforces advisor fiduciary standards and disclosure protocols that shape product suitability requirements across the United States. The EU's MiFID II framework mandates granular fee transparency and best-execution reporting that restructures how European advisors price and deliver services. Stakeholders must monitor evolving regulatory divergence between jurisdictions while building compliance architectures flexible enough to absorb simultaneous SEC, FCA, and ECB supervisory expectations.
Market Dynamics
The SEC's fiduciary rule evolution is compressing commission-based revenue models while forcing advisory platforms toward transparent fee structures and documented suitability protocols. This regulatory pressure is redistributing competitive advantage toward firms with scale to absorb compliance infrastructure costs.
Growth Catalysts
- MiFID II Fee Transparency Mandates:European advisors must disclose granular cost breakdowns, accelerating client migration from opaque product wrappers to clean fee-based arrangements.
- Singapore Wealth Management Incentives:The Monetary Authority of Singapore's family office framework attracts ultra-high-net-worth capital from Greater China and Southeast Asia.
- Algorithmic Portfolio Construction:Machine learning-driven asset allocation reduces marginal service costs for mass-affluent segments previously excluded from personalized advice.
Market Restraints
- Talent Acquisition Costs:Certified financial planners command premium compensation in Zurich, Geneva, and Singapore, compressing margins for mid-tier advisory practices.
- Cross-Border Licensing Friction:Advisors operating across Switzerland-Luxembourg-UAE corridors face overlapping regulatory registrations and conflicting fiduciary standards.
- Robo-Advisor Substitution:Automated platforms capture routine rebalancing and tax-loss harvesting functions that previously sustained recurring advisory fees.
Strategic Opportunities
- India's Underserved Mass-Affluent Segment:SEBI's Registered Investment Advisor framework creates compliant pathways for foreign firms to serve Mumbai and Delhi's emerging wealthy households.
- ESG Integration Mandates:EU Green Deal disclosure requirements position sustainability-linked advisory as a premium service tier for institutional pension funds.
- Embedded Finance Distribution:Banking-as-a-Service APIs enable advisory modules inside fintech super-apps, bypassing traditional client acquisition costs.
Industry Challenges
- Cybersecurity Certification Delays:FINRA and state-level cybersecurity compliance timelines stretch 18-24 months, delaying platform launches for digital-native entrants.
- Legacy System Integration:Established practices face data migration friction when consolidating client records across incompatible CRM and portfolio accounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Advisory Services Market |
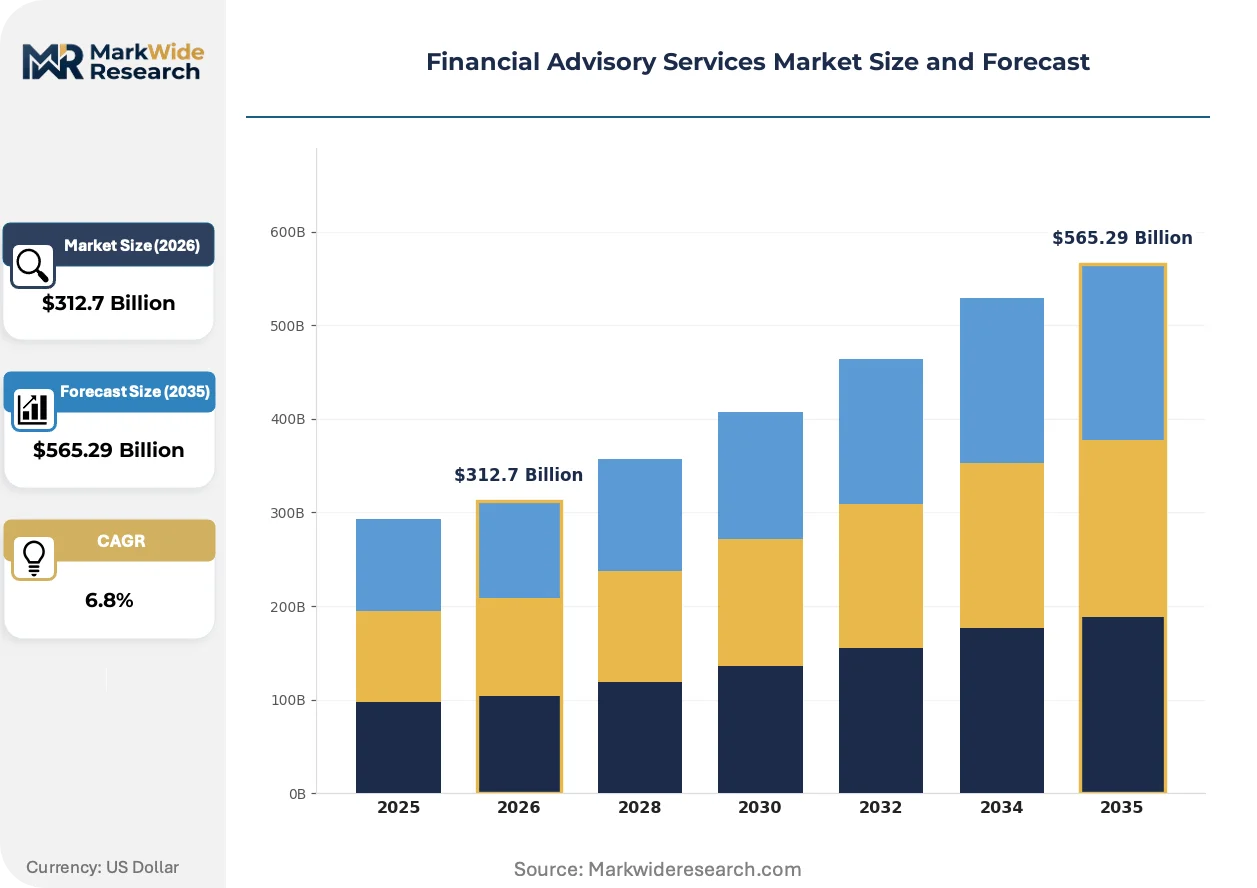
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Investment Advisory, Wealth Management, Retirement Planning, Tax Consulting Client Type: High-Net-Worth Individuals, Corporations, Non-Profits, Institutional Investors Engagement Model: Fee-Only, Commission-Based, Hybrid, Subscription Asset Class: Equities, Fixed Income, Real Estate, Alternative Investments |
| Companies Covered | Bank of America Corporation, Morgan Stanley, Goldman Sachs Group Inc., JPMorgan Chase & Co., Deloitte, Ernst & Young (EY), PwC, Charles Schwab Corporation, Ameriprise Financial Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Advisory Services Market Emerging Trajectories
Advisory delivery models are fragmenting across human-digital hybrid architectures, with platform economics favoring consolidated providers who can amortize technology investment across million-plus client relationships.
Unified data architectures are unifying client onboarding, portfolio reporting, and tax document generation into single-cloud workflows. Mid-size registered investment advisors in Texas and Florida are adopting these stacks fastest, driven by competitive pressure from national consolidators. The structural consequence is compressing back-office headcount requirements while raising minimum viable scale thresholds for independent practices.
EU AI Act algorithmic governance requirements will mandate human oversight protocols for automated investment recommendations across European Economic Area jurisdictions. Asset managers deploying machine-driven strategies must document decision audit trails and maintain explainability standards. German and Dutch pension funds are demanding vendor certifications ahead of enforcement timelines, filtering supplier pools toward established technology providers.
Subscription pricing models are displacing traditional assets-under-management fee structures among investors under forty-five. Flat monthly rates for unlimited advisor access appeal to professionals in technology and healthcare sectors with volatile bonus income. This pattern concentrates in coastal US metropolitan markets where robo-advisor penetration already normalized digital-first wealth management relationships.
Financial Advisory Services Market Segmentation
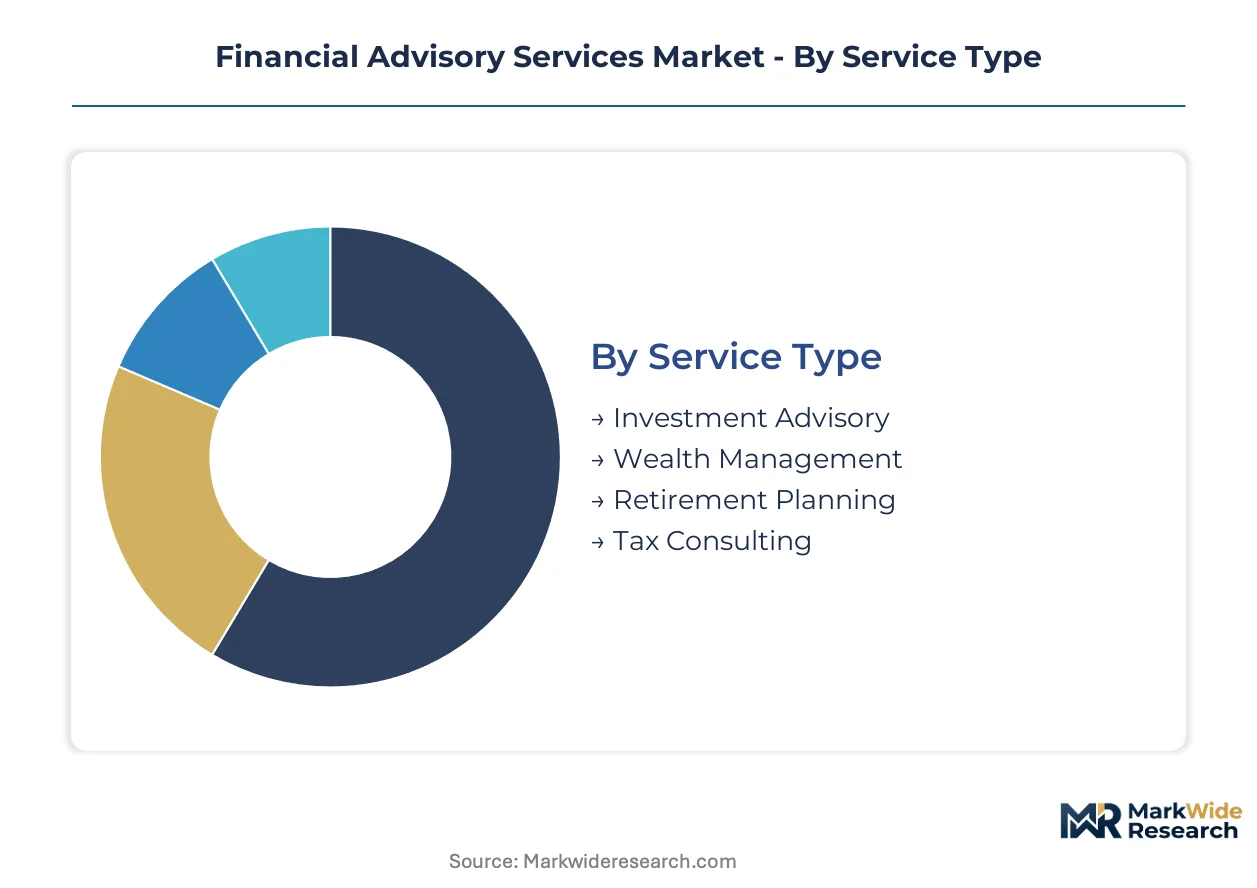
Segmentation in financial advisory services reveals how revenue concentrates across service tiers and client sophistication levels. Advisory platforms calibrate compliance infrastructure and talent deployment differently for each segment, creating distinct competitive moats.
Service Type:
Supply concentration in wealth management and investment advisory segments forces mid-tier firms toward specialized niches or scale-driven consolidation.
- Investment Advisory:Discrete recommendations on security selection and portfolio construction delivered under SEC or FCA fiduciary standards. Demand clusters among mass-affluent households in Texas and Florida seeking algorithm-augmented human guidance. Regulatory disclosure requirements compress margins for standalone practitioners lacking unified data architectures.
- Wealth Management:Comprehensive balance sheet oversight spanning trusts, generational transfers, and concentrated position management. Ultra-high-net-worth families in Singapore and Switzerland anchor capacity expansion here, drawn by multi-jurisdictional tax coordination and family governance structures. The Monetary Authority of Singapore's family office framework accelerates platform buildout.
- Retirement Planning:Accumulation and decumulation strategies for defined contribution and pension assets.
- Tax Consulting:Cross-border compliance and optimization for mobile capital and multinational corporate treasury functions.
Wealth management absorbs the bulk of installed capacity; investment advisory is expanding most quickly.
Client Type:
Cost tier differentiation separates white-glove family office infrastructure from standardized corporate retirement plan administration.
- High-Net-Worth Individuals:Personal balance sheet complexity requiring coordinated investment, tax, and estate planning across multiple domiciles. Demand concentrates in Dubai and Geneva for cross-border wealth preservation structures. Singapore's tax incentive regimes for family offices redirect Greater China capital flows.
- Corporations:Treasury risk management, pension fiduciary oversight, and M&A transaction advisory. Multinational headquarters in Luxembourg and the Netherlands drive integrated tax-advisory bundling. MiFID II best-execution mandates reshape how corporate treasury functions select advisory counterparties.
- Non-Profits:Endowment investment policy and donor-advised fund administration with constrained fee tolerance.
- Institutional Investors:Outsourced chief investment officer services and liability-driven investment strategies for pension funds and insurance reserves.
Corporations anchor the highest absolute fee pools; high-net-worth individuals are climbing the fastest.
Engagement Model:
Margin structure varies dramatically across compensation mechanisms, with subscription models capturing younger cohorts previously excluded from advice relationships.
- Fee-Only:Transparent assets-under-management or hourly billing without product commissions. Coastal US metropolitan professionals in technology and healthcare sectors favor this structure for alignment clarity. SEC fiduciary rule evolution accelerates migration from conflicted compensation.
- Commission-Based:Product-driven revenue from insurance and annuity sales, now contracting under regulatory pressure. Legacy practices in Florida and Arizona retain older client bases resistant to fee conversion. Compressed margins force consolidation into bank-owned distribution networks.
- Hybrid:Blended fee and commission structures permitting flexibility across client life stages.
- Subscription:Flat monthly rates for unlimited advisor access, displacing traditional AUM pricing among investors under forty-five.
Fee-only arrangements dominate current revenue; subscription models are gaining share fastest.
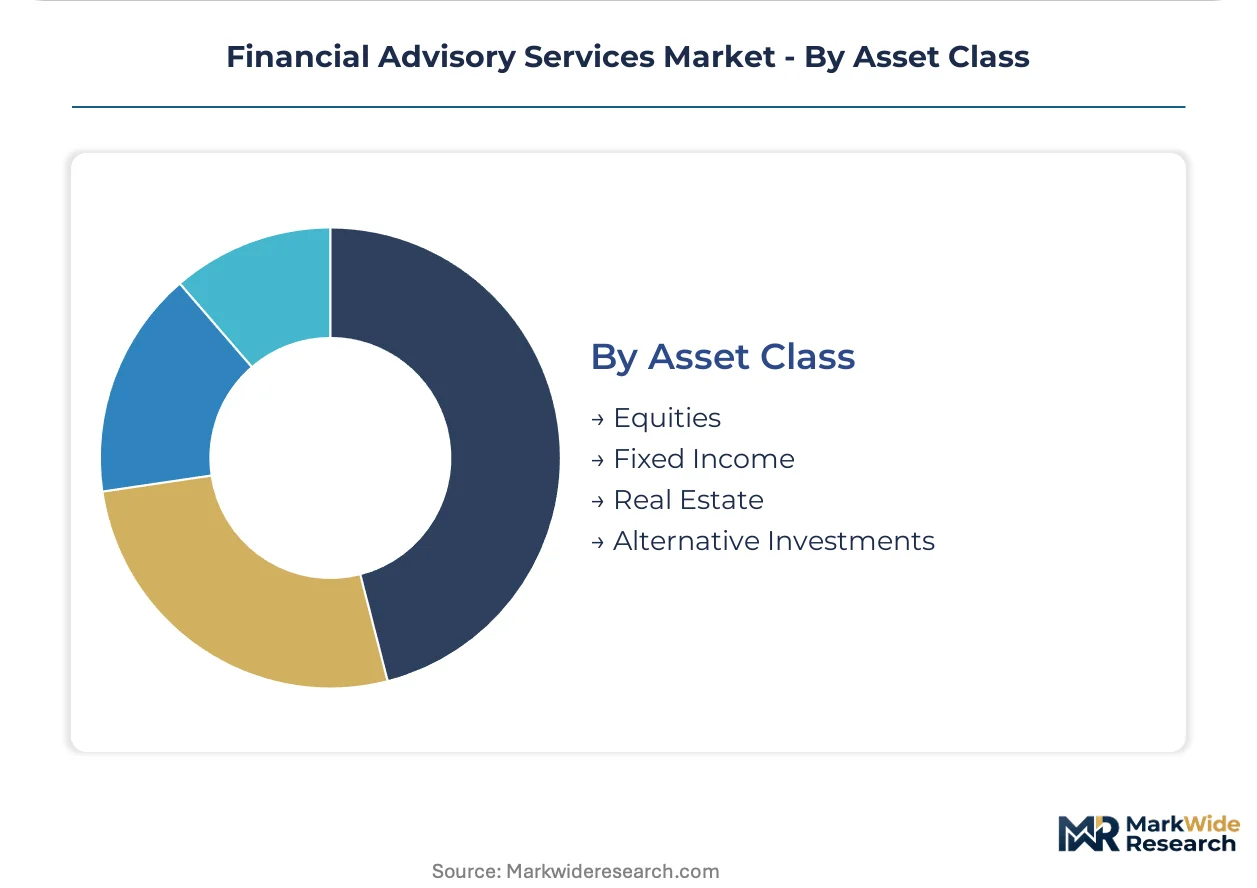
Asset Class:
Application focus determines whether advisory platforms build internal research capacity or outsource to third-party managers.
- Equities:Direct stock selection and factor-based allocation requiring security-level research infrastructure. Retail investor demand in India and Brazil supports specialized emerging market advisory boutiques. SEBI's Registered Investment Advisor framework creates compliant entry pathways for foreign firms.
- Fixed Income:Duration management and credit analysis for liability-matching institutional mandates. German and Dutch pension funds drive demand for liability-driven investment advisory. EU Green Deal disclosure requirements embed sustainability screens into bond portfolio construction.
- Real Estate:Direct property investment and REIT allocation for inflation-sensitive portfolios.
- Alternative Investments:Private equity, hedge fund, and infrastructure access for qualified purchasers.
Equities deployment absorbs the bulk of advisory capacity; alternative investments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advisory production concentrates in financial centers with deep regulatory infrastructure and cross-border expertise, while consumption disperses across emerging wealth corridors seeking institutional-grade guidance.
United States
Ultra-high-net-worth households in New York and California drive demand for multi-generational wealth structures. The SEC's fiduciary rule evolution forces documented suitability protocols and transparent fee disclosures. Texas and Florida registered investment advisors adopt unified data architectures fastest, compressing back-office costs amid consolidator pressure.
Singapore
Family offices from Greater China and Southeast Asia anchor capacity expansion for cross-border tax coordination. The Monetary Authority of Singapore's family office framework offers tax incentive regimes that redirect regional capital flows. Marina Bay and Orchard Road clusters host institutional-grade advisory platforms serving mobile ultra-affluent capital.
Switzerland
Geneva and Zurich private banks preserve wealth preservation demand from Middle Eastern and Latin American clients. FINMA supervision maintains strict fiduciary standards that filter advisory licensing toward established institutions. The Switzerland-Luxembourg-UAE corridor faces overlapping registrations that raise compliance barriers for mid-tier entrants.
Germany
Liability-driven investment advisory dominates as German and Dutch pension funds outsource CIO functions. The EU AI Act mandates human oversight protocols for algorithmic recommendations, filtering vendor pools toward established technology providers. Frankfurt's asset management cluster demands sustainability-linked advisory certifications ahead of enforcement timelines.
India
Mumbai and Delhi's emerging wealthy households seek compliant advisory pathways for equity and fixed income allocation. SEBI's Registered Investment Advisor framework creates entry routes for foreign firms with localized compliance infrastructure. Bangalore's technology professionals favor subscription-based engagement models over traditional AUM pricing.
Financial Advisory Services Market Vendor Landscape
Top-tier vendors anchor the institutional-grade advisory tier, while mid-size registered investment advisors face compressing margins from technology-driven scale requirements. The market structure favors consolidated providers who amortize compliance infrastructure across million-plus client relationships. Three archetypes dominate: universal bank wealth divisions, accounting firm advisory bundlers, and technology-enabled independent platforms. Competitive moves concentrate on M&A-driven consolidation and unified data architecture deployment.
Within the universal banking tier, Goldman Sachs Group Inc. and JPMorgan Chase & Co. occupy positions defined by private wealth infrastructure and ultra-affluent relationship depth. Among professional services bundlers, Deloitte and PwC exemplify integrated tax-advisory models that extend across multinational corporate treasury functions. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Bank of America Corporation |
| Morgan Stanley |
| Goldman Sachs Group Inc. |
| JPMorgan Chase & Co. |
| Deloitte |
| Ernst & Young (EY) |
| PwC |
| Charles Schwab Corporation |
| Ameriprise Financial Inc. |
| Others |
Supply Flow & Price Mechanics
FINRA cybersecurity certification timelines cascade through advisory platform economics, elevating compliance infrastructure costs that stratify pricing tiers between consolidated national providers and fragmented independent practices. Mid-tier registered investment advisors absorb these cost pressures through unified data architecture adoption, compressing back-office headcount while raising minimum viable scale thresholds.
Pricing Analysis
Margin tightening in subscription-based tiers reflects algorithmic portfolio construction commoditizing routine rebalancing functions previously sustaining recurring fees. Three-tier pricing structure across premium family office, standard wealth management, and economy robo-augmented segments separates white-glove multi-jurisdictional tax coordination from standardized digital-first delivery. Commission-based models face pricing erosion as SEC fiduciary rule evolution accelerates fee-only migration. Corporate treasury clients exhibit lowest price sensitivity given bundled tax-advisory complexity; mass-affluent technology professionals in coastal US markets demonstrate highest sensitivity to AUM-based structures.
Supply Chain Analysis
Domestic-content mandates in India's SEBI Registered Investment Advisor framework reshape foreign firm entry pathways toward localized compliance infrastructure partnerships. Advisory platform supply concentrates in the United States, Singapore, and Switzerland, drawing from certified financial planner talent pools, cloud-based portfolio accounting systems, and regulatory technology middleware. Single-source vulnerability concentrates in algorithmic recommendation engines subject to EU AI Act human-oversight mandates. Distribution runs through bank-owned wealth divisions, independent registered investment advisor networks, and embedded finance APIs within fintech super-apps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
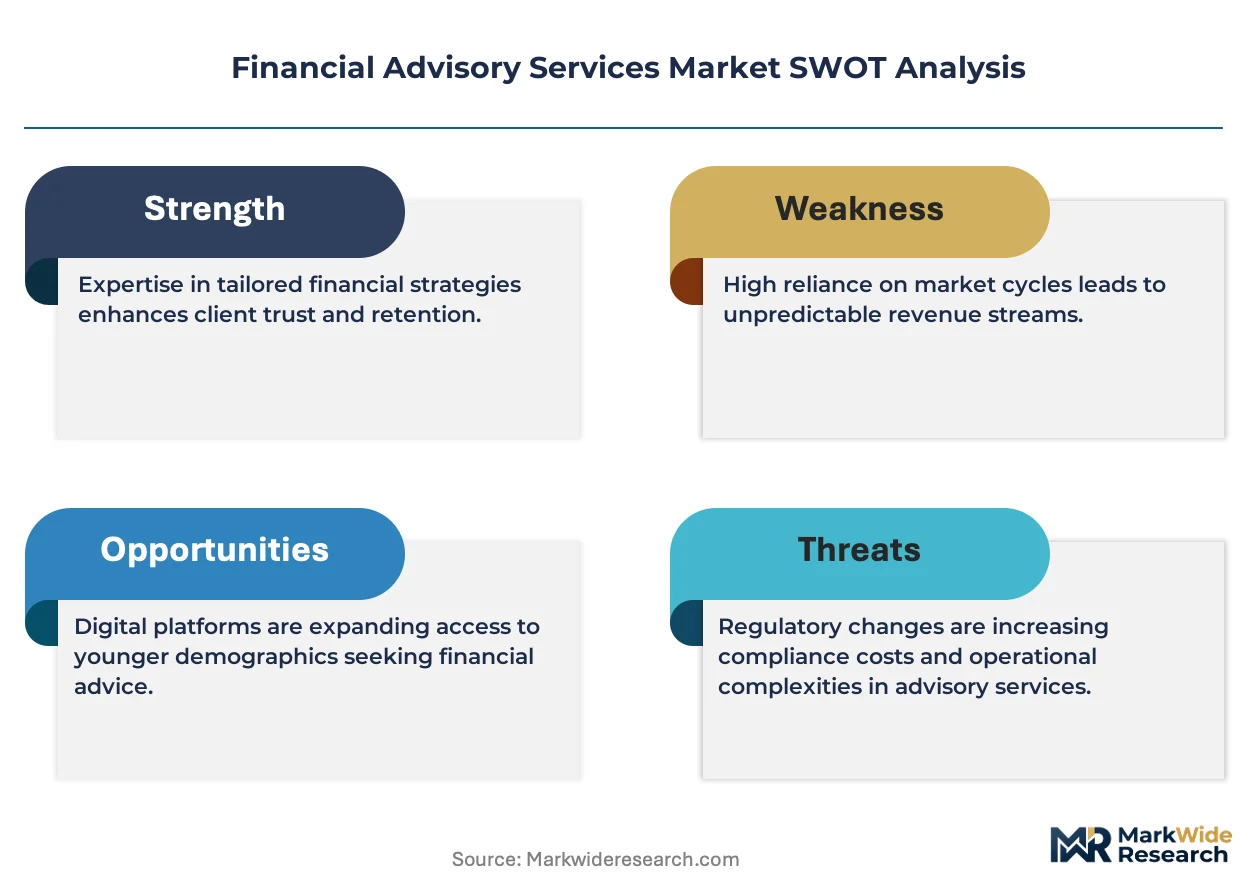
Financial advisory services function as a cost-of-compliance market where SEC fiduciary rule evolution erects durable barrier-to-entry moats favoring scaled platforms with amortized regulatory infrastructure.
For Market Incumbents: Deploy unified data architecture consolidation to absorb FINRA cybersecurity certification timelines that delay digital-native competitor launches. Absorb mid-tier registered investment advisors in Texas and Florida facing back-office compression from national consolidator pressure. Robo-advisor substitution threatens routine rebalancing fee streams; counter through hybrid human-digital service tiers preserving high-touch client relationships. For New Entrants and Emerging Players: Banking-as-a-Service APIs offer white-label distribution pathways into embedded finance modules, bypassing traditional client acquisition costs. Target India's mass-affluent segment in Mumbai and Delhi where SEBI compliance frameworks create first-mover advantages for foreign firms with localized infrastructure. Subscription pricing models penetrate technology professionals under forty-five in Bangalore and coastal US metros resistant to legacy AUM structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size registered investment advisors with unified data stacks in Texas and Florida facing margin compression but retaining sticky client bases. Long-term viability hinges on scale thresholds crossing million-plus client relationships where platform economics amortize compliance technology. Watch EU AI Act enforcement timelines as inflection indicator filtering algorithmic advisory vendor pools toward established providers.| Strategic Initiative | Industry Significance |
|---|---|
| Unified Data Architecture Deployment | Compresses back-office costs for mid-tier advisors competing against national consolidators. |
| Subscription Pricing Model Launch | Captures mass-affluent technology professionals rejecting traditional AUM fee structures. |
| SEBI Localization Partnership | Creates compliant entry pathway for foreign firms targeting Mumbai and Delhi wealth. |
| EU AI Act Certification Investment | Filters algorithmic advisory vendor pools toward established technology providers ahead of enforcement. |
| Family Office Platform Buildout | Monetizes Monetary Authority of Singapore tax incentives redirecting Greater China capital flows. |
Methodological Framework
Document review covered SEC disclosure filings, FINRA regulatory bulletins, and Monetary Authority of Singapore family office framework guidelines, complemented by interviews with wealth management platform executives, certified financial planners, regulatory compliance officers, and fintech partnership leads. Secondary validation drew from SEBI Registered Investment Advisor registration databases, EU MiFID II transparency reports, and cloud-based advisory technology vendor disclosures. Bottom-up client segmentation data triangulated against top-down market size estimates across service type, client tier, engagement model, and asset class dimensions.
Cross-referencing historical advisory platform adoption curves against expert panel input on regulatory timeline probabilities shaped projection modeling across the analysis window. Segmentation dimensions included service type, client sophistication tier, compensation mechanism, and asset class focus. CAGRs derived from regression analysis of advisory fee compression rates, technology substitution elasticities, and regulatory compliance cost trajectories. Industry-specific inputs incorporated fiduciary rule evolution pace, robo-advisor penetration saturation points, and cross-border licensing friction indices.
Caveats apply where SEC fiduciary rule implementation delays, EU AI Act enforcement timeline extensions, or cybersecurity certification backlogs could materially shift the outlook for platform launch economics and competitive consolidation timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Digital Account Opening Market
Financial Services
Direct Selling Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Silver Economy Market
Financial Services
United States Payroll Services Market
Financial Services
Account Aggregators Market
Financial Services
India Legal Services Market
Financial Services
Reconciliation Software Market
Financial Services
Debt Settlement Solution Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Cash Logistics Market
Financial Services
China Financial Services Software Market
Financial Services
Africa Factoring Services Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
E-Brokerage Market