
 Capital Restructuring Services Market | 2026-2036
Capital Restructuring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Capital Restructuring Services Market Analysis
North American distressed-asset capacity is tilting toward complex cross-border mandates. AlixPartners anchors turnaround advisory through deep sector specialization in automotive and retail insolvencies. FTI Consulting leverages forensic accounting and litigation support to sustain premium pricing on contested restructuring engagements. McKinsey & Company competes at the intersection of operational transformation and creditor negotiations, extending its traditional strategy footprint into balance-sheet repair.
Capital restructuring services encompass negotiated modifications to debt covenants, equity recapitalization, and formal insolvency proceedings administered under jurisdictional bankruptcy codes, typically requiring certified valuation methodologies and creditor-class certification protocols. The primary purpose centers on preserving enterprise value while reallocating claims across capital-structure tiers under judicial or contractual supervision. Debt restructuring commands the largest fee pool due to covenant-heavy leveraged lending maturities, yet bankruptcy consulting exhibits the fastest trajectory as regional insolvency regimes expand administrative complexity. Project-based engagements dominate manufacturing verticals where episodic distress drives episodic demand, while retainer relationships concentrate among investment firms managing portfolio-wide exposure.
The US Bankruptcy Code, EU Restructuring Directive, and UK Insolvency Act collectively elevate procedural standards for cross-border recognition, mandating local licensing that fragments service delivery across jurisdictions. SEC disclosure requirements and FERC utility-specific protocols further shape engagement scope for publicly traded and regulated entities. Stakeholders must monitor jurisdictional licensing reciprocity and emerging creditor-rights frameworks to calibrate geographic expansion and partnership structures.
Market Dynamics
Financial distress among leveraged retail chains and manufacturing conglomerates is compressing restructuring timelines from months to weeks, forcing advisory firms to deploy pre-positioned sector teams rather than assemble bespoke engagements. This velocity shift favors specialists with embedded forensic capabilities and pre-cleared jurisdictional licensing.
Growth Catalysts
- US Chapter 11 Subchapter V:Streamlined small-business reorganization procedures lower administrative thresholds, expanding the addressable client base to mid-market manufacturers and regional retail chains previously priced out of formal proceedings.
- EU Restructuring Directive:Mandatory pre-insolvency frameworks across member states create uniform demand for cross-border advisory capacity, particularly in German industrial corridors where distressed automotive suppliers require harmonized creditor negotiations.
- covenant-lite loan maturities:The 2024-2028 wall of leveraged loan expirations concentrates refinancing failures, generating episodic spikes in out-of-court restructuring mandates for private-equity-backed portfolio companies.
Market Restraints
- Regulatory fragmentation:SEC disclosure requirements for publicly traded entities and FERC utility-specific protocols create jurisdictional licensing reciprocity gaps that inflate compliance overhead on multi-state engagements.
- Talent scarcity:Certified valuation professionals with dual bankruptcy-code expertise command premium compensation, compressing margin structures on fixed-fee mandates in secondary markets.
- Substitution by in-house teams:Large investment firms building captive restructuring capabilities displace external advisors on repeat engagements, particularly for standardized debt-for-equity exchanges.
Strategic Opportunities
- Climate-linked distress:EU Green Deal transition financing requirements generate restructuring demand for carbon-intensive manufacturers seeking balance-sheet repair alongside decarbonization capital.
- Digital forensics convergence:Integration of AI-driven document review with traditional valuation methodologies creates differentiated positioning on contested Chapter 11 proceedings with complex intercompany claims.
- India insolvency modernization:IBC code amendments and cross-border recognition protocols under UNCITRAL frameworks open advisory opportunities for distressed steel and textile conglomerates in Gujarat and Maharashtra industrial belts.
Industry Challenges
- Credential portability:Multi-jurisdictional engagements require simultaneous admission to state bars and bankruptcy courts, creating staffing bottlenecks when distressed assets span Delaware, New York, and London restructuring venues.
- Legacy data integration:Manufacturing clients with decades of decentralized ERP systems impose discovery costs that erode fee economics on smaller mandates, particularly in Midwest automotive supplier clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capital Restructuring Services Market |
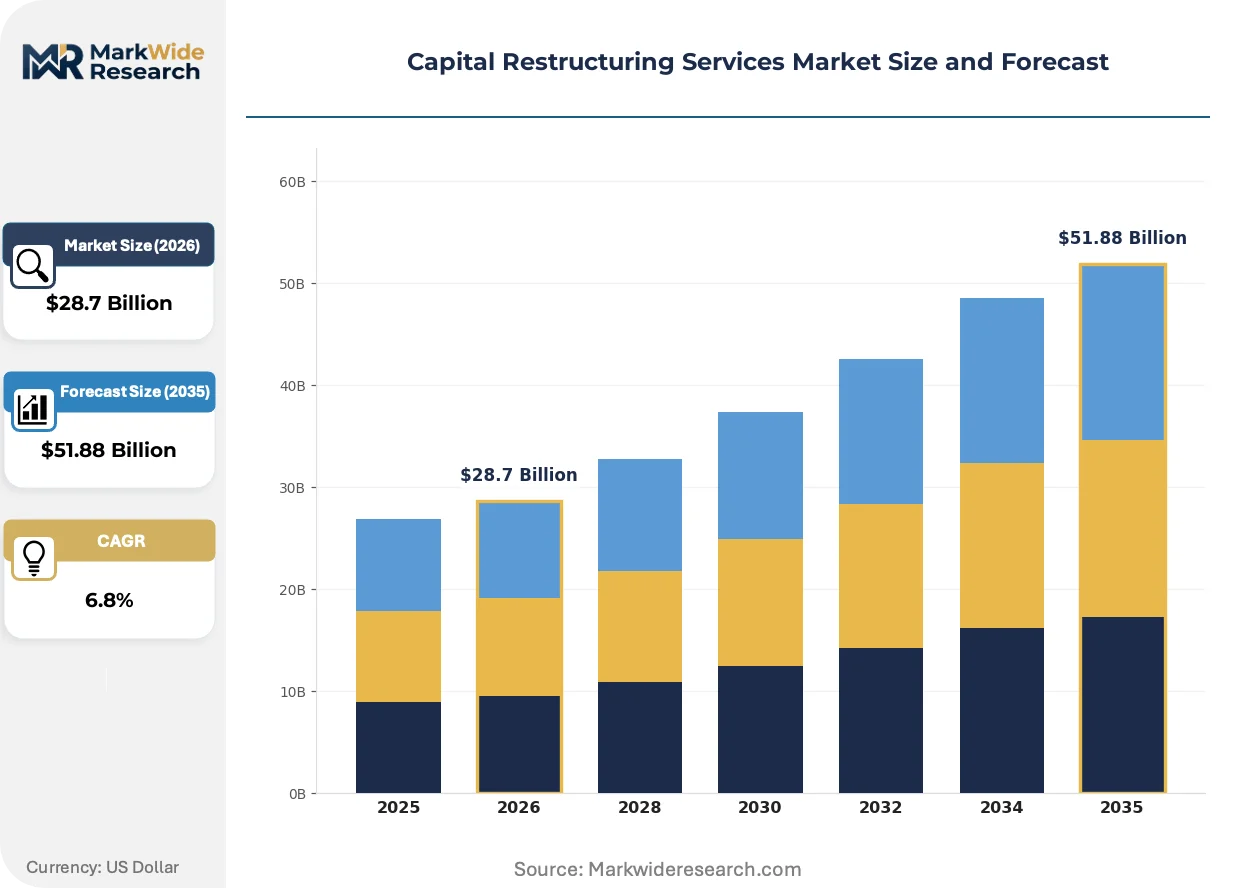
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Debt Restructuring, Equity Restructuring, Financial Advisory, Bankruptcy Consulting Client Type: Corporations, Small Businesses, Startups, Investment Firms Engagement Model: Retainer-Based, Project-Based, Contingency Fee, Hourly Rate Industry Vertical: Real Estate, Manufacturing, Retail, Technology |
| Companies Covered | Bain & Company, KPMG, AlixPartners, FTI Consulting, PwC, Alvarez & Marsal, EY, Grant Thornton, McKinsey & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capital Restructuring Services Market Emerging Trajectories
Restructuring advisory is bifurcating between technology-enabled scale players and relationship-driven boutiques, with data analytics compressing due-diligence timelines while creditor sophistication demands deeper sector specialization. This tension reshapes fee structures and talent deployment models simultaneously.
Artificial intelligence document classification is rendering obsolete manual covenant-compliance review in leveraged-loan restructurings. Large-cap advisory firms now deploy machine-learning models trained on precedent Chapter 11 plans to flag intercreditor conflicts within 48 hours. This compression is rendering obsolete the traditional 90-day diagnostic phase, forcing mid-tier competitors to cede complex mandates or absorb unsustainable labor costs.
EU Restructuring Directive harmonization is eliminating forum-shopping advantages that previously favored UK schemes of arrangement. German and French insolvency practitioners now compete on equal procedural footing, compressing fee premiums previously commanded by London-based advisors on cross-border manufacturing restructurings. Distressed automotive suppliers in Stuttgart and Wolfsburg increasingly retain local counsel with pre-cleared EU-wide recognition rather than defaulting to UK venues.
Fixed-fee outcome arrangements are displacing hourly billing for standardized out-of-court restructurings among private-equity sponsors. This procurement compression concentrates margin risk on advisors while transferring timing uncertainty to service providers. The shift is most visible in US middle-market manufacturing, where sponsor-backed portfolio companies negotiate success-fee caps tied to creditor recovery rates rather than process duration.
Capital Restructuring Services Market Segmentation
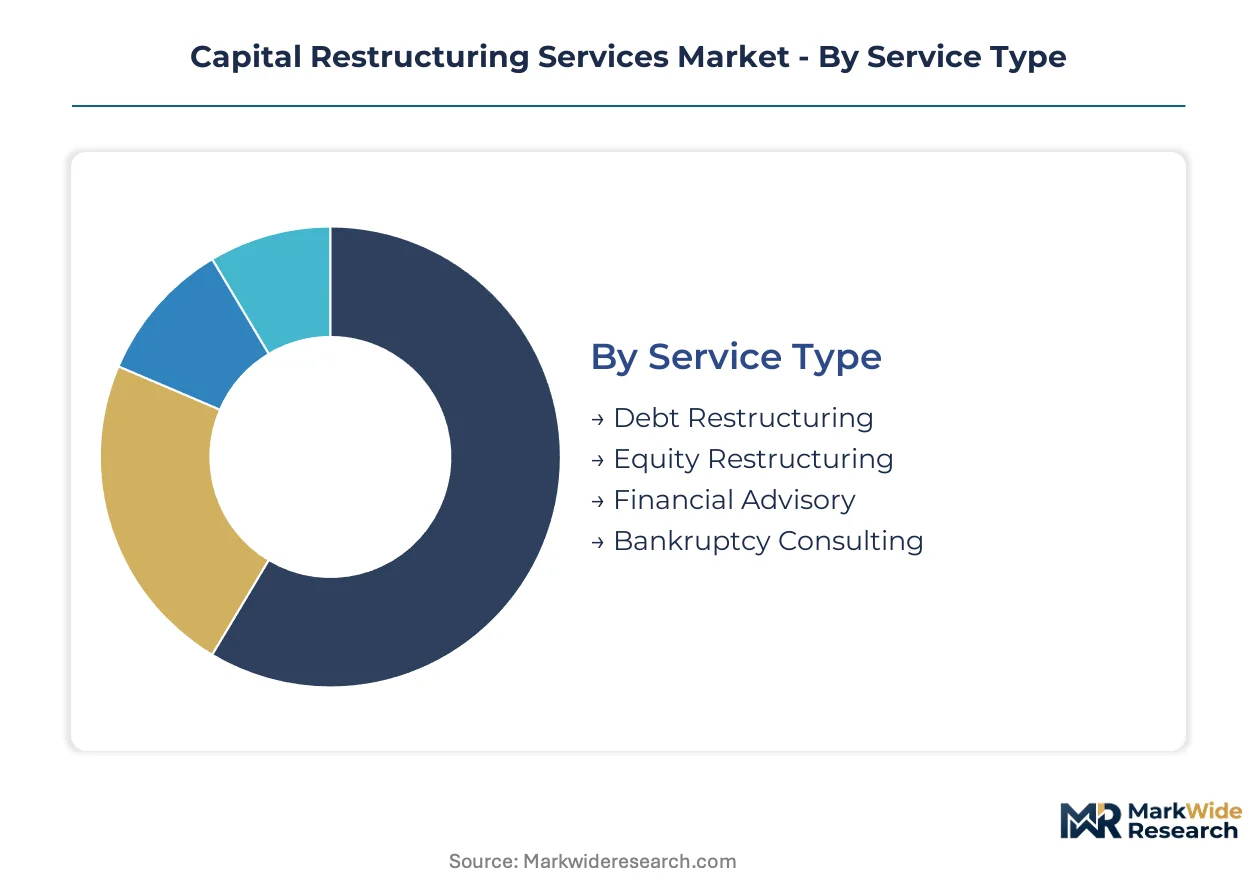
Capital restructuring services fragment across four distinct dimensions that shape pricing power and client retention. Service type determines fee structures and credential requirements. Client type governs deal velocity and margin profiles. Engagement models allocate risk between advisor and sponsor. Industry verticals concentrate demand in cyclical corridors where distress clusters predictably.
Service Type:
Mature advisory lines anchor revenue while emerging specializations capture premium pricing through scarcity.
- Debt Restructuring:Covenant modifications, maturity extensions, and interest-rate resets dominate fee pools across leveraged-finance mandates. Demand concentrates among private-equity-backed portfolio companies in the American Midwest facing 2024-2028 loan maturation walls, driven by sponsor pressure to avoid Chapter 11 triggers.
- Bankruptcy Consulting:Formal insolvency proceedings under US Chapter 11 and EU Restructuring Directive frameworks require certified valuation methodologies and creditor-class certification protocols. German automotive suppliers in Stuttgart and Wolfsburg drive fastest expansion as EU harmonization eliminates UK forum-shopping advantages.
- Equity Restructuring:Recapitalization and rights offerings reshape ownership structures without judicial supervision.
- Financial Advisory:Strategic alternatives reviews and liquidity assessments precede formal restructuring engagements.
Debt Restructuring handles the majority of throughput; Bankruptcy Consulting is the fastest mover on share.
Client Type:
Enterprise scale dictates staffing ratios and jurisdictional licensing complexity.
- Corporations:Large-cap manufacturers and retail chains require multi-jurisdictional teams with simultaneous admission to Delaware, New York, and London restructuring venues. Demand clusters among distressed Midwest automotive suppliers and leveraged retail chains compressing timelines from months to weeks.
- Investment Firms:Private-equity sponsors and distressed-debt funds drive standardized out-of-court mandates with fixed-fee outcome arrangements displacing hourly billing. US middle-market manufacturing sponsors negotiate success-fee caps tied to creditor recovery rates.
- Small Businesses:US Chapter 11 Subchapter V streamlined procedures lower administrative thresholds, expanding addressable base to mid-market manufacturers previously priced out.
- Startups:Venture-backed technology companies facing down-round recapitalizations require specialized equity restructuring expertise.
Corporations generate the deepest fee pools per engagement; Investment Firms are expanding most quickly as captive in-house capabilities displace repeat external advisors.
Engagement Model:
Fee structures allocate timing risk and outcome uncertainty between service provider and client.
- Project-Based:Discrete mandates with defined deliverables dominate manufacturing verticals where episodic distress drives episodic demand. German industrial corridors and American Midwest automotive clusters exhibit pronounced cyclicality.
- Retainer-Based:Ongoing relationships concentrate among investment firms managing portfolio-wide exposure across multiple jurisdictions.
- Contingency Fee:Outcome-dependent compensation aligns advisor incentives with creditor recovery maximization in contested proceedings.
- Hourly Rate:Traditional time-and-materials billing persists in complex litigation support and forensic accounting engagements where scope uncertainty prevents fixed pricing.
Project-Based structures capture the highest volume of mandates; Retainer-Based relationships are climbing the fastest as sponsors seek predictable advisory costs.
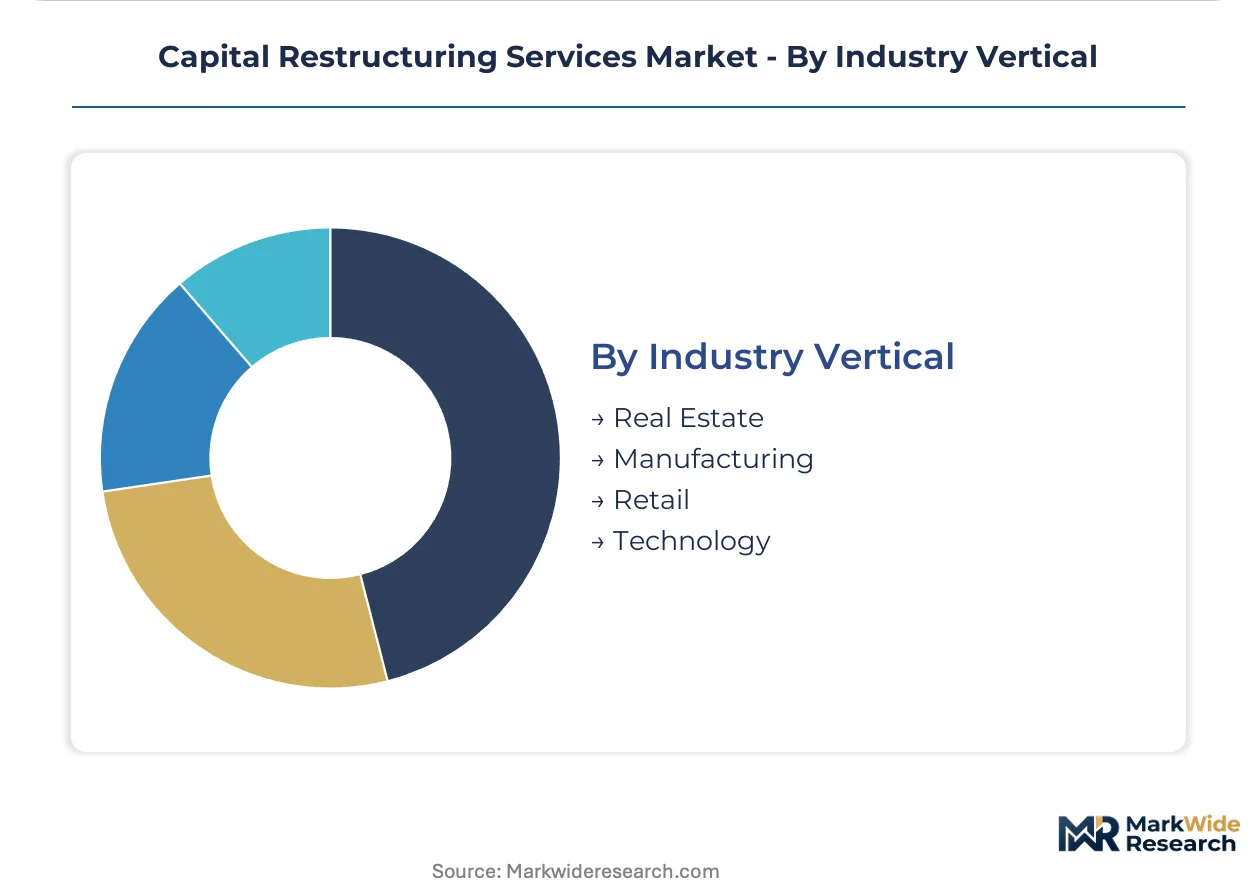
Industry Vertical:
Sector specialization determines competitive positioning through embedded forensic capabilities and pre-cleared licensing.
- Manufacturing:Distressed automotive suppliers and industrial conglomerates in German heartlands and American Midwest require harmonized creditor negotiations under EU Restructuring Directive and US Chapter 11 frameworks. Legacy ERP systems impose discovery cost challenges.
- Retail:Leveraged chains facing compressed restructuring timelines drive demand for pre-positioned sector teams with embedded forensic capabilities.
- Real Estate:Commercial property workouts and REIT recapitalizations involve specialized asset-level valuation and secured-creditor coordination.
- Technology:Software and hardware companies with venture-debt overhang require equity restructuring and strategic alternatives expertise.
Manufacturing vertical commands the deepest specialist expertise; Retail is gaining share fastest as distress accelerates among leveraged chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers deploy capital restructuring services for accelerated Chapter 11 timelines, while German purchasers emphasize EU Restructuring Directive harmonization for cross-border supplier negotiations. This consumption-mix differential shapes service delivery models across jurisdictions.
United States
Distressed automotive suppliers and leveraged retail chains drive compressed restructuring timelines from months to weeks. SEC disclosure requirements and FERC utility-specific protocols shape engagement scope for publicly traded entities. Midwest manufacturing corridors in Michigan and Ohio concentrate demand for pre-positioned sector teams with embedded forensic capabilities.
Germany
Distressed automotive suppliers in Stuttgart and Wolfsburg require harmonized creditor negotiations under EU Restructuring Directive frameworks. The EU Green Deal transition financing requirements generate restructuring demand for carbon-intensive manufacturers seeking balance-sheet repair. Industrial heartlands in Baden-Württemberg and Lower Saxony increasingly retain local counsel with pre-cleared EU-wide recognition.
United Kingdom
Cross-border manufacturing restructurings previously favored UK schemes of arrangement, though EU harmonization now eliminates forum-shopping advantages. The UK Insolvency Act mandates local licensing that fragments service delivery alongside EU frameworks. London-based advisors pivot toward complex litigation support and forensic accounting for contested international proceedings.
India
IBC code amendments and UNCITRAL cross-border recognition protocols open advisory opportunities for distressed steel and textile conglomerates. The country's central bank and SEBI shape disclosure requirements for publicly traded distressed entities. Industrial belts in Gujarat and Maharashtra concentrate demand for restructuring mandates as insolvency modernization accelerates.
Canada
Cross-border recognition with US Chapter 11 frameworks creates integrated advisory demand for manufacturing exporters facing dual-jurisdiction distress. Health Canada and PMRA regulations shape engagement scope for pharmaceutical and agrochemical restructurings. Ontario automotive suppliers leverage harmonized creditor negotiations with Michigan and Ohio counterpart operations.
Capital Restructuring Services Market Vendor Landscape
Capability concentration sits with boutiques possessing embedded sector forensic teams; scale advantage sits with diversified professional services networks with multi-jurisdictional licensing. The market structures around three tiers: turnaround specialists with pre-cleared bankruptcy court admissions, Big Four accounting firms with integrated valuation and tax capabilities, and strategy consultancies extending operational transformation into balance-sheet repair. Dominant competitive moves include strategic partnerships for jurisdictional licensing reciprocity and portfolio diversification into climate-linked distress advisory.
Within the turnaround specialist tier, AlixPartners and FTI Consulting exemplify archetypes differentiated by sector depth versus forensic breadth. Among diversified professional services networks, KPMG and PwC occupy positions spanning accounting, tax, and restructuring under unified brand architecture. McKinsey & Company represents the strategy-consultancy archetype competing at the intersection of operational transformation and creditor negotiations.
| Leading Market Players |
|---|
| Bain & Company |
| KPMG |
| AlixPartners |
| FTI Consulting |
| PwC |
| Alvarez & Marsal |
| EY |
| Grant Thornton |
| McKinsey & Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity among mid-tier restructuring advisory firms in the American Midwest and German industrial corridors is compressing fee realization while accelerating consolidation toward specialists with pre-cleared jurisdictional licensing. This utilization imbalance simultaneously erodes pricing power for generalist providers and concentrates margin capture among embedded sector teams.
Pricing Analysis
Project-based engagement structures dominate fee arrangements for manufacturing verticals where episodic distress drives episodic demand, while retainer relationships concentrate among investment firms managing portfolio-wide exposure. Pricing stratifies across premium, standard, and economy tiers based on credential depth, sector specialization, and jurisdictional licensing breadth. Cost compression in middle-market mandates is intensifying because private-equity sponsors negotiate success-fee caps tied to creditor recovery rates. Investment firms exhibit highest price sensitivity due to standardized procurement protocols, while contested Chapter 11 proceedings with complex intercompany claims show lowest sensitivity due to outcome-dependent compensation alignment.
Supply Chain Analysis
Extended payment terms from distressed corporate clients and supply-chain finance facilities from sponsor-backed portfolio companies shape working capital dynamics for advisory firms. Talent supply concentrates in the United States, United Kingdom, and Germany where certified valuation professionals with dual bankruptcy-code expertise command premium compensation. Raw material inputs for service delivery include licensed legal databases, forensic accounting software, and AI-driven document review platforms. Single-source vulnerability rests on concentrated pools of professionals admitted simultaneously to Delaware, New York, and London restructuring venues. Distribution runs through direct partner relationships with private-equity sponsors, corporate general counsels, and creditor committee chairs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Restructuring Directive harmonization represents a regulatory inflection compressing cross-border advisory premiums while expanding addressable mandate volume. AI-driven document classification simultaneously disrupts traditional due-diligence economics and creates differentiation vectors for technology-enabled scale players.
For Market Incumbents: Build jurisdictional licensing reciprocity as the primary defensive moat against margin erosion from fixed-fee outcome arrangements. Incumbents should acquire boutique specialists with embedded forensic capabilities in automotive and retail verticals to pre-position sector teams before distress spikes. Investment firms building captive restructuring capabilities pose immediate substitution threats requiring deeper retainer relationship lock-in through portfolio-wide exposure management.
For New Entrants and Emerging Players: Climate-linked distress advisory for carbon-intensive manufacturers under EU Green Deal transition financing requirements represents the most penetrable entry point for differentiated positioning. India insolvency modernization under IBC code amendments and UNCITRAL frameworks offers second-mover advantage in distressed steel and textile conglomerates across Gujarat and Maharashtra industrial belts. A go-to-market angle anchored in digital forensics convergence with traditional valuation methodologies bypasses entrenched relationship networks.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because advisory firm fragmentation across jurisdictional licensing boundaries creates roll-up economics for unified multi-venue platforms. Acquisition targets should emphasize boutiques with pre-cleared bankruptcy court admissions and embedded sector forensic teams rather than generalist practices. The signal to watch is accelerated fixed-fee procurement compression forcing mid-tier competitors into distressed sale processes.
| Strategic Initiative | Industry Significance |
|---|---|
| Jurisdictional Licensing Expansion | SEC and FERC protocol expertise opens multi-state engagement scope for publicly traded and regulated entities. |
| Digital Forensics Integration | AI-driven document review with traditional valuation methodologies differentiates positioning on contested Chapter 11 proceedings. |
| Climate-Linked Distress Advisory | EU Green Deal transition financing requirements generate restructuring demand for carbon-intensive manufacturers seeking balance-sheet repair. |
| Cross-Border Partnership Structuring | EU Restructuring Directive harmonization mandates local licensing that fragments service delivery across jurisdictions. |
| Sector Specialization Deepening | Pre-positioned automotive and retail teams capture compressed restructuring timelines from months to weeks. |
Methodological Framework
The analysis maps debt restructuring, bankruptcy consulting, equity restructuring, and financial advisory service lines, each validated through managing directors at turnaround advisory firms, general counsels at distressed manufacturers, private-equity operating partners, and creditor committee financial advisors. Primary interview data triangulates against SEC filings, EU Restructuring Directive implementation reports, bankruptcy court docket analytics, and leveraged loan maturity databases. Bottom-up mandate tracking across identified engagements reconciles with top-down market sizing from professional services revenue disclosures.
Forecast assumptions hold regulatory framework evolution and jurisdictional licensing reciprocity conditions fixed while varying distressed asset volume and sponsor-backed portfolio company distress incidence across the projection horizon. Segmentation dimensions modeled include service type, client scale tier, engagement model structure, and industry vertical concentration. CAGRs derive from fitted growth curves calibrated to historical advisory fee realization patterns and projected loan maturity wall concentrations. Industry-specific inputs encompass Chapter 11 filing velocity indices and EU pre-insolvency framework adoption rates.
Practitioners should monitor regulatory fragmentation intensity and talent scarcity escalation for early signals of forecast deviation. Macroeconomic stress amplification, accelerated insolvency regime harmonization, or breakthrough AI document classification adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Billing and Revenue Management Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Africa Lottery Market
Financial Services
Source to Pay Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
White Glove Services Market
Financial Services
South Korea Factoring Services Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
Global Temporary Labor Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
E-KYC Market
Financial Services
China Financial Services Software Market
Financial Services
Multivendor ATM Software Market
Financial Services
South Korea Trade Finance Market
Financial Services
ATM Outsourcing Services Market