
 Germany Factoring Services Market | 2026-2036
Germany Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Factoring Services Market Insights
CSRD is rebalancing operational disclosure burdens for mid-tier factoring providers across Germany. Deutsche Factoring Bank leverages its captive banking license to sustain lower funding costs than independent competitors. A.B.S. Global Factoring AG anchors its position through specialization in cross-border receivables across Central European manufacturing clients.
Factoring services constitute a structured finance instrument wherein a business sells its accounts receivable to a specialized financial intermediary at a discount, with the factor assuming collection risk and providing immediate liquidity against invoice face value. The mechanism accelerates cash conversion cycles for enterprises with elongated payment terms from trade buyers. Non-recourse factoring captures expanding margin pools as German exporters seek balance-sheet protection against Southern European buyer defaults. Recourse factoring dominates transaction volume among domestic SME clients where credit information transparency reduces risk-pricing spreads. Invoice discounting retains structural importance for large corporations managing working capital without notifying their debtor base.
BaFin supervises factoring entities under Germany's Banking Act where credit transformation occurs, while the EU Green Deal's sustainable finance taxonomy increasingly shapes eligibility criteria for supply-chain financing programs. The German Banking Federation's self-regulatory codes on receivable purchasing transparency constrain pricing practices for SME-facing products. Stakeholders must monitor how the EU AI Act's risk-classification framework affects automated credit-scoring deployments in factoring underwriting workflows.
Market Dynamics
BaFin's tightened capital adequacy rules for non-bank lenders are compressing funding cost differentials between captive banking units and independent factoring providers across Germany's receivables finance landscape.
Growth Catalysts
- Liquidity Constraints in Manufacturing:German automotive suppliers in Baden-Württemberg face elongated payment terms from OEMs. Factoring accelerates cash conversion cycles for these capital-intensive SMEs.
- CSRD Disclosure Mandates:The EU's Corporate Sustainability Reporting Directive requires mid-tier enterprises to enhance supply-chain transparency. This creates structured data requirements that factoring platforms can monetize through integrated reporting tools.
- Cross-Border Receivables Expansion:Central European manufacturing corridors generate growing volumes of export invoices denominated in multiple currencies. Specialized factors capture margin pools from currency risk management and collection services.
Market Restraints
- Capital Adequacy Compression:BaFin's implementation of Basel-aligned rules for non-bank lenders elevates regulatory capital requirements. Independent factoring houses face structurally higher funding costs than bank-captive competitors.
- Credit Information Asymmetry:Southern European buyer defaults create pricing opacity for non-recourse export factoring. Risk premiums compress margins on cross-border transactions to peripheral EU markets.
- Substitution by Supply Chain Finance:Reverse factoring programs offered by major corporate buyers displace traditional receivables purchasing. Large German manufacturers increasingly bypass independent factors through captive supplier financing platforms.
Strategic Opportunities
- Green Taxonomy Alignment:The EU Green Deal's sustainable finance taxonomy creates eligibility criteria for ESG-linked supply-chain financing. Factors can structure premium products around verified low-carbon manufacturing receivables.
- AI-Enabled Underwriting:Automated credit-scoring deployments leveraging machine learning reduce manual review costs. The EU AI Act's risk-classification framework permits high-volume SME onboarding with regulatory clarity.
- North Rhine-Westphalia Industrial Density:Germany's most populous state concentrates diversified manufacturing SMEs with fragmented banking relationships. Local factoring penetration remains below levels observed in automotive-dominated southern regions.
Industry Challenges
- Legacy System Integration:Mid-tier factoring providers operate on aging core banking platforms. API connectivity with client ERP systems requires capital-intensive modernization to match fintech competitor responsiveness.
- Specialized Credit Analyst Scarcity:Cross-border receivables assessment demands multilingual expertise in Central European commercial law. Recruitment pipelines for this hybrid skill set remain underdeveloped in German financial services labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Factoring Services Market |
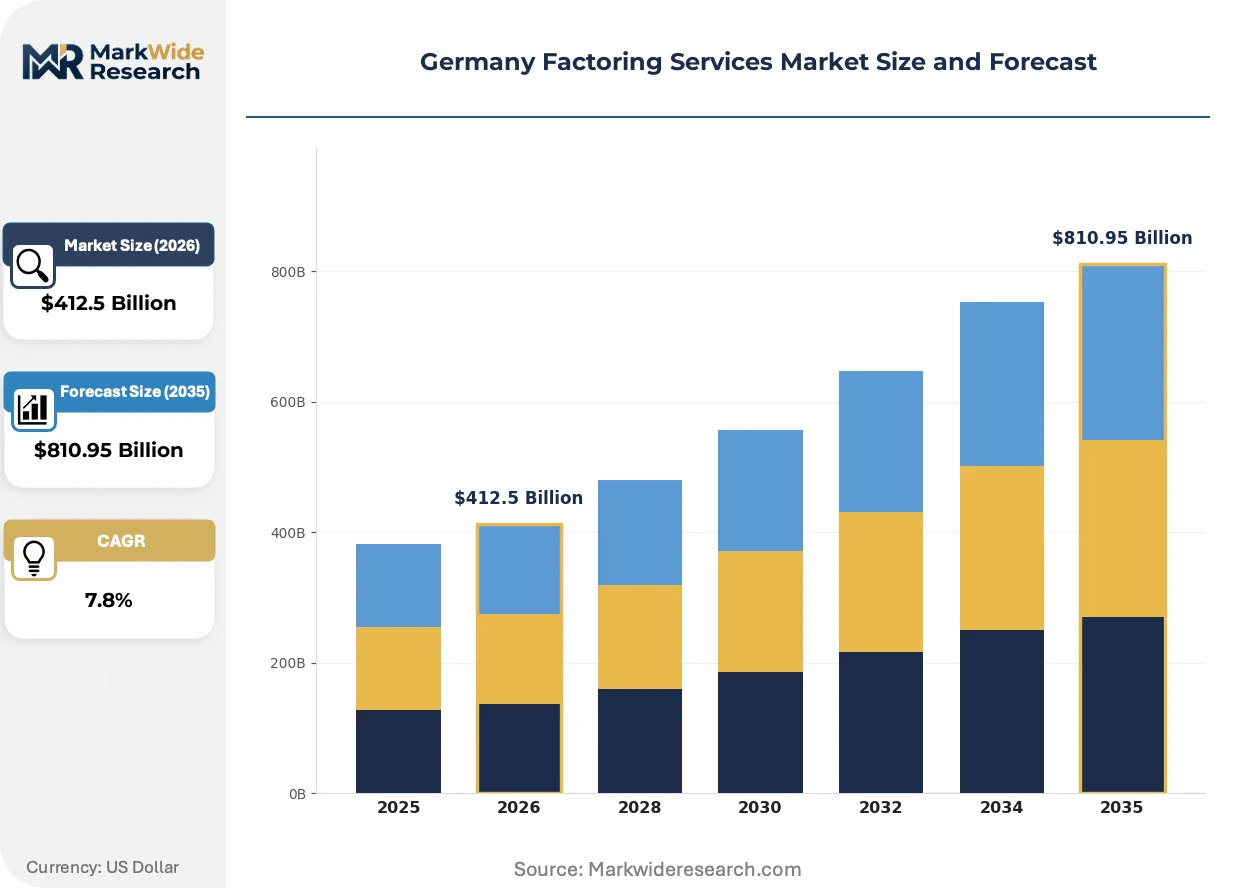
| Market Size in 2026 | $412.5 Billion |
| Market Size in 2035 | $810.95 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-Recourse Factoring, Maturity Factoring, Invoice Discounting, Reverse Factoring Application: Invoice Financing, Cash Flow Management, Risk Mitigation, Credit Protection, Working Capital Optimization, Debt Collection Client Type: Small and Medium Enterprises, Large Corporations, Exporters, Importers, Sole Proprietors Distribution Channel: Direct Sales, Online Platforms, Banking Institutions, Financial Advisors, Independent Brokers |
| Companies Covered | ING Groep N.V., HSBC Holdings plc, A.B.S. Global Factoring AG, Societe Generale SA, Barclays Bank plc, Deutsche Factoring Bank, Banco Santander S.A., UniCredit S.p.a., Deutsche Bank AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Factoring Services Market Trends and Innovations
Digitization of receivables verification and automated risk pricing are compressing operational cost structures across German factoring services. These shifts enable margin expansion while reducing client onboarding friction.
Blockchain-based invoice tokenization is absorbing document verification workflows previously handled through manual trade documentation. Automotive suppliers in Baden-Württemberg adopt this technology for multi-party supply-chain visibility. The mechanism is absorbing fraud detection costs while accelerating payment settlement cycles for complex tiered supplier networks.
CSRD implementation timelines are mandating granular sustainability disclosures from mid-market enterprises. German factoring providers must restructure client data collection to capture Scope 3 emissions and supply-chain labor metrics. Manufacturing exporters in North Rhine-Westphalia face the steepest compliance burdens as they reconcile legacy reporting systems with new EU standardization requirements.
SME treasurers are consolidating working capital management through single-platform solutions. Traditional standalone factoring relationships face displacement from integrated cash management and payables financing suites. This behavioral shift concentrates most visibly among Baden-Württemberg's Mittelstand automotive component suppliers seeking unified banking interfaces.
Germany Factoring Services Market Segmentation
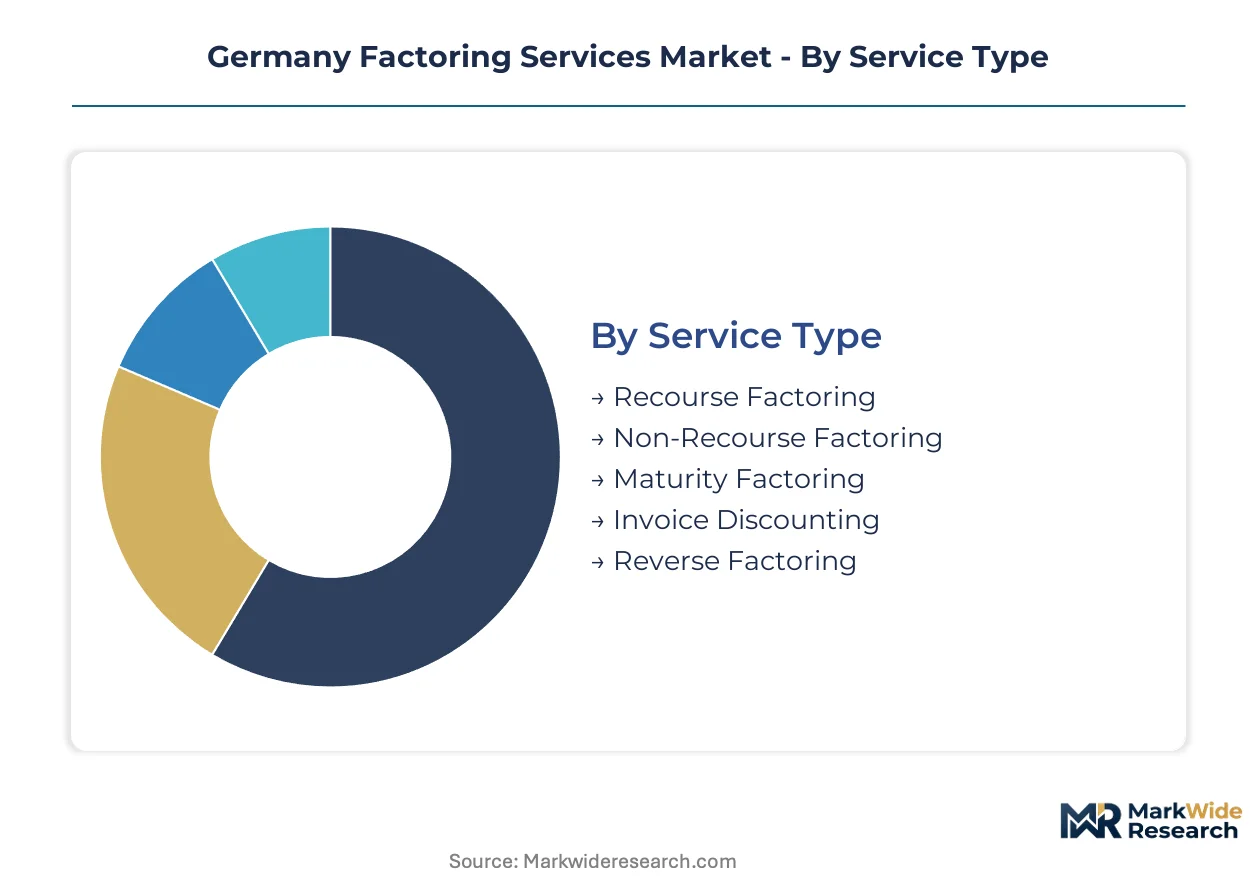
German factoring services fragment across four structural dimensions that determine pricing power, regulatory exposure, and client acquisition economics. Service type and client category configurations dictate capital requirements under BaFin supervision, while application focus shapes technology investment priorities for platform providers.
Service Type:
Recourse structures demand minimal regulatory capital reserves from BaFin-licensed providers, while non-recourse offerings trigger full credit transformation supervision under Germany's Banking Act.
- Recourse Factoring:The factor purchases receivables with the seller retaining default risk, enabling leaner capital deployment and tighter pricing spreads. Baden-Württemberg automotive suppliers dominate uptake, leveraging transparent domestic credit information to minimize risk premiums.
- Non-Recourse Factoring:Full credit risk transfer to the factor requires elevated capital buffers and sophisticated buyer assessment capabilities. German exporters targeting Southern European markets absorb higher pricing to secure balance-sheet protection against peripheral EU default events.
- Maturity Factoring:Payment collection services without advance financing suit enterprises seeking administrative outsourcing rather than liquidity injection. North Rhine-Westphalia manufacturing SMEs deploy this structure for multi-currency receivable management.
- Invoice Discounting:Confidential financing arrangements preserve supplier-debtor relationships while accelerating cash conversion. Large German corporations favor this structure for working capital optimization without notifying their buyer base.
- Reverse Factoring:Buyer-initiated programs leverage corporate credit ratings to secure supplier financing at preferential rates. Major German OEMs displace independent factors through captive platforms anchored to their own balance sheets.
Recourse factoring sits at the top of the volume ranking, with reverse factoring climbing the fastest as corporate buyers consolidate supply-chain financing relationships.
Application:
Application focus determines platform architecture requirements, with invoice financing demanding real-time ERP integration and risk mitigation solutions requiring specialized credit analytics infrastructure.
- Invoice Financing:Immediate liquidity provision against receivable face value accelerates cash conversion for capital-constrained enterprises. Mittelstand manufacturers in automotive supplier belts concentrate demand, driven by elongated OEM payment terms.
- Cash Flow Management:Treasury optimization services integrate factoring with payables and foreign exchange functions. SMEs across fragmented banking relationships in North Rhine-Westphalia adopt bundled solutions for operational simplicity.
- Risk Mitigation:Credit protection and collection outsourcing transfers administrative burden and default exposure to specialized intermediaries. Cross-border exporters absorb premium pricing for multilingual legal expertise in Central European commercial frameworks.
- Credit Protection:Standalone buyer default insurance complements or substitutes traditional factoring arrangements. German exporters to high-volatility markets deploy this structure for selective risk transfer without full receivable sale.
- Working Capital Optimization:Holistic balance-sheet management combines factoring with inventory financing and supply-chain finance. Large corporate treasurers consolidate vendor relationships through single-platform solutions.
- Debt Collection:Recovery services for aged receivables leverage specialized legal enforcement capabilities across German federal states. Factors with established attorney networks capture margin pools from distressed asset workflows.
Invoice financing commands the largest revenue pool, while working capital optimization gains share fastest as treasury platform consolidation accelerates.
Client Type:
Client scale determines service configuration, with SME segments requiring standardized onboarding automation and large corporations demanding bespoke structuring and multi-jurisdictional coverage.
- Small and Medium Enterprises:Capital-constrained Mittelstand manufacturers drive core transaction volume, particularly in automotive-dominated southern regions. CSRD disclosure mandates create data integration opportunities for factors offering sustainability-linked reporting tools.
- Large Corporations:Sophisticated treasury functions demand confidential invoice discounting and integrated cash management solutions. Reverse factoring programs displace traditional receivable purchasing as buyers internalize supplier financing.
- Exporters:Cross-border receivable specialists require currency hedging and collection expertise across Central European legal frameworks. Non-recourse structures absorb elevated pricing for Southern European buyer default protection.
- Importers:Domestic distribution enterprises leverage factoring for inventory financing against import receivables. North Rhine-Westphalia logistics corridors concentrate demand for multi-currency working capital solutions.
- Sole Proprietors:Micro-enterprise segments face limited factor penetration due to high per-transaction onboarding costs. Digital platform automation under EU AI Act risk frameworks may expand addressable population.
SMEs anchor transaction volume, with exporters expanding most quickly as Central European manufacturing integration deepens.
Distribution Channel:
Channel economics vary sharply, with direct sales sustaining premium pricing and digital platforms compressing acquisition costs through automated underwriting workflows.
- Direct Sales:Relationship-managed acquisition targets mid-market enterprises with complex multi-entity structures. Established factors deploy industry-specialized coverage teams for Baden-Württemberg automotive supplier penetration.
- Online Platforms:Self-service onboarding and automated credit scoring reduce marginal acquisition costs for standardized SME transactions. API connectivity with accounting software providers expands distribution reach without proportional sales force investment.
- Banking Institutions:Captive factoring subsidiaries leverage parent balance sheets for funding cost advantages. Deutsche Factoring Bank and comparable bank-owned entities dominate this channel through regulatory arbitrage.
- Financial Advisors:Intermediary referral networks capture commission-based placement for specialized or distressed situations. Independent brokers maintain relevance where complex cross-border structuring demands bespoke expertise.
- Independent Brokers:Third-party distribution aggregates fragmented SME demand for factor platform access. Commission structures align incentives toward transaction completion rather than ongoing relationship management.
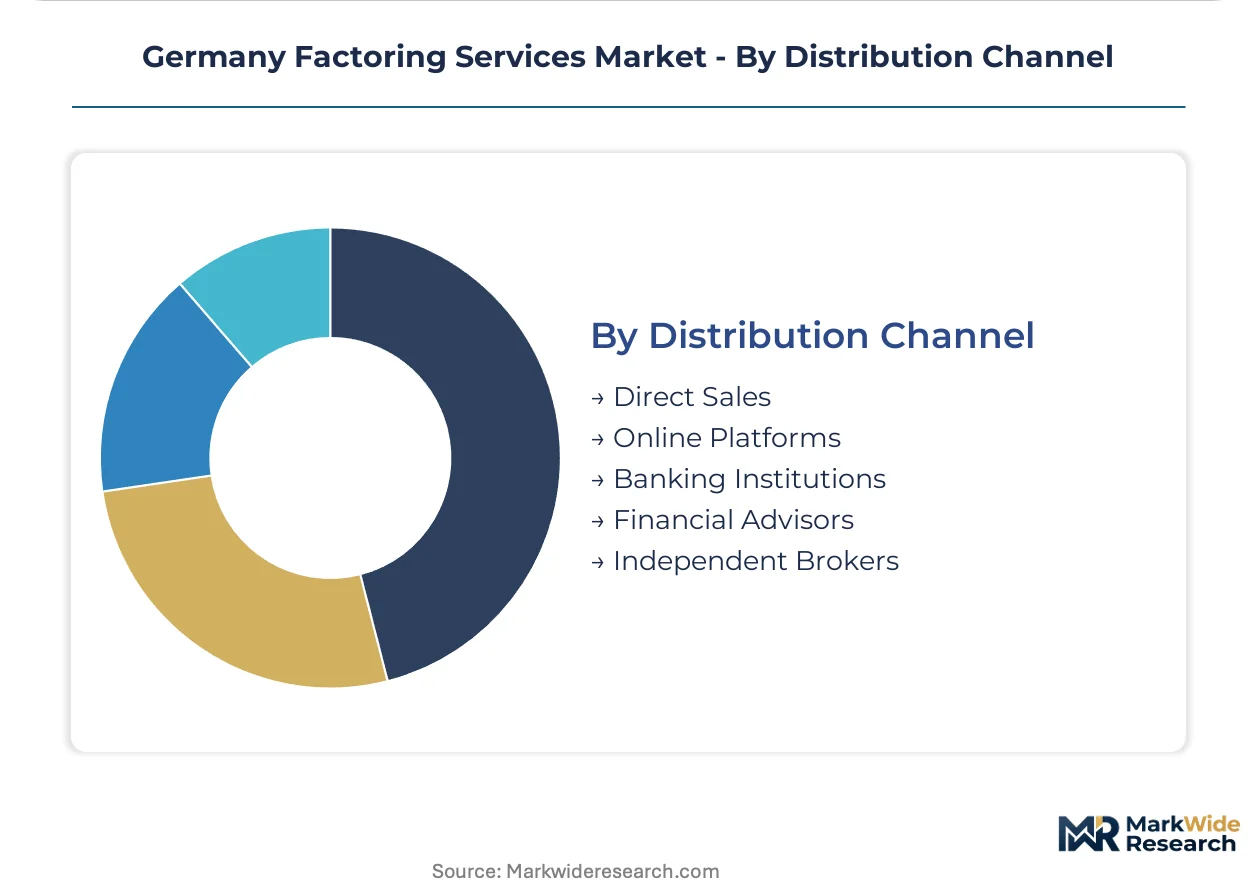
Direct sales retains the steepest margin profile, with online platforms scaling fastest as API integration standardizes across German ERP systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German factoring expertise concentrates in industrial finance clusters anchored by Stuttgart's automotive supplier networks and Düsseldorf's banking infrastructure. These workforce pools sustain specialized credit assessment capabilities across receivables finance.
Baden-Württemberg
Automotive component manufacturers dominate demand as elongated OEM payment terms strain Mittelstand liquidity. BaFin's Banking Act supervision applies to full-service factors operating here. Stuttgart's supplier belt generates concentrated invoice volumes from tier-1 and tier-2 automotive relationships.
North Rhine-Westphalia
Diversified manufacturing SMEs across machinery, chemicals, and logistics drive adoption outside automotive-centric southern markets. The EU Green Deal's sustainable finance taxonomy shapes eligibility for ESG-linked supply-chain programs. Düsseldorf and Cologne banking corridors host captive factoring subsidiaries leveraging parent balance sheets.
Bavaria
Precision engineering and electronics exporters generate cross-border receivable flows into Central European manufacturing networks. CSRD disclosure mandates create structured data requirements for mid-market enterprises. Munich's industrial periphery concentrates demand for multi-currency working capital solutions.
Hesse
Frankfurt's financial infrastructure anchors back-office functions and regulatory compliance operations for national factoring platforms. The EU AI Act's risk-classification framework governs automated credit-scoring deployments. Rhein-Main logistics corridors sustain import-focused factoring for distribution enterprises.
Lower Saxony
Wind energy supply chains and agricultural machinery manufacturers create specialized receivables profiles. Germany's Banking Federation self-regulatory codes constrain pricing transparency for SME-facing products. Hanover and Brunswick industrial zones exhibit below-national factoring penetration rates relative to manufacturing output.
Germany Factoring Services Market Competitive Landscape
The competitive structure tilts toward bank-captive subsidiaries with funding cost advantages over independent specialists. Three archetypes populate the landscape: universal banking groups with dedicated factoring divisions, independent non-bank factors pursuing niche verticals, and fintech-enabled platforms automating SME onboarding. Consolidation pressures intensify as regulatory capital requirements compress margins for standalone operators. Strategic moves center on API integration with client ERP systems and sustainability-linked product structuring.
Among bank-captive entities, Deutsche Factoring Bank and ING Groep N.V. occupy positions leveraging regulatory arbitrage through parent balance sheet access. A.B.S. Global Factoring AG exemplifies the independent specialist archetype, anchoring its market presence through cross-border receivables expertise. These three entities represent distinct competitive vectors: regulatory-scale efficiency, relationship-driven specialization, and technology-enabled automation.
| Leading Market Players |
|---|
| ING Groep N.V. |
| HSBC Holdings plc |
| A.B.S. Global Factoring AG |
| Societe Generale SA |
| Barclays Bank plc |
| Deutsche Factoring Bank |
| Banco Santander S.A. |
| UniCredit S.p.a. |
| Deutsche Bank AG |
| Others |
Pricing and Supply Chain Analysis
SME treasurers in Baden-Württemberg's automotive supplier belt increasingly demand bundled working capital solutions that integrate factoring with payables financing and foreign exchange functions. This procurement preference forces independent factors to restructure service architectures and compresses pricing spreads on standalone receivables purchasing.
Pricing Analysis
Bundled service offerings versus unbundled transactional factoring define the pricing architecture across Germany's receivables finance landscape. Three-tier pricing structure across premium advisory, standard operational, and economy automated tiers separates relationship-managed mid-market accounts from self-service SME platforms. Cost compression in economy tiers is intensifying because API-enabled competitors reduce manual underwriting overhead. Mittelstand manufacturers with fragmented banking relationships exhibit highest price sensitivity, while large corporate treasurers prioritize service integration over rate minimization.
Supply Chain Analysis
BaFin licensing and EU AI Act compliance certification gate factor entry into Germany's regulated receivables finance market. Technology vendors concentrate in Ireland, Estonia, and Lithuania for cloud infrastructure serving automated underwriting platforms. Funding draws from parent bank balance sheets, institutional credit lines, and securitization markets. Single-source vulnerability runs through core banking platform providers serving mid-tier factors. Distribution runs through direct sales teams for complex multi-entity structures and API-integrated online platforms for standardized SME transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's factoring services market functions as a stable compounder anchored by persistent liquidity constraints among capital-intensive Mittelstand manufacturers. BaFin's regulatory framework creates durable competitive moats for licensed operators.
For Market Incumbents: Extend API connectivity investments to match fintech competitor responsiveness in SME onboarding workflows. Deepen vertical integration into sustainability data collection infrastructure to capture CSRD-driven reporting tool demand. Independent factors face displacement risk from reverse factoring programs offered by major OEMs; defend through specialized cross-border expertise in Central European legal frameworks. For New Entrants and Emerging Players: North Rhine-Westphalia's diversified manufacturing SMEs represent an underserved buyer archetype with below-national factoring penetration relative to industrial output. White-space targets include ESG-linked supply-chain financing for Green Deal taxonomy alignment and AI-enabled underwriting for sole proprietor micro-enterprises under regulatory risk-classification clarity. Go-to-market through accounting software API partnerships minimizes direct sales force investment. For Investors and Strategic Acquirers: Asymmetric upside sits with bank-captive factoring subsidiaries leveraging regulatory arbitrage through parent balance sheet access. Long-term viability rests on durable funding cost advantages as Basel-aligned capital requirements compress independent operator margins. Acquisition target archetype: independent factors with established Central European cross-border expertise and modernized core platforms. Signal to watch: BaFin enforcement intensity on non-bank lender capital adequacy compliance.| Strategic Initiative | Industry Significance |
|---|---|
| API-ERP Integration | Self-service onboarding reduces marginal acquisition costs for standardized Mittelstand transactions across Baden-Württemberg. |
| CSRD Data Infrastructure | Structured sustainability disclosure collection creates premium product eligibility under EU Green Deal taxonomy criteria. |
| AI Act Compliance Investment | Automated credit-scoring deployments gain regulatory clarity for high-volume SME risk assessment workflows. |
| Cross-Border Legal Expertise | Multilingual Central European collection capabilities capture margin pools from export receivables to peripheral EU markets. |
| Reverse Factoring Platform Development | Buyer-initiated programs displace independent factors; captive structures leverage corporate credit ratings for supplier financing. |
Research Methodology
Multiple input streams — factoring platform executives, SME treasury managers at automotive suppliers, BaFin regulatory specialists, and ERP integration consultants — were reconciled against trade association disclosures and banking federation publications. Primary interviews with risk officers at captive factoring subsidiaries, credit analysts at independent factors, and procurement leads at Tier 1 automotive suppliers informed operational dynamics. Secondary validation drew from Bundesbank payment system statistics, EU sustainable finance taxonomy technical screening criteria, and KfW SME financing survey data. Bottom-up transaction volume estimates and top-down banking sector allocation models were triangulated for consistency.
Historical receivables growth patterns were cross-referenced against panel input from industry practitioners across the projection horizon. Segmentation dimensions modeled include service type configuration, client scale tier, application focus, and regional industrial cluster. CAGRs were derived through driver-based modeling linking manufacturing output growth, payment term extension trends, and regulatory capital requirement evolution. Industry-specific forecast inputs incorporate automotive supplier liquidity stress indicators and CSRD implementation timeline compliance burdens.
Underlying measurement precision varies by segment; recourse factoring volume estimates carry tighter precision than non-recourse export exposure given data availability asymmetries. Forecasts reflect assumptions on BaFin supervisory intensity, EU AI Act enforcement phasing, and Mittelstand payment behavior stability. Deviation in OEM payment term policies or peripheral EU sovereign credit events would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Treasury Management Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Global Product Cost Management Market
Financial Services
China Supply Chain Financing Market
Financial Services
BFSI A2P SMS Market
Financial Services
Spain E-Brokerage Market
Financial Services
E-Invoicing Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
E-Brokerage Market
Financial Services
Belgium Gift Card and Incentive Card Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
Latin America Factoring Services Market
Financial Services
North America Financial Advisory Services Market