
 Reusable Period Panties Market | 2026-2036
Reusable Period Panties Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Period Panties Market Outlook
Teenager and young adult adoption through school wellness programs and university sustainability initiatives is expanding the addressable base for reusable period panties. Thinx leverages its brand strength in direct-to-consumer education to sustain engagement with first-time users. Modibodi anchors the Australasian market through localized manufacturing and climate-adapted product ranges. Knix competes aggressively in North American specialty retail, controlling shelf presence in premium department stores and independent boutiques.
Reusable period panties are engineered multi-layer garments combining moisture-wicking top sheets, antimicrobial absorbent cores, and leak-resistant backings, typically constructed from organic cotton, bamboo viscose, or recycled synthetic blends with absorbency ratings from light flow to super absorbent. Their primary commercial purpose is to replace disposable menstrual products through washable, reusable alternatives that reduce waste and long-term consumer expenditure. Heavy flow and super absorbent segments dominate unit volume due to functional necessity driving repeat purchase, while organic cotton variants command margin premiums through certification differentiation. Subscription services represent the fastest-growing distribution channel, capturing recurring revenue and reducing customer acquisition costs relative to one-time online retail transactions.
The EU Green Deal and REACH chemical safety standards shape material sourcing and textile certification requirements across European markets, while the US FDA regulates absorbency claims and product safety labeling for menstrual devices sold domestically. BIS textile standards in India and China's GB standards for textile hygiene products create divergent compliance pathways that fragment manufacturing and testing protocols. Stakeholders must monitor evolving extended producer responsibility frameworks for textiles and anticipate how regional chemical restrictions will reshape acceptable fiber compositions and coating technologies.
Market Dynamics
EU Green Deal textile sustainability mandates are forcing rapid material transitions across the reusable period panties value chain, compressing development timelines for certified organic and recycled fiber alternatives while fragmenting compliance pathways across national implementations.
Growth Catalysts
- REACH chemical safety standards:European manufacturers accelerate substitution of synthetic coatings with bio-based alternatives, opening premium positioning for certified clean-label products.
- School wellness program integration:Educational institutions in Germany and France incorporate reusable menstrual products into student health curricula, normalizing first-time trial among teenagers.
- Recycled polyester fiber blends:Mechanical recycling advances reduce virgin petroleum dependence while maintaining absorbency performance thresholds required for heavy-flow segments.
Market Restraints
- Organic cotton price volatility:Climate-induced yield fluctuations in India and Turkey inflate raw material costs unpredictably, squeezing margin structures for mid-tier producers.
- Absorbency testing protocol fragmentation:Divergent FDA, BIS, and GB standards require multiple certification rounds, extending time-to-market for cross-border launches.
- Disposable menstrual cup substitution:Lower per-unit cost and established retail presence of silicone cups capture price-sensitive consumers seeking waste reduction without laundry burden.
Strategic Opportunities
- Subscription channel expansion:Direct-to-consumer recurring revenue models reduce customer acquisition costs while building predictable demand baselines for capacity planning.
- Extended producer responsibility frameworks:Pending EU textile waste regulations will mandate take-back schemes, favoring brands with established circular logistics infrastructure.
- Postpartum and incontinence applications:Absorbent garment technology transfers to adjacent medical-adjacent segments with higher willingness-to-pay and reimbursement potential.
Industry Challenges
- Antimicrobial chemistry expertise scarcity:Formulation chemists capable of balancing efficacy against skin-safety certification requirements command premium compensation, constraining R&D throughput.
- Multi-standard compliance timeline compression:Simultaneous FDA absorbency claim validation and EU organic textile certification processes extend product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Period Panties Market |
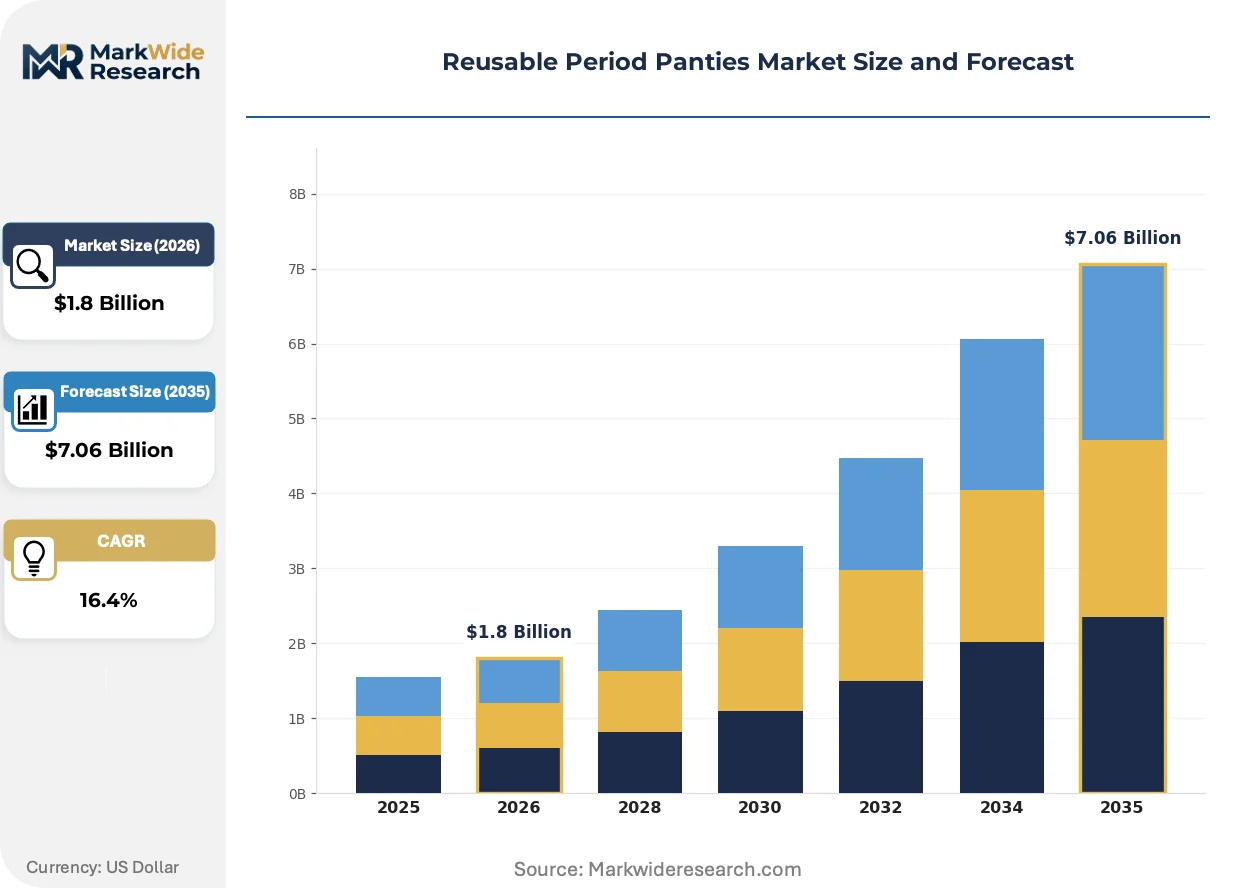
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Flow, Heavy Flow, Super Absorbent, Organic Cotton Customer Type: Teenagers, Young Adults, Women, Eco-Conscious Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Subscription Services Pricing Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Knix, Proof, Thinx, Rael, Neione, Modibodi, Ruby Love, FANNYPANTS, Saalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Period Panties Market Strategic Shifts
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape product architecture across absorbency tiers, while distribution economics favor recurring revenue models over transactional retail.
Biodegradable TPU laminate barriers are expanding into super-absorbent product tiers previously dominated by petroleum-derived polyurethane. Teenager and young adult segments in Nordic markets demonstrate fastest uptake of these plant-derived alternatives. This substitution is expanding into premium pricing tiers as certification differentiation justifies 15-30% unit premiums over conventional constructions.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating long-chain water-repellent chemistries from European-sourced textiles. Manufacturers reformulate with silicone-based or paraffin-derived alternatives, sacrificing some durability for compliance certainty. German and French brands face tightest enforcement timelines, compressing supplier qualification windows to 12-18 months.
Educational procurement through school district bulk purchasing is displacing individual retail trial as the dominant customer acquisition pathway for first-time users. United Kingdom and Netherlands wellness programs negotiate multi-year supply agreements with absorbency-tiered product bundles. This channel consolidation concentrates volume with vendors capable of GOTS-certified manufacturing at 10,000+ unit scale.
Reusable Period Panties Market Segmentation
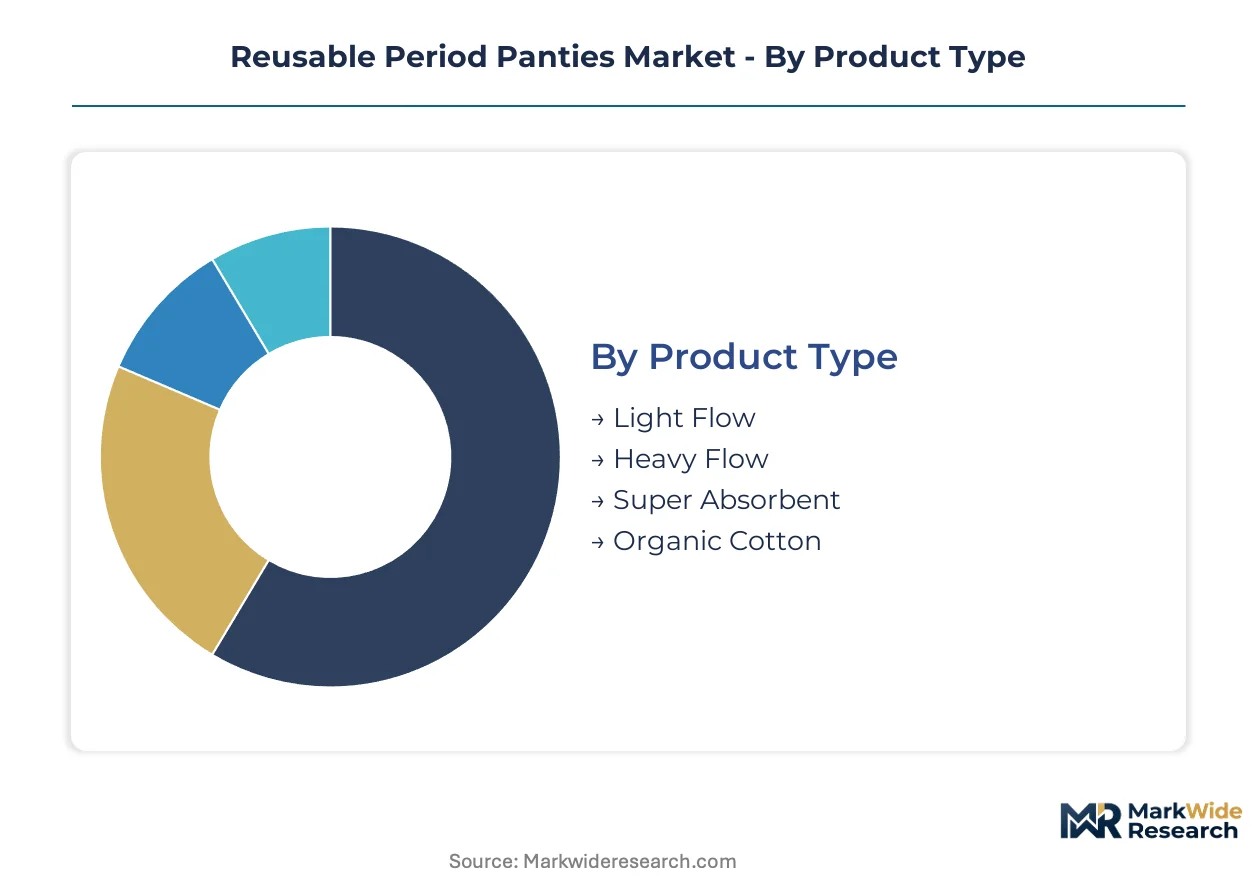
Reusable period panties segment across functional performance, demographic life stages, and purchasing contexts that shape material specifications and channel economics. Each segmentation axis reveals distinct margin structures and loyalty patterns that manufacturers must align against.
Product Type:
Absorbency rating determines manufacturing complexity, certification requirements, and repeat purchase frequency across the user base.
- Heavy Flow:Multi-layer construction with antimicrobial cores and leak-resistant barriers addresses the highest functional necessity. Demand concentrates among working-age women in Germany and France where workplace discretion drives premium willingness-to-pay.
- Super Absorbent:Maximum-capacity engineering with extended-wear certification supports overnight and postpartum applications. Adoption accelerates through NHS procurement frameworks in the United Kingdom and hospital discharge kit integrations.
- Light Flow:Slim-profile designs with moisture-wicking top layers serve backup protection and spotting needs. Lower price points attract first-time trialists through online sampling programs.
- Organic Cotton:GOTS-certified fiber constructions with chemical-free processing command certification premiums. Supply concentrates with Turkish and Indian organic cotton processors facing climate yield volatility.
Volume sits with Heavy Flow; growth tilts toward Super Absorbent.
Customer Type:
Life-stage positioning shapes education requirements, channel selection, and brand relationship depth.
- Teenagers:School wellness program distribution normalizes first exposure through bulk procurement and peer normalization. Germany's federal state education ministries and France's regional health authorities drive institutional adoption.
- Eco-Conscious Consumers:Carbon-footprint transparency and end-of-life take-back programs anchor loyalty. This segment demonstrates highest subscription conversion and cross-category purchasing across sustainable personal care.
- Young Adults:University sustainability initiatives and social media discovery patterns dominate acquisition. Price sensitivity moderates against ethical positioning.
- Women:Broad demographic catch-all spanning perimenopause through established menstrual management, served through diversified retail presence.
Acquisition concentrates with Teenagers; lifetime value peaks with Eco-Conscious Consumers.
Distribution Channel:
Channel selection determines margin capture, data ownership, and customer relationship continuity.
- Subscription Services:Recurring revenue models with absorbency-tiered bundles reduce customer acquisition costs and enable demand forecasting. Fastest-expanding channel across Nordic markets and United Kingdom direct-to-consumer platforms.
- Online Retail:Transactional marketplaces with review-driven discovery serve price-comparison shoppers and geographic markets lacking specialty retail infrastructure.
- Specialty Stores:Premium department store placement and independent boutique curation support tactile evaluation and gift purchasing occasions.
- Supermarkets:Mass-market penetration with standardized absorbency tiers reaches convenience-oriented shoppers through established grocery loyalty programs.
Transaction volume flows through Online Retail; margin expansion concentrates in Subscription Services.
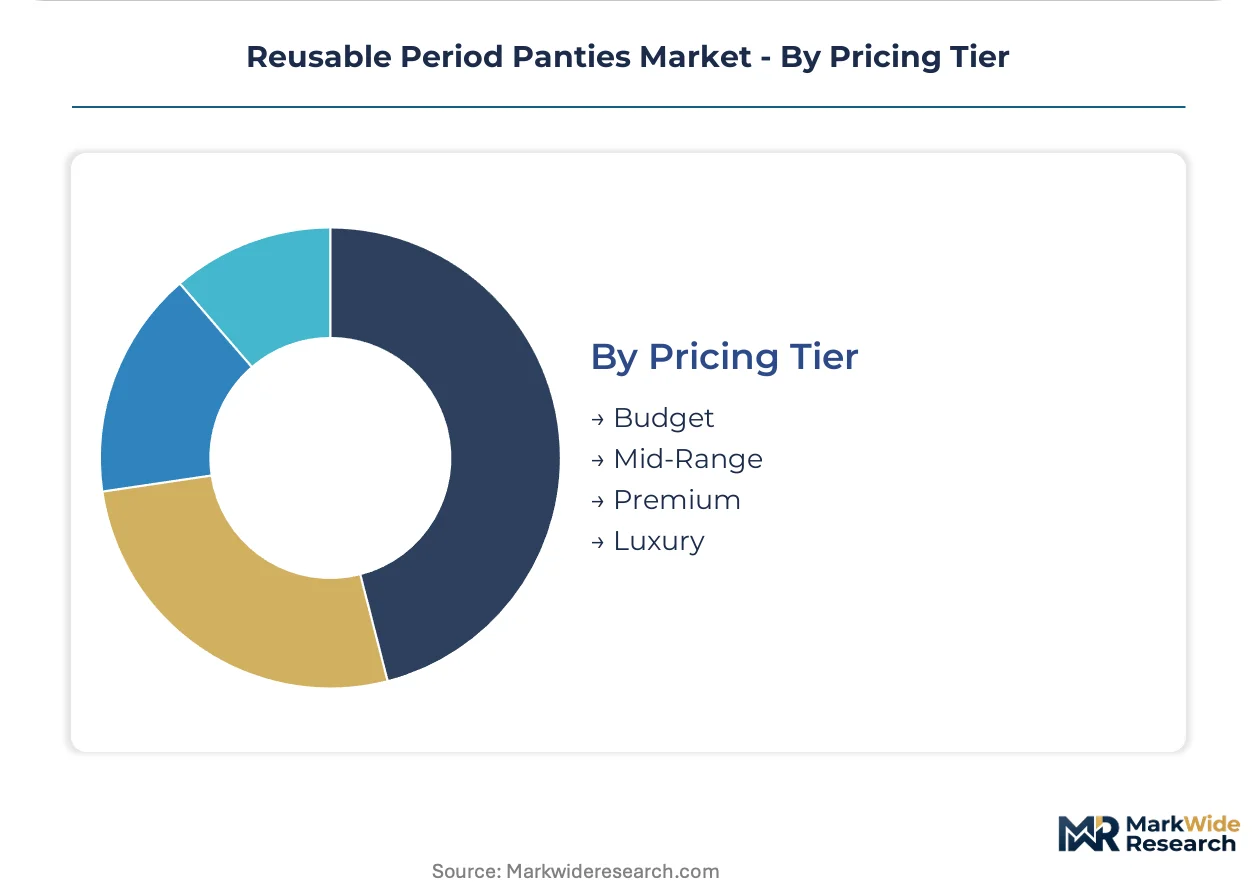
Pricing Tier:
Price positioning aligns material certification, manufacturing geography, and distribution overhead against willingness-to-pay segmentation.
- Premium:GOTS-certified organic constructions with biodegradable TPU barriers and extended-wear engineering. German and French specialty retail placement supports 15-30% unit premiums over standard tiers.
- Mid-Range:Blended fiber constructions balancing absorbency performance with accessible pricing. Dominates volume across supermarket and mainstream online channels.
- Budget:Basic absorbent core designs with conventional synthetic barriers serve price-sensitive entry trial. Highest churn and lowest repeat rates.
- Luxury:Designer collaborations, limited editions, and concierge service models with personalized fit consultations. Niche positioning through exclusive retail partnerships.
Unit economics favor Premium; volume concentrates in Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Southeast Asia and special economic corridors in Eastern Europe are concentrating contract manufacturing capacity for textile hygiene products. These zones attract investment through tariff exemptions and streamlined customs processing. The resulting geographic dispersion creates divergent regulatory compliance pathways for brands serving multiple markets.
Germany
Federal state education ministries in Bavaria and North Rhine-Westphalia procure reusable period panties through bulk wellness program tenders. The EU Green Deal's textile sustainability mandates accelerate GOTS-certified manufacturing transitions. Industrial clusters around Stuttgart and Munich host specialized antimicrobial chemistry R&D facilities serving domestic brands.
United States
FDA absorbency claim regulations shape product labeling requirements for direct-to-consumer brands. University sustainability initiatives in California and Massachusetts drive campus procurement programs. The Pacific Northwest corridor from Seattle to Portland concentrates organic cotton processing infrastructure and subscription fulfillment operations.
France
Regional health authorities in Île-de-France and Auvergne-Rhône-Alpes integrate reusable menstrual products into student health curricula. REACH Annex XVII restrictions on PFAS chemicals eliminate long-chain water-repellent treatments from domestic supply chains. Lyon-based textile research institutes pioneer silicone-based barrier alternatives for leak-resistant layers.
United Kingdom
NHS procurement frameworks for postpartum care accelerate super-absorbent product adoption through hospital discharge kits. Extended producer responsibility consultations for textiles mandate future take-back scheme participation. Manchester and Leeds manufacturing zones scale GOTS-certified production for educational bulk purchasing contracts.
Australia
Therapeutic Goods Administration guidance on menstrual device classification influences absorbency testing protocols for domestic brands. University sustainability programs in Melbourne and Sydney normalize first-time trial through campus retail partnerships. Localized manufacturing in Victoria adapts product ranges to climate-specific moisture management requirements.
Reusable Period Panties Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer labels capturing margin premiums while OEM fabricators dominate unit volume in private-label arrangements. The vendor base organizes into three tiers: vertically integrated specialists controlling organic cotton supply chains, technology licensors offering antimicrobial coating formulations, and regional cut-and-sew contractors serving price-sensitive markets. Consolidation pressures favor brands with captive GOTS-certified manufacturing capacity. Strategic moves concentrate on subscription platform acquisitions and circular logistics infrastructure buildouts.
Within the direct-to-consumer branded tier, Thinx and Knix exemplify divergent geographic anchoring strategies, with the former leveraging educational content for first-user acquisition and the latter controlling premium retail shelf presence. Modibodi occupies a position as the Australasian market reference point through climate-adapted product development. Among specialty retail channels, Proof and Rael represent the subscription-native archetype with recurring revenue models reducing customer acquisition costs relative to transactional competitors.
| Leading Market Players |
|---|
| Knix |
| Proof |
| Thinx |
| Rael |
| Neione |
| Modibodi |
| Ruby Love |
| FANNYPANTS |
| Saalt |
| Others |
Value Chain & Pricing Dynamics
NHS procurement frameworks mandating GOTS-certified super-absorbent products for postpartum discharge kits are compressing supplier qualification timelines and forcing mid-tier manufacturers to absorb certification premiums or exit tender participation. This demand-side specification tightening cascades through contract manufacturing networks, concentrating volume with vertically integrated specialists and widening price spreads between certified and uncertified production tiers.
Pricing Analysis
Short lead-time premiums for GOTS-certified organic cotton constructions command 15-30% unit markups over standard fiber alternatives, while spot inventory discounts attract price-sensitive trialists in online retail channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and absorbency performance, with organic cotton variants capturing margin premiums through EU Green Deal compliance positioning. Cost compression in mid-range tiers is intensifying because Turkish and Indian organic cotton processors face climate-induced yield volatility. Budget-tier shoppers exhibit highest price sensitivity, while eco-conscious consumers demonstrate lowest elasticity against certification-driven premiums.
Supply Chain Analysis
Skilled cut-and-sew workforce availability in Bangladesh, Vietnam, and Turkey determines production capacity allocation for absorbent garment assembly, with GOTS-certified facilities commanding labor premiums. Raw material sourcing draws from Indian organic cotton processors, Chinese bamboo viscose manufacturers, and German antimicrobial chemistry specialists. Single-source vulnerability concentrates in GOTS-certified organic cotton supply, where climate yield fluctuations in Turkey and India create input cost unpredictability. Distribution runs through subscription fulfillment centers in the Pacific Northwest and direct-to-consumer platforms in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH Annex XVII restrictions on PFAS chemicals function as a cost-of-compliance moat, elevating capital requirements for barrier chemistry reformulation and eliminating marginal competitors from European market participation. This regulatory barrier-to-entry protects first-mover brands with established silicone-based alternative supply chains.
For Market Incumbents: Anticipate disposable menstrual cup substitution pressure by deepening subscription channel control and accelerating biodegradable TPU barrier adoption ahead of enforcement timelines. Capture GOTS-certified manufacturing capacity in Manchester and Leeds zones to defend against educational procurement consolidation. Prioritize antimicrobial chemistry R&D investment to offset formulation expertise scarcity constraining competitor R&D throughput. For New Entrants and Emerging Players: Begin with postpartum and incontinence application white-space, where NHS procurement frameworks and medical-adjacent reimbursement potential offer penetrable entry points. Target super-absorbent segment gaps in hospital discharge kit supply chains. Launch through direct-to-consumer subscription models with absorbency-tiered bundles to bypass saturated retail shelf competition. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive GOTS-certified manufacturing and established circular logistics infrastructure. Long-term viability hinges on extended producer responsibility framework preparedness across the EU textile waste regulatory horizon. Monitor NHS procurement framework expansion velocity as inflection indicator for super-absorbent segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS-Certified Manufacturing Scale-Up | Captures educational procurement volume concentrated in Germany and United Kingdom wellness programs. |
| Biodegradable TPU Barrier Transition | Positions premium tiers ahead of REACH Annex XVII PFAS enforcement timelines in France and Germany. |
| Subscription Platform Acquisition | Reduces customer acquisition costs relative to transactional online retail in Nordic markets. |
| Circular Logistics Infrastructure Buildout | Prepares compliance with pending EU extended producer responsibility textile waste mandates. |
| Postpartum Application Extension | Accesses NHS procurement frameworks with higher willingness-to-pay and reimbursement potential. |
Study Parameters
Independent corroboration across antimicrobial chemistry specialists, GOTS-certified manufacturing plant managers, and educational procurement officers underwrites the qualitative findings. Primary interviews with subscription platform operators, specialty retail buyers, and REACH compliance consultants combined with secondary validation from customs records, EU textile trade databases, and FDA absorbency claim filings. Bottom-up demand modeling across absorbency tiers and top-down macroeconomic triangulation anchored volume and value outputs.
Comparable-period anchoring to historical certification adoption curves and subscription channel penetration rates structured the projection horizon across the analysis window. Segmentation dimensions modeled include absorbency performance tier, customer life stage, distribution channel economics, and regional regulatory cluster. CAGRs derived from absorption rate differentials between certified and conventional fiber constructions, with inputs from organic cotton yield volatility patterns and educational procurement contract velocity.
Underlying measurement precision varies by segment; subscription channel data carries tighter precision than emerging postpartum application estimates. Forecasts reflect assumptions on REACH enforcement consistency and NHS procurement framework expansion velocity. Material deviation in organic cotton yield stability or extended producer responsibility implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market