
 Recycled Cotton Market | 2026-2036
Recycled Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Cotton Market Analytics
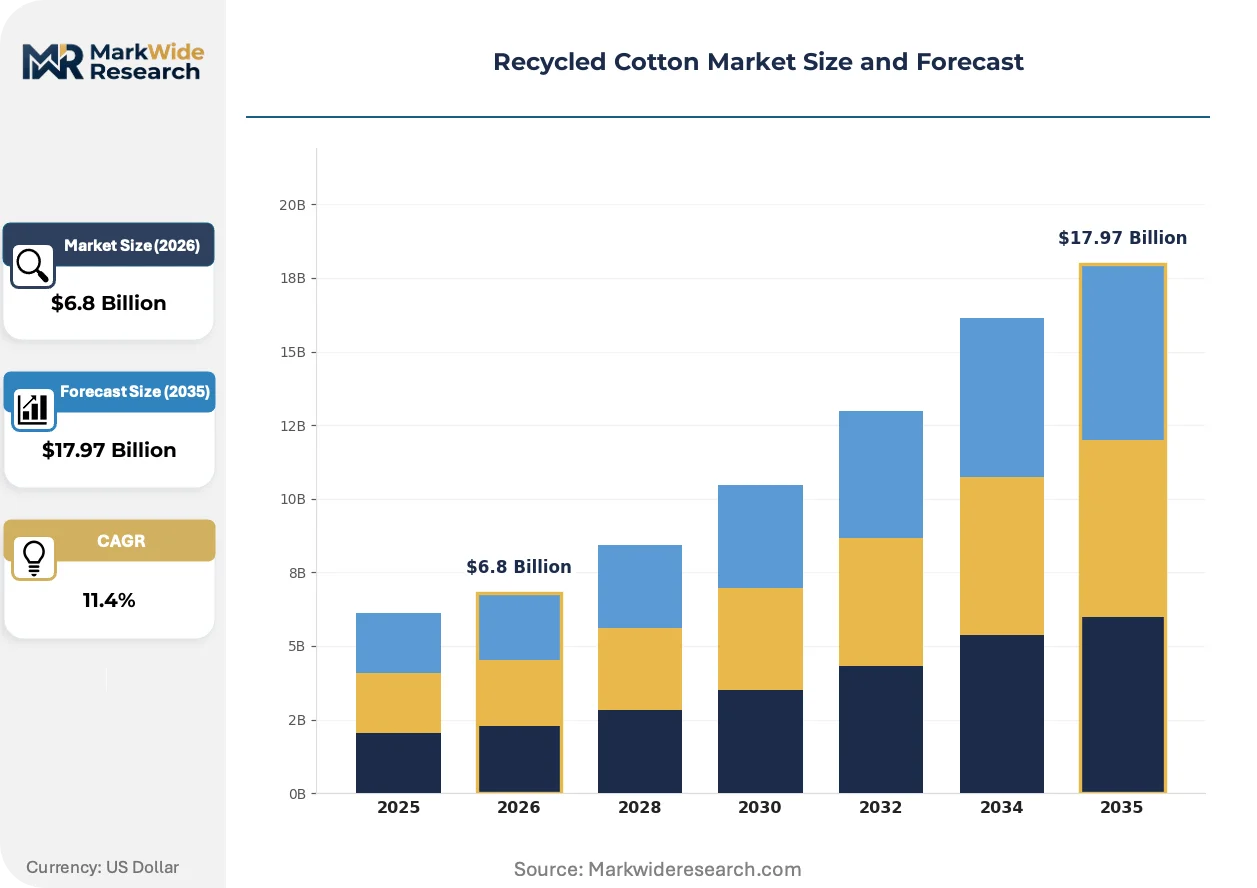
Subscription-based fiber traceability services is shifting how recycled cotton gets sold to brands. Unifi, Inc. leverages its REPREVE platform to anchor premium positioning through verified recycled content claims. Lenzing Group competes by extending wood-based and recycled fiber portfolios into blended yarn segments. Patagonia, Inc. differentiates through closed-loop take-back programs that control garment-to-fiber feedstock quality.
Recycled cotton comprises reclaimed textile fibers processed through mechanical shredding or chemical depolymerization, typically yielding staple lengths between 12 and 38 millimeters depending on source material and processing severity. This recovered cellulose fiber primarily substitutes virgin cotton in spun yarns and woven fabrics to reduce agricultural water consumption and landfill diversion. Yarn and fabric segments dominate current volume, with denim representing the fastest-growing product type as brands pursue lower-impact jeans lines. Premium and organic grades capture disproportionate margin pools because certification complexity limits supplier competition and sustains price premiums over regular recycled grades.
The EU Green Deal and REACH chemical standards shape recycled cotton demand by mandating recycled content thresholds and restricting hazardous substances in textile reprocessing. The EPA in the United States and ECHA in Europe both scrutinize chemical inputs in mechanical recycling, pushing processors toward water-based or enzymatic fiber separation methods. Stakeholders must monitor how evolving extended producer responsibility schemes alter feedstock access economics and whether chemical recycling scale-up reshapes the grade-quality hierarchy that currently favors mechanical routes.
Market Dynamics
Mechanical recycling clusters in Germany and chemical depolymerization pilots in Spain are bifurcating feedstock flows, forcing brands to choose between cost efficiency and fiber quality consistency.
Growth Catalysts
- EU Green Deal Extended Producer Responsibility:Mandatory recycled content thresholds in denim and knitwear lines pull volume through certified supply chains.
- Water-based enzymatic separation:This processing method expands mechanically recycled cotton output while satisfying EPA and ECHA chemical input scrutiny.
- Central European garment manufacturing concentration:Proximity to German mechanical recycling clusters reduces logistics costs for spun yarn producers serving apparel brands.
Market Restraints
- Staple length degradation:Mechanical shredding limits recovered fiber lengths to 12-38 millimeters, constraining high-count yarn applications.
- Virgin cotton price volatility:Agricultural commodity swings compress recycled cotton price premiums during cotton harvest gluts.
- REACH chemical compliance costs:Hazardous substance restrictions in reprocessing raise certification expenses for smaller mechanical recyclers.
Strategic Opportunities
- Chemical recycling scale-up in Spain and Italy:Depolymerization infrastructure investment could restore fiber quality for premium apparel segments.
- Closed-loop take-back program expansion:Direct brand control over post-consumer textile streams secures higher-quality feedstock.
- Subscription-based fiber traceability:Verified recycled content claims through digital platforms command pricing power in sustainability-focused procurement.
Industry Challenges
- Certification timeline compression:Multiple organic and recycled standards create audit backlogs that delay supplier qualification.
- Feedstock sorting automation gaps:Manual separation of cotton-polyester blends limits throughput at preprocessing facilities.
- Blended yarn R&D integration:Combining recycled cotton with wood-based cellulosic fibers requires reconfigured spinning equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Cotton Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yarn, Fabric, Non-woven, Denim End Use: Apparel, Home Textiles, Industrial Products, Automotive Grade: Regular, Premium, Organic, Blended Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Birla Cellulose, Lenzing Group, Unifi, Inc., Anandhi Texstyles Private Limited, Renewcell, Patagonia, Inc., Worn Again Technologies, The Boer Group, Prokotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Cotton Market Evolving Landscape
Digital traceability infrastructure and enzymatic processing advances are restructuring how recycled cotton moves from waste stream to finished garment, with certification complexity becoming a competitive filter.
Enzymatic fiber separation is decentralizing preprocessing capacity away from concentrated mechanical shredding hubs. Mid-sized processors in Portugal and Turkey adopt modular enzymatic units to serve local denim manufacturers. This geographic diffusion reduces feedstock transport distances and enables smaller batch customization for premium lines.
REACH chemical standards revision tightens hazardous substance thresholds in textile reprocessing. European mechanical recyclers face reformulation costs for dye and finish removal chemicals. German processors respond by accelerating water-based separation pilot programs to preempt compliance disruption.
Brand procurement teams now require third-party verified recycled content claims before supplier onboarding. Sustainability-focused buyers in Scandinavia and Benelux reject uncertified mechanical grades. This certification-driven preference shift concentrates volume with traceability-platform-enabled suppliers and marginalizes opaque intermediaries.
Recycled Cotton Market Segmentation
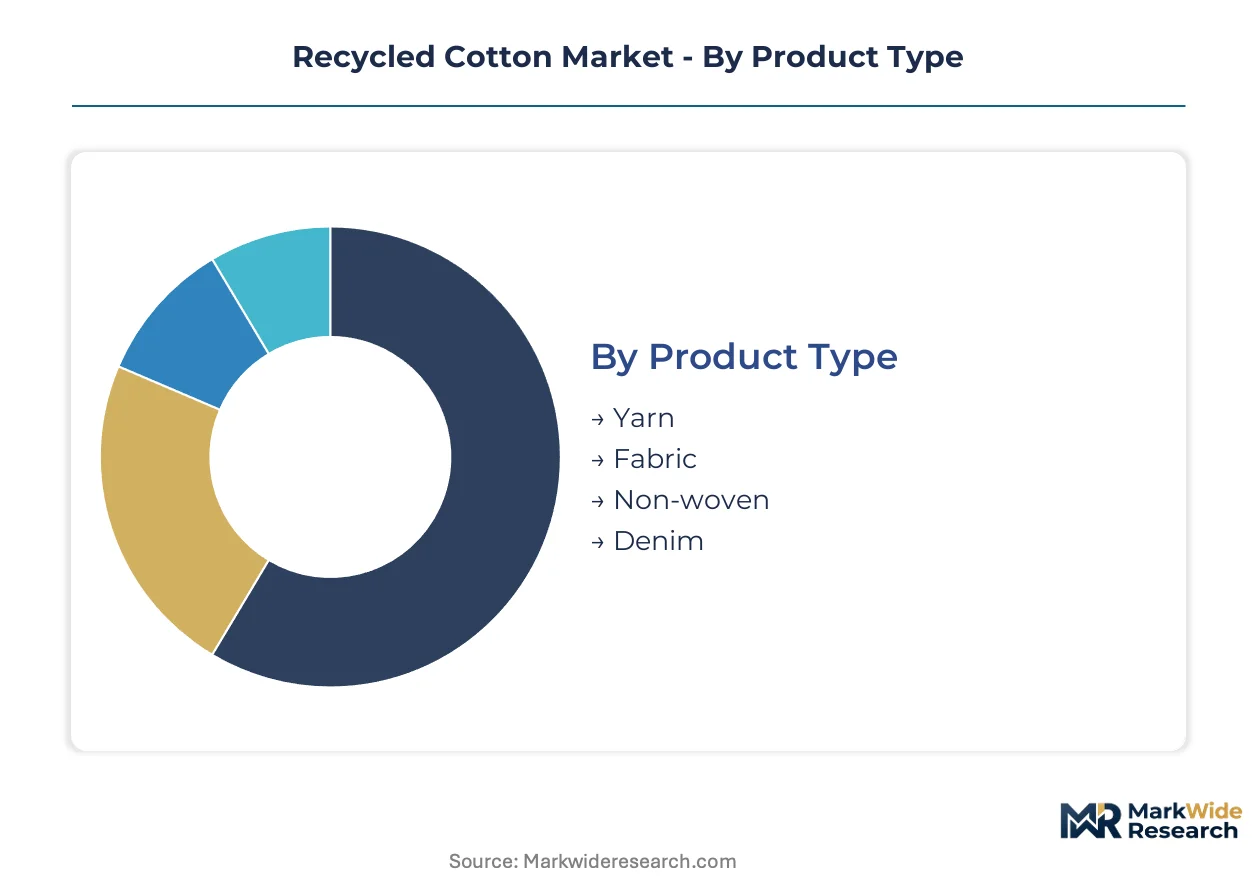
Recycled cotton buyers prioritize fiber length consistency, certification status, and proximity to processing clusters. Segment differentiation determines which suppliers capture premium procurement contracts versus commodity volume plays.
Product Type:
Cost tier separates buyers seeking certified premium outputs from those optimizing per-unit fiber economics.
- Yarn:Spun staple fibers ranging 12-38 millimeters serve knitwear manufacturers in Portugal and Turkey. German mechanical recycling clusters supply Central European garment makers demanding verified recycled content for EU Green Deal compliance.
- Denim:Heavier fabric constructions absorb shorter staple lengths without quality degradation. Brands source denim-grade recycled cotton through direct mill relationships in Spain and Italy where chemical depolymerization pilots restore fiber integrity for premium jeans lines.
- Fabric:Woven constructions from reclaimed fibers substitute virgin cotton in basic apparel applications.
- Non-woven:Compressed fiber mats enter automotive insulation and industrial padding segments.
Volume sits with Yarn; growth tilts toward Denim.
End Use:
Application requirements dictate fiber grade acceptance thresholds and certification stringency.
- Apparel:Garment brands in Scandinavia and Benelux mandate third-party verified recycled content claims before supplier onboarding. Denim and knitwear lines absorb the majority of mechanically processed output.
- Home Textiles:Bedding and towel manufacturers source lower-grade recycled cotton where softness requirements permit shorter staple fibers.
- Industrial Products:Cleaning wipes and technical textiles prioritize cost over fiber length consistency.
- Automotive:Seat upholstery and interior paneling specifications drive demand for blended grades meeting flame-retardant standards.
Apparel commands the largest share; Home Textiles expand most quickly as sustainability claims penetrate consumer bedding purchases.
Grade:
Margin capture concentrates where certification complexity limits supplier competition.
- Premium:Extended fiber length and batch traceability command pricing power. German mechanical recyclers and Spanish chemical depolymerization pilots serve luxury apparel brands requiring documented supply chain transparency.
- Organic:Dual certification as recycled and organic restricts eligible feedstock to pre-consumer textile waste from certified organic cotton garments.
- Regular:Standard mechanically processed grades compete primarily on price against virgin cotton.
- Blended:Wood-based cellulosic fiber combinations require reconfigured spinning equipment.
Premium and Organic grades sustain the widest margins; Regular grade absorbs volume in price-sensitive applications.
Distribution Channel:
Customer type determines whether procurement prioritizes traceability platforms or logistical efficiency.
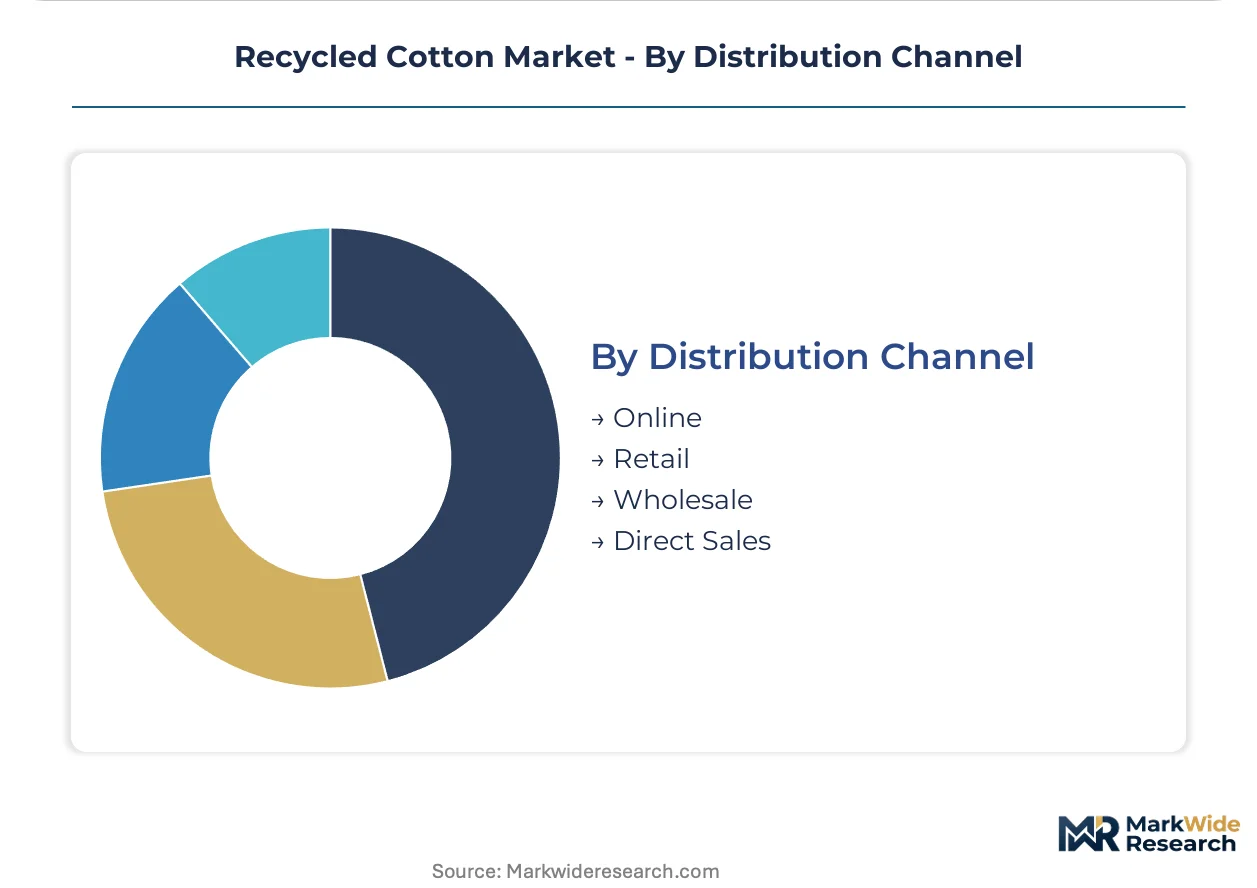
- Direct Sales:Brand procurement teams negotiate long-term supply agreements with German mechanical recycling clusters and emerging Spanish chemical processors. Subscription-based fiber traceability services anchor these relationships through verified content claims.
- Wholesale:Intermediary traders aggregate smaller mechanical recycler output for garment manufacturers lacking direct mill relationships.
- Online:Digital platforms enable mid-sized Portuguese and Turkish processors to reach specialty denim manufacturers.
- Retail:Limited application given bulk fiber and yarn purchasing patterns.
Direct Sales dominate certified premium transactions; Online channels gain traction among mid-tier processors seeking geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordrhein-Westfalen's mechanical recycling corridor anchors European recycled cotton processing, with shredding facilities clustered around Mönchengladbach and Krefeld supplying Central European denim manufacturers.
Germany
Denim brands in Hamburg and Munich drive certified recycled cotton procurement for EU Green Deal compliance. ECHA's tightening REACH chemical standards push processors toward water-based separation methods. Mechanical recycling clusters in Mönchengladbach and Krefeld process post-industrial textile waste for Central European garment makers.
Spain
Chemical depolymerization pilots in Barcelona and Valencia attract premium jeans manufacturers seeking restored fiber integrity. Spain's national waste management framework aligns with extended producer responsibility mandates. Emerging processing infrastructure in Catalonia serves Italian luxury apparel brands demanding documented supply chain transparency.
Italy
Luxury denim houses in Milan and Florence source chemically recycled cotton for high-end jeans lines. Italy's environmental ministry enforces hazardous substance limits in textile reprocessing. Processing partnerships between Lombardy-based mills and Spanish depolymerization facilities reshape premium feedstock flows.
United States
Outdoor apparel brands in California and Colorado mandate verified recycled content for sustainability marketing claims. EPA scrutiny of chemical inputs in mechanical recycling accelerates enzymatic separation adoption. Collection and preprocessing facilities in North Carolina serve East Coast garment manufacturers.
Turkey
Denim manufacturers in Istanbul and Bursa integrate recycled cotton into export-oriented jeans production. Turkey's Ministry of Environment implements textile waste reduction targets for industrial zones. Mid-sized processors in Izmir adopt modular enzymatic units to serve local spinning mills.
Recycled Cotton Market Competitive Landscape
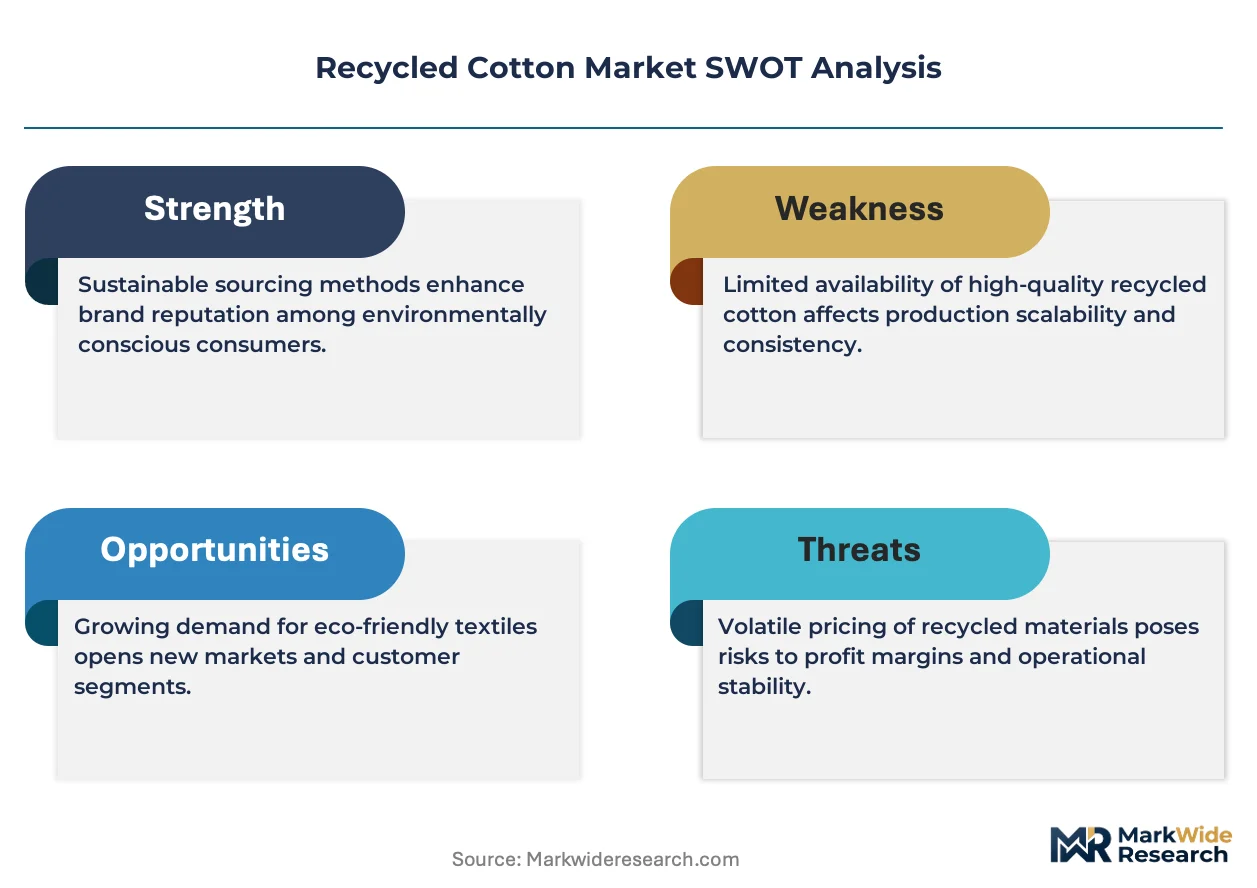
Capital-heavy fiber producers compete with asset-light traceability platform operators across tiered supply positions. The market structure fragments between integrated mechanical recyclers, chemical technology licensors, and brand-controlled closed-loop operators. Three archetypes dominate: certification-anchored premium suppliers, scale-driven mechanical processors, and vertically integrated apparel brands. Competitive moves concentrate on strategic partnerships for feedstock security and geographic expansion of preprocessing capacity.
Among fiber technology specialists, Lenzing Group and Birla Cellulose occupy positions blending wood-based and recycled fiber portfolios. Unifi, Inc. anchors the traceability-platform archetype through subscription-based verified content services. Patagonia, Inc. exemplifies brand-controlled closed-loop positioning, securing garment-to-fiber feedstock quality through direct take-back program ownership.
| Leading Market Players |
|---|
| Birla Cellulose |
| Lenzing Group |
| Unifi, Inc. |
| Anandhi Texstyles Private Limited |
| Renewcell |
| Patagonia, Inc. |
| Worn Again Technologies |
| The Boer Group |
| Prokotex |
| Others |
Value Network & Pricing Analysis
Virgin cotton futures volatility at the Intercontinental Exchange cascades through recycled cotton supply chains, compressing price premiums when agricultural harvests surge and amplifying margin capture for certified grades when commodity markets tighten. Mechanical recyclers in Germany and chemical depolymerization operators in Spain respond with divergent pricing strategies that reflect feedstock security and certification investment levels.
Pricing Analysis
Margin tightening in regular-grade recycled cotton reflects virgin cotton price collapses during bumper harvest cycles in India and the United States. Three-tier pricing structure across premium, standard, and economy levels separates certified organic grades commanding traceability premiums from uncertified mechanical outputs competing on fiber cost alone. Pricing pressure intensifies in standard grades as Turkish and Portuguese mid-tier processors absorb enzymatic separation equipment costs. Apparel brands in Scandinavia and Benelux exhibit lowest price sensitivity, prioritizing verified content claims over per-kilogram economics.
Supply Chain Analysis
Post-consumer textile feedstock rests on collection infrastructure concentration in Germany, Spain, and Turkey, with garment-to-fiber flows controlled by brand take-back programs or municipal waste contracts. Cotton-polyester blend separation, dye removal chemicals, and enzymatic processing reagents constitute critical input dependencies. Single-source vulnerability pervades premium-grade supply where Spanish chemical depolymerization pilots serve Italian luxury denim houses exclusively. Distribution runs through direct mill relationships for certified grades and wholesale trader networks for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recycled cotton supply chains consolidate around certification-capable processors as EU Green Deal compliance costs eliminate smaller mechanical recyclers lacking audit infrastructure. REACH chemical standard revisions and extended producer responsibility mandates accelerate this filtering mechanism.
For Market Incumbents: Extend traceability platform subscriptions to lock in brand procurement relationships before chemical recycling scale-up disrupts mechanical grade hierarchies. Secure backward integration into post-consumer textile collection through municipal waste partnerships in Germany and Spain. Defensive positioning requires pre-emptive enzymatic separation pilot investments to satisfy ECHA's tightening hazardous substance thresholds. For New Entrants and Emerging Players: Modular enzymatic preprocessing technology offers white-space entry points in Portugal and Turkey where centralized mechanical shredding capacity remains undersized relative to local denim manufacturer demand. Chemical depolymerization licensing agreements with Spanish pilot operators provide the most penetrable wedge into premium-grade supply gaps. Direct digital platform sales to mid-tier apparel brands circumvent entrenched wholesale trader relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor certification-anchored mechanical recyclers in Germany's Nordrhein-Westfalen corridor where compliance cost burdens strain undercapitalized competitors. Long-term viability hinges on feedstock contract duration and brand direct relationship depth. Watch chemical depolymerization yield consistency rates as the inflection signal determining whether premium-grade supply expands or concentrates further.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Separation Scale-Up | Portuguese processors deploying modular units capture local denim manufacturer volume from German cluster competitors. |
| Closed-Loop Take-Back Expansion | Brand-controlled garment collection secures higher-quality feedstock for premium-grade mechanical recycling output. |
| Chemical Depolymerization Licensing | Spanish pilot technology transfer enables Italian and Turkish entrants to restore fiber integrity for luxury apparel segments. |
| Subscription Traceability Platform | Digital verified content claims concentrate procurement volume with platform-enabled suppliers across Scandinavian markets. |
| Feedstock Sorting Automation | Cotton-polyester blend separation technology unlocks throughput expansion at preprocessing facilities serving Central Europe. |
Research Methodology
Independent corroboration across mechanical recycler operations data, brand procurement disclosure filings, and ECHA regulatory submissions underwrites the qualitative findings. Primary interviews with German plant managers, Italian luxury denim procurement leads, Spanish chemical technology directors, and Turkish spinning mill operators combined with secondary validation from EU textile waste statistics, REACH compliance databases, and customs trade flows. Bottom-up fiber volume estimates and top-down apparel brand recycled content commitments were triangulated for consistency.
Rate-of-change decomposition across the analysis window isolates volume drivers by product type, grade tier, end-use application, and geographic processing cluster. CAGRs were derived from segment-level growth factor modeling incorporating EU Green Deal threshold implementation timelines, enzymatic processing adoption curves, and chemical depolymerization pilot expansion schedules. Fiber length distribution constraints and certification audit backlog durations served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential REACH chemical standard revisions beyond current draft thresholds, trade policy disruptions affecting Turkish-EU textile flows, and breakthrough chemical recycling yield improvements that could regrade fiber quality hierarchies. Forecasts reflect assumptions about extended producer responsibility scheme implementation pacing and brand procurement team sustainability mandate durability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Europe Textile Recycling Market