
 PET Microfiber Fleece Garment Recycling Streams in Europe Market | 2026-2036
PET Microfiber Fleece Garment Recycling Streams in Europe Market Size, Share, and Industry Trends Forecast 2026-2036
PET Microfiber Fleece Garment Recycling Streams in Europe Market Insights
Mechanical sorting and enzymatic depolymerization is narrowing the cost gap between virgin and recycled PET microfiber output. SOEX leverages its continental collection infrastructure to secure post-consumer fleece volumes across multiple European markets. CARBIOS differentiates through enzymatic recycling technology that processes colored and blended polyester textiles without heat degradation. Nouvelles Fibres Textiles anchors French circular textile manufacturing with integrated mechanical shredding and fiber respinning operations.
PET microfiber fleece garment recycling streams comprise post-consumer and post-industrial polyester textile waste collected, sorted, and processed into reusable fiber or polymer feedstock, with fleece garments typically containing 100-300 denier polyethylene terephthalate filaments knitted into brushed pile structures for thermal insulation. Chemical recycling of blended and dyed fleece waste is expanding fastest as mechanical methods struggle with elastane contamination and color variability. Fiber for textiles dominates end product value capture, while insulation material for building applications offers emerging margin pools as construction sector sustainability procurement standards tighten.
EU Ecodesign for Sustainable Products Regulation and REACH chemical compliance frameworks mandate recycled content minimums and restrict hazardous substance residues in regenerated fibers. The European Commission's textile strategy and extended producer responsibility schemes in France, Netherlands, and Sweden shape collection infrastructure investment and sorting technology deployment priorities. Stakeholders must monitor enzymatic recycling yield improvements and chemical recycler offtake agreements to assess feedstock competition between textile-to-textile and bottle-to-fleece recycling pathways.
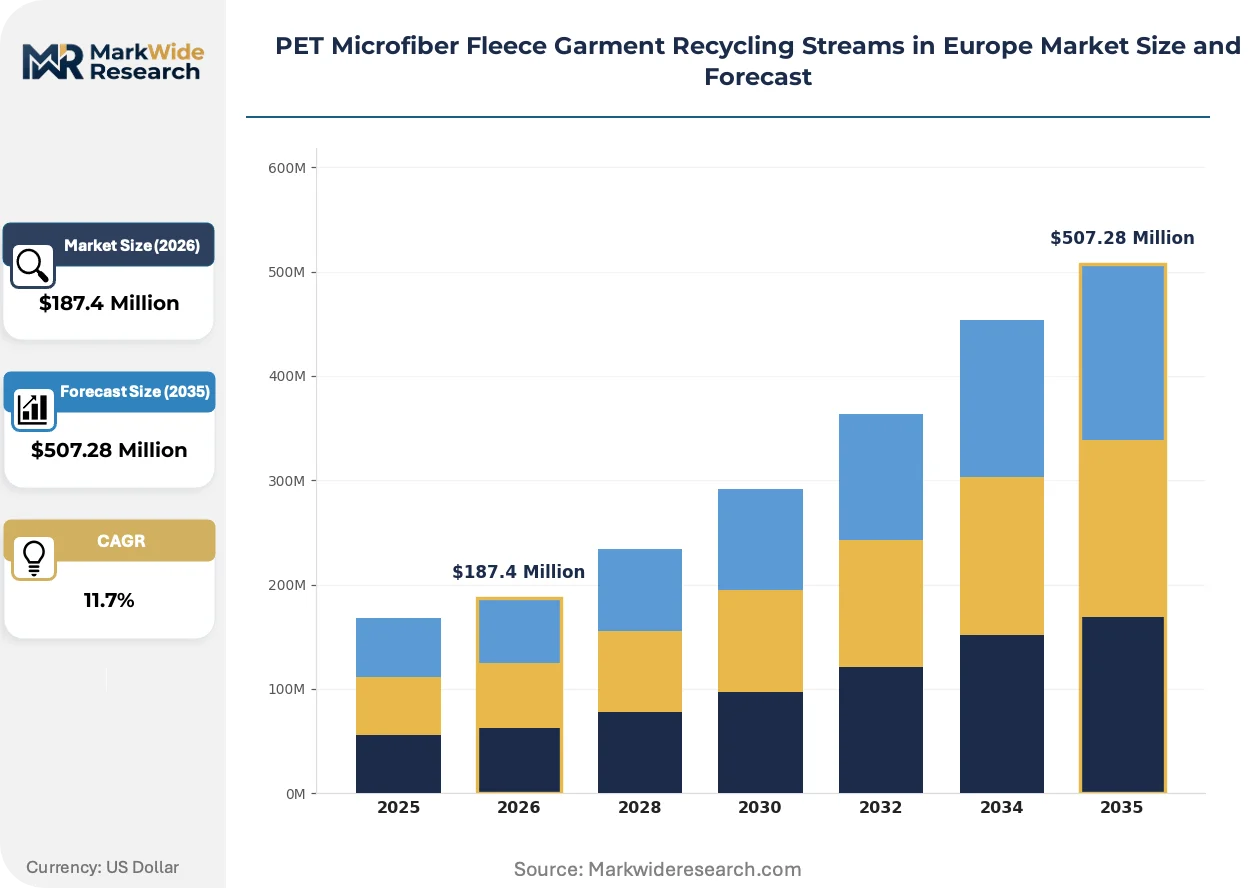
Market Dynamics
Chemical recycling capacity buildout across Germany and France is compressing mechanical recycling margins while enzymatic depolymerization advances promise to unlock previously uneconomic blended fleece feedstock streams.
Growth Catalysts
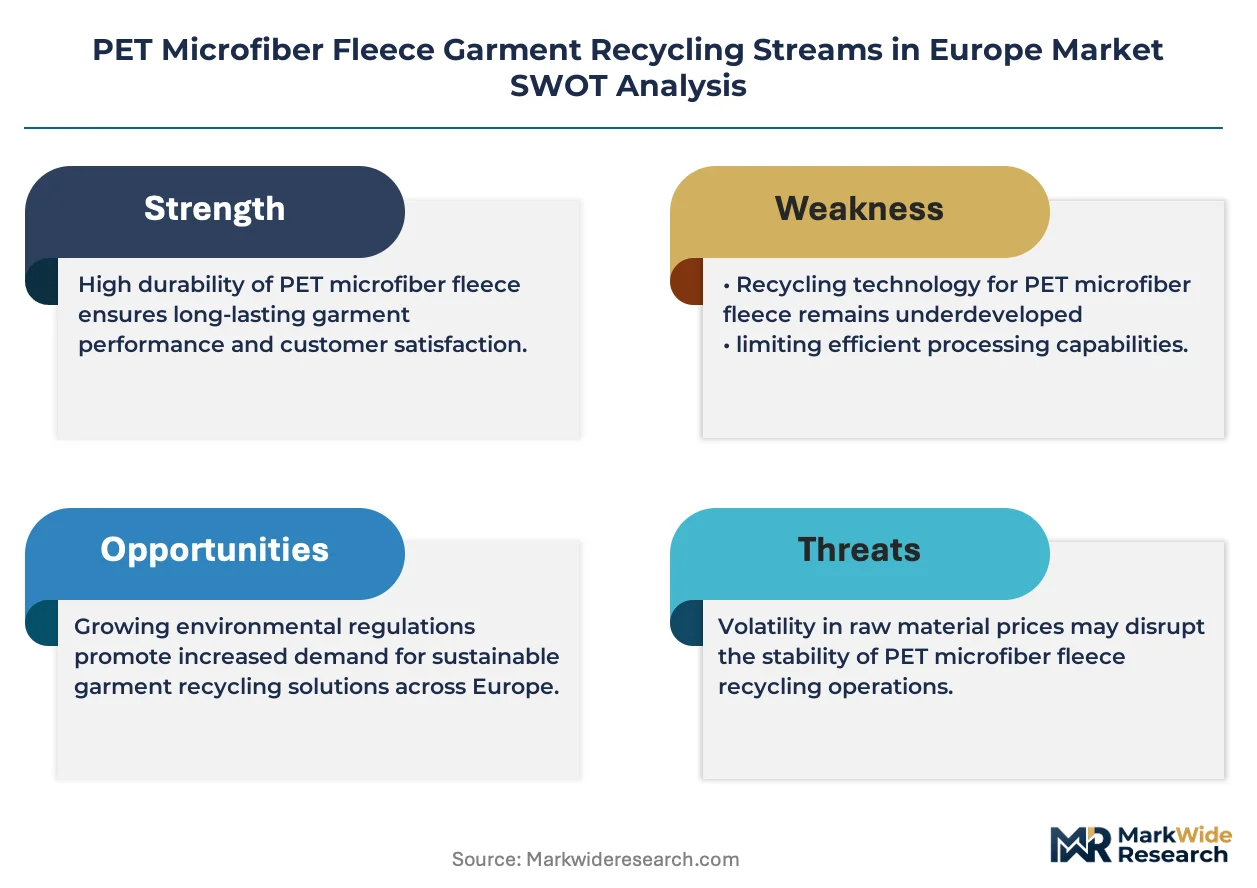
- Ecodesign for Sustainable Products Regulation:Mandatory recycled content minimums for textiles sold in the European Union are forcing outdoor apparel brands to secure certified post-consumer fleece supply chains ahead of compliance deadlines.
- Extended producer responsibility schemes:France, Netherlands, and Sweden now require fashion brands to finance collection infrastructure, directly expanding sorted post-consumer microfiber volumes available to recyclers.
- Enzymatic recycling yield improvements:Biological depolymerization processes that operate at low temperatures without heat degradation are opening colored and elastane-contaminated fleece waste streams that mechanical methods cannot process.
Market Restraints
- Feedstock supply concentration:Post-consumer fleece collection concentrates in Germany, France, and Benelux, leaving southern and eastern European recyclers dependent on costly cross-border transport or lower-quality industrial scrap.
- Sorting technology capex barriers:Near-infrared and robotic sorting systems required to separate PET microfiber from cotton, wool, and elastane blends demand capital commitments that smaller mechanical recyclers cannot finance.
- REACH chemical compliance friction:Hazardous substance residue testing for regenerated fibers adds certification timelines and laboratory costs that virgin PET filament producers do not face.
Strategic Opportunities
- Building insulation applications:Construction sector sustainability procurement standards in Germany and France are creating margin pools for recycled PET microfiber as thermal insulation material competing with mineral wool and fiberglass.
- Spain and Italy collection infrastructure:Underdeveloped post-consumer textile sorting capacity in southern Europe offers first-mover advantages for integrated collectors able to secure municipal collection contracts.
- Chemical-mechanical hybrid processing:Converging enzymatic purification with mechanical fiber respinning promises to produce textile-grade recycled microfiber at costs approaching virgin polymer routes.
Industry Challenges
- Polymer chemist and enzymology talent scarcity:Scaling enzymatic recycling requires specialized biochemical process engineers and polymer scientists that European technical universities are not producing at sufficient rates.
- Multi-stakeholder certification coordination:Aligning Global Recycled Standard, OEKO-TEX, and EU Ecolabel requirements demands dedicated compliance staff and extended audit timelines that fragment management attention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Microfiber Fleece Garment Recycling Streams in Europe Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Recycling Method: Mechanical Recycling, Chemical Recycling, Thermal Depolymerization, Enzymatic Recycling End Product Type: Fiber for Textiles, Insulation Material, Filling for Bedding, Composite Reinforcements Collection Channel: Retail Take-Back, Municipal Waste Collection, Textile Banks, Industrial Waste Streams, Donation Centers Consumer Segment: Outdoor Apparel Users, Sportswear Enthusiasts, Casual Wear Consumers, Corporate Uniform Providers |
| Companies Covered | SOEX, TOMRA Textiles, Nouvelles Fibres Textiles, CARBIOS, Reju, Circ, Eastman, PETCORE EUROPE, Syre, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Microfiber Fleece Garment Recycling Streams in Europe Market Trends and Innovations
Technology convergence between biological and mechanical processing routes is collapsing traditional boundaries between chemical and textile recycling, while regulatory pressure accelerates investment in feedstock preparation and purification capabilities.
Enzymatic depolymerization platforms that selectively break PET ester bonds at ambient temperatures are rendering obsolete energy-intensive glycolysis and methanolysis processes that require high-pressure reactors and extensive purification steps. Outdoor apparel brands with science-based targets for recycled content are piloting offtake agreements with enzymatic recyclers in France, accepting longer lead times for fiber that meets color consistency specifications without virgin blending.
REACH restrictions on microplastic shedding from synthetic textiles are tightening testing protocols for regenerated fibers sold into EU markets. The European Chemicals Agency is expanding registration requirements for polymer additives used in recycled feedstock, forcing recyclers to document supply chain provenance and chemical composition with granularity previously reserved for virgin polymer producers. German and French textile-to-textile recyclers are investing in spectroscopic fingerprinting to demonstrate compliance ahead of enforcement phases.
Brand procurement teams are consolidating supplier relationships around integrated recyclers that control collection, sorting, and fiber production rather than fragmented toll-processing arrangements. Outdoor apparel manufacturers in Scandinavia and the Alpine region are signing multi-year supply agreements directly with chemical recycling ventures, bypassing traditional fiber traders and merchant suppliers. This concentration is most visible in Germany, where direct contracting now accounts for the majority of certified recycled microfiber volume.
PET Microfiber Fleece Garment Recycling Streams in Europe Market Segmentation
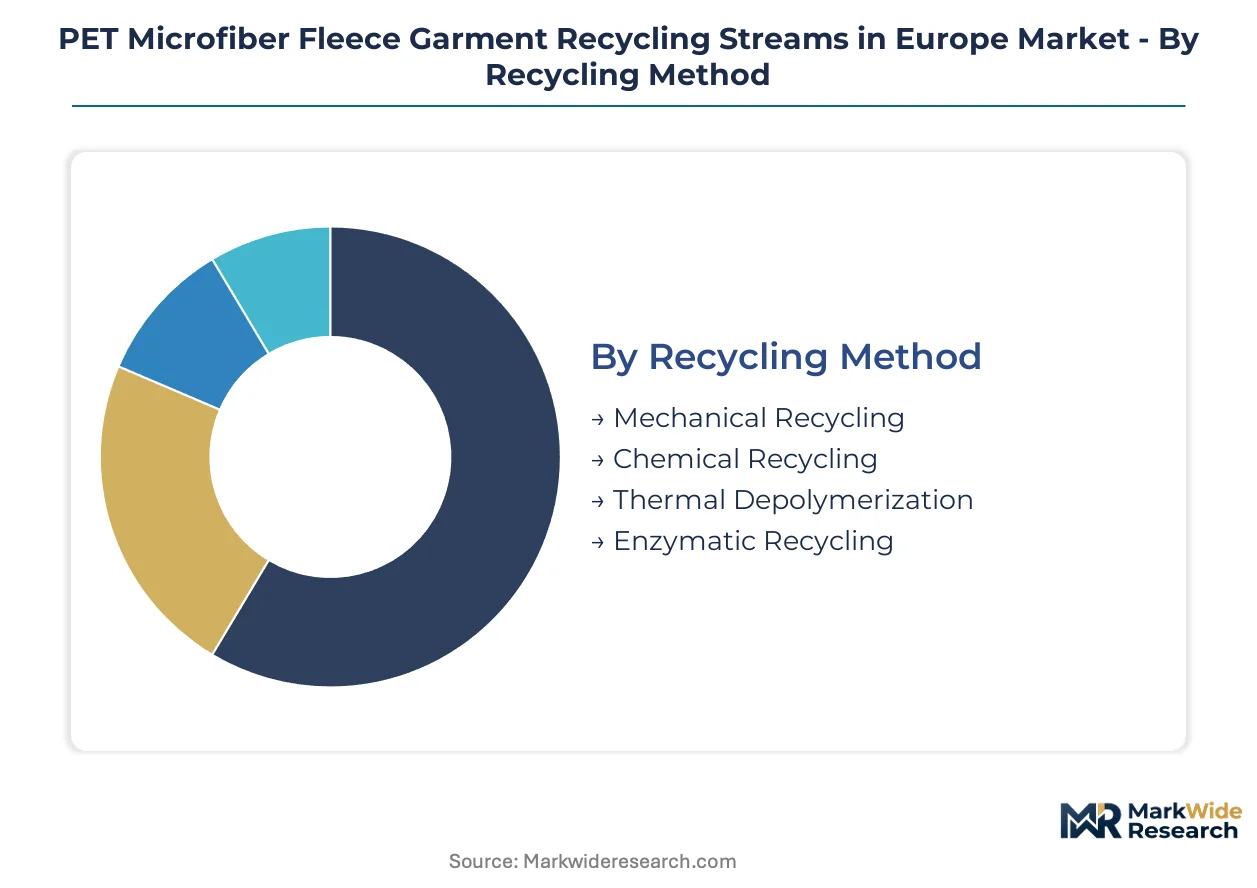
Segmentation in European PET microfiber fleece recycling reveals how feedstock quality, processing technology, and end-market specifications intersect to determine value capture. Each dimension shapes capital deployment priorities and operational complexity for recyclers navigating Ecodesign compliance deadlines.
Recycling Method:
Cycle times vary dramatically across these technologies, with mechanical routes turning inventory in hours while enzymatic batches require days for biological depolymerization to complete.
- Mechanical Recycling:Shredding and fiber respinning of sorted PET fleece operates at ambient temperatures without chemical transformation. German and French mechanical recyclers face margin compression as chemical capacity expands, though their speed advantages preserve share in color-consistent textile applications.
- Chemical Recycling:Glycolysis and methanolysis break polyester chains into purified monomers for repolymerization. Capacity buildout across Germany and France is concentrating investment as outdoor apparel brands seek certified post-consumer content for Ecodesign compliance.
- Thermal Depolymerization:High-temperature pyrolysis routes process contaminated feedstock streams that mechanical methods reject. Energy intensity limits deployment to facilities with waste heat integration.
- Enzymatic Recycling:Biological depolymerization at low temperatures handles elastane-contaminated and deeply colored fleece without heat degradation. French pilot facilities are scaling yields to commercial viability.
Mechanical Recycling anchors the volume base while Enzymatic Recycling gains share at the steepest rate.
End Product Type:
Margin structures diverge sharply between premium textile-grade fiber and commodity insulation applications, with certification requirements driving cost-to-serve differentiation.
- Fiber for Textiles:Respun PET microfiber meeting Global Recycled Standard and OEKO-TEX specifications commands premium positioning in outdoor apparel supply chains. Scandinavian and Alpine region brands are consolidating procurement around integrated recyclers controlling full chain of custody.
- Insulation Material:Lower-specification recycled fiber for building thermal insulation competes with mineral wool and fiberglass. German and French construction sustainability procurement standards are opening margin pools previously inaccessible to textile recyclers.
- Filling for Bedding:Recycled polyester staple for pillows and duvets requires less stringent color consistency than apparel fiber. Dutch and Swedish extended producer responsibility schemes are expanding sorted feedstock availability for this mid-tier application.
- Composite Reinforcements:Chopped fiber for automotive and construction composites represents emerging offtake as polymer compounders seek recycled content for sustainability reporting.
Fiber for Textiles dominates value capture while Insulation Material expands most quickly as building codes tighten across northern Europe.
Collection Channel:
Geographic coverage and feedstock quality vary systematically by channel type, with municipal contracts concentrating volume in Germany, France, and Benelux while southern Europe remains underdeveloped.
- Retail Take-Back:Brand-operated collection at point of sale yields high-quality sorted fleece with documented provenance. French and Dutch regulatory mandates are accelerating deployment of in-store collection infrastructure.
- Municipal Waste Collection:Curbside textile collection programs generate volume but require capital-intensive sorting to separate PET microfiber from cotton, wool, and contaminants. German municipalities lead investment in near-infrared and robotic separation systems.
- Textile Banks:Container-based donation networks concentrate volume in urban centers with established consumer habits. Benelux operators leverage dense population geography to minimize collection logistics costs.
- Industrial Waste Streams:Post-industrial fleece scrap from garment manufacturing offers consistent quality without consumer contamination. Portugal and Spain retain significant uncaptured volumes from coastal apparel production clusters.
- Donation Centers:Charitable collection channels divert wearable garments while routing damaged fleece to recyclers. Sorting labor intensity limits integration with automated processing lines.
Municipal Waste Collection anchors the volume base while Retail Take-Back climbs the fastest as Ecodesign compliance tightens brand accountability.
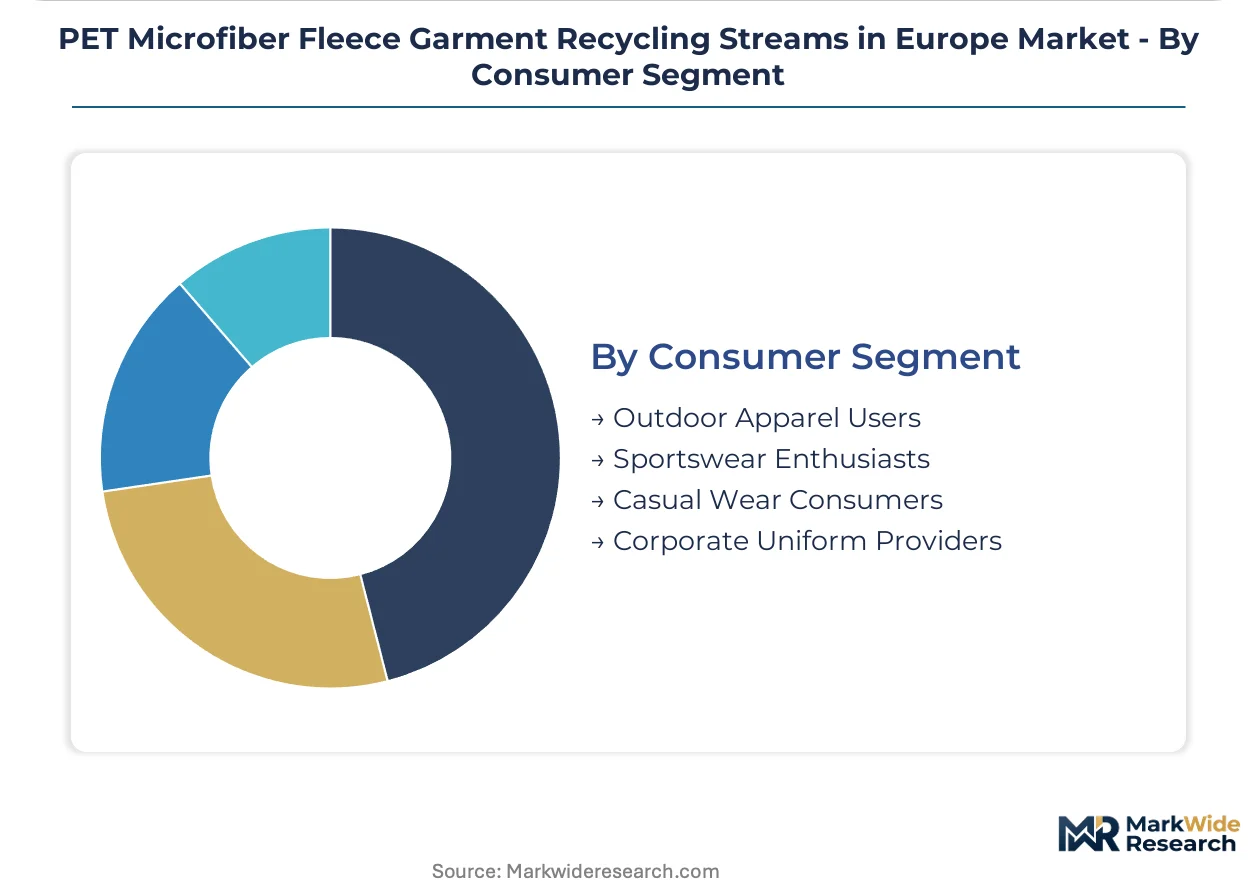
Consumer Segment:
End-user durability requirements and brand sustainability positioning determine specification stringency and price tolerance across consumer categories.
- Outdoor Apparel Users:Technical fleece garments for hiking, skiing, and mountaineering demand high-tenacity recycled fiber with verified performance in abrasion and moisture management. Scandinavian brands are signing multi-year offtake agreements directly with chemical recyclers.
- Sportswear Enthusiasts:Athletic fleece applications prioritize moisture wicking and lightweight thermal properties over extreme durability. Italian and Spanish sportswear manufacturers are piloting enzymatic fiber for color consistency without virgin blending.
- Casual Wear Consumers:Mass-market fleece jackets and loungewear accept broader quality tolerances and higher virgin blend ratios. Price sensitivity constrains recycled content penetration in discount retail channels.
- Corporate Uniform Providers:Institutional procurement specifications increasingly mandate recycled content minimums for sustainability reporting. German and French public sector tenders are driving standardization of recycled fiber certification requirements.
Outdoor Apparel Users anchors the volume base while Corporate Uniform Providers gains share at the steepest rate as institutional procurement standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports mechanically recycled PET microfiber to outdoor apparel manufacturers across Scandinavia, while France ships enzymatically depolymerized polymer to Italian textile mills seeking color-consistent feedstock without virgin blending.
Germany
Extended producer responsibility mandates under the Kreislaufwirtschaftsgesetz drive municipal collection infrastructure investment across North Rhine-Westphalia and Bavaria. The Federal Environment Agency enforces strict sorting technology standards for post-consumer textile separation. Berlin-Brandenburg hosts dense networks of mechanical recyclers competing for certified feedstock volumes.
France
Agence de la transition écologique administers textile EPR schemes that finance collection point expansion in Île-de-France and Auvergne-Rhône-Alpes. The country's national chemical regulator evaluates enzymatic recycling processes for REACH compliance ahead of commercial scale-up. Clermont-Ferrand anchors pilot facilities demonstrating biological depolymerization at ambient temperatures.
Netherlands
Amsterdam-based sorting technology vendors supply near-infrared separation systems to Benelux collectors handling dense urban textile volumes. The Human Environment and Transport Inspectorate monitors hazardous substance residues in regenerated fibers destined for EU markets. Rotterdam's port infrastructure enables cost-efficient cross-border feedstock distribution to German chemical recyclers.
Sweden
Swedish Environmental Protection Agency rules mandate recycled content reporting for public sector uniform procurement. Stockholm's municipal waste authority operates automated textile banks that yield high-purity PET fleece streams. Gothenburg's industrial cluster concentrates mechanical fiber respinning capacity serving Nordic outdoor apparel brands.
Spain
Underdeveloped post-consumer sorting capacity in Catalonia and Madrid leaves coastal apparel production clusters dependent on imported feedstock. Spain's national consumer affairs authority is drafting EPR implementation timelines aligned with EU Ecodesign deadlines. Valencia's emerging collection infrastructure offers first-mover positioning for integrated operators securing municipal contracts.
PET Microfiber Fleece Garment Recycling Streams in Europe Market Competitive Landscape
On the supply side, the industry is bifurcating between capital-intensive chemical recyclers and speed-focused mechanical operators. Tier-one players control integrated collection-sorting-processing chains while mid-scale specialists toll-process feedstock for brand-certified output. Two strategic archetypes dominate: enzymatic technology licensors and continental collection infrastructure owners. Capacity expansion and direct offtake contracting with outdoor apparel brands represent the primary competitive vectors.
Within the enzymatic technology tier, CARBIOS exemplifies biological depolymerization specialists targeting colored and elastane-contaminated waste streams that mechanical methods reject. SOEX occupies a position as a continental collection infrastructure anchor leveraging cross-border logistics networks across multiple European markets. Nouvelles Fibres Textiles represents integrated French circular manufacturing, combining mechanical shredding with fiber respinning under unified ownership. These three entities illustrate how technology differentiation and geographic coverage interact to secure Ecodesign-compliant supply chain positioning.
| Leading Market Players |
|---|
| SOEX |
| TOMRA Textiles |
| Nouvelles Fibres Textiles |
| CARBIOS |
| Reju |
| Circ |
| Eastman |
| PETCORE EUROPE |
| Syre |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and French chemical recycling capacity determines both pricing tier spreads and supply chain shape across the European PET microfiber fleece garment recycling market. REACH compliance testing requirements and Ecodesign for Sustainable Products Regulation certification timelines fragment procurement costs across mechanical, chemical, and enzymatic processing routes.
Pricing Analysis
The technology-generation pricing gap between mechanical shredding, glycolysis-based chemical recycling, and enzymatic depolymerization stratifies cost structures across feedstock quality tiers. Contract-based long-term offtake agreements dominate as outdoor apparel brands secure certified post-consumer supply chains ahead of compliance deadlines, with price differentiation driven by Global Recycled Standard certification level and volume scale. Cost compression in mechanical recycling is intensifying because chemical capacity expansion in Germany and France absorbs premium feedstock volumes. Corporate uniform providers demonstrate highest price sensitivity due to institutional procurement constraints, while Scandinavian outdoor apparel brands exhibit lowest sensitivity given science-based recycled content targets.
Supply Chain Analysis
Export-control regime restrictions on enzymatic recycling technology licensing limit technology transfer from French pilot facilities to southern European markets, constraining capacity buildout beyond the Rhine-Alpine corridor. Geographic supply concentration centers on Germany, France, and the Netherlands, with raw material dependencies on post-consumer fleece collection infrastructure, near-infrared sorting systems, and biological depolymerization enzymes. Single-source vulnerability characterizes enzymatic enzyme supply, which hinges on specialized biochemical process engineering talent concentrated in Clermont-Ferrand and Paris-Saclay research clusters. Distribution runs through integrated collectors controlling municipal waste contracts rather than fragmented toll-processing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU member states creates white-space opportunities as Ecodesign compliance deadlines stagger between 2026 and 2030, enabling specialized players to capture niche certification tiers before market consolidation.
For Market Incumbents: Build certification moats around integrated chain-of-custody documentation from collection through fiber respinning. Secure exclusive municipal collection contracts in underdeveloped Spanish and Italian markets before EPR implementation tightens feedstock access. Expand enzymatic recycling capacity in France to defend against mechanical recyclers adopting hybrid chemical-mechanical processing routes. Anchor procurement relationships with Scandinavian outdoor apparel brands through multi-year offtake agreements specifying color consistency without virgin blending. For New Entrants and Emerging Players: Southern European municipal collection infrastructure in Valencia and Catalonia represents the most penetrable entry point for integrated operators able to finance near-infrared sorting capex ahead of national EPR rollout. Building insulation applications in German and French construction procurement offer margin pools with lower certification barriers than textile-grade fiber. Partner with Dutch extended producer responsibility scheme administrators to secure guaranteed feedstock volumes through retail take-back channel development. For Investors and Strategic Acquirers: Ecodesign for Sustainable Products Regulation implementation reshapes the acquisition landscape toward integrated recyclers controlling collection-sorting-processing capabilities rather than fragmented toll processors. The five-to-ten-year viability window favors targets with enzymatic technology licensing agreements or exclusive municipal waste contracts in Benelux and German markets. Monitor enzymatic recycling yield improvements at commercial scale as the primary inflection signal for feedstock competition between textile-to-textile and bottle-to-fleece recycling pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | SOEX leverages continental logistics networks to secure post-consumer fleece volumes across multiple European markets. |
| Enzymatic Technology Licensing | CARBIOS differentiates through biological depolymerization processing colored and elastane-contaminated waste streams. |
| Long-term Supply Agreement | Scandinavian outdoor apparel brands consolidate procurement around integrated recyclers with verified chain-of-custody documentation. |
| Capacity Expansion in Chemical Recycling | Nouvelles Fibres Textiles anchors French circular manufacturing with integrated mechanical shredding and fiber respinning operations. |
| Sustainability Repositioning | Construction sector procurement standards in Germany and France create margin pools for recycled PET microfiber insulation material. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with textile collection infrastructure managers, enzymatic recycling process engineers, outdoor apparel brand sustainability officers, and EPR scheme administrators. Secondary validation drew from EU Ecodesign regulatory filings, Agence de la transition écologique collection volume reports, German Federal Environment Agency sorting technology standards, and Benelux customs trade data. Bottom-up feedstock flow modeling and top-down market sizing triangulated volume estimates across mechanical, chemical, and enzymatic processing routes.
Calibration against historical capacity buildout patterns and regulatory compliance timeline shifts anchored projections across the analysis window. Segmentation dimensions modeled include recycling method technology tier, end product specification grade, collection channel type, and consumer segment durability requirements. CAGRs were derived from technology adoption curves and Ecodesign mandate enforcement phasing. Industry-specific inputs incorporated enzymatic recycling yield improvement trajectories and extended producer responsibility scheme financing mechanisms.
Practitioners should monitor enzymatic depolymerization commercial scale-up delays and REACH chemical compliance testing backlogs for early signals of feedstock competition intensity. Forecasts reflect assumptions regarding Ecodesign enforcement consistency across EU member states and chemical recycling capacity commissioning schedules. Material shifts in enzymatic technology licensing availability or EPR scheme implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Recycled Cotton Market