
 EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market | 2026-2036
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market Insights
Modular take-back bundling is expanding as brands pair return logistics with resale credits and repair subscriptions. SOEX Group leverages its European collection infrastructure to anchor reverse supply chains for sportswear retailers. Recover differentiates through proprietary fiber regeneration technology that sustains output quality across batch-variable inputs. Decathlon competes on volume by integrating in-house refurbishment with its secondhand marketplace platform.
EU outdoor and sportswear textile returns refurbishment and recycling encompasses the collection, sorting, mechanical or chemical reprocessing, and resale of post-consumer functional garments containing blended synthetic and natural fibers with moisture-wicking, thermal, or stretch properties. The field exists to recover value from durable technical textiles that resist biodegradation while reducing virgin resource extraction for replacement production. Mechanical recycling of polyester and cotton blends currently occupies the largest volume share due to lower capital requirements and established fiber shortening protocols. Chemical recycling of nylon and elastane represents the fastest-expanding processing method as depolymerization yields virgin-equivalent polymers suitable for high-performance re-spinning. Hiking equipment and performance gear end-use applications concentrate margin pools because technical specifications command premium pricing for refurbished or recycled outputs.
The EU Green Deal, ECHA REACH chemical safety frameworks, and national extended producer responsibility transpositions under the EU Textile Strategy shape collection mandates, restricted substance thresholds, and recycling content claims. Ecodesign requirements emerging under the EU Sustainable Products Regulation will force disclosure of fiber composition and recyclability grades at point of sale. Stakeholders must monitor how chemical recycling scale-up interacts with REACH authorization processes for novel depolymerization catalysts and solvents.
Market Dynamics
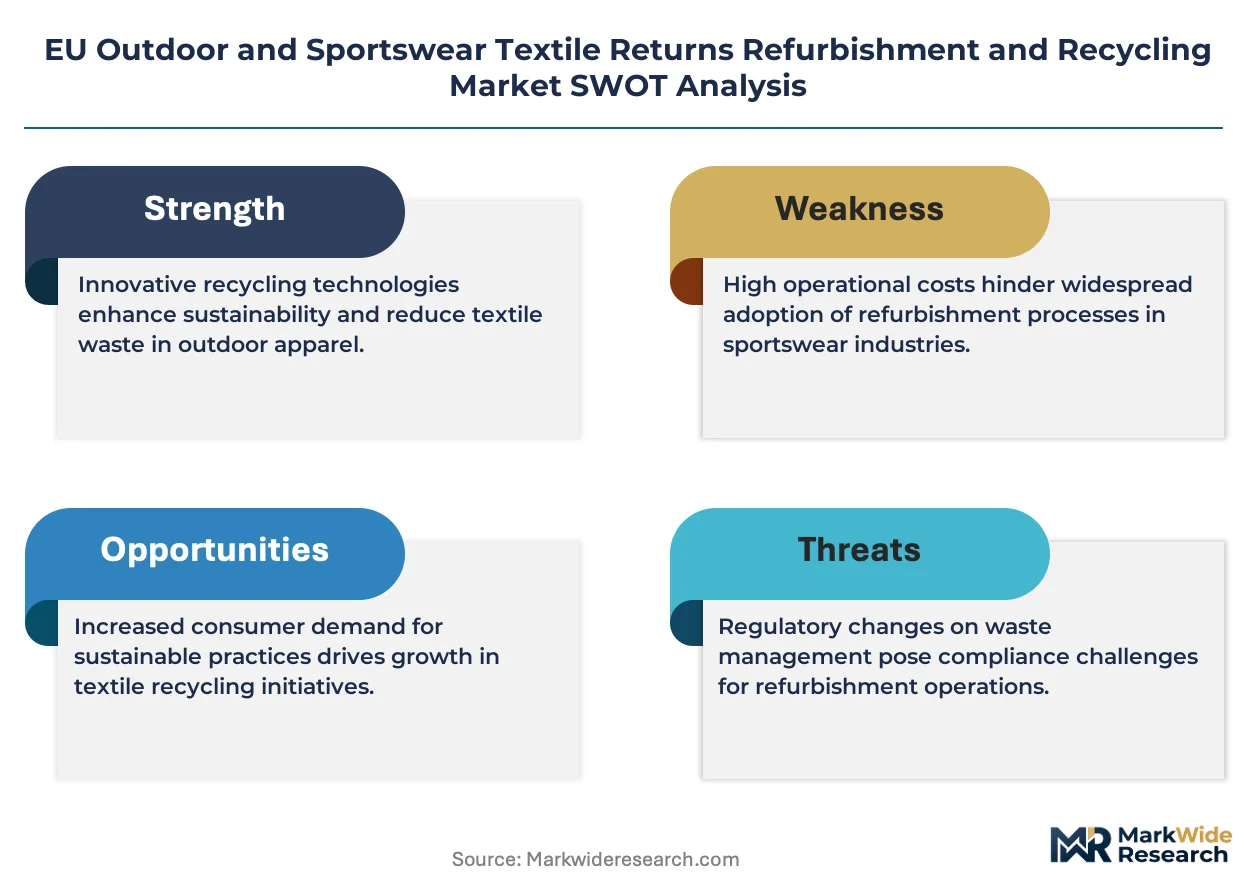
Extended producer responsibility transpositions under the EU Textile Strategy are forcing outdoor brands to internalize reverse logistics costs, compressing margins for pure retail plays while rewarding integrated collection-processing operators.
Growth Catalysts
- EU Green Deal collection mandates:National transpositions require separate textile collection infrastructure by 2025, creating guaranteed feedstock pipelines for refurbishment facilities.
- Belgium and Italy:Chemical recycling clusters for nylon and polyester performance fabrics attract concentrated capital deployment from polymer producers seeking circular feedstocks.
- Secondhand marketplace integration:Rental services and peer-to-peer platforms normalize pre-owned technical gear acceptance among younger outdoor recreation demographics.
Market Restraints
- Depolymerization catalyst costs:REACH authorization timelines for novel chemical recycling solvents extend development cycles beyond typical venture capital horizons.
- Feedstock quality variance:Post-consumer sportswear arrives contaminated with PFAS treatments and blended elastane content that degrades mechanical recycling yields.
- Refurbishment labor intensity:Skilled repair technicians for technical outerwear command premium wages that scale poorly against automated sorting alternatives.
Strategic Opportunities
- Netherlands reverse logistics hub:Rotterdam port infrastructure supports import of used technical textiles from Nordic markets for EU-wide redistribution.
- Ecodesign for Sustainable Products Regulation:Digital product passport requirements create first-mover advantage for brands with pre-integrated fiber tracing systems.
- Repair subscription bundling:Outdoor retailers pair seasonal gear refresh programs with refurbishment credits, locking recurring revenue streams.
Industry Challenges
- Blended fiber separation:Polyester-cotton-elastane combinations in stretch performance wear resist current mechanical sorting technologies without quality degradation.
- Certification timeline compression:OEKO-TEX and GRS recycled content verification processes lag behind brand marketing claims, creating greenwashing exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market |
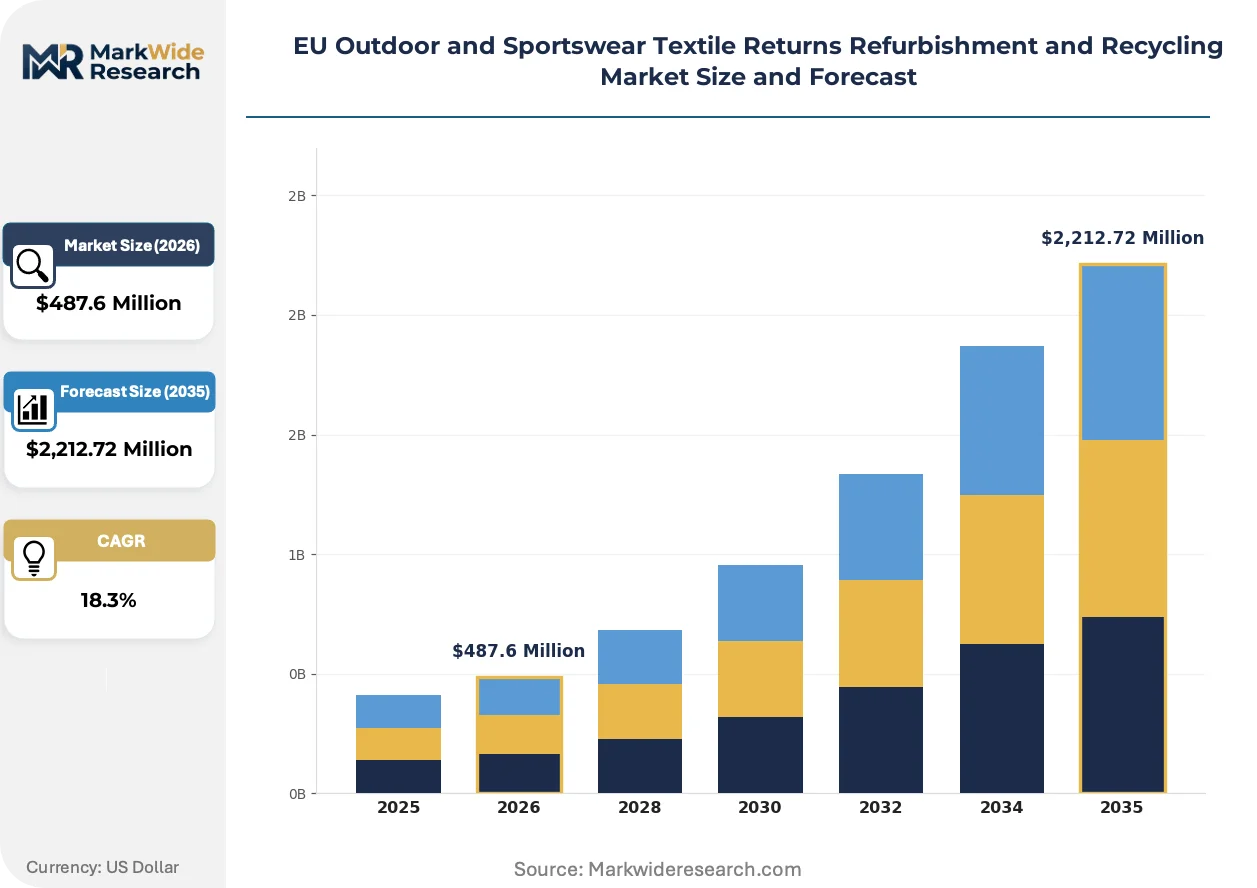
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,212.72 Million |
| CAGR (2026 – 2036) | 18.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Nylon, Cotton, Wool, Elastane, Acrylic End Use Application: Hiking Equipment, Fitness Apparel, Casual Wear, Performance Gear, Winter Sportswear, Yoga Apparel Processing Method: Mechanical Recycling, Chemical Recycling, Refurbishment, Downcycling, Upcycling, Repurposing Customer Segment: Specialty Retailers, Online Marketplaces, Secondhand Shops, Rental Services, Corporate Uniform Providers, Sports Clubs |
| Companies Covered | SOEX Group, ACS Clothing, Recover, Infinited Fiber Company, Reju, Resortecs, Decathlon, Lenzing Group, H&M Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market Trends and Innovations
Chemical recycling infrastructure is scaling faster than mechanical alternatives across the EU, driven by polymer quality requirements for high-performance re-spinning applications.
Enzymatic depolymerization of polyester is overtaking thermal glycolysis as the preferred chemical recycling pathway for moisture-wicking sportswear. Outdoor brands in Germany and France are piloting closed-loop take-back programs that feed enzymatic processes directly. This technology is overtaking legacy mechanical recycling for premium technical fibers by preserving polymer chain length suitable for stretch performance specifications.
Ecodesign for Sustainable Products Regulation disclosure requirements will force point-of-sale fiber composition and recyclability grading by 2027. REACH restricted substance thresholds for PFAS in water-repellent treatments are tightening simultaneously. Hiking and mountaineering gear manufacturers face dual compliance pressure, accelerating substitution of C6 fluorocarbon chemistries with silicone-based alternatives.
Rental and subscription models for technical outdoor equipment are displacing outright ownership among urban recreational users. Decathlon and specialized alpine outfitters in France and Switzerland now offer seasonal gear access programs with embedded refurbishment cycles. This consumption-pattern shift concentrates demand for durable, easily serviceable construction methods that simplify component replacement and fiber recovery.
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market Segmentation
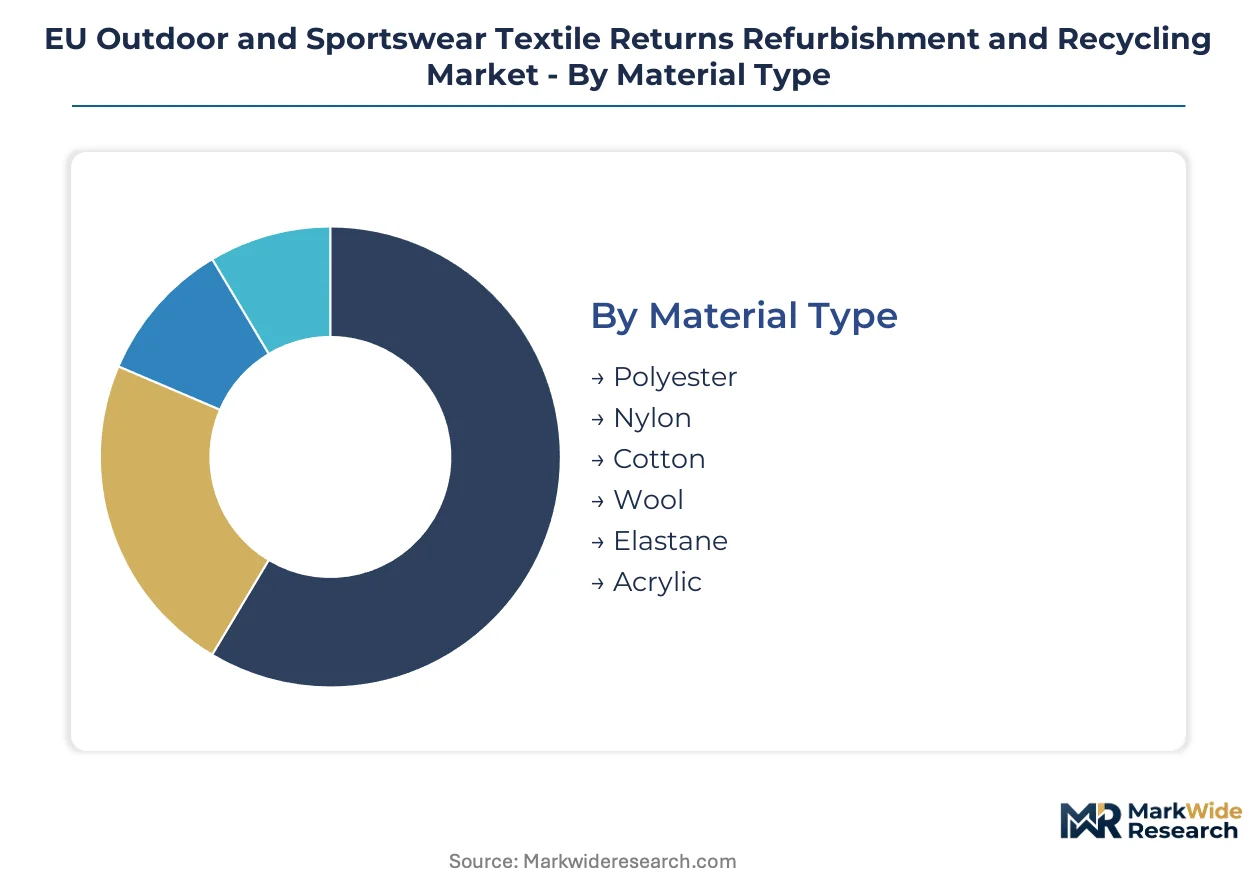
Segmentation in this market reveals how technical fiber properties, end-use durability requirements, and processing economics intersect to determine value recovery pathways. Distinct material compositions and performance specifications create divergent refurbishment economics across the EU regulatory landscape.
Material Type:
Technical specifications around fiber length retention, polymer chain integrity, and blend separation difficulty define processing route selection and output quality tiers.
- Polyester:Dominant synthetic input derived from PET bottles and post-consumer sportswear with established glycolysis and enzymatic depolymerization pathways. German chemical recycling clusters in North Rhine-Westphalia concentrate capacity for moisture-wicking base layer recovery. Demand concentrates in performance gear re-spinning where virgin-equivalent polymer quality commands premium offtake terms from alpine outfitters.
- Nylon:Polyamide 6 and 6,6 variants from technical outerwear and climbing harnesses require acid hydrolysis or aminolysis for depolymerization. Italian polymer producers near Milan anchor EU capacity for carpet-to-textile and apparel-to-apparel circular feedstock regeneration. Belgian investment flows target closed-loop nylon 6 regeneration for stretch performance specifications in cycling and mountaineering applications.
- Cotton:Cellulosic fiber from casual outdoor wear suits mechanical shredding and short-staple respinning for insulation batting and nonwoven applications. French sorting infrastructure prioritizes cotton-polyester blend separation for hybrid mechanical-chemical processing routes.
- Wool:Protein fiber from hiking socks and base layers retains thermal properties through mechanical garnetting for premium insulation markets. Scottish and Irish wool recovery operations supply EU-wide heritage brand refurbishment programs.
- Elastane:Polyurethane-based stretch content complicates mechanical recycling yields due to thermoset crosslinking behavior. Netherlands research consortia pilot solvent-based separation for spandex recovery from yoga and fitness apparel.
- Acrylic:Synthetic wool substitute from cheaper fleece garments presents limited chemical recycling viability; downcycling to nonwoven industrial applications dominates current processing economics.
Polyester leads on scale; nylon leads on momentum.
End Use Application:
Product durability specifications and contamination exposure patterns determine refurbishment feasibility and residual value capture across outdoor activity categories.
- Hiking Equipment:Technical backpacks, tents, and sleeping bags with reinforced construction and modular components support component-level repair and resale. German and Austrian alpine retailers operate dedicated refurbishment workshops for premium hardshell and load-bearing equipment.
- Fitness Apparel:High-rotation synthetic garments with elastane content drive chemical recycling feedstock volumes but resist mechanical fiber quality preservation. French sportswear brands pilot enzymatic polyester recovery from club and gym return streams.
- Casual Wear:Lower technical specification outdoor-inspired clothing enables straightforward resale and mechanical recycling pathways with minimal preprocessing. Dutch online marketplaces concentrate volume for this category.
- Performance Gear:Compression wear, trail running shoes, and technical base layers with bonded seams and membrane laminations require specialized disassembly labor. Italian footwear clusters develop automated sole separation for running shoe midsole recovery.
- Winter Sportswear:Ski and snowboard apparel with waterproof-breathable membranes and insulated constructions present PFAS contamination challenges under tightening ECHA restrictions. Scandinavian rental services embed seasonal refresh cycles with membrane replacement protocols.
- Yoga Apparel:Stretch-intensive synthetic blends from studio wear generate concentrated elastane-contaminated feedstock for emerging solvent separation trials in Netherlands pilot facilities.
Hiking equipment commands margin premiums; fitness apparel generates volume throughput.
Processing Method:
Capital intensity and output quality specifications segment operators across mechanical shredding, chemical depolymerization, and labor-intensive refurbishment workflows.
- Mechanical Recycling:Shredding, garnetting, and short-staple respinning of single-fiber or compatible blends dominates current EU volume due to lower equipment thresholds. Spanish and Portuguese operations concentrate on cotton and polyester mechanical processing for insulation and automotive nonwoven offtake.
- Chemical Recycling:Depolymerization to monomer or oligomer intermediates enables virgin-equivalent polymer regeneration for high-performance re-spinning. Belgium and Italy attract disproportionate capital deployment for nylon and polyester glycolysis scale-up.
- Refurbishment:Skilled repair, cleaning, and quality grading for direct resale captures highest value per kilogram but scales poorly against automated alternatives. French and Swiss outdoor retailers integrate in-house refurbishment with subscription rental programs.
- Downcycling:Quality-degrading conversion to insulation, wiping cloth, or industrial nonwoven applications absorbs contaminated or degraded feedstock unsuitable for fiber-to-fiber recovery.
- Upcycling:Design-driven transformation into higher-value products through creative reconstruction remains niche but commands brand collaboration premiums in Netherlands and Denmark.
- Repurposing:Component extraction and alternative application of functional elements like zippers, buckles, and membrane panels supports repair ecosystem supply.
Mechanical recycling dominates current throughput; chemical recycling climbs the fastest.
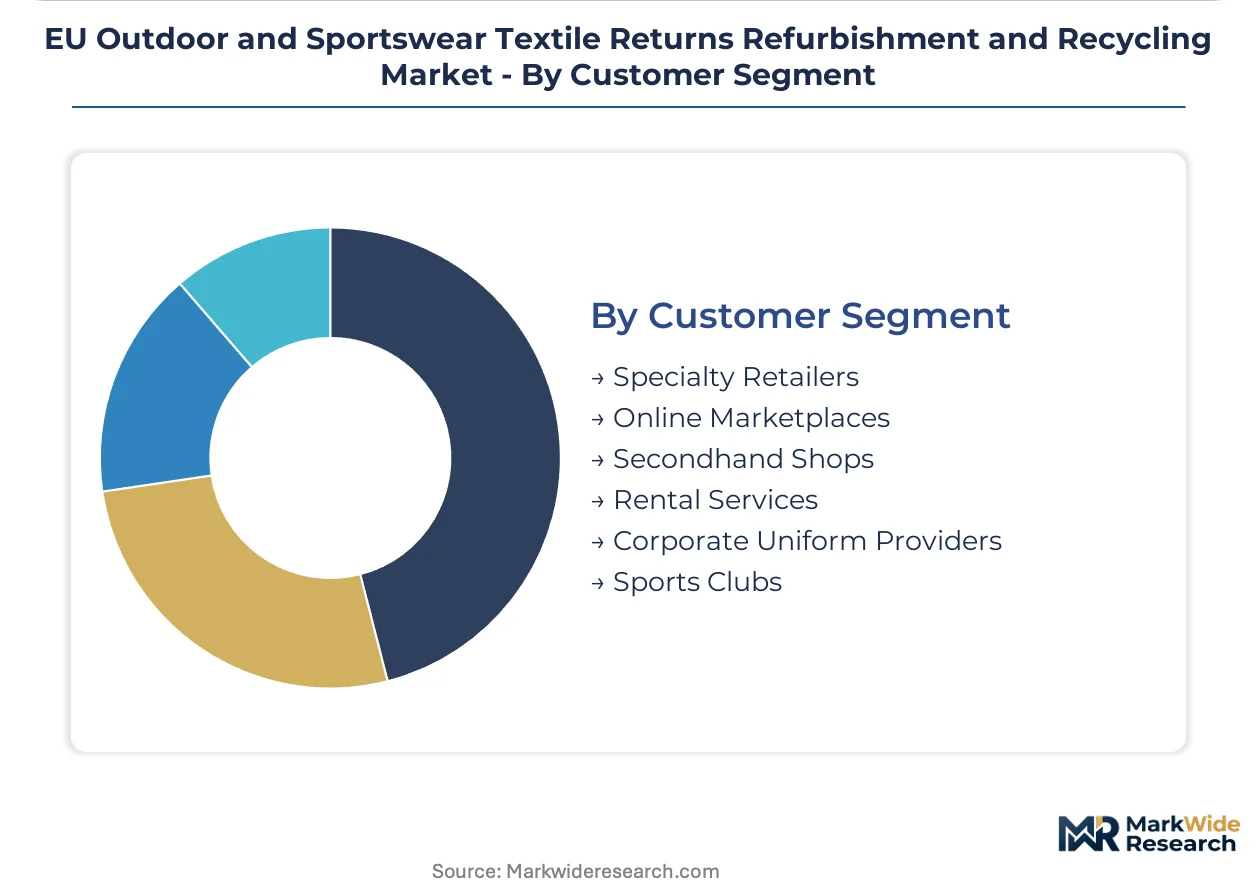
Customer Segment:
Channel-specific quality standards, volume predictability, and integration depth with collection infrastructure shape processor offtake agreements and pricing structures.
- Specialty Retailers:Integrated outdoor chains with in-house take-back and refurbishment capabilities capture closed-loop value and customer loyalty through resale credit programs. Decathlon's EU-wide platform exemplifies volume-integrated refurbishment economics.
- Online Marketplaces:Peer-to-peer and curated resale platforms normalize secondhand technical gear acceptance among younger demographics but struggle with authentication and quality standardization.
- Secondhand Shops:Physical thrift and consignment operations provide local collection points with variable quality sorting that feeds regional refurbishment workshops or downcycling streams.
- Rental Services:Subscription-based outdoor gear access models concentrate demand for durable, serviceable construction and embed predictable refurbishment cycles. Swiss and French alpine outfitters scale seasonal programs.
- Corporate Uniform Providers:Bulk return streams from branded workwear and team sports kits offer volume concentration but limited style diversity for resale channels.
- Sports Clubs:Team kit rotation and end-of-season returns generate polyester-heavy feedstock suitable for mechanical recycling or chemical depolymerization depending on elastane content.
Specialty retailers lead on integration depth; rental services lead on growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Textile circularity infrastructure first scaled through German sorting networks and Dutch port logistics before spreading to chemical recycling clusters in Belgium and Italy. The EU Green Deal's mandatory collection targets now channel investment toward refurbishment hubs and depolymerization facilities across member states with established technical textile manufacturing heritage.
Germany
SOEX Group anchors EU-wide collection infrastructure from its North Rhine-Westphalia sorting facilities, feeding mechanical recycling streams for polyester sportswear. The country's national transposition of extended producer responsibility under the EU Textile Strategy mandates separate textile bins by 2025. Berlin and Hamburg host refurbishment workshops serving Decathlon's secondhand marketplace with skilled repair labor for technical outerwear.
Netherlands
Rotterdam port infrastructure enables import of Nordic used technical textiles for redistribution across continental processing networks. ECHA REACH compliance frameworks for chemical recycling solvents concentrate regulatory expertise in Dutch research consortia piloting elastane separation technologies. Amsterdam-based rental services embed seasonal refresh cycles that normalize pre-owned gear acceptance among urban outdoor recreation users.
Belgium
Antwerp's petrochemical heritage attracts capital deployment for nylon 6 closed-loop regeneration targeting cycling and mountaineering stretch specifications. The EU Green Deal's circular economy action plan channels innovation funding toward depolymerization catalyst development. Ghent textile engineering clusters collaborate with Italian polymer producers on quality-preserving fiber recovery protocols.
Italy
Milan anchors EU capacity for polyamide regeneration from carpet-to-textile and apparel-to-apparel circular feedstocks. The country's transposed EPR framework under the EU Textile Strategy enforces producer financing of collection infrastructure. Prato's historic wool recovery operations supply premium insulation markets while Tuscan footwear clusters develop automated sole separation for running shoe midsole recovery.
France
Decathlon's integrated take-back and resale platform exemplifies volume-driven refurbishment economics from its Lille headquarters. Ecodesign for Sustainable Products Regulation disclosure requirements drive Paris-based outdoor brands toward pre-integrated fiber tracing systems. Lyon chemical engineering expertise supports enzymatic polyester depolymerization pilots for moisture-wicking base layer recovery.
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market Competitive Landscape
The competitive structure tilts toward integrated collection-processing operators over pure retail plays. Extended producer responsibility mandates compress margins for brands lacking reverse logistics capabilities while rewarding operators with captive feedstock pipelines. Three archetypes dominate: chemical recycling technology licensors, vertically integrated retail-refurbishment platforms, and specialized fiber regeneration specialists. Capacity expansion in Belgian and Italian chemical clusters and strategic partnerships between sorters and polymer producers constitute the dominant competitive moves.
Within the integrated retail-refurbishment tier, Decathlon exemplifies volume-anchored platform economics through its EU-wide secondhand marketplace. Among collection infrastructure specialists, SOEX Group occupies a position representing reverse supply chain anchoring for sportswear retailers. On the fiber regeneration vector, Recover sits within the technology-differentiated archetype, with Lenzing Group representing adjacent cellulosic fiber circularity expertise.
| Leading Market Players |
|---|
| SOEX Group |
| ACS Clothing |
| Recover |
| Infinited Fiber Company |
| Reju |
| Resortecs |
| Decathlon |
| Lenzing Group |
| H&M Group |
| Others |
Pricing and Supply Chain Analysis
Specialty outdoor retailers with integrated take-back platforms command pricing power through bundled resale credits and repair subscriptions that lock recurring revenue streams. This buyer concentration forces pure collection processors toward volume-based contract terms while rewarding operators with captive refurbishment capacity.
Pricing Analysis
Three-tier pricing structure across premium certified, standard verified, and economy ungraded levels segments the EU market by fiber tracing depth and OEKO-TEX certification status. Price differentiation hinges on GRS recycled content verification and digital product passport integration, with premium tiers commanding offtake premiums from alpine outfitters. Cost compression in standard mechanical recycling is intensifying because polyester feedstock quality variance degrades yield rates. Sports clubs and corporate uniform providers exhibit highest price sensitivity, while specialty retailers with in-house refurbishment show lowest elasticity due to customer loyalty lock-in.
Supply Chain Analysis
Skilled repair technician shortages in North Rhine-Westphalia and Prato constrain refurbishment scaling against automated sorting alternatives. Supply concentration rests on Belgian nylon depolymerization clusters, Italian polyamide regeneration facilities, and German mechanical recycling infrastructure. Raw material dependencies include post-consumer polyester sportswear, PFAS-contaminated membrane laminates, and elastane-blended yoga apparel. Single-source vulnerability to REACH authorization delays for novel chemical recycling solvents threatens capacity expansion timelines. Distribution feeds from Rotterdam port import hubs through Dutch sorting networks into EU-wide redistribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market derives from chemical recycling scale-up that preserves virgin-equivalent polymer quality for premium re-spinning applications. Ecodesign disclosure mandates create first-mover advantage for operators with pre-integrated fiber tracing systems.
For Market Incumbents: Lock in captive feedstock pipelines through exclusive collection partnerships with Decathlon-scale retail platforms before EPR mandates saturate reverse logistics capacity. Defend margin position by accelerating enzymatic polyester depolymerization R&D in Lyon and North Rhine-Westphalia clusters to outpace mechanical recycling commoditization. For New Entrants and Emerging Players: Capture white-space in Netherlands elastane separation pilot facilities where solvent-based spandex recovery from yoga apparel remains pre-commercial. Target Scandinavian rental services with seasonal refresh cycle integration as the most penetrable customer segment, leveraging component-level repair expertise from Austrian alpine workshop models. For Investors and Strategic Acquirers: Polymer producers with circular feedstock commitments are the most active acquirer in this space, seeking backward integration into depolymerization capacity. Long-term viability centers on chemical recycling technology licensors with REACH-authorized catalyst portfolios. Watch for ECHA PFAS restriction tightening as the inflection signal that accelerates membrane replacement protocol adoption and concentrates refurbishment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Depolymerization Scale-Up | Belgian and Italian polymer producers anchor circular nylon and polyester feedstock regeneration for high-performance re-spinning. |
| Digital Product Passport Integration | French outdoor brands with pre-integrated fiber tracing systems secure Ecodesign compliance advantage by 2027 disclosure deadlines. |
| Rotterdam Hub Expansion | Netherlands port infrastructure consolidates Nordic used technical textile import for EU-wide redistribution to processing clusters. |
| Repair Subscription Bundling | Swiss and French alpine outfitters embed predictable refurbishment cycles that normalize pre-owned gear acceptance among urban users. |
| REACH Catalyst Authorization | Dutch research consortia pilot novel solvent approvals that determine chemical recycling capacity expansion feasibility. |
Research Methodology
Bottom-up end-use application modeling reconciled against top-down chemical recycling capacity tracking forms the analytical core of this study. Primary interviews with outdoor brand sustainability directors, ECHA regulatory affairs specialists, polymer producer procurement leads, and Dutch sorting facility operators combined with secondary validation from EU Textile Strategy implementation reports, ECHA REACH substance databases, and national EPR transposition documents. This approach triangulates collection volume estimates against processing capacity buildouts.
Input-output matrices map fiber type flows through mechanical shredding, chemical depolymerization, and refurbishment pathways across the projection horizon. Segmentation dimensions include material composition, end-use durability specifications, processing method capital intensity, and customer channel integration depth. CAGRs derive from capacity utilization rates and offtake agreement pricing trends, with enzymatic polyester recovery adoption curves and rental service penetration rates as key forecast inputs.
REACH authorization delays, PFAS restriction enforcement timelines, and chemical recycling catalyst cost curves are the dominant revision risks. Forecasts reflect documented assumptions about EPR mandate compliance rates and enzymatic technology scale-up trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Recycle Yarn Market