
 Global Recycled Textiles Market | 2026-2036
Global Recycled Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recycled Textiles Market Foresight
The EU Green Deal is repositioning capital allocation across European textile recycling, raising compliance costs for virgin fiber imports while creating preferential market access for certified recycled inputs. Lenzing AG leverages its Tencel Refibra technology to anchor premium positioning in closed-loop cellulosic recycling. Birla Cellulose competes through integrated pulp-to-fiber operations that sustain cost discipline across multiple recycled feedstock streams.
Recycled textiles comprise post-consumer and post-industrial fiber, yarn, fabric, and nonwoven materials reprocessed through mechanical shredding, chemical depolymerization, or thermal recovery to serve as substitutes for virgin textile inputs in industrial and consumer applications. Fiber-grade recycled cotton typically achieves staple lengths of 12-25mm, constraining its use to ring-spun blends below 30% recycled content without strength degradation. Nonwoven applications lead volume absorption due to lower performance thresholds and established automotive interior specifications, while chemically recycled polyester yarn captures the fastest value growth as bottle-to-textile pathways mature and brand commitments harden. Blended textiles remain structurally disadvantaged because mixed-fiber compositions resist both mechanical and chemical separation, concentrating margin pools in mono-material collection and preprocessing systems.
REACH compliance and the EU's forthcoming Digital Product Passport requirements are reshaping traceability obligations, with ECHA substance restrictions now extending to recycled input certification. The F-Gas Regulation indirectly affects polyester recycling energy profiles by constraining thermal process refrigerants, while ISO 14021 environmental claims standards govern how brands communicate recycled content ratios to wholesale distributors and retail channels. Stakeholders must monitor how chemical recycling scale-up interacts with mechanical recycling economics, as feedstock competition between these pathways will determine which source material categories achieve viable offtake at each quality tier.
Market Dynamics
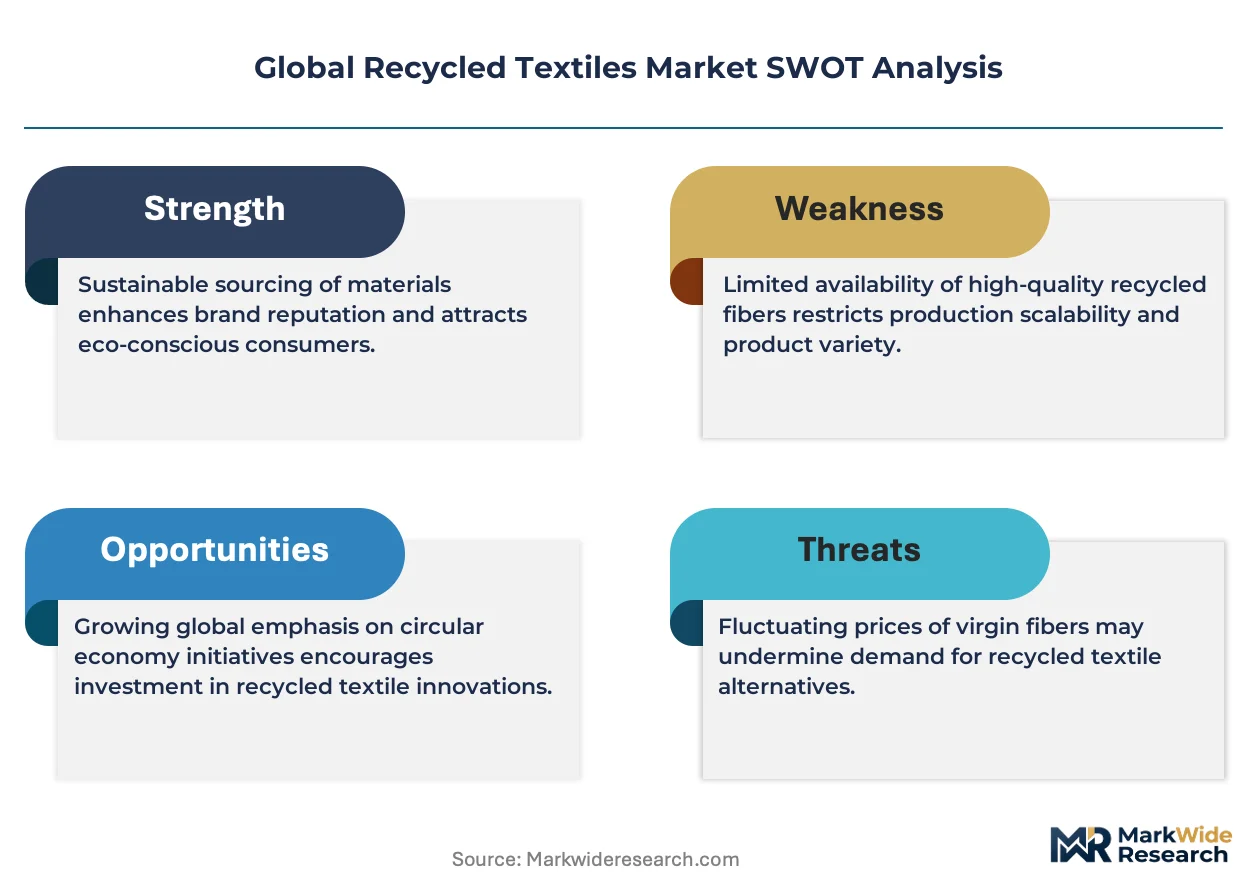
Feedstock competition between mechanical and chemical recycling pathways is compressing margin pools across the value chain, forcing processors to secure long-term collection contracts before infrastructure scale-up locks in sourcing hierarchies.
Growth Catalysts
- EU Green Deal mandates:Extended producer responsibility frameworks in Germany, France, and the Netherlands are mandating minimum recycled content thresholds, creating guaranteed offtake for certified fiber suppliers.
- Automotive nonwoven specifications:Tier 1 seating and interior suppliers in Stuttgart and Wolfsburg are qualifying recycled polyester staple for acoustic insulation and surface materials under OEM sustainability scorecards.
- Chemical depolymerization scale-up:Industrial-scale glycolysis and methanolysis installations in Belgium and Italy are expanding feedstock acceptance to colored and contaminated post-consumer polyester streams previously rejected by mechanical processors.
Market Restraints
- Cotton staple length degradation:Mechanical shredding of post-consumer denim and knitwear yields fiber averaging 15mm staple length, restricting ring-spinning compatibility and forcing reliance on open-end rotor systems with lower yarn tenacity ceilings.
- Blended textile structural disadvantage:Polyester-cotton and elastane-containing garments resist both mechanical separation and chemical selectivity, leaving 40-60% of post-consumer feedstock stranded in downcycling or energy recovery pathways.
- REACH certification costs:ECHA substance restrictions extending to recycled input verification are imposing testing burdens on small and mid-scale collectors, consolidating preprocessing capacity toward integrated chemical fiber producers with in-house laboratories.
Strategic Opportunities
- India collection infrastructure:Informal waste picker networks in Mumbai, Delhi, and Tirupur handle substantial post-consumer textile volumes without formal sorting systems, creating first-mover advantage for processors establishing standardized feedstock contracts.
- Digital Product Passport alignment:The EU's forthcoming DPP requirements for textile traceability are opening service contracts for blockchain-enabled chain-of-custody platforms linking collection points to certified fiber output.
- Cellulosic chemical recycling convergence:Partnerships between pulp processors and viscose manufacturers are piloting direct dissolution pathways for cotton-rich waste streams, bypassing mechanical shredding entirely and preserving fiber integrity for filament applications.
Industry Challenges
- Feedstock quality variance:Post-consumer collection systems yield inconsistent fiber compositions, moisture levels, and contamination profiles that disrupt continuous chemical recycling reactor operations and require adaptive preprocessing investments.
- ISO 14021 claim substantiation:Brands face audit complexity when communicating recycled content ratios across blended supply chains, as mechanical recycling content calculations differ from mass-balance approaches used in chemical recycling certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recycled Textiles Market |
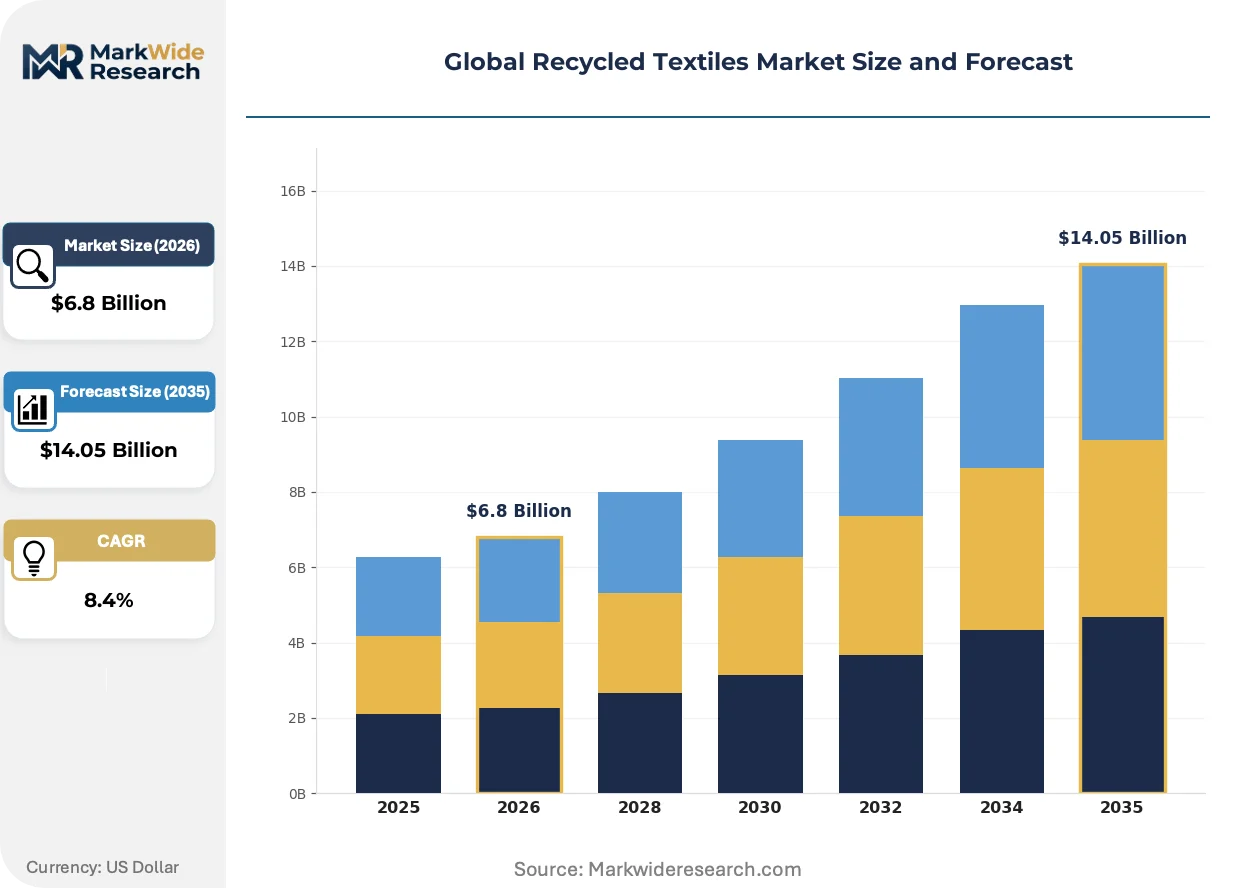
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber, Yarn, Fabric, Nonwoven, Blended Textiles Source Material: Cotton, Polyester, Nylon, Wool, Acrylic End Use Application: Apparel, Home Textiles, Automotive Interiors, Industrial Textiles, Footwear Sales Channel: Wholesale Distributors, E-commerce, Retail Stores, Direct Sales, Specialty Shops |
| Companies Covered | Lenzing AG, Birla Cellulose, HYOSUNG TNC, Unifi, Inc., Renewcell, The Woolmark Company, The Boer Group, Martex Fiber, Worn Again Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recycled Textiles Market Shifts & Advancements
Chemical recycling infrastructure is consolidating competitive advantage around mono-material feedstock security, while regulatory traceability mandates and buyer certification preferences are rewiring procurement hierarchies across the value chain.
Depolymerization-based polyester regeneration is consolidating technical leadership in the premium fiber tier. Automotive seating suppliers and outdoor apparel brands are adopting chemically recycled filament yarn for performance specifications requiring consistent dye uptake and tensile strength. This technology is consolidating margin capture toward integrated producers with captive glycolysis capacity, compressing mechanical recyclers into commodity staple markets.
REACH substance restrictions and the EU Digital Product Passport are tightening traceability obligations across the value chain. ECHA's extension of SVHC screening to recycled inputs is forcing collectors to implement pre-sorting protocols that segregate potentially contaminated feedstock streams. German and French textile brands are responding by consolidating supplier bases toward vertically integrated chemical fiber producers with certified chain-of-custody documentation.
Brand-led take-back programs are rewiring collection economics in European markets. H&M, Zara, and independent resale platforms are establishing direct consumer return channels that bypass traditional municipal waste streams, securing higher-quality post-consumer feedstock with known fiber compositions. This channel innovation is most visible in Stockholm, Berlin, and Amsterdam, where logistics density supports economically viable reverse supply chains for mono-material garment categories.
Global Recycled Textiles Market Segmentation
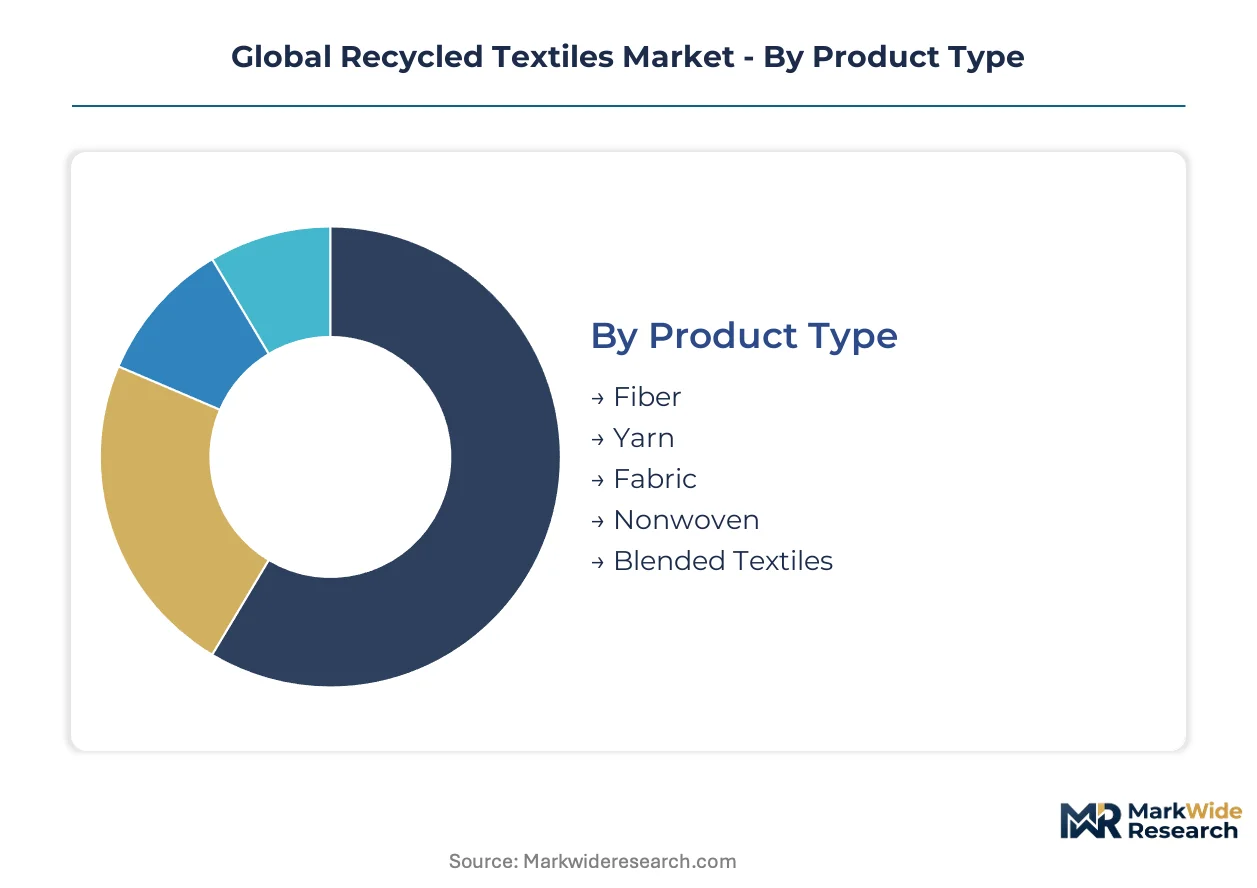
Segmentation in recycled textiles reveals how technical specifications, feedstock chemistry, and certification requirements fragment procurement decisions across buyer categories. Each dimension exposes distinct margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Buyers select product types based on performance thresholds and spinning system compatibility, with fiber integrity directly determining yarn tenacity and dye uptake consistency.
- Fiber:Mechanically shredded cotton and polyester staple dominate volume flows, though staple length degradation to 12-25mm restricts ring-spinning applications without virgin fiber blending. Automotive nonwoven suppliers in Stuttgart specify recycled polyester staple for acoustic insulation under OEM sustainability scorecards.
- Yarn:Chemically recycled polyester filament yarn achieves consistent molecular weight distribution, enabling performance specifications for outdoor apparel brands requiring uniform dye uptake. Belgium's industrial-scale glycolysis installations supply this tier with bottle-derived feedstock.
- Fabric:Woven and knitted constructions from recycled inputs serve home textile and industrial applications where aesthetic uniformity matters less than certification compliance.
- Nonwoven:Lower performance thresholds and established automotive interior specifications make this the primary volume absorption channel for mechanically recycled staple.
- Blended Textiles:Mixed-fiber compositions resist separation technologies, leaving most post-consumer blended feedstock stranded in downcycling or energy recovery pathways.
Nonwoven leads on scale; chemically recycled yarn leads on momentum.
Source Material:
Feedstock chemistry governs reprocessing pathway economics, with mono-material streams commanding premium collection contracts.
- Cotton:Post-consumer denim and knitwear yields mechanically shredded fiber averaging 15mm staple length, forcing reliance on open-end rotor spinning. India's informal waste picker networks in Mumbai and Tirupur handle substantial volumes without formal sorting.
- Polyester:Bottle-to-textile pathways mature through industrial-scale depolymerization, with colored and contaminated streams now accepted by chemical recyclers in Italy and Belgium.
- Nylon:Carpet and fishing net waste streams supply depolymerization reactors, though collection infrastructure remains concentrated in European and North American markets.
- Wool:Premium garment take-back programs yield higher-quality post-consumer feedstock with known fiber compositions.
- Acrylic:Limited chemical recycling infrastructure constrains circular pathways, with most volumes directed toward thermal recovery.
Polyester leads on scale; cotton leads on momentum.
End Use Application:
Application selection hinges on performance certification requirements and brand sustainability commitments that mandate recycled content thresholds.
- Apparel:Fashion brands seeking circular supply chains drive procurement of mechanically and chemically recycled fibers, with EU Green Deal mandates creating guaranteed offtake.
- Home Textiles:Lower performance thresholds accommodate shorter staple recycled cotton in bedding and towel applications.
- Automotive Interiors:Tier 1 seating suppliers in Wolfsburg qualify recycled polyester staple for surface materials under OEM sustainability scorecards.
- Industrial Textiles:Geotextiles and filtration media absorb commodity-grade recycled fiber with minimal aesthetic requirements.
- Footwear:Upper materials and linings incorporate recycled polyester and nylon, though elastane-containing constructions resist recycling.
Automotive interiors lead on scale; apparel leads on momentum.
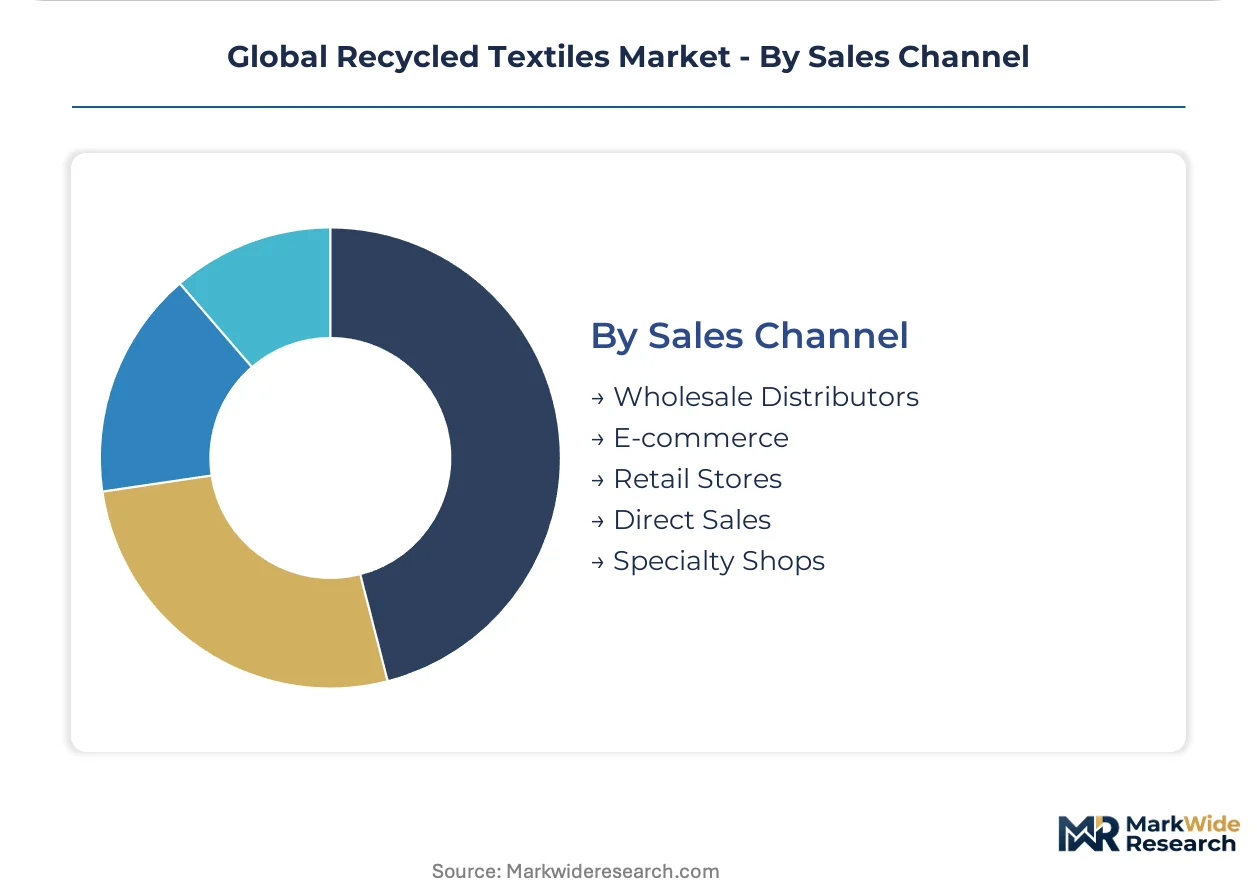
Sales Channel:
Channel selection reflects certification complexity and lot-size requirements, with traceability documentation favoring integrated supply relationships.
- Wholesale Distributors:Bulk fiber and yarn transactions dominate, with REACH certification requirements consolidating procurement toward suppliers with in-house laboratory verification.
- E-commerce:Direct-to-brand platforms for certified recycled inputs are expanding as Digital Product Passport requirements tighten traceability obligations.
- Retail Stores:Limited penetration for industrial textile inputs, though consumer-facing resale platforms in Berlin and Amsterdam establish reverse supply chains.
- Direct Sales:Long-term collection contracts between brands and chemical fiber producers bypass traditional distribution tiers.
- Specialty Shops:Niche sustainable fashion retailers source small-lot certified recycled fabrics with full chain-of-custody documentation.
Wholesale distributors lead on scale; e-commerce leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled chemical engineers and polymer scientists cluster in Germany's industrial heartland, anchoring Europe's chemical recycling capacity. Textile chemistry PhDs concentrate in India's Tirupur-Mumbai corridor, sustaining low-cost mechanical processing operations.
Germany
Automotive OEM sustainability scorecards from Stuttgart and Wolfsburg drive demand for certified recycled polyester staple. Extended producer responsibility frameworks mandate minimum recycled content thresholds, tightening compliance for virgin fiber imports. Industrial-scale glycolysis installations in North Rhine-Westphalia process colored post-consumer polyester streams previously rejected by mechanical recyclers.
Belgium
Chemical fiber producers with captive depolymerization capacity secure premium positioning in bottle-to-textile supply chains. The F-Gas Regulation constrains thermal process refrigerants, elevating energy costs for polyester regeneration facilities. Antwerp's port infrastructure enables efficient feedstock aggregation from European collection networks.
Italy
Prato's textile district integrates mechanically recycled wool and cotton into heritage knitwear production. Methanolysis installations in Lombardy expand feedstock acceptance to contaminated polyester streams. REACH substance restrictions extend to recycled input verification, consolidating preprocessing capacity toward integrated producers with in-house laboratories.
India
Informal waste picker networks in Mumbai and Tirupur handle substantial post-consumer textile volumes without formal sorting systems. Bureau of Indian Standards certification requirements for recycled fiber quality create entry barriers for unorganized collectors. Maharashtra's garment exporters establish backward linkages to secure standardized feedstock contracts for mechanical shredding operations.
United States
EPA waste diversion incentives and state-level extended producer responsibility pilots in California and New York reshape collection economics. Unifi's bottle-to-fiber operations in North Carolina exemplify integrated chemical recycling at scale. Tier 1 automotive seating suppliers in Detroit qualify recycled polyester staple for acoustic insulation under OEM sustainability scorecards.
Global Recycled Textiles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across mechanical and chemical recycling pathways. The vendor base stratifies into three tiers: integrated chemical fiber producers with captive depolymerization capacity, mid-scale mechanical processors serving commodity staple markets, and technology licensors commercializing novel separation chemistries. Dominant competitive moves include long-term feedstock collection contracts and strategic partnerships between apparel brands and chemical recyclers.
Within the integrated chemical fiber tier, Lenzing AG exemplifies premium positioning through closed-loop cellulosic recycling technology. Birla Cellulose occupies a position among pulp-to-fiber operators sustaining cost discipline across multiple feedstock streams. Unifi, Inc. represents the scale-driven end of bottle-to-textile polyester regeneration, anchoring North American supply capacity.
| Leading Market Players |
|---|
| Lenzing AG |
| Birla Cellulose |
| HYOSUNG TNC |
| Unifi, Inc. |
| Renewcell |
| The Woolmark Company |
| The Boer Group |
| Martex Fiber |
| Worn Again Technologies |
| Others |
Supply & Pricing Matrix
EU Green Deal extended producer responsibility mandates gate both qualified supply and premium-tier pricing access, as certified recycled fiber producers command long-term offtake premiums while uncertified mechanical processors absorb commodity-grade margin compression.
Pricing Analysis
Certification-bundled versus unbundled feedstock contracts split the pricing landscape. Contract-based long-term offtake agreements dominate the premium tier, with price differentiation anchored in REACH compliance grade and volume scale commitments. Cost compression in mechanical recycling is intensifying because chemical depolymerization scale-up is locking in mono-material feedstock security. Fast-fashion brands exhibit highest price sensitivity, while automotive OEMs accept premium positioning for certified chain-of-custody documentation.
Supply Chain Analysis
Reverse-logistics flows through brand-led take-back programs in Berlin, Amsterdam, and Stockholm are rewiring collection economics. Feedstock concentration centers on Germany, Belgium, and Italy for chemical recycling infrastructure, with India anchoring low-cost mechanical processing. Raw material dependencies draw from post-consumer polyester streams, cotton-rich garment waste, and bottle-derived PET bales. Single-source vulnerability concentrates in glycolysis reactor feedstock contracts. Distribution runs through wholesale fiber distributors consolidating toward integrated producers with in-house laboratory verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in recycled textiles rests on chemical recycling scale-down economics and the premium-tier shift toward certified filament yarn for performance apparel applications.
For Market Incumbents: Deepen backward integration into mono-material collection infrastructure before feedstock competition locks in sourcing hierarchies. Secure long-term contracts with automotive Tier 1 suppliers in Stuttgart and Wolfsburg to defend against emerging chemical recycling entrants in Belgium and Italy. Prioritize REACH certification investment to maintain premium positioning as ECHA substance restrictions extend to recycled input verification. For New Entrants and Emerging Players: Direct-to-brand e-commerce platforms for blockchain-enabled chain-of-custody documentation represent the most penetrable route. Target India's informal waste picker networks in Mumbai and Tirupur for standardized feedstock contract establishment. Deploy Digital Product Passport alignment services as the primary go-to-market angle, leveraging regulatory traceability mandates to bypass entrenched wholesale distribution tiers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale mechanical processors with regional collection density because feedstock quality variance creates consolidation pressure toward integrated laboratory capacity. The five-to-ten year viability window favors acquisitions of chemical depolymerization technology licensors over commodity staple operators. Watch chemical recycling reactor utilization rates as the inflection signal for pathway economics tipping toward glycolysis and methanolysis scale-up.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Secures mono-material feedstock streams before chemical recycling scale-up locks in sourcing hierarchies in Germany and Belgium. |
| REACH Certification Investment | ECHA substance restrictions extending to recycled inputs consolidate preprocessing capacity toward integrated producers with in-house laboratories. |
| Digital Product Passport Platform Development | EU traceability mandates open service contracts for blockchain-enabled chain-of-custody linking collection points to certified fiber output. |
| Long-term Automotive Supply Agreement | OEM sustainability scorecards from Stuttgart and Wolfsburg mandate minimum recycled content thresholds for Tier 1 seating suppliers. |
| Cellulosic Chemical Recycling Joint Venture | Partnerships between pulp processors and viscose manufacturers pilot direct dissolution pathways bypassing mechanical shredding entirely. |
Research Methodology
Direct dialogue with chemical fiber plant managers, brand sustainability officers, automotive Tier 1 procurement leads, and waste collection network operators grounded the qualitative foundation. Secondary validation drew from ECHA substance restriction filings, EU Digital Product Passport regulatory drafts, customs and trade data on recycled fiber imports, and SEC disclosures from integrated textile producers. Bottom-up feedstock flow modeling and top-down market sizing triangulated volume estimates across mechanical and chemical recycling pathways.
Bottom-up capacity aggregation across glycolysis and methanolysis reactor installations combined with top-down apparel brand recycled content commitment tracking. Segmentation dimensions modeled include fiber grade tier, reprocessing pathway chemistry, end-use application performance threshold, and regional regulatory framework cluster. CAGRs were derived from feedstock availability projections and brand procurement timeline analysis, with chemical recycling yield rates and mechanical shredding staple length degradation curves as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for cellulosic direct dissolution would alter the outlook if pulp-to-fiber partnerships achieve commercial scale faster than projected. Forecasts reflect base-case assumptions on EU Green Deal implementation timing and EPR enforcement intensity across member states. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market