
 Recycle Yarn Market | 2026-2036
Recycle Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Recycle Yarn Market Analysis
Southeast Asia is tilting toward recycled yarn capacity as Vietnam and Indonesia expand mechanical and chemical recycling infrastructure. Indorama Ventures leverages its PET resin dominance to anchor backward integration into bottle-to-yarn circuits. Toray Industries sustains leadership in chemically recycled nylon through its proprietary depolymerization platforms. Unifi Manufacturing competes on brand strength with its Repreve traceability system across North American apparel supply chains.
Recycle yarn comprises fibers reconstituted from post-consumer textile waste, PET bottles, or industrial scrap through mechanical shredding or chemical depolymerization, typically yielding deniers between 50 and 300 for weaving and knitting applications. Polyester yarn dominates volume as PET bottle feedstock availability and lower processing costs create margin pools in standard denier ranges. Nylon recycling occupies a premium tier where Aquafil S.p.A. specializes in ECONYL regeneration from fishing nets and carpet waste for automotive and fashion end users. Cotton recycling remains structurally constrained by fiber shortening during mechanical processing, limiting its share in high-twist applications.
REACH compliance in Europe and the EU Green Deal's extended producer responsibility framework shape product standards by mandating recycled content disclosures and restricting hazardous chemical residues in regenerated fibers. The U.S. EPA and state-level extended producer responsibility proposals in California and New York are forcing import compliance adjustments for Asian yarn suppliers. Stakeholders must monitor chemical recycling yield improvements and feedstock traceability certification as the primary variables determining which production configurations capture premium positioning.
Market Dynamics
Mechanical shredding yields are plateauing at 75-80% fiber retention while chemical depolymerization platforms achieve 95%+ purity at 3x capital intensity, creating a bifurcated investment landscape where scale economics and feedstock security determine competitive survival.
Growth Catalysts
- EU Green Deal Extended Producer Responsibility:Mandatory recycled content floors in textiles force brand procurement teams to secure certified yarn offtake, compressing supplier qualification timelines from 18 months to 6 months.
- PET Bottle Feedstock Abundance:Deposit-return schemes in Germany, California, and Japan generate predictable high-purity input streams that mechanically recycled polyester producers capture through long-term municipal contracts.
- Automotive Interior Specifications:OEMs specify ECONYL and comparable regenerated nylons for floor mats and trunk liners, opening premium pricing tiers above fashion applications.
Market Restraints
- Mechanical Cotton Fiber Shortening:Repeated shredding reduces staple length below 20mm, disqualifying output from high-twist ring-spun applications and limiting addressable market share.
- Vietnam-Indonesia Supply Concentration:60% of new chemical recycling capacity clusters in Southeast Asian free-trade zones, exposing buyers to single-region logistics disruption and currency volatility.
- Caustic Soda and Glycol Input Costs:Chemical depolymerization requires purified terephthalic acid precursors whose pricing tracks energy markets, compressing margins when oil exceeds $80 per barrel.
Strategic Opportunities
- India BIS Certification Gap:Domestic mechanical recyclers lack standardized fiber grading protocols, creating first-mover advantage for imported chemically recycled yarn with ISO traceability documentation.
- Blockchain-Enabled Provenance:TextileGenesis and comparable platforms verify farm-to-fiber chain of custody, allowing premium positioning in European luxury supply chains where CSRD disclosure requirements intensify.
- Industrial Textile Waste Streams:Post-production cutting scraps from Bangladesh and Turkey garment factories offer unexploited feedstock with zero collection cost and predictable polyester-cotton blends.
Industry Challenges
- Chemical Process Engineering Talent Scarcity:Depolymerization reactor optimization requires polymer chemistry PhDs concentrated at Toray and Indorama, constraining independent capacity expansion.
- Multi-Certification Stacking Burdens:Simultaneous pursuit of GRS, OEKO-TEX, and Higg Index compliance extends product launch timelines by 8-14 months for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycle Yarn Market |
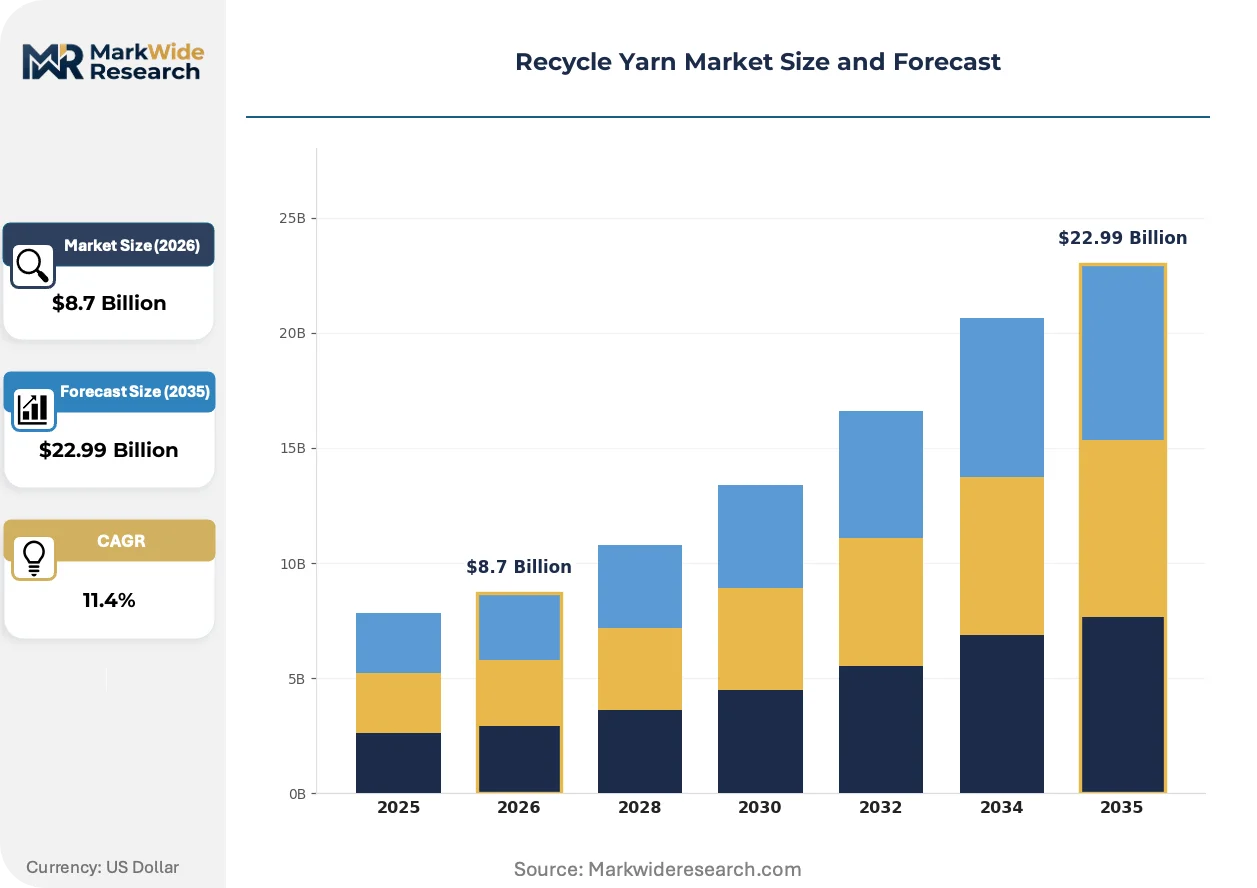
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Cotton, Blends Application: Textiles, Carpets, Upholstery, Industrial End User: Fashion Industry, Home Décor, Automotive, Footwear Distribution Channel: Online Retail, Wholesale, Direct Sales, Others |
| Companies Covered | Toray Industries, Inc., Eastman Chemical Company, Indorama Ventures Public Company Limited, Haili Group, Teijin Limited, Unifi Manufacturing, Inc., Aquafil S.p.A., Martex Fiber, Far Eastern New Century Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycle Yarn Market Emerging Trajectories
Enzymatic hydrolysis of PET at ambient temperatures is collapsing the energy cost differential between mechanical and chemical routes, forcing incumbent producers to retrofit facilities or surrender margin in standard denier segments.
Carbios and Samsara Eco deploy engineered enzymes that selectively break ester bonds in mixed-plastic waste streams, achieving virgin-equivalent PET purity without thermal degradation. Activewear brands in Germany and the Netherlands are qualifying these outputs for 2025 collection launches. The technology is rendering obsolete the 180°C melt-phase processing that has dominated mechanical recycling for three decades.
REACH SVHC candidate list expansion to include microplastic shedding from synthetic textiles imposes pre-market safety dossier requirements on all imported yarn above 1 ton annual volume. European converters now demand third-party filtration efficiency testing before contract execution. Italian and Portuguese weavers are consolidating supplier panels to three certified partners to limit compliance audit duplication.
Brand-led pre-competitive consortia are pooling chemical recycling offtake commitments to de-risk capital-intensive plant investments, replacing bilateral negotiations with volume guarantees spanning 5-7 year horizons. This structure transfers feedstock security risk from technology licensors to apparel holding companies with stronger balance sheets. The H&M and Inditex circularity pledges demonstrate the mechanism most visibly in Scandinavian and Iberian sourcing offices.
Recycle Yarn Market Segmentation
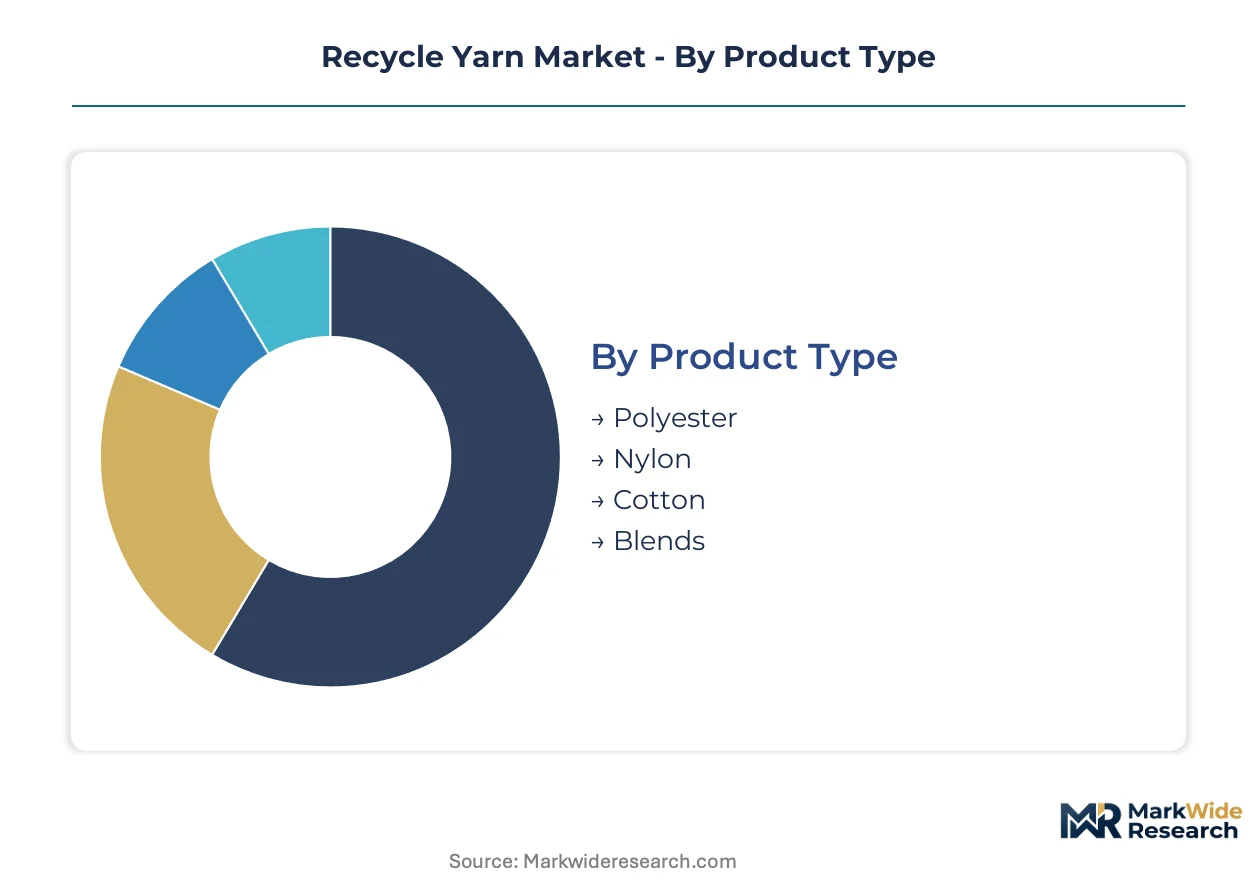
Segmentation in the recycle yarn market reveals how feedstock chemistry, end-use performance requirements, and certification complexity create distinct competitive arenas. Producers must align technical capabilities with specific buyer procurement mandates across fashion, automotive, and industrial verticals.
Product Type:
Use-case spectrum spans commodity apparel at volume scale to engineered fibers demanding molecular-level purity restoration.
- Polyester:Mechanically reconstituted from PET bottle flake, this segment dominates standard denier ranges between 50 and 300 for weaving and knitting. Demand concentrates in Southeast Asia's integrated spinning clusters where Vietnam and Indonesia producers leverage municipal bottle deposit contracts for feedstock security.
- Nylon:Chemically depolymerized through proprietary platforms yielding virgin-equivalent purity for automotive floor mats and luxury fashion. Toray Industries and Aquafil S.p.A. anchor production in Japan and Italy respectively, capturing premium pricing tiers above mechanical routes.
- Cotton:Mechanically shredded post-consumer textile waste with staple length degradation limiting high-twist ring-spun applications. European fashion brands specify this fiber for transparency marketing despite performance constraints.
- Blends:Polyester-cotton and nylon-wool combinations balancing cost and performance for mid-market upholstery and workwear applications.
The dominant share belongs to Polyester, while Nylon is closing the gap fastest through automotive OEM specification expansion.
Application:
Cost tier separation distinguishes mass-market commodity buyers from specification-driven industrial purchasers.
- Textiles:Apparel and home fabric production consuming mechanically recycled polyester at scale. H&M and Inditex circularity pledges in Sweden and Spain are pooling offtake commitments to de-risk chemical recycling plant investments.
- Carpets:Nylon 6 recovery from post-consumer carpet waste through Aquafil's ECONYL regeneration process. This application commands the highest recycled content premiums in the entire market.
- Upholstery:Furniture and commercial seating fabrics requiring flame-retardant compliance alongside recycled content credentials.
- Industrial:Geotextiles, filtration media, and reinforcement fibers where performance specifications override sustainability marketing.
Textiles holds the volume lead, though Carpet applications maintain the steepest expansion trajectory through closed-loop collection infrastructure buildout.
End User:
Customer type fragmentation separates brand-led sustainability marketing from specification-engineered procurement.
- Fashion Industry:Apparel brands mandating recycled fiber minimums under EU Green Deal extended producer responsibility. Procurement teams compress supplier qualification timelines from 18 months to 6 months to meet compliance deadlines.
- Home Décor:Retailers and contract furnishers seeking GRS-certified yarn for private label collections.
- Automotive:OEMs specifying ECONYL and comparable regenerated nylons for interior components, opening premium pricing tiers above fashion applications.
- Footwear:Athletic and lifestyle brands integrating recycled polyester uppers and laces with blockchain-enabled provenance verification.
Fashion Industry commands the dominant position, while Automotive is gaining share fastest through tier-1 supplier integration mandates.
Distribution Channel:
Supply concentration patterns determine which intermediaries capture margin between producer and converter.
- Online Retail:Direct-to-brand platforms enabling small-batch sampling and rapid qualification for sustainable fashion startups.
- Wholesale:Traditional yarn merchants consolidating volumes across multiple mills for European and North American weaving houses.
- Direct Sales:Long-term offtake agreements between major producers and holding companies, transferring feedstock security risk to apparel balance sheets.
- Others:Agent-mediated transactions and consignment arrangements for specialty industrial specifications.
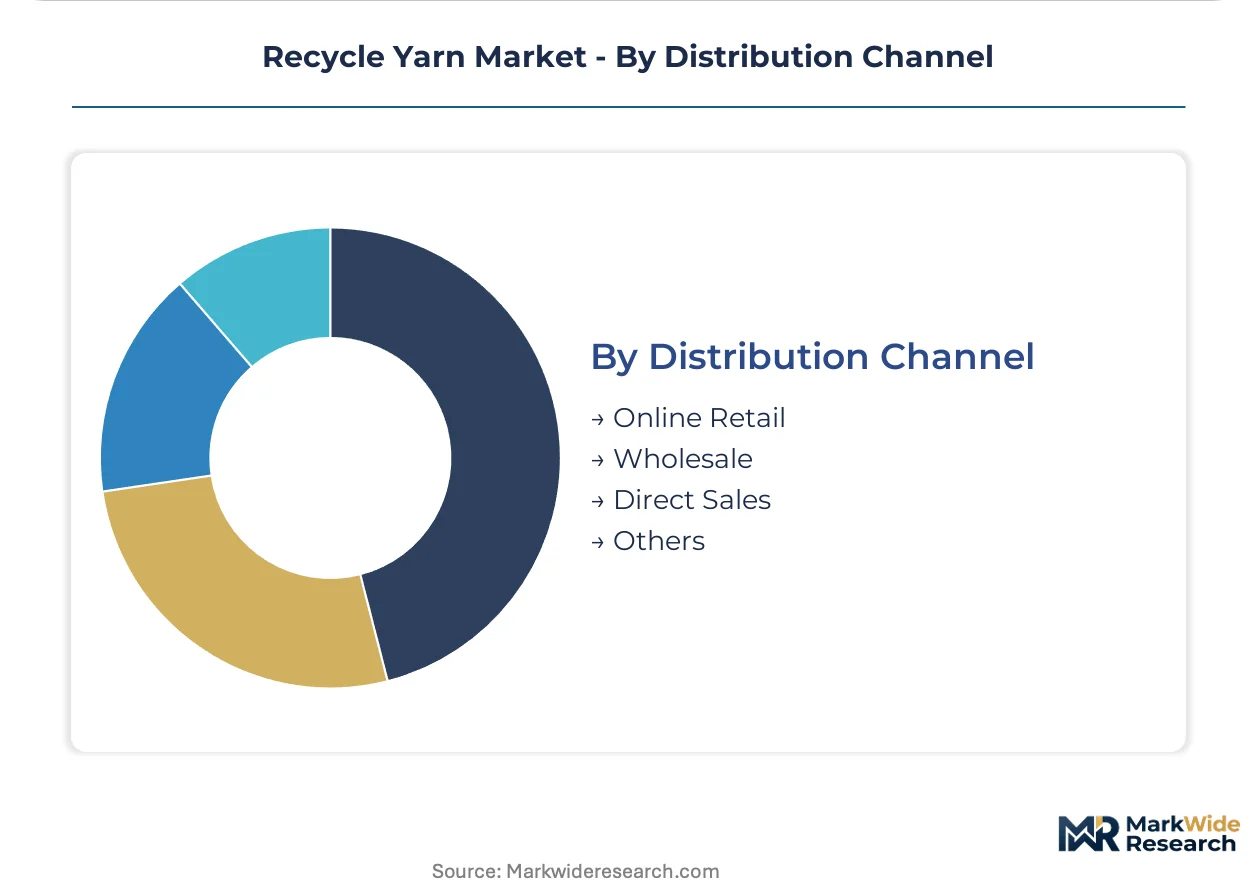
Direct Sales dominates value capture, while Online Retail is expanding most quickly through digital traceability platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical recycling capacity clusters in Southeast Asian free-trade zones, while European converters consolidate supplier panels to limit compliance audit duplication under REACH SVHC expansion.
Vietnam
Integrated spinning mills in Binh Duong and Dong Nai provinces scale mechanical recycling lines to serve H&M and Inditex circularity pledges. The country's Ministry of Industry and Trade incentivizes textile waste collection infrastructure through preferential land leases. Ho Chi Minh City anchors the largest bottle-to-yarn cluster, where municipal PET deposit contracts secure feedstock for Indorama Ventures' backward integration.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify ECONYL-grade regenerated nylon for interior components, opening premium pricing tiers above fashion applications. The national packaging act strengthens deposit-return schemes generating high-purity PET input streams. The Stuttgart industrial corridor concentrates chemical recycling pilot plants testing enzymatic hydrolysis at ambient temperatures.
United States
Unifi Manufacturing's Repreve traceability system captures North American apparel supply chain demand from activewear brands in Oregon and Colorado. The EPA and California's extended producer responsibility proposals force import compliance adjustments for Asian yarn suppliers. The Carolinas textile belt revives shuttered mill infrastructure for mechanically recycled polyester production.
Italy
Luxury fashion houses in Milan and Florence mandate GRS-certified recycled cotton for transparency marketing despite mechanical processing constraints. ECHA's REACH SVHC candidate list expansion imposes pre-market safety dossier requirements on imported yarn above 1 ton annual volume. The Prato textile district specializes in post-industrial wool recovery from garment factory cutting scraps.
Japan
Toray Industries sustains leadership in chemically recycled nylon through proprietary depolymerization platforms serving automotive and electronics sectors. METI's green transformation bonds subsidize chemical recycling yield improvements at the Nagoya production complex. Osaka-based converters consolidate procurement around ISO-traceable chemically recycled yarn to satisfy CSRD-aligned customer requirements.
Recycle Yarn Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying purified intermediates. The vendor base organizes around three strategic archetypes: PET resin majors leveraging backward integration into bottle-to-yarn circuits, specialty chemical houses licensing depolymerization technology, and mechanical recyclers competing on traceability certification. Dominant competitive moves include capacity expansion in Vietnamese and Indonesian free-trade zones and strategic partnerships pooling offtake commitments across 5-7 year horizons.
Among Asia-Pacific-based conglomerates, Indorama Ventures Public Company Limited and Far Eastern New Century Corporation anchor the resin-to-yarn integration tier. Toray Industries, Inc. occupies a position exemplifying specialty chemical leadership in regenerated nylon. Unifi Manufacturing, Inc. and Aquafil S.p.A. represent the traceability-premium archetype, with the latter sitting within Italian industrial textile networks.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Eastman Chemical Company |
| Indorama Ventures Public Company Limited |
| Haili Group |
| Teijin Limited |
| Unifi Manufacturing, Inc. |
| Aquafil S.p.A. |
| Martex Fiber |
| Far Eastern New Century Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European chemical recycling facilities tilts supplier behavior toward long-term offtake negotiations and compresses spot-market availability for premium-certified yarn. This utilization dynamic rewards backward-integrated PET resin producers with captive feedstock while squeezing independent mechanical recyclers on margin.
Pricing Analysis
EU Green Deal extended producer responsibility dictates the pricing tier structure across the recycle yarn market. Three-tier pricing structure across premium, standard, and economy levels separates chemically recycled nylon with automotive OEM validation from mechanically recycled polyester for commodity apparel and un-certified cotton blends for transparency marketing. Cost compression in standard denier mechanical polyester is intensifying because enzymatic hydrolysis pilots threaten incumbent melt-phase processors. Fashion procurement teams show highest price sensitivity, while automotive tier-1 suppliers absorb premiums for ECONYL-grade regenerated nylon with traceability documentation.
Supply Chain Analysis
Extended payment terms from Inditex and H&M sourcing offices force Vietnamese and Indonesian spinners to rely on supply-chain finance facilities for working capital. Feedstock security draws from municipal PET deposit contracts in Germany and California, purified terephthalic acid precursors tracking energy markets, and post-industrial cutting scraps from Bangladesh garment factories. Single-region logistics vulnerability concentrates in Southeast Asian free-trade zones where sixty percent of new chemical recycling capacity clusters. Distribution runs through direct sales agreements transferring feedstock security risk to apparel holding company balance sheets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recycle yarn market sits in early-cycle expansion as EU Green Deal mandates force brand procurement teams to compress supplier qualification timelines and secure certified offtake ahead of compliance deadlines.
For Market Incumbents: Build feedstock moats through long-term municipal PET deposit contracts in Germany, California, and Japan to lock in high-purity input streams before enzymatic hydrolysis platforms achieve scale. Anchor capacity in Vietnamese free-trade zones to capture preferential land leases from the Ministry of Industry and Trade. Defend against Carbios and Samsara Eco enzyme-based disruption by retrofitting mechanical lines for ambient-temperature processing or surrendering standard denier segments. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification gap where domestic mechanical recyclers lack standardized fiber grading protocols. Target unexploited post-industrial textile waste streams from Turkey and Bangladesh garment factories offering zero collection cost and predictable polyester-cotton blends. Go-to-market through blockchain-enabled provenance platforms like TextileGenesis qualifying outputs for European luxury supply chains under CSRD disclosure requirements. For Investors and Strategic Acquirers: Long-term, this sits as a platform-integrated feedstock security play because brand-led pre-competitive consortia pool chemical recycling offtake commitments across five-to-seven year horizons, transferring capital risk from technology licensors to apparel balance sheets. Target specialty chemical houses with proprietary depolymerization platforms and reactor optimization capabilities concentrated among polymer chemistry PhDs. Watch enzymatic hydrolysis yield improvements at pilot scale as the inflection signal determining whether mechanical or chemical routes capture standard denier segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | Indorama Ventures anchors bottle-to-yarn circuits through captive feedstock from municipal deposit contracts. |
| Enzymatic Hydrolysis Scale-Up | Carbios and Samsara Eco ambient-temperature platforms threaten to collapse energy cost differentials against mechanical routes. |
| Blockchain Provenance Deployment | TextileGenesis verification enables premium positioning in European luxury supply chains under intensifying CSRD requirements. |
| Long-Term Offtake Consortium | H&M and Inditex circularity pledges pool commitments to de-risk capital-intensive chemical recycling plant investments. |
| Automotive OEM Specification Capture | Toray Industries and Aquafil S.p.A. command premium tiers above fashion through ECONYL-grade regenerated nylon for floor mats and trunk liners. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from publicly traded resin producers, EU ECHA REACH registration databases, and municipal waste management authority reports. Primary interviews engaged spinning mill operations directors, brand sustainability procurement leads, chemical recycling plant engineers, and automotive tier-1 supplier quality managers. Bottom-up capacity and utilization estimates triangulated against top-down demand projections from apparel production databases and OEM interior component specifications.
Forecast inputs span feedstock availability trajectories from deposit-return scheme expansion, chemical recycling yield improvement curves, and regulatory enforcement timelines under EU Green Deal extended producer responsibility. Segmentation dimensions modeled include fiber chemistry, end-use performance tier, certification grade, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand curves reflecting substitution patterns between mechanical and chemical routes across the projection horizon. Industry-specific inputs incorporate enzymatic hydrolysis technology maturation and blockchain traceability platform adoption rates.
Sensitivities concentrate around feedstock security disruptions, regulatory enforcement variance across EU member states, and enzymatic hydrolysis cost parity achievement. Forecasts reflect assumptions on chemical recycling capital intensity ratios and mechanical shredding yield plateaus. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market