
 Automotive Seat Cover and Interior Textile Recycling in Europe Market | 2026-2036
Automotive Seat Cover and Interior Textile Recycling in Europe Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Cover and Interior Textile Recycling in Europe Market Insights
REACH is restructuring compliance obligations for recycled textile inputs across European supply chains. Autoneum leverages its acoustic textile expertise to develop closed-loop recovery systems for automotive interiors. Trèves Group anchors its competitive position through vertically integrated fiber-to-fabric operations serving premium OEMs. FORVIA differentiates by controlling proprietary chemical recycling pathways for polyamide seat cover materials.
Automotive seat cover and interior textile recycling encompasses the recovery and reprocessing of woven, knitted, and non-woven fabrics from end-of-life vehicle cabins, typically involving fiber separation, depolymerization, or melt re-extrusion to achieve virgin-equivalent tensile properties. The primary purpose is to reintegrate recovered polymers into new automotive interior components, reducing petroleum-derived raw material dependence. Polyester dominates material type volumes due to its prevalence in seat cover and headliner applications, though chemical recycling technology commands the fastest expansion trajectory as mechanical methods struggle with blended fiber complexity. Component manufacturers represent the most concentrated end user segment, capturing margin pools through long-term supply agreements with OEMs implementing circularity targets.
EMA, ECHA, and the EU Green Deal collectively establish the regulatory architecture governing recycled content verification, chemical safety in reprocessed fibers, and extended producer responsibility obligations across member states. ECHA's SVHC screening requirements directly shape which recycled textile streams achieve market access for automotive interior applications. Stakeholders must monitor evolving EU-wide end-of-life vehicle directive revisions and assess chemical recycling scale-up economics against mechanical alternatives.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing automotive OEMs to restructure supply chains around verified recycled content quotas, compressing the timeline for chemical recycling scale-up across European manufacturing corridors.
Growth Catalysts
- REACH compliance restructuring:ECHA's evolving SVHC screening requirements for reprocessed fibers are creating certified market access pathways for automotive interior applications that mechanical recycling cannot satisfy.
- Premium OEM circularity targets:German luxury vehicle manufacturers are embedding post-consumer textile recovery clauses into multi-year supplier agreements, locking in demand for chemically recycled polyamide streams.
- Chemical recycling infrastructure:Depolymerization technologies achieving virgin-equivalent tensile properties are expanding capacity along the Rhine-Ruhr industrial belt.
Market Restraints
- Feedstock cost volatility:End-of-life vehicle collection rates fluctuate with scrap metal prices, destabilizing the post-consumer textile input economics for recyclers dependent on shredded automotive cabin residue.
- Blended fiber separation limits:Mechanical methods fail on polyester-polyamide-elastane combinations common in premium seat covers, forcing reliance on nascent chemical processes with higher unit economics.
- Extended producer responsibility fragmentation:Divergent national implementations of EU-wide end-of-life vehicle directives across member states create compliance multiplicity for pan-European suppliers.
Strategic Opportunities
- CSRD disclosure mandates:The EU Corporate Sustainability Reporting Directive's scope expansion to supply chain emissions is creating first-mover advantage for recyclers offering auditable recycled content certificates to tier-one component manufacturers.
- Eastern European manufacturing expansion:Poland and Czechia's growing automotive assembly capacity presents underdeveloped collection infrastructure for establishing integrated fiber-to-fabric operations.
- Acoustic textile recovery:Non-woven headliner and insulation materials represent an emerging application stream with less fiber complexity than woven seat covers, enabling faster mechanical recycling pathways.
Industry Challenges
- Chemical process engineering talent scarcity:Depolymerization reactor operation and catalyst optimization require specialized skill sets concentrated in petrochemical sectors, creating recruitment friction for textile recyclers scaling operations.
- Multi-site certification timelines:ECHA's substance of very high concern testing protocols impose 12-18 month validation cycles for each recycled fiber variant, delaying product launches.
- Legacy ERP integration:Mass balance accounting for chemically recycled content requires traceability system overhauls that conflict with existing automotive supplier quality management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Cover and Interior Textile Recycling in Europe Market |
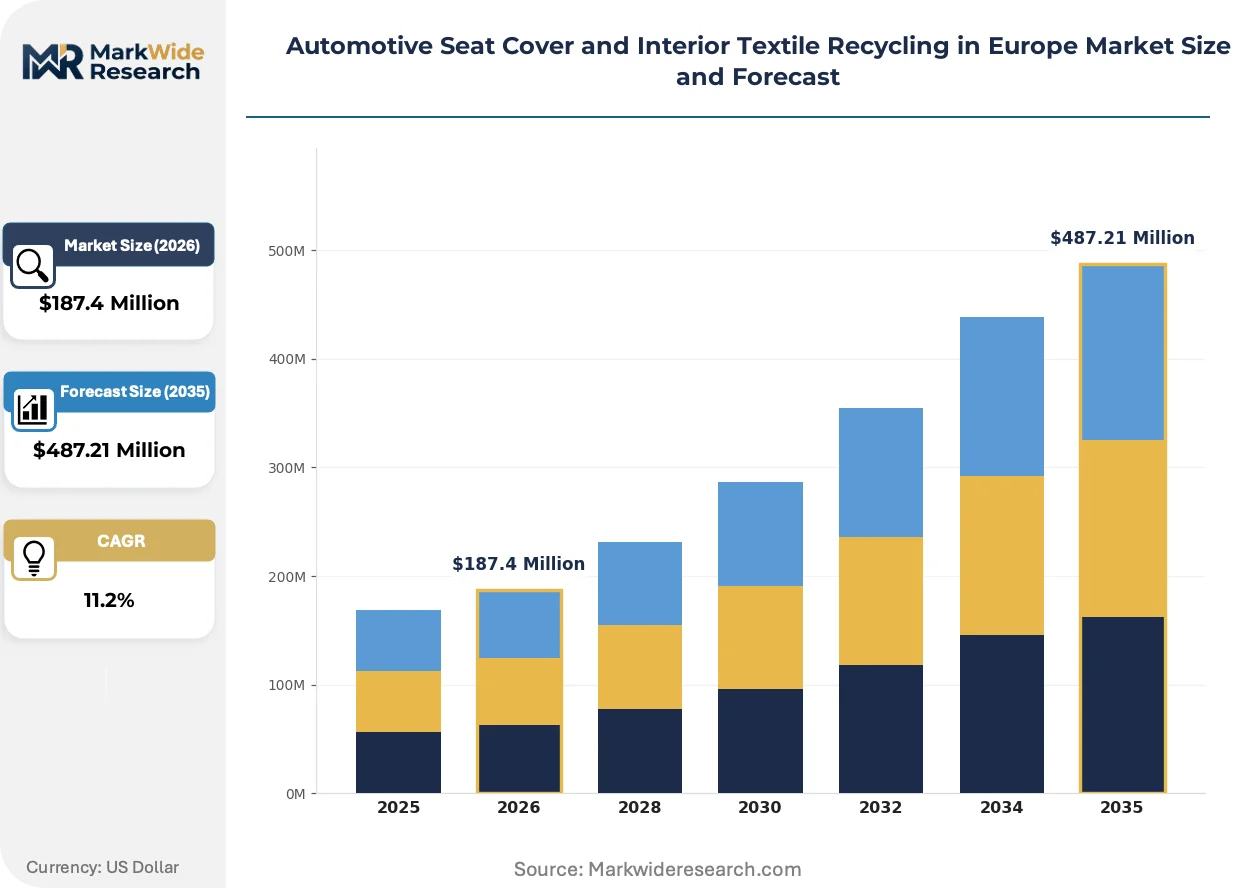
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Nylon, Cotton, Acrylic, Wool, Blends Recycling Technology: Mechanical, Chemical, Thermal, Enzymatic, Cryogenic, Electrochemical End User: Component Manufacturers, Upholstery Specialists, Automotive Refurbishers, Rental Fleets Application: Seat Covers, Door Panels, Headliners, Floor Mats, Dashboard Covers, Trunk Liners |
| Companies Covered | Autoneum, Trèves Group, Grupo Antolin, Adler Pelzer Group, Lear Corporation, FORVIA, Sage Automotive Interiors, Adient, Johnson Controls International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Cover and Interior Textile Recycling in Europe Market Trends and Innovations
Enzymatic hydrolysis processes are rewriting competitive boundaries in European automotive textile recycling, enabling selective polymer breakdown at lower temperatures than thermal depolymerization. Three convergent developments are compressing technology adoption cycles and reshaping supplier qualification protocols.
Depolymerization catalysts targeting mixed polyamide streams are rewriting the economics of premium seat cover recovery. Tier-one component manufacturers in Stuttgart and Munich are qualifying these inputs for 2027 model year interiors. The technology is compressing the cost gap between virgin and recycled polyamide to under fifteen percent at commercial scale.
REACH authorization requirements for legacy flame retardants in automotive textiles are forcing reformulation of reprocessed fiber streams. ECHA's 2024 SVHC candidate list expansion directly affects headliner and seat cover materials containing halogenated compounds. German and French OEMs are accelerating supplier audits to exclude non-compliant recycled inputs from new vehicle programs.
Component manufacturers are consolidating procurement around long-term offtake agreements with certified recyclers, displacing spot-market purchasing for interior textile inputs. This contractual shift is concentrating volume commitments among suppliers with verified mass balance systems. The transformation is most visible in Bavaria's automotive supplier corridor, where circularity scorecards now determine sourcing decisions.
Automotive Seat Cover and Interior Textile Recycling in Europe Market Segmentation
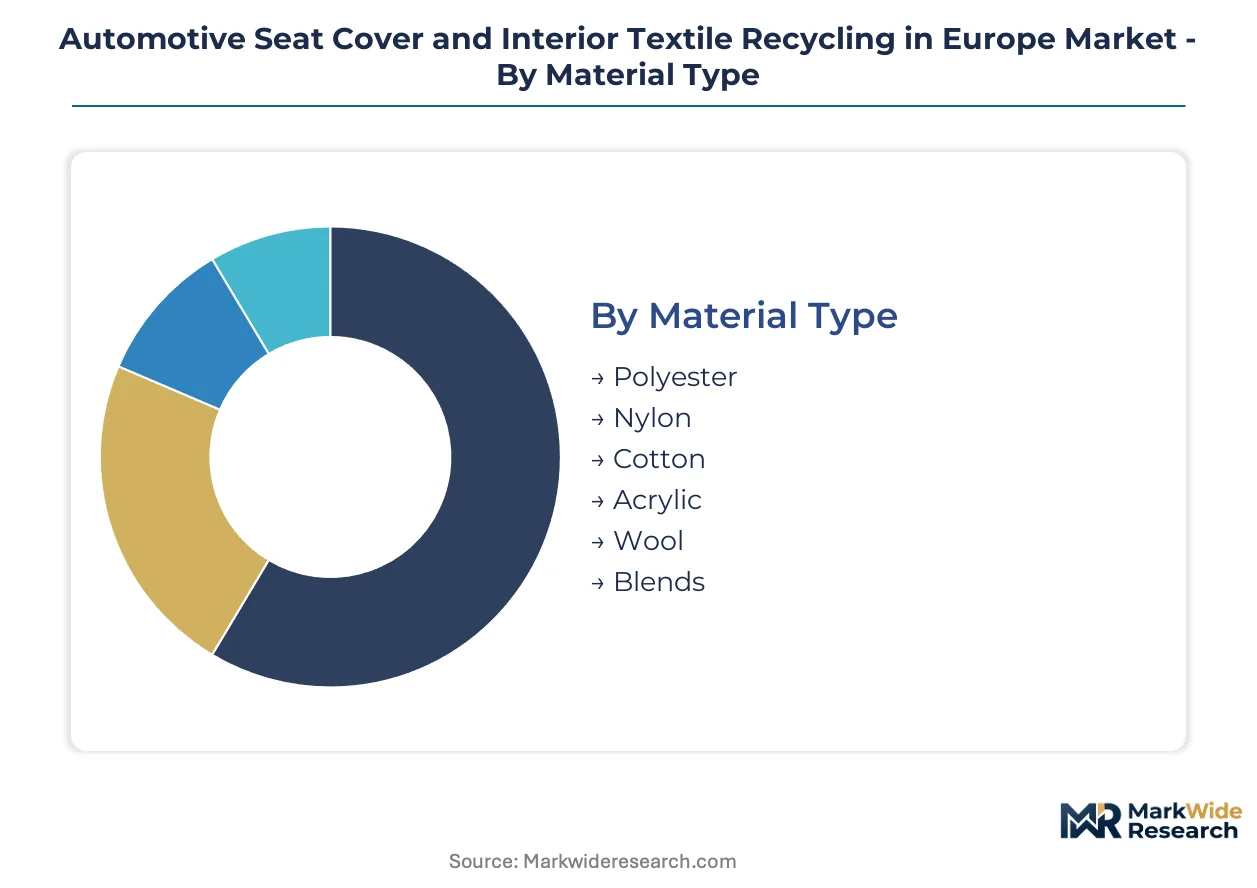
Material composition and recycling technology selection determine compliance pathways and margin structures for European automotive textile recyclers. Component manufacturers structure procurement around certified fiber streams that satisfy OEM circularity mandates while managing ECHA screening costs.
Material Type:
Replacement cycles for interior textiles vary dramatically by fiber chemistry, with synthetic polymers offering longer service intervals but presenting complex end-of-life separation challenges.
- Polyester:Dominates seat cover and headliner applications through polyethylene terephthalate variants optimized for abrasion resistance and dye retention. German OEMs in Stuttgart and Munich specify recycled PET streams for 2027 model year interiors, locking in volume commitments through multi-year supply agreements.
- Nylon:Polyamide 6 and 6,6 variants deliver superior tensile strength for premium seat cover applications requiring elastomeric recovery. Chemical depolymerization capacity along the Rhine-Ruhr corridor is scaling specifically to address polyamide waste streams that mechanical methods cannot process.
- Cotton:Limited to luxury vehicle applications where natural fiber aesthetics command specification premiums.
- Acrylic:Found in sun-exposed components requiring UV stability; recycling infrastructure remains underdeveloped.
- Wool:Restricted to ultra-premium segments with minimal recovery volumes.
- Blends:Polyester-polyamide-elastane combinations common in sport seating configurations create the most acute separation challenges for European recyclers.
Polyester sits at the top of the volume ranking, with nylon climbing the fastest as chemical recycling economics improve.
Recycling Technology:
Technology selection directly determines which fiber streams achieve market access under REACH authorization protocols.
- Mechanical:Shredding and melt re-extrusion processes handle single-fiber waste streams with established cost structures. Bavarian component manufacturers favor mechanical pathways for acoustic non-woven applications where fiber length preservation matters less than for woven seat covers.
- Chemical:Depolymerization and repolymerization achieve virgin-equivalent tensile properties for polyamide recovery. French and German OEMs are qualifying chemically recycled inputs for premium interior programs ahead of EU Green Deal recycled content mandates.
- Thermal:Pyrolysis-based approaches handle contaminated automotive textiles with limited preprocessing requirements.
- Enzymatic:Selective polymer breakdown at lower temperatures than thermal methods; catalyst development is concentrated in Dutch and Belgian research clusters.
- Cryogenic:Brittle fracture separation for multi-layer composites; niche application in dashboard cover recovery.
- Electrochemical:Emerging pathway for conductive textile fractions in next-generation vehicle interiors.
Chemical processes command the steepest expansion trajectory, though mechanical methods retain volume leadership for less complex fiber streams.
End User:
Customer type determines certification requirements and contract structures across the value chain.
- Component Manufacturers:Tier-one suppliers in Germany's automotive corridor consolidate procurement around long-term offtake agreements with verified mass balance systems. Circularity scorecards now determine sourcing decisions for seat cover and headliner programs.
- Upholstery Specialists:Aftermarket refinishers in Poland and Czechia represent fragmented demand with spot-market purchasing patterns.
- Automotive Refurbishers:End-of-life vehicle processors in France and Italy generate feedstock volumes but lack downstream fiber separation capabilities.
- Rental Fleets:Corporate fleet operators in the Netherlands and Scandinavia are piloting closed-loop textile recovery for high-turnover vehicle pools.
Component manufacturers capture the dominant procurement volume, with rental fleets gaining share fastest as circular service models expand.
Application:
Component function dictates fiber performance requirements and recycling pathway feasibility.
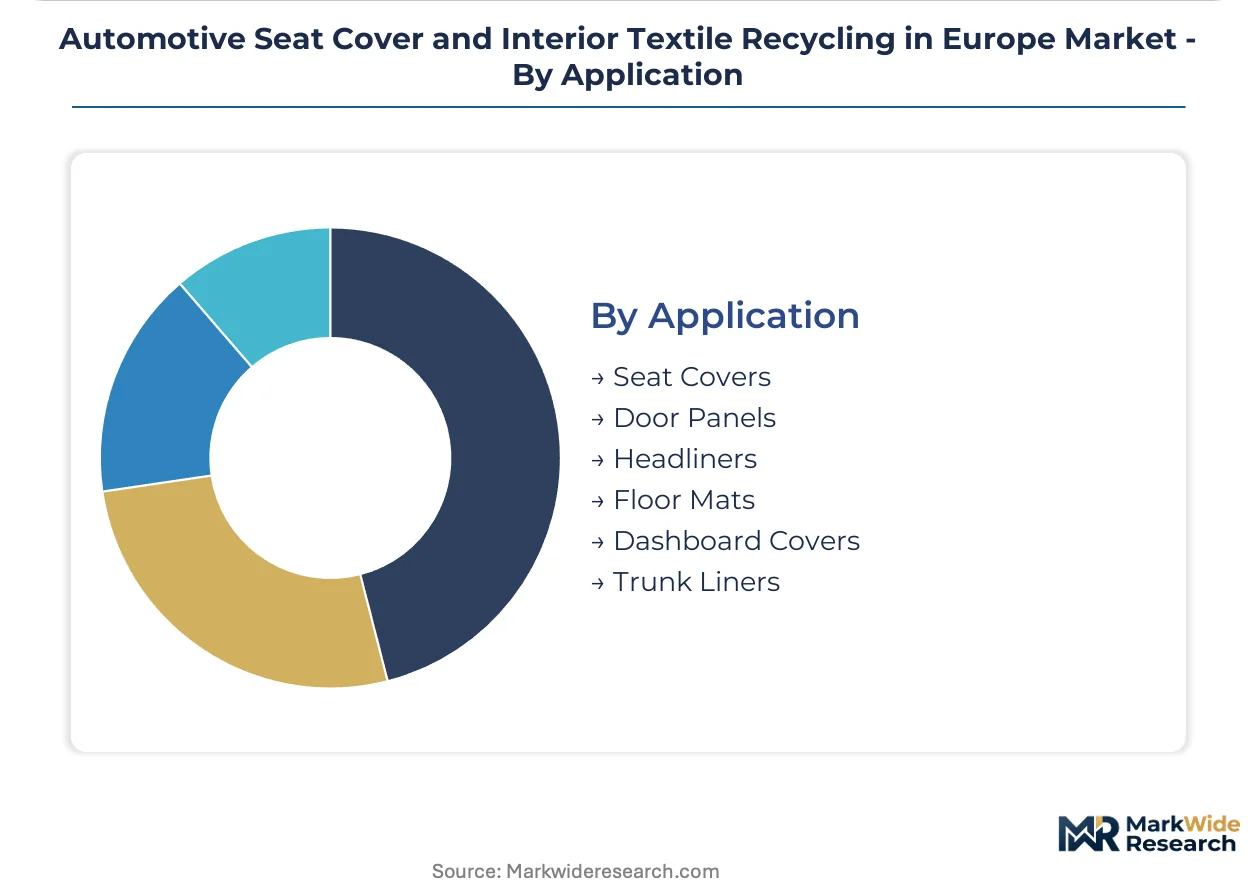
- Seat Covers:Woven and knitted fabrics face the most stringent durability specifications, with polyester and polyamide blends requiring chemical separation. German luxury OEMs are embedding post-consumer recovery clauses specifically for seat cover streams.
- Door Panels:Lower mechanical stress permits broader acceptance of mechanically recycled inputs with modest tensile property degradation.
- Headliners:Non-woven acoustic textiles present simpler fiber compositions than woven seat covers, enabling faster mechanical recycling scale-up in Eastern European manufacturing zones.
- Floor Mats:Heavy contamination limits recovery economics for this application stream.
- Dashboard Covers:Multi-layer constructions with foam backing create separation complexity that thermal methods address.
- Trunk Liners:Cargo area textiles tolerate lower-grade recycled inputs, opening margin-sensitive volume opportunities.
Seat covers lead application volumes, with headliners expanding most quickly as acoustic textile recovery infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive textile recovery systems through Stuttgart's early adoption of closed-loop seat cover programs in the 2010s. This heritage established the technical protocols now diffusing across European manufacturing corridors. The regulatory architecture of REACH and the EU Green Deal now binds national implementations into a coherent continental framework.
Germany
Bavarian luxury OEMs mandate post-consumer textile recovery clauses in multi-year supplier contracts. ECHA's SVHC screening requirements for reprocessed fibers create certified market access pathways that Stuttgart-based component manufacturers exploit. The Rhine-Ruhr industrial belt hosts expanding chemical depolymerization capacity targeting polyamide waste streams from premium vehicle interiors.
France
Paris-headquartered OEMs accelerate supplier audits to exclude non-compliant recycled inputs under REACH authorization protocols. The EU Green Deal's circular economy mandates compress timelines for chemical recycling scale-up across French manufacturing zones. Lyon-based research clusters concentrate enzymatic hydrolysis development for selective polymer breakdown at reduced temperatures.
Italy
Turin automotive suppliers face fragmented extended producer responsibility implementations across member states. EMA guidance on recycled content verification shapes procurement decisions for component manufacturers serving premium interior programs. The Emilia-Romagna manufacturing corridor develops acoustic textile recovery infrastructure for non-woven headliner applications.
Poland
Warsaw and Poznań assembly plants generate underdeveloped collection infrastructure for integrated fiber-to-fabric operations. CSRD disclosure mandates create first-mover advantage for recyclers offering auditable certificates to tier-one suppliers establishing Eastern European operations. The Silesian automotive zone attracts capacity investments targeting spot-market upholstery demand from fragmented aftermarket refinishers.
Czechia
Mladá Boleslav and Ostrava production hubs concentrate OEM circularity targets into supplier qualification protocols. ECHA's substance testing protocols impose validation cycles that delay product launches for regional recyclers. The Moravian manufacturing belt presents acquisition opportunities for mass balance system providers serving pan-European component manufacturers.
Automotive Seat Cover and Interior Textile Recycling in Europe Market Competitive Landscape
The competitive structure tilts toward integrated component manufacturers with captive chemical recycling pathways. Tier-one suppliers consolidate procurement around long-term offtake agreements, displacing spot-market purchasing for interior textile inputs. Three archetypes dominate: acoustic specialists leveraging textile expertise for closed-loop recovery, vertically integrated fiber-to-fabric operators, and diversified automotive suppliers controlling proprietary chemical processing. Capacity expansion along the Rhine-Ruhr corridor and strategic partnerships for mass balance certification represent the dominant competitive moves.
Among diversified automotive suppliers, Lear Corporation and Adient exemplify scale-driven positions serving multiple OEM circularity programs. FORVIA occupies a specialized tier through its control of proprietary chemical recycling pathways. Autoneum and Trèves Group anchor the acoustic textile recovery segment, representing the vertically integrated archetype with in-house fiber separation capabilities. These three company groupings illustrate how competitive positioning stratifies across technology ownership, integration depth, and OEM relationship intensity.
| Leading Market Players |
|---|
| Autoneum |
| Trèves Group |
| Grupo Antolin |
| Adler Pelzer Group |
| Lear Corporation |
| FORVIA |
| Sage Automotive Interiors |
| Adient |
| Johnson Controls International |
| Others |
Pricing and Supply Chain Analysis
Enzymatic hydrolysis scale-up along the Rhine-Ruhr corridor is simultaneously compressing chemical recycling unit economics and concentrating supply relationships around qualified mass balance providers. This dual transformation rewards early movers with ECHA-certified fiber streams while squeezing spot-market recyclers unable to absorb validation costs.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between German component manufacturers and verified recyclers, displacing transactional spot purchasing for interior textile inputs. Price differentiation separates REACH-certified chemical recycling streams from mechanical alternatives, with certification grade and volume scale as primary tiering mechanisms. Cost compression in mechanical recycling is intensifying because blended fiber complexity limits addressable premium seat cover volumes. Aftermarket upholstery specialists in Eastern Europe exhibit the highest price sensitivity, while Bavarian tier-one suppliers prioritize circularity scorecards over unit cost.
Supply Chain Analysis
ECHA's SVHC screening protocols gate market access, creating 12-18 month qualification timelines that tether supply relationships to certified recyclers. Geographic concentration centers on Germany, France, and Poland, with the Rhine-Ruhr belt hosting chemical depolymerization capacity and Eastern European assembly plants generating underdeveloped collection infrastructure. Raw material dependencies draw from post-consumer automotive cabin residue, catalyst supplies for depolymerization reactors, and virgin-equivalent polymer feedstocks for blending. Single-source vulnerability runs through specialized chemical process engineering talent concentrated in petrochemical sectors. Distribution runs through tier-one component manufacturers with direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between established German chemical recycling infrastructure and underdeveloped Polish-Czech collection networks, with CSRD disclosure mandates widening the compliance cost differential.
For Market Incumbents: Cement supply relationships through captive mass balance certification investments ahead of EU Green Deal recycled content mandates. Lock in multi-year offtake agreements with Stuttgart and Munich OEMs before Eastern European capacity matures. Prioritize enzymatic hydrolysis R&D partnerships with Lyon and Dutch research clusters to defend against thermal depolymerization substitutes.
For New Entrants and Emerging Players: The premium-economy pricing gap in acoustic textile recovery presents white-space opportunity in Poland and Czechia's expanding assembly corridors. Target non-woven headliner applications where mechanical recycling pathways face less fiber complexity than woven seat covers. Pursue CSRD-compliant audit infrastructure as a go-to-market wedge to attract tier-one suppliers establishing Eastern European operations.
For Investors and Strategic Acquirers: Valuations sit cheapest among vertically integrated fiber-to-fabric operators with underutilized chemical recycling assets. Long-term viability over the medium-term projection horizon hinges on ECHA certification velocity and OEM circularity clause penetration. Watch for inflection in enzymatic hydrolysis catalyst cost curves as the signal to accelerate deployment capital.
| Strategic Initiative | Industry Significance |
|---|---|
| Mass Balance Certification Investment | ECHA validation protocols compress supply relationships around certified recyclers serving BMW and Mercedes-Benz programs. |
| Enzymatic Hydrolysis Scale-Up | Lower-temperature depolymerization reduces energy costs for polyamide recovery in Rhine-Ruhr chemical parks. |
| Eastern European Collection Infrastructure | Poland and Czechia assembly growth outpaces local recycling capacity, creating integrated fiber-to-fabric acquisition targets. |
| Long-Term Offtake Agreements | Component manufacturers displace spot purchasing through multi-year contracts locking in circularity scorecard compliance. |
| Acoustic Textile Recovery Specialization | Non-woven headliner applications enable faster mechanical recycling pathways with simpler fiber compositions than seat covers. |
Research Methodology
Coverage spans Western and Eastern European automotive manufacturing corridors, with primary inputs from each regional cluster. The approach combines structured interviews with tier-one supplier procurement directors, OEM sustainability officers, chemical recycling plant managers, and ECHA regulatory specialists with secondary validation from EU customs trade data, REACH registration databases, vehicle production registries, and automotive supplier SEC filings. Bottom-up fiber stream volume estimates triangulate against top-down OEM circularity target aggregations.
Granularity-level modeling disaggregates the projection horizon across material type, recycling technology, end-user archetype, and application segment, with additional dimensioning by OEM tier and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to chemical recycling capacity announcements and mechanical recycling yield improvements. Forecast inputs incorporate ECHA SVHC list expansion schedules, EU Green Deal recycled content mandate trajectories, and end-of-life vehicle collection rate sensitivities to scrap metal pricing.
Caveats apply where ECHA authorization delays, feedstock cost volatility, or enzymatic catalyst performance shortfalls could materially shift the outlook. Forecasts reflect assumptions around chemical recycling scale-up economics and OEM circularity clause enforcement intensity. A model refresh is warranted upon material change in EU-wide end-of-life vehicle directive harmonization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
Textile Recycling Market