
 Recycled Fibers Market | 2026-2036
Recycled Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Fibers Market Outlook
Automotive interior applications is expanding as manufacturers replace virgin synthetic padding with recycled polyester and nylon blends. Indorama Ventures leverages its integrated PET recycling network across Southeast Asia and Europe to supply certified automotive-grade fiber. UNIFI, Inc. anchors North American demand through its Repreve brand, which dominates branded recycled polyester supply to apparel and automotive Tier 1 suppliers. Lenzing AG specializes in wood-based cellulosic recycled fibers, competing on biodegradability credentials that petroleum-based recyclers cannot match.
Recycled fibers are reclaimed textile or polymer-based filaments reprocessed through mechanical shredding, chemical depolymerization, or solvent extraction to achieve specified tenacities above 3.5 grams per denier and contaminant thresholds below 0.1% by weight, serving primarily as sustainable feedstock for woven, nonwoven, and composite applications. Polyester recycled from post-consumer PET bottles leads volume due to mature collection infrastructure and lower reprocessing energy versus virgin polymerization, though chemical recycling of blended textiles is capturing margin pools as technology costs decline. Nylon recovery from fishing nets and carpet scrap represents the fastest-growing material type, driven by automotive and industrial demand for high-tenacity engineered fibers.
The EU Green Deal and REACH chemical safety frameworks mandate recycled content thresholds and restrict hazardous substance residues in textile products placed on European markets, directly shaping fiber certification requirements and import access conditions. The US EPA promotes textile waste diversion through sustainable materials management programs, while China's MEE enforces dual carbon goals that pressure domestic mills to source verified recycled inputs. Stakeholders must monitor chemical recycling scale-up economics and evolving extended producer responsibility schemes that will determine which fiber recovery technologies achieve commercial viability.
Market Dynamics
Chemical depolymerization of blended textiles is electrifying capacity investment as EU Green Deal mandates tighten virgin polyester substitution requirements and automotive OEMs specify certified recycled content thresholds.
Growth Catalysts
- EU Green Deal circular economy mandates:Binding recycled content thresholds for textiles placed on European markets are forcing fiber-to-fiber recycling infrastructure buildout near Frankfurt and Antwerp chemical clusters.
- Automotive interior specification shifts:OEM seat padding and carpet programs now require post-consumer recycled nylon and polyester blends with verified chain-of-custody documentation.
- Mechanical shredding cost curves:Mature PET bottle collection networks in Germany and Thailand are compressing feedstock acquisition costs below virgin polymerization economics.
Market Restraints
- Blended textile sorting complexity:Automated near-infrared separation of cotton-polyester and wool-synthetic blends remains technically immature, limiting feedstock quality for chemical recyclers.
- Caprolactam price volatility:Nylon 6 recycled fiber margins compress when virgin caprolactam spot prices drop below threshold levels, eroding chemical recycling project IRRs.
- REACH chemical safety compliance:Legacy textile contaminants including restricted azo dyes and heavy metal residues block circular feedstock access to EU markets without costly detoxification pretreatment.
Strategic Opportunities
- Extended producer responsibility schemes:France's AGEC law and upcoming EU-wide textile EPR frameworks will internalize end-of-life collection costs, advantaging integrated recyclers with captive feedstock access.
- Fishing net and carpet nylon recovery:Aquafil's ECONYL demonstration in Slovenia proves commercial scalability of maritime and flooring waste streams for high-tenacity automotive airbag fiber applications.
- Enzymatic polyester hydrolysis:Convergence of biotech fermentation platforms with textile processing is lowering energy intensity versus thermochemical depolymerization, opening margin capture in blended feedstock segments.
Industry Challenges
- Textile-to-textile certification timelines:GRS and RCS chain-of-custody audits require 6-12 month implementation cycles that delay qualified supplier status for tier-2 mills.
- Chemical recycling capex intensity:Methanolysis and glycolysis plants demand $150-400 million per facility, concentrating investment capacity among petrochemical incumbents with balance sheet depth.
- Polymer contamination detection:Legacy optical sorting equipment misses microfiber fragmentation and elastane blends, causing downstream quality failures in spun yarn production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Fibers Market |
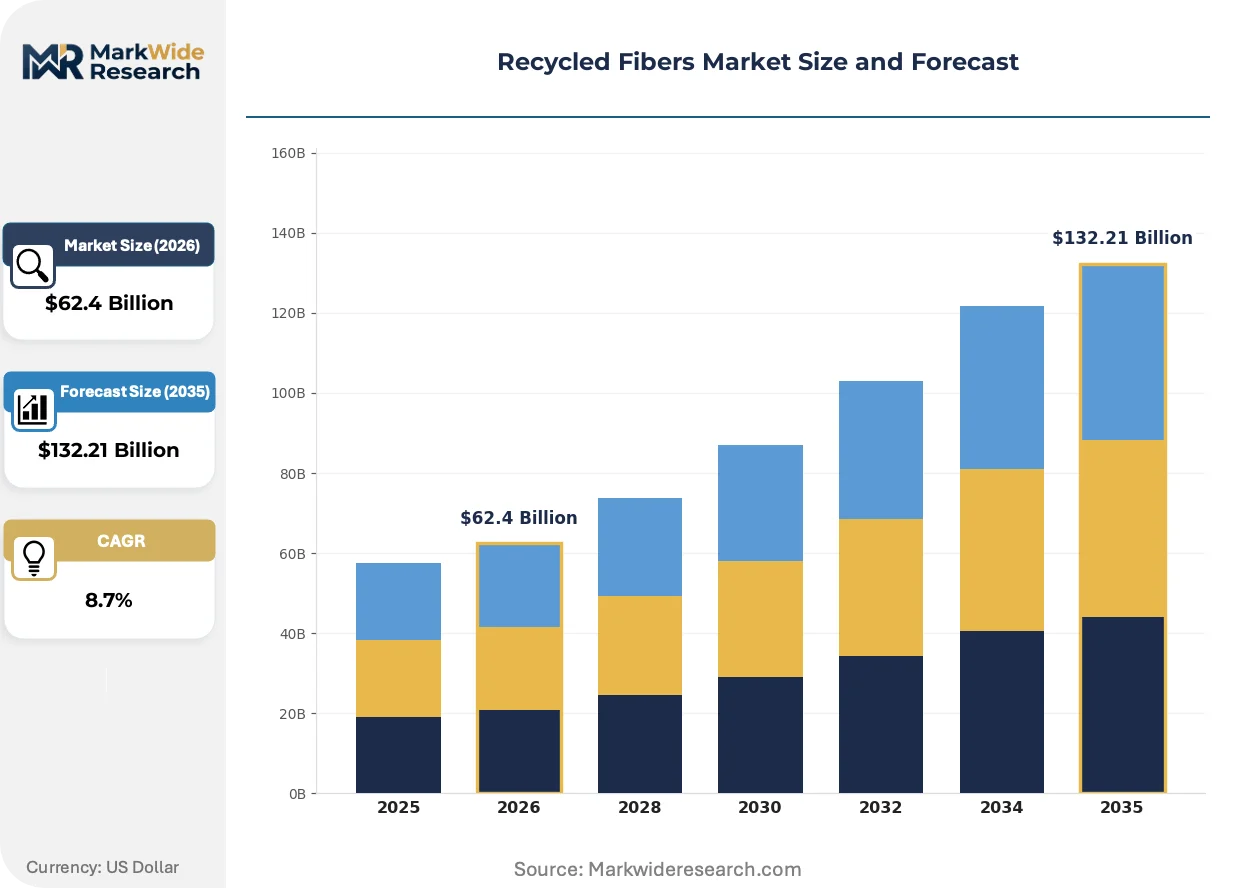
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cotton, Polyester, Nylon, Wool Application: Textiles, Automotive, Construction, Insulation End User: Apparel, Home Furnishing, Industrial, Footwear Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Indorama Ventures Public Company Limited, UNIFI, Inc., Reliance Industries Limited, Lenzing AG, Aquafil S.p.A., Hyosung TNC, Martex Fiber, Infinited Fiber Company, Recover Textile Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Fibers Market Strategic Shifts
Technology convergence across biotechnology, chemical engineering, and automated sorting is compressing the cost gap between mechanical and advanced recycling pathways for complex textile waste streams.
Solvent-based purification of post-consumer polyester is electrifying interest from automotive seating suppliers seeking fiber-to-fiber circularity without the tenacity degradation typical of mechanical reprocessing. Tier 1 suppliers in Germany and Michigan are qualifying purified terephthalate outputs for airbag and seatbelt applications previously reserved for virgin polymer. This technology is compressing the premium that branded recycled fibers command over commodity mechanical grades.
REACH restriction proposals on microplastic release from synthetic textiles are forcing mills to invest in closed-loop water filtration and fiber fragment capture systems ahead of anticipated enforcement timelines. The European Chemicals Agency's 2023-2025 restriction roadmap specifically targets shedding from apparel and home textiles, compelling fiber producers to certify low-shedding yarn constructions. Italian and Portuguese knitwear exporters are responding with surface-modified recycled polyester filament engineered for reduced fragmentation during washing cycles.
Brand-led procurement consortiums are consolidating purchase commitments for certified recycled volumes, displacing fragmented spot-market sourcing that previously dominated textile mill feedstock acquisition. The Fashion Pact and Textile Exchange's Fiber Preferences consortium aggregate demand from 250+ brands, concentrating buying power among recyclers with GRS certification and verified mass-balance documentation. This concentration is most visible in Bangladesh and Vietnam garment manufacturing clusters where mills now require pre-committed offtake agreements to justify recycling line investments.
Recycled Fibers Market Segmentation
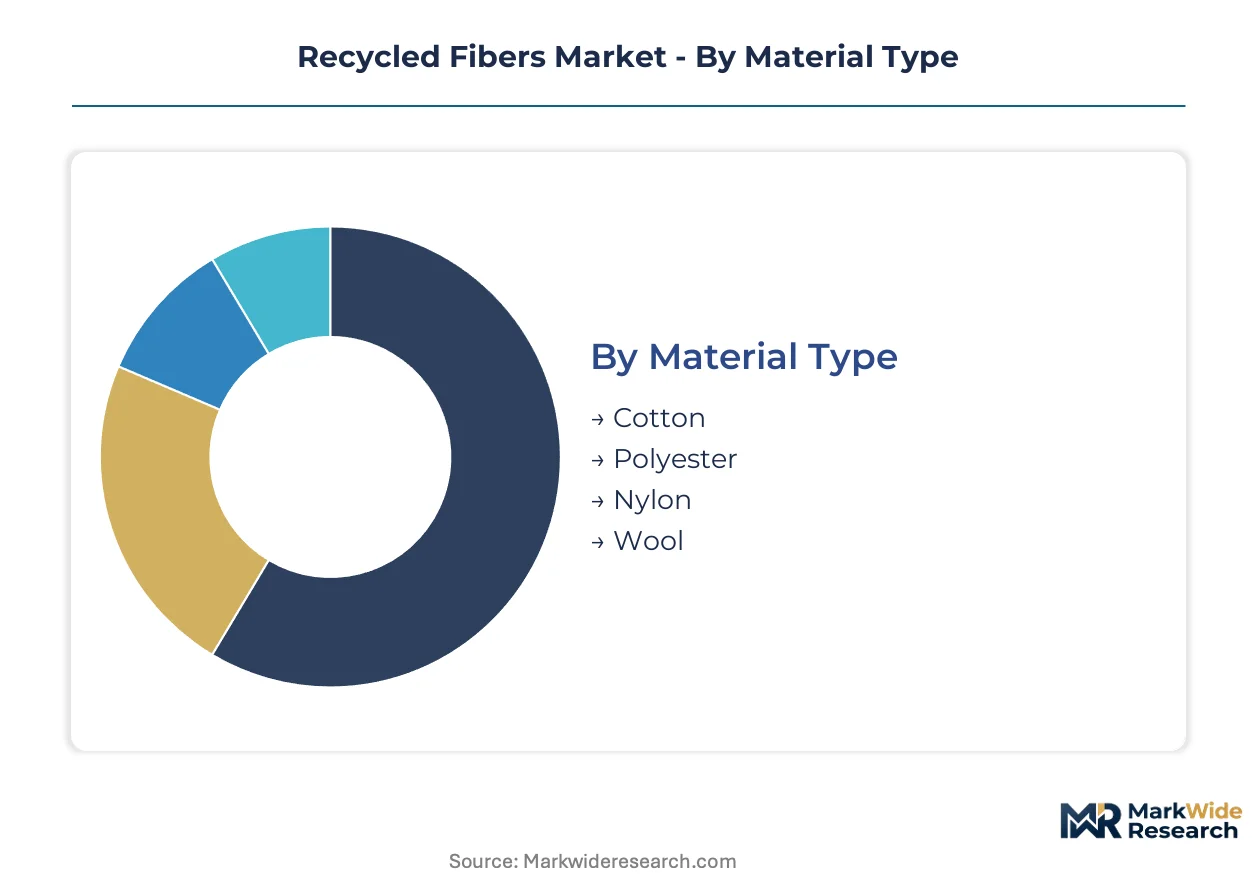
Recycled fiber procurement patterns diverge sharply by material chemistry and end-use performance requirements. Automotive OEMs enforce certified chain-of-custody standards that apparel buyers rarely match, while chemical versus mechanical recycling economics sort segments by price tolerance and technical specification.
Material Type:
Volume concentration favors established polymer recovery, while premium capture shifts toward engineered fiber regeneration.
- Polyester:Post-consumer PET bottle depolymerization yields staple fiber and filament yarn with tenacities matching virgin polymer at 40% lower embodied energy. Demand clusters in German automotive seating programs and Bangladesh garment manufacturing where GRS-certified mass-balance documentation satisfies EU Green Deal import requirements.
- Nylon:Recovered from fishing nets, carpet scrap, and industrial pre-consumer waste through Aquafil's ECONYL chemical regeneration process. High-tenacity specifications for automotive airbag and seatbelt webbing command price premiums over commodity apparel grades, with Slovenia and Italy anchoring European capacity.
- Cotton:Mechanical shredding of pre-consumer textile clips and post-consumer denim generates shortened staple lengths suitable for blended yarn spinning. Lenzing AG's Refibra technology integrates cotton pulp with wood cellulose to extend fiber length for premium knitwear applications.
- Wool:Shearing waste and post-consumer garment recovery through mechanical carbonizing removes vegetable matter for re-spinning into insulation batts and lower-grade apparel. New Zealand and Australian merino processors dominate premium fiber-to-fiber recycling for luxury knitwear.
Mature deployment sits with Polyester. Newer deployment is concentrated in Nylon.
Application:
Specification intensity separates commodity filling from engineered structural applications.
- Automotive:OEM seat padding, carpet backing, and safety webbing now mandate post-consumer recycled content thresholds with third-party verification. Tier 1 suppliers in Michigan and Germany qualify fiber outputs through IMDS material data systems for traceability compliance.
- Textiles:Apparel and home furnishing mills source mechanically recycled polyester staple for blended woven and knit constructions. Fashion Pact consortium members pre-commit volumes to secure GRS-certified supply from Southeast Asian recyclers.
- Construction:Nonwoven geotextiles and concrete reinforcement fibers utilize lower-grade recycled nylon and polyester with relaxed tenacity specifications. German infrastructure projects specify recycled content for public procurement compliance.
- Insulation:Recycled cotton and wool batts serve residential and commercial thermal acoustic applications, competing with synthetic alternatives on biodegradability credentials. REACH chemical safety restrictions on formaldehyde binders favor natural fiber insulation in EU markets.
Price discipline runs tightest in Textiles. Technical qualification barriers peak in Automotive.
End User:
Brand visibility and regulatory exposure determine certification investment willingness.
- Apparel:Fast fashion and premium outdoor brands specify recycled polyester for marketing differentiation and Scope 3 emissions reduction. Patagonia and Adidas anchor North American and European demand through long-term offtake agreements with UNIFI and other certified suppliers.
- Home Furnishing:Upholstery, drapery, and bedding manufacturers source recycled fiber for sustainability labeling without the performance engineering required in transportation applications. IKEA's circular design commitments drive volume concentration in European supply chains.
- Industrial:Filtration media, rope and cordage, and technical textiles demand high-tenacity recycled nylon with lot-traceable quality documentation. Marine and oil-and-gas applications specify recovered fishing net fiber for corrosion resistance in saltwater environments.
- Footwear:Upper materials, laces, and midsole components integrate recycled polyester and nylon for lightweight performance. Nike's Space Hippie and Allbirds product lines demonstrate commercial scalability of recycled fiber integration in athletic and casual segments.
Certification cost absorption works best in Apparel. Specification engineering dominates in Industrial.
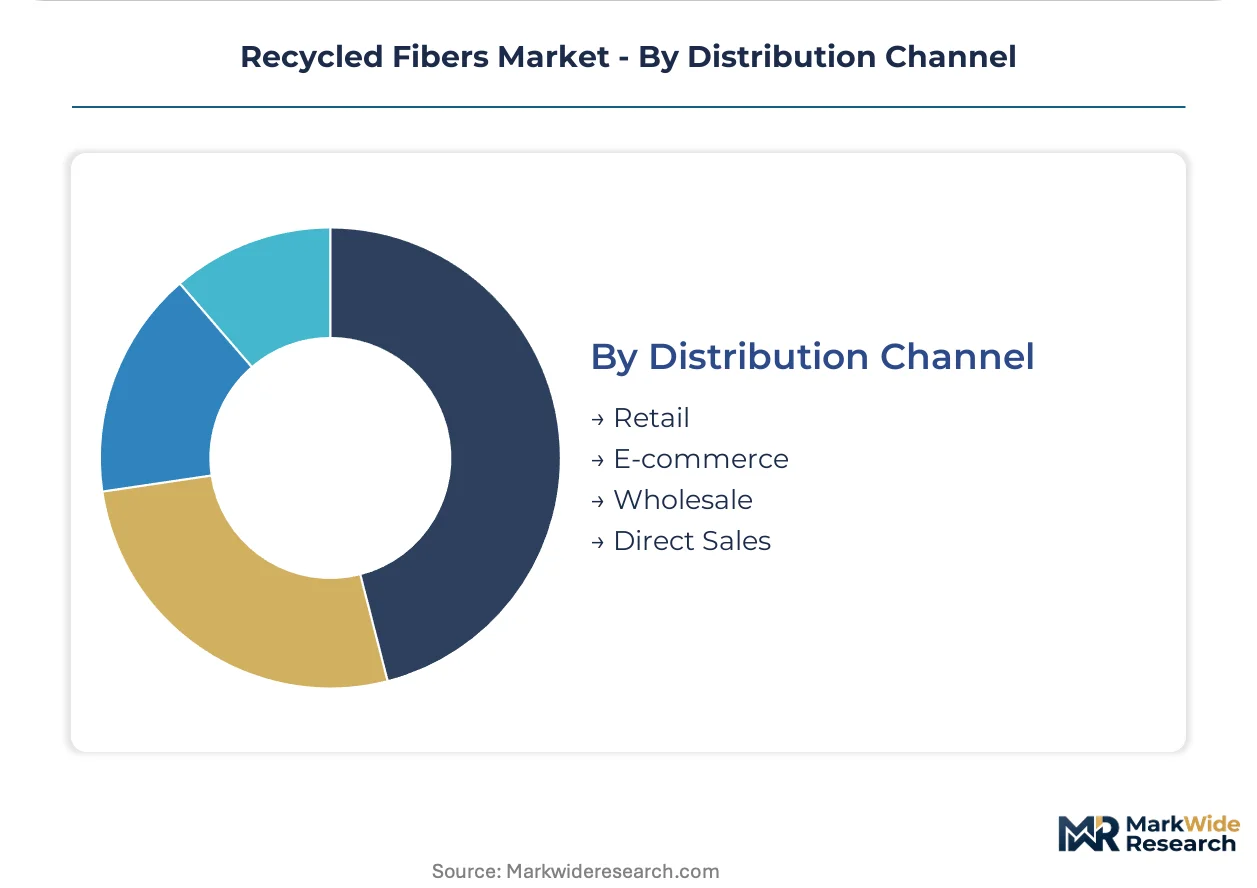
Distribution Channel:
Transaction scale and relationship intensity sort channel selection by buyer sophistication.
- Wholesale:Mill-direct purchasing of fiber bales and tow by integrated textile manufacturers concentrates volume in Bangladesh, Vietnam, and Turkey garment production clusters. Annual contracts with indexed pricing reduce spot market exposure for large-scale spinners.
- Direct Sales:Automotive Tier 1 and OEM buyers negotiate multi-year supply agreements with dedicated recycling capacity and joint technology development clauses. Indorama Ventures and Far Eastern New Century operate direct sales teams for strategic accounts.
- E-commerce:Small-batch specialty fiber sales to independent designers and craft producers operate through Alibaba and regional B2B platforms. Limited quality verification increases contamination risk for buyers lacking incoming inspection capabilities.
- Retail:Consumer-facing recycled fiber products including insulation batts and craft yarn sell through home improvement and specialty stores. Marketing emphasizes sustainability credentials with third-party certification labeling.
Contract discipline concentrates in Wholesale. Relationship investment peaks in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor tax incentives have concentrated PET bottle collection and depolymerization investments near Map Ta Phut, drawing integrated chemical recyclers to the Gulf of Thailand industrial zone.
Germany
Automotive OEMs in Stuttgart and Munich mandate certified recycled nylon for seat padding and airbag webbing. The EU Green Deal's binding recycled content thresholds force fiber-to-fiber infrastructure buildout. Chemical recycling clusters near Frankfurt partner with Indorama Ventures to scale closed-loop polyester production for export markets.
United States
Tier 1 automotive suppliers in Michigan qualify recycled fiber outputs through IMDS material data systems. The EPA's sustainable materials management programs promote textile waste diversion through voluntary corporate commitments. North Carolina's textile belt hosts mechanical recycling operations serving apparel brands with GRS-certified mass-balance documentation.
China
Domestic mills face pressure from MEE dual carbon goals to source verified recycled inputs for export compliance. Yangtze River Delta chemical parks host glycolysis capacity for polyester regeneration. Zhejiang province concentrates mechanical shredding operations serving Bangladesh garment manufacturing clusters.
Italy
Luxury knitwear exporters in Tuscany and Lombardy invest in surface-modified recycled polyester filament engineered for reduced microfiber shedding. ECHA restriction proposals on synthetic textile microplastic release compel closed-loop water filtration upgrades. Aquafil's ECONYL demonstration in Slovenia supplies high-tenacity fiber for Italian automotive Tier 1 suppliers.
India
Gujarat's petrochemical corridor attracts investment in bottle-to-fiber recycling for European export markets. Reliance Industries leverages integrated refining infrastructure to compress reprocessing energy costs below virgin polymerization economics. Tamil Nadu's Tiruppur knitwear cluster sources mechanically recycled cotton blends for fast fashion supply chains.
Recycled Fibers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with certification-holding recyclers commanding premium positioning in automotive and apparel procurement. The vendor base organizes around three strategic archetypes: integrated petrochemical conglomerates with backward collection infrastructure, pure-play mechanical recyclers serving commodity textile markets, and biotechnology ventures commercializing enzymatic depolymerization. Dominant competitive moves include capacity expansion near feedstock clusters and strategic partnerships with automotive OEMs for qualified supplier status.
Among Southeast Asian and European integrated players, Indorama Ventures Public Company Limited and Hyosung TNC represent the petrochemical conglomerate archetype with captive bottle collection networks. UNIFI, Inc. anchors North American branded supply through its Repreve platform, exemplifying the specialist model that aggregates demand from apparel and automotive Tier 1 suppliers. Lenzing AG occupies a distinct position in wood-based cellulosic fiber regeneration, competing on biodegradability credentials that petroleum-based recyclers cannot match.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| UNIFI, Inc. |
| Reliance Industries Limited |
| Lenzing AG |
| Aquafil S.p.A. |
| Hyosung TNC |
| Martex Fiber |
| Infinited Fiber Company |
| Recover Textile Systems |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM mandates for certified recycled content with third-party verification are compressing supplier qualification timelines and forcing recyclers to absorb certification costs upfront, elevating pricing power for GRS-accredited producers with captive feedstock access while spot-market mechanical grades face margin erosion.
Pricing Analysis
Short lead-time premiums for automotive-qualified recycled nylon and polyester separate contract-tier suppliers from commodity spot sellers. Three-tier pricing structure across premium, standard, and economy levels sorts by certification grade and chain-of-custody documentation depth, with Fashion Pact consortium members locking in annual offtake at indexed rates. Cost compression in mechanical PET bottle recycling is intensifying because mature collection infrastructure in Germany and Thailand has compressed feedstock acquisition economics. Apparel spinners in Bangladesh exhibit highest price sensitivity, while automotive Tier 1 suppliers in Michigan and Stuttgart accept premium positioning for IMDS-traceable fiber.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for safety-critical applications like airbag webbing and seatbelt fiber, fragmenting volume concentration among qualified recyclers. Supply concentrates in Thailand, Germany, and China, with Map Ta Phut chemical parks, Frankfurt industrial clusters, and Zhejiang mechanical shredding operations anchoring regional capacity. Raw material dependencies draw from post-consumer PET bottle bales, fishing net recovery networks, and carpet scrap collection streams. Single-source vulnerability persists in chemical recycling catalyst supply and specialized solvent purification systems. Distribution runs through mill-direct wholesale contracts for integrated textile manufacturers and dedicated direct sales teams for strategic automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified recycled fiber capacity is supply-constrained relative to procurement commitments from brand consortiums and automotive OEMs, with chemical recycling plant commissioning timelines creating a 24-36 month bottleneck that props pricing for qualified incumbent suppliers.
For Market Incumbents: Anticipate enzymatic hydrolysis platforms and solvent-based purification technologies disrupting thermochemical recycling economics, and respond by securing backward integration into textile waste collection networks near Frankfurt and Bangkok to defend feedstock access. Prioritize GRS certification maintenance and IMDS database qualification for automotive Tier 1 supplier status retention. For New Entrants and Emerging Players: Enzymatic polyester hydrolysis technology offers a defensible entry wedge into blended textile feedstock segments where mechanical recyclers face quality limitations. Target fishing net and carpet nylon recovery for high-tenacity automotive applications in Slovenia and Italy, where Aquafil's ECONYL demonstration has validated commercial scalability but regional capacity remains concentrated. Pursue joint development agreements with Italian luxury knitwear exporters seeking low-shedding recycled filament. For Investors and Strategic Acquirers: The window for entry favors biotechnology ventures with enzymatic depolymerization platforms and integrated recyclers with captive collection infrastructure in EU chemical clusters. Long-term viability hinges on extended producer responsibility scheme implementation internalizing end-of-life collection costs. Monitor EU-wide textile EPR framework rollout as the inflection indicator for feedstock cost structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Chemical recycling plant buildout near Frankfurt serves EU Green Deal compliance and automotive OEM demand. |
| Backward Integration | Captive PET bottle collection networks in Thailand compress feedstock costs below virgin polymerization economics. |
| Green Manufacturing Transition | Enzymatic hydrolysis adoption lowers energy intensity versus thermochemical depolymerization for blended textiles. |
| Long-term Supply Agreement | Fashion Pact consortium pre-commitments secure volume offtake for GRS-certified Southeast Asian recyclers. |
| Joint Venture | Indorama Ventures partnerships with German chemical clusters scale closed-loop polyester production for export markets. |
Study Parameters
Multi-period observation of chemical recycling capacity investments, EU Green Deal implementation timelines, and automotive OEM specification shifts anchored the trend analysis, supplemented by interviews with recycling plant managers, automotive Tier 1 procurement leads, textile mill technical directors, and brand sustainability officers. Secondary validation drew from customs trade data, ECHA restriction proposal filings, SEC 10-K disclosures by listed recyclers, and Textile Exchange fiber preference reports. Bottom-up fiber demand modeling by application and material type triangulated against top-down market sizing from petrochemical capacity announcements.
Segment-weighting across material chemistry, end-use performance requirements, and geographic production clusters shaped the analytical framework across the analysis window. Modeled dimensions included polyester versus nylon versus cellulosic fiber types, automotive versus apparel versus industrial applications, and mechanical versus chemical versus enzymatic recycling technology pathways. CAGRs were derived from feedstock availability projections, regulatory mandate compliance deadlines, and OEM specification adoption curves. Key inputs incorporated EU EPR scheme rollout assumptions and enzymatic platform commercialization timelines.
Several conditions sit outside the modeled scope, including unannounced REACH restriction amendments, breakthroughs in automated blended textile sorting, and macroeconomic disruptions to virgin polymer pricing. Forecasts reflect assumptions about EPR implementation pace and chemical recycling scale-up economics. Deviation in EU Green Deal enforcement intensity or automotive OEM recycled content threshold adjustments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market