
 United States Textile Recycling Market | 2026-2036
United States Textile Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
United States Textile Recycling Market Intelligence
Automotive interior sourcing is consolidating around recycled textile feedstocks as Detroit-based OEMs rewrite material specifications. Unifi Inc. leverages its Repreve platform to anchor supply relationships with seating and panel suppliers across the Southeast. Parkdale Mills sustains vertical control from fiber recovery to yarn finishing, insulating margin pools from commodity cotton volatility. American Textile Recycling Service competes through dense drop-off network coverage in Texas and California metro corridors.
United States textile recycling encompasses the collection, sorting, and reprocessing of post-industrial and post-consumer textile waste into reusable fiber, yarn, or nonwoven inputs, typically requiring contamination levels below five percent for mechanical routes and polymer purity above ninety-five percent for chemical depolymerization. The practice primarily serves to displace virgin fiber demand in apparel, automotive, and building insulation applications while diverting material from municipal solid waste streams. Cotton dominates volume flows through established mechanical shredding and re-spinning lines, though chemical processing of polyester is gaining traction as fiber-to-fiber recovery yields improve. Mechanical routes still occupy the largest installed base, but margin pools increasingly concentrate in chemical recycling where output quality approaches virgin-grade specification. Collection through drop-off locations and thrift store donations supplies the bulk of feedstock, yet curbside programs in cities like San Francisco and New York are expanding addressable volume.
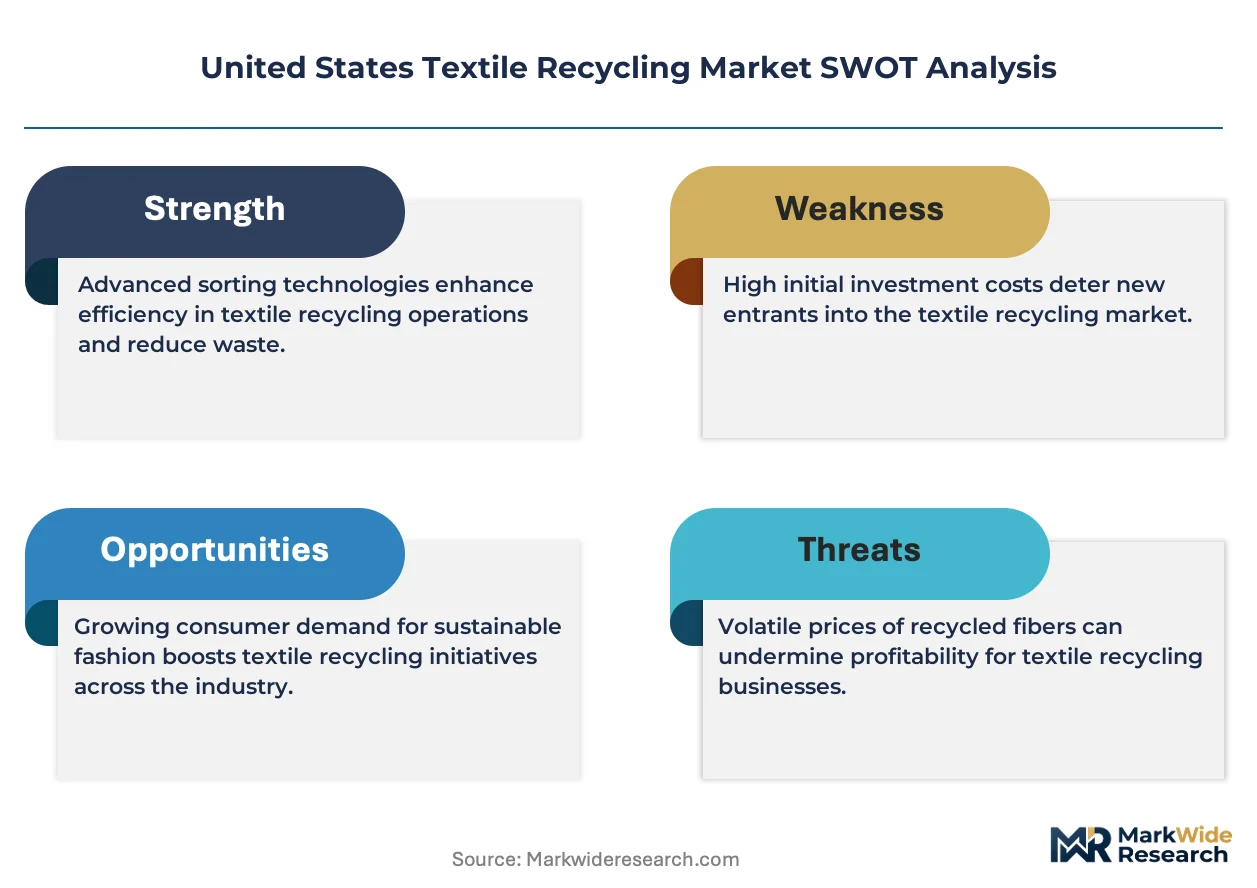
EPA landfill diversion guidelines and state-level extended producer responsibility frameworks in California and New York shape collection infrastructure investment and sorting technology requirements. OSHA standards govern baling and shredding facility operations, while FTC Green Guides constrain marketing claims around recycled content percentages. Stakeholders must monitor whether chemical recycling scale-up achieves cost parity with mechanical alternatives before committing capital to next-generation facilities.
Market Dynamics
EPA landfill diversion guidelines and state-level extended producer responsibility frameworks are compressing feedstock availability timelines and forcing rapid capital deployment into automated sorting infrastructure across the Carolinas and California textile processing corridors.
Growth Catalysts
- California EPR mandates:The state's textile stewardship program requires producers to finance collection and recycling infrastructure, accelerating post-consumer fiber recovery volumes into mechanical reprocessing lines.
- Automotive interior specifications:Detroit-based OEMs have rewritten material standards to mandate minimum recycled content thresholds in seating fabrics and panel substrates, pulling polyester fiber-to-fiber recovery capacity online.
- Chemical depolymerization yields:Advances in glycolysis and methanolysis routes for PET now achieve polymer purity above ninety-five percent, enabling closed-loop feedstock substitution in premium apparel spinning.
Market Restraints
- Contamination cost volatility:Post-consumer feedstock streams carry five to fifteen percent non-textile contamination by weight, forcing preprocessing capex that mechanical recyclers in Texas and Georgia struggle to amortize at current cotton price levels.
- Collection infrastructure concentration:Dense drop-off networks remain concentrated in coastal metropolitan corridors, leaving interior states with feedstock supply gaps that raise logistics costs for inland reprocessors.
- Polyester-cotton blend separation:Mechanical shredding of polycotton textiles degrades both fiber streams below spinner quality thresholds, limiting addressable volume in the dominant fast-fashion waste category.
Strategic Opportunities
- Curbside program expansion:Municipalities in New York and San Francisco are piloting textile-inclusive curbside collection, creating direct household feedstock access that bypasses thrift store intermediation.
- Building insulation nonwovens:Reclaimed denim and cotton textiles are penetrating thermal and acoustic insulation applications in residential construction, displacing fiberglass at competitive R-value performance.
- FTC Green Guide compliance services:Third-party verification of recycled content claims is emerging as a margin pool as brands face enforcement risk on marketing assertions.
Industry Challenges
- Optical sorting technician scarcity:Near-infrared and robotics-based separation systems require skilled operators that community colleges in North Carolina and South Carolina have not yet trained at sufficient scale.
- Chemical recycling capex intensity:Depolymerization reactors and purification trains demand facility investments that exceed mechanical shredding lines by an order of magnitude, constraining independent processor entry.
- OSHA baling safety compliance:Dense textile bale handling operations face heightened inspection scrutiny on lockout-tagout protocols and dust exposure limits, extending facility certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Textile Recycling Market |
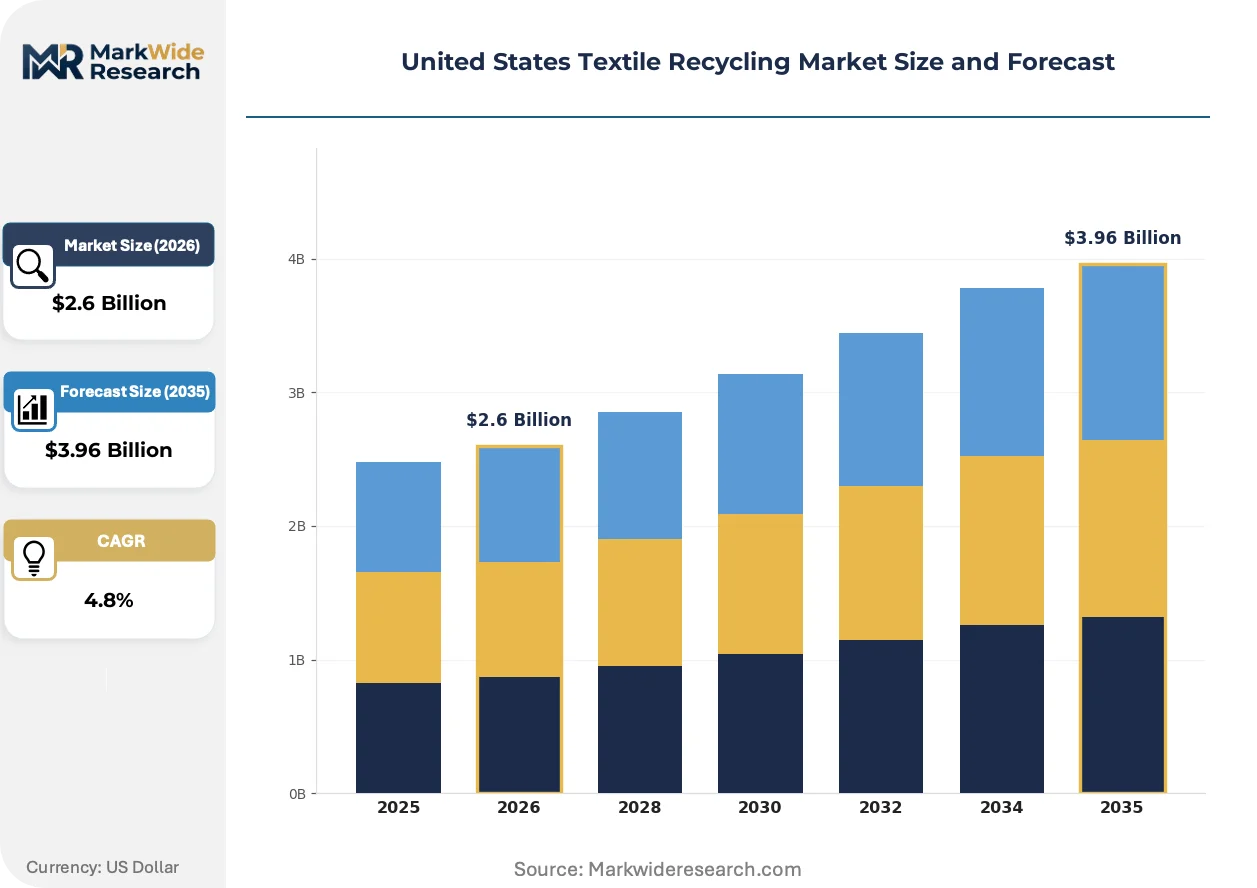
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $3.96 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Wool, Nylon Collection Method: Drop-off Locations, Curbside Collection, Thrift Store Donations, Textile Banks End User: Manufacturers, Retailers, Non-profits, Waste Management Companies Processing Technology: Mechanical, Chemical, Thermal, Biodegradation |
| Companies Covered | Parkdale Mills, Mount Vernon Mills, American Textile Recycling Service, International Textile Group, Glen Raven Inc., Unifi Inc., Milliken & Company, Waste Management Inc., Patagonia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Textile Recycling Market Strategic Shifts & Innovations
Technology maturation in chemical fiber recovery is compressing quality premiums between virgin and recycled inputs while regulatory pressure on landfill diversion accelerates collection infrastructure deployment.
Enzymatic hydrolysis of cellulosic textiles is converging with mechanical shredding pre-treatment to recover cotton fiber strength properties previously degraded in conventional reprocessing. Premium denim brands in Los Angeles and New York are piloting these hybrid routes to secure closed-loop feedstock with fiber length retention above virgin cotton benchmarks. The convergence is enabling price parity between reclaimed and virgin cotton in ring-spun yarn categories that mechanical routes could not previously serve.
The EPA's advancing landfill diversion guidelines are tightening municipal solid waste enforcement timelines across states without existing textile EPR frameworks. Waste management authorities in Florida and Illinois are responding with requests-for-proposals for automated material recovery facility retrofits capable of textile separation. The regulatory pressure is most acute in apparel-producing regions where brand headquarters face reputational exposure on scope three emissions reporting.
Brand procurement departments are consolidating supplier relationships around vertically integrated recyclers capable of certifying chain-of-custody from collection through finished yarn. This concentration is displacing fragmented broker networks that previously aggregated feedstock across multiple collection tiers. The shift is most visible in Southeast spinning corridors where Parkdale Mills and Unifi Inc. have captured preferred supplier status through captive collection infrastructure.
United States Textile Recycling Market Segmentation
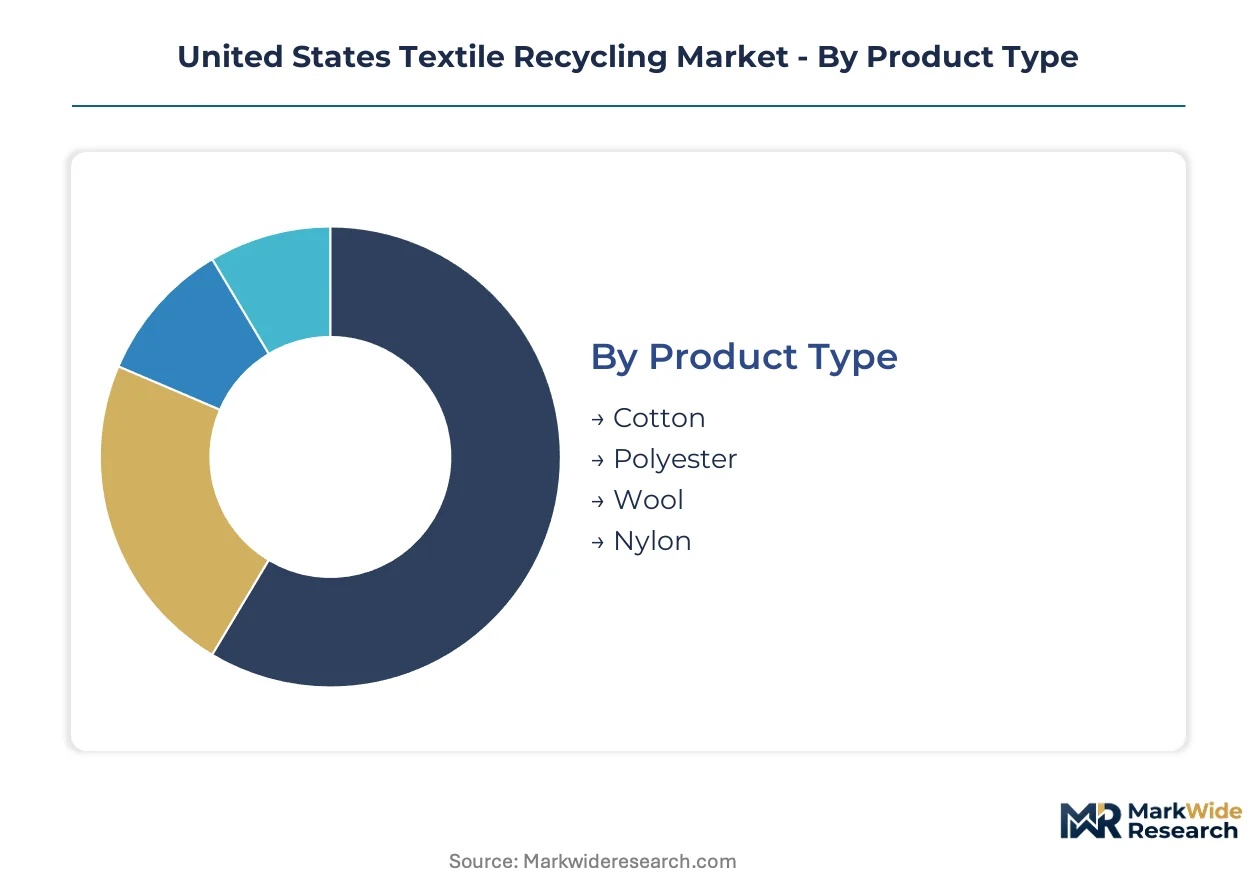
Segmentation in United States textile recycling reveals how feedstock composition, collection logistics, and processing economics intersect. Understanding these divisions exposes where margin pools concentrate and where infrastructure gaps persist across mechanical and chemical recovery routes.
Product Type:
Cotton commands volume flows while polyester captures premium pricing in fiber-to-fiber applications.
- Cotton:Mechanical shredding and re-spinning lines dominate installed capacity across the Carolinas textile belt. Reclaimed cotton serves denim and basic apparel spinning where fiber length tolerance permits shorter staple, with EPA landfill diversion targets tightening feedstock availability timelines in municipal corridors.
- Polyester:Chemical depolymerization via glycolysis and methanolysis achieves polymer purity above ninety-five percent, enabling closed-loop substitution in automotive seating and premium apparel. Detroit-based OEM material specifications now mandate minimum recycled content thresholds, pulling capacity expansion toward Southeast processing clusters.
- Wool:Premium fiber recovery concentrates in niche reprocessing facilities serving luxury apparel brands with strict contamination controls.
- Nylon:Limited mechanical routes exist; chemical recycling scale-up lags due to depolymerization complexity and capex intensity.
Today's leader: Cotton. Tomorrow's challenger: Polyester.
Collection Method:
Geographic concentration of infrastructure creates supply asymmetries between coastal metros and interior states.
- Drop-off Locations:Dense networks in Texas and California metro corridors supply bulk feedstock to mechanical recyclers. American Textile Recycling Service competes through coverage depth, though logistics costs rise for inland reprocessors sourcing from these coastal concentrations.
- Curbside Collection:San Francisco and New York pilot programs create direct household access bypassing thrift store intermediation. Municipal solid waste authorities in Florida and Illinois are issuing RFPs for automated material recovery facility retrofits capable of textile separation as EPA enforcement timelines advance.
- Thrift Store Donations:Established channel supplying resale-grade textiles with residual feedstock diverted to recyclers; quality sorting remains labor-intensive.
- Textile Banks:Limited deployment in the United States compared to European models; EPR framework expansion in California may accelerate deployment.
Current infrastructure favors drop-off density. Curbside pilots are gaining share fastest where municipal budgets permit automation investment.
End User:
Procurement consolidation around vertically integrated recyclers is displacing fragmented broker networks.
- Manufacturers:Apparel and automotive producers dominate demand, with spinning infrastructure in the Carolinas processing reclaimed cotton and polyester blends. Parkdale Mills and Unifi Inc. have captured preferred supplier status through captive collection infrastructure and chain-of-custody certification.
- Retailers:Brand procurement departments face FTC Green Guide enforcement risk on recycled content marketing claims, driving third-party verification demand.
- Non-profits:Collection operators with dense donation networks; margin pressure from rising logistics costs and contamination preprocessing requirements.
- Waste Management Companies:Responding to EPA landfill diversion guidelines with automated sorting capex; optical sorting technician scarcity extends facility certification timelines in North Carolina and South Carolina.
Manufacturer procurement concentration defines current value capture. Waste management vertical integration poses the steepest competitive threat to incumbent collectors.
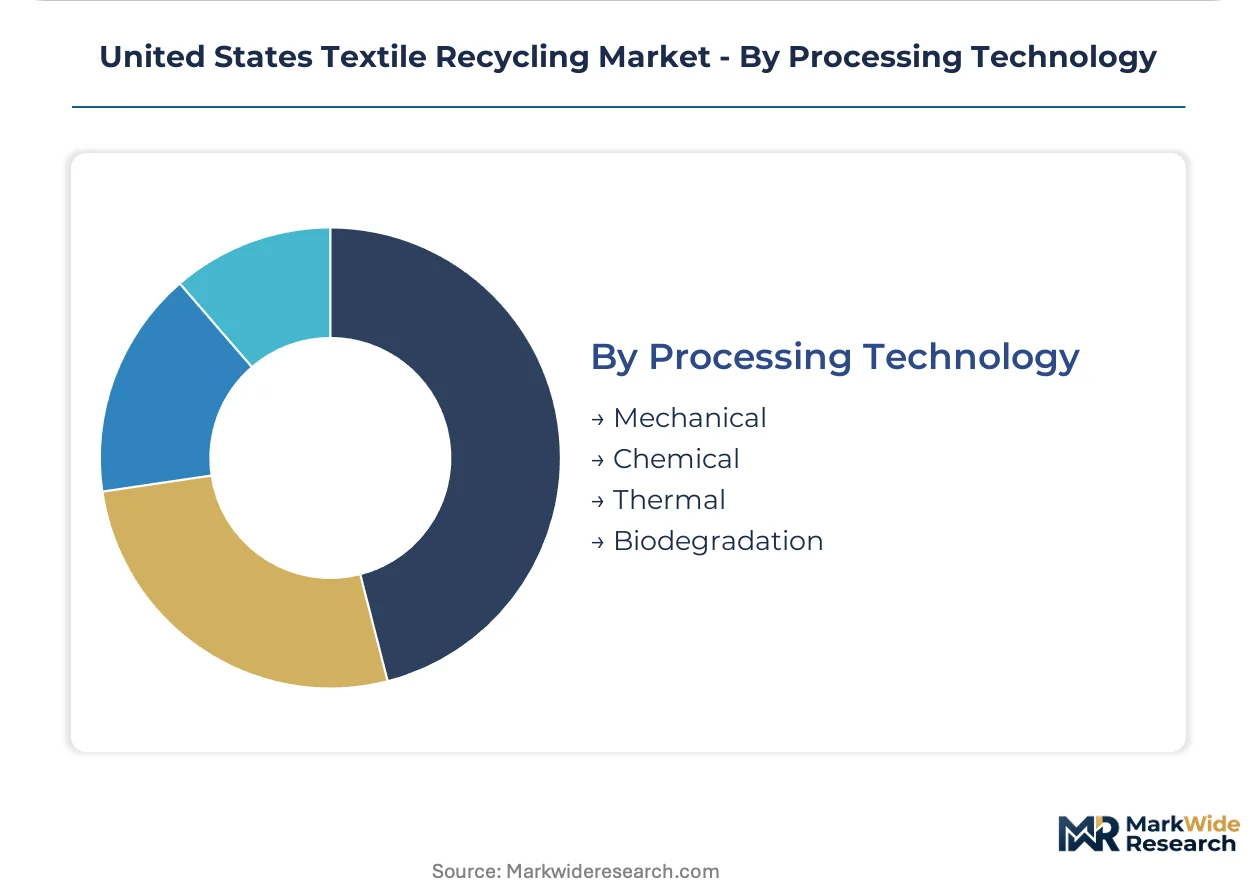
Processing Technology:
Mechanical routes hold installed base dominance while chemical recycling concentrates margin pools in premium output categories.
- Mechanical:Shredding and re-spinning lines occupy the largest installed base across Texas and Georgia. Contamination cost volatility—five to fifteen percent non-textile content in post-consumer streams—forces preprocessing capex that struggles to amortize at prevailing cotton price levels.
- Chemical:Depolymerization reactors and purification trains demand facility investments exceeding mechanical lines by an order of magnitude. Output quality approaches virgin-grade specification, enabling price parity in ring-spun yarn categories mechanical routes cannot serve.
- Thermal:Limited deployment for synthetic fiber recovery; energy intensity constrains commercial viability under current utility rate structures.
- Biodegradation:Enzymatic hydrolysis of cellulosic textiles converges with mechanical pre-treatment in pilot stages; Los Angeles and New York denim brands test hybrid routes for fiber length retention above virgin benchmarks.
Mechanical scale dominates feedstock volume. Chemical purity commands the expanding premium tier as fiber-to-fiber yields improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping textile recycling investment flows as processors migrate toward states with favorable EPR cost structures and established spinning infrastructure. The Carolinas textile belt attracts capital deployment due to integrated fiber recovery-to-yarn finishing capabilities, while California's stringent mandates compress compliance timelines for coastal operators.
Southeast (Carolinas/Georgia)
Mechanical shredding and re-spinning lines cluster around Charlotte and Greenville where cotton processing infrastructure dates to the 20th century. EPA landfill diversion guidelines tighten feedstock availability timelines across municipal corridors, forcing rapid automated sorting capex. Parkdale Mills anchors vertical control from fiber recovery through yarn finishing, insulating margin pools from commodity cotton volatility.
Texas
American Textile Recycling Service competes through dense drop-off network coverage in Dallas-Fort Worth and Houston metro corridors. Post-consumer feedstock streams carry elevated contamination levels that force preprocessing investments mechanical recyclers struggle to amortize. The state's waste management authorities respond to EPA enforcement timelines with requests-for-proposals for automated material recovery facility retrofits.
California
The state's textile stewardship program requires producers to finance collection and recycling infrastructure, accelerating post-consumer fiber recovery volumes. San Francisco pilots textile-inclusive curbside collection creating direct household feedstock access. Premium denim brands in Los Angeles test enzymatic hydrolysis hybrid routes for fiber length retention above virgin cotton benchmarks.
New York Metro
Municipal solid waste authorities expand curbside textile collection pilots bypassing thrift store intermediation. Brand procurement departments face FTC Green Guide enforcement risk on recycled content marketing claims. The region's apparel brand headquarters concentrate reputational exposure on scope three emissions reporting.
Midwest (Illinois/Ohio)
Waste management authorities issue RFPs for automated sorting infrastructure as EPA enforcement timelines advance without existing state-level EPR frameworks. Interior states face feedstock supply gaps raising logistics costs for inland reprocessors. Collection infrastructure concentration in coastal metros leaves this region dependent on long-haul transportation for post-consumer textile streams.
United States Textile Recycling Market Key Industry Players
Capacity expansion dominates the current landscape as vertically integrated processors build captive collection infrastructure to secure feedstock streams. The market structure concentrates around three tiers: established spinning conglomerates with backward integration into recovery, specialized collection operators with dense geographic coverage, and waste management incumbents retrofitting material recovery facilities for textile separation. Strategic archetypes include fiber-to-fiber purity specialists, volume-scale mechanical processors, and municipal contract holders. Competitive moves center on geographic expansion of drop-off networks and technology licensing for automated sorting systems.
Among vertically integrated processors, Parkdale Mills exemplifies the spinning conglomerate archetype with control spanning fiber recovery through finished yarn, while Unifi Inc. anchors supply relationships through its Repreve platform serving automotive and apparel end-users. American Textile Recycling Service occupies the specialized collection tier with dense network coverage in Texas and California metro corridors. These three entities represent distinct competitive positions: captive supply chain integration, brand-facing certification platforms, and logistics-intensive collection scale.
| Leading Market Players |
|---|
| Parkdale Mills |
| Mount Vernon Mills |
| American Textile Recycling Service |
| International Textile Group |
| Glen Raven Inc. |
| Unifi Inc. |
| Milliken & Company |
| Waste Management Inc. |
| Patagonia |
| Others |
Cost & Logistics Intelligence
Detroit-based OEM procurement departments concentrate purchasing power for recycled polyester feedstocks, forcing contract-based long-term offtake structures that compress spot-market premiums. This buyer concentration reshapes margin distribution across mechanical and chemical processing tiers.
Pricing Analysis
Direct-to-OEM discounts dominate volume transactions, with three-tier pricing structure across premium, standard, and economy levels separating fiber-to-fiber certified outputs from downcycled insulation grades. Price differentiation centers on polymer purity certification and chain-of-custody verification, with automotive seating specifications commanding premiums over basic apparel spinning. Cost compression in mechanical cotton routes is intensifying because contamination preprocessing capex struggles to amortize at prevailing commodity price levels. Small independent processors in Texas and Georgia exhibit highest price sensitivity, while vertically integrated Carolinas spinners with captive collection infrastructure maintain pricing discipline.
Supply Chain Analysis
Dual-sourcing requirements from EPA landfill diversion guidelines mandate multi-supplier qualification for municipal feedstock contracts, fragmenting collection infrastructure across competing networks. Geographic supply concentration centers on the United States Carolinas textile belt, California coastal corridors, and Texas metro clusters. Raw material dependencies rest on post-consumer cotton streams, polyester textile waste, and post-industrial fiber scrap. Single-source vulnerability concentrates in automated optical sorting equipment where Near-Infrared systems draw from limited qualified vendors. Distribution runs through vertically integrated processors with captive logistics, bypassing traditional broker intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between California's stringent EPR compliance costs and the Carolinas' established spinning infrastructure with lower regulatory overhead.
For Market Incumbents: Deepen backward integration into automated sorting technology to insulate margin pools from rising contamination preprocessing costs. Parkdale Mills and Unifi Inc. anchor competitive position through captive collection infrastructure; smaller mechanical processors must consolidate or exit as EPA enforcement timelines compress feedstock availability. Capacity addition in Southeast processing clusters remains the priority defensive lever against waste management incumbents retrofitting material recovery facilities.
For New Entrants and Emerging Players: Chemical depolymerization technology-first wedges open premium fiber-to-fiber recovery where mechanical routes degrade polycotton blends below spinner thresholds. White-space targets concentrate in Midwest interior states with feedstock supply gaps and elevated logistics costs for long-haul transportation from coastal collection density. Municipal curbside program partnerships in New York and San Francisco offer the most penetrable go-to-market angle, bypassing entrenched thrift store intermediation.
For Investors and Strategic Acquirers: Waste management conglomerates are the most active acquirer in this space, consolidating fragmented collection networks to secure feedstock streams for vertical integration into reprocessing. Long-term viability favors processors with demonstrated chemical recycling scale-up achieving cost parity with mechanical alternatives. The signal to watch is fiber-to-fiber yield improvements in glycolysis and methanolysis routes as inflection indicator for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Infrastructure Deployment | EPA enforcement timelines in Florida and Illinois accelerate capital deployment into Near-Infrared separation systems. |
| Chemical Recycling Scale-Up | Depolymerization reactor investments exceed mechanical lines by order of magnitude, concentrating margin pools in premium outputs. |
| Curbside Collection Program Expansion | San Francisco and New York pilots create direct household feedstock access bypassing thrift store intermediation. |
| Backward Integration into Collection Networks | Parkdale Mills and Unifi Inc. capture preferred supplier status through captive infrastructure insulating against commodity volatility. |
| FTC Green Guide Compliance Certification | Third-party verification services emerge as margin pool as brand procurement faces enforcement risk on recycled content claims. |
Research Approach
Coverage spans the United States Southeast, Texas, California, and New York Metro regions, with primary inputs from each. The approach combines structured interviews with textile recycling plant managers, brand procurement leads, municipal solid waste authority directors, and automotive Tier 1 supplier sustainability officers with secondary validation. Sources include EPA landfill diversion filings, state EPR framework documentation, SEC 10-K disclosures from publicly traded processors, and customs data on reclaimed fiber trade flows. Bottom-up feedstock volume estimates triangulate against top-down apparel waste generation models.
Rate-of-change decomposition separates volume drivers from price evolution across the analysis window. Segmentation dimensions modeled include fiber type, collection method, end-use vertical, and processing technology tier. CAGRs derive from installed capacity expansion schedules, regulatory enforcement timeline assumptions, and OEM material specification adoption curves. Industry-specific inputs incorporate polyester chemical depolymerization yield improvement trajectories and mechanical shredding line contamination cost volatility.
The model holds under steady EPA enforcement progression and stable cotton commodity price regimes; deviation in chemical recycling capex cost curves or state-level EPR framework adoption delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
Reusable Period Panties Market